


Beef Cattle Feed Market
Beef Cattle Feed Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
Beef cattle feed encompasses the complete feeds, concentrates, and feed additives formulated to support growth, weight gain, and overall health across the beef cattle production cycle, from cow-calf and backgrounding operations through feedlot finishing prior to processing. Feed formulation varies substantially across production stages, with feedlot finishing rations optimized for rapid, efficient weight gain and cow-calf operations relying more heavily on pasture supplementation and mineral programs.
Demand growth through the 2026-2033 window is closely tied to sustained global beef consumption supporting continued cattle production volumes, ongoing intensification of beef production systems in major producing regions seeking improved feed conversion efficiency, and growing adoption of feed additives and supplements that enhance growth performance and animal health outcomes. Rising feed grain and forage cost volatility continues to reinforce producer focus on feed conversion efficiency as a critical driver of production profitability.
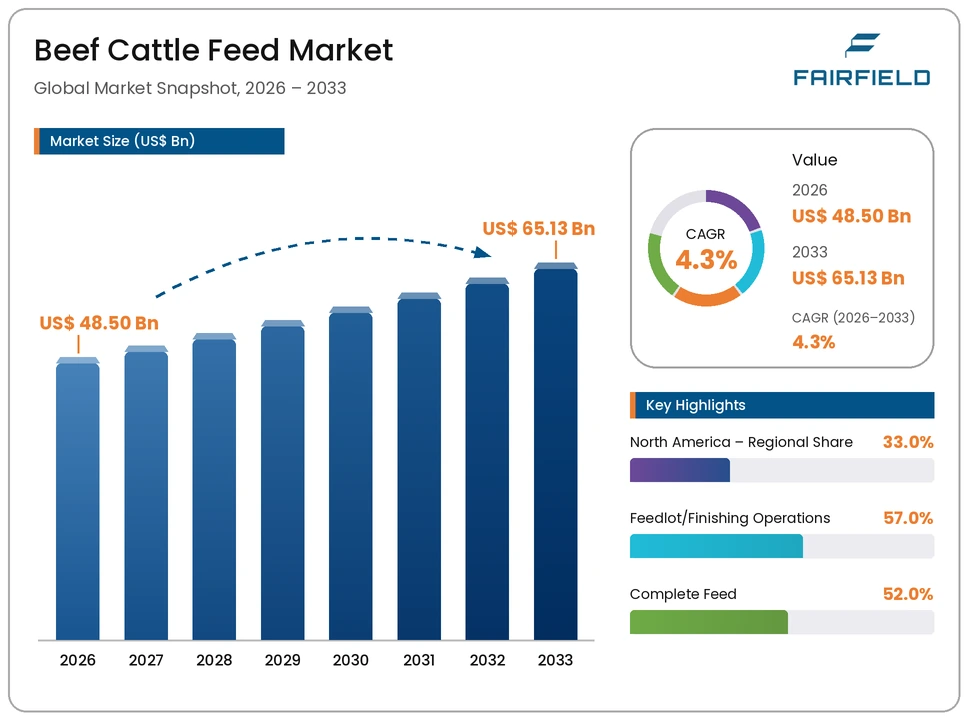
The market is valued at USD 48.50 Billion in 2026, with feed manufacturers directing investment toward improved feed formulation precision and additive integration that supports efficient weight gain across varying production system types. By 2033, the market is forecast to reach USD 65.13 Billion, reflecting steady growth across established feedlot finishing operations alongside expanding supplementation adoption in cow-calf and pasture-based systems.
Key Highlights
- The global beef cattle feed market is valued at USD 48.50 Billion in 2026 and is projected to reach USD 65.13 Billion by 2033, expanding at a CAGR of 4.3% across the 2026-2033 forecast period.
- Complete Feed leads the type segment with a 52.0% share in 2026, equivalent to USD 25.22 Billion.
- Feedlot/Finishing Operations remain the dominant production-system segment, accounting for 57.0% of global demand, or USD 27.65 Billion, in 2026.
- North America commands the largest regional share at 33.0% of the global market in 2026.
- Cow-calf and pasture-based operations are emerging as the fastest-growing production-system segment through 2033.
Key Growth Drivers
Growth in the beef cattle feed market is driven primarily by sustained global beef consumption, as continued demand for beef across both established and emerging consumer markets supports ongoing cattle production volumes and the associated feed requirements across all stages of the production cycle.
A second driver is ongoing intensification of beef production systems in major producing regions, as producers increasingly adopt feedlot finishing and other intensive production approaches seeking improved feed conversion efficiency and more predictable, consistent weight gain outcomes relative to extensive pasture-based systems alone.
Key Restraints
Feed grain and forage cost volatility, driven by weather variability and broader agricultural commodity market fluctuations, creates significant input cost uncertainty for beef cattle producers, directly affecting production economics and feed purchasing decisions across the industry.
Additionally, regional variation in cattle production system structure and available forage resources requires feed manufacturers to maintain diverse product portfolios suited to different production approaches, creating formulation and distribution complexity relative to more standardized feed categories.
Market Opportunities
The expansion of feed additive and supplement adoption presents a substantial opportunity, as producers increasingly seek to improve feed conversion efficiency and animal health outcomes through targeted supplementation, an area of growing scientific validation and producer interest across both feedlot and pasture-based production systems.
A second opportunity lies in the development of formulations optimized for cow-calf and pasture-based operations, an area that has historically received less dedicated feed product development attention than feedlot finishing rations. Manufacturers that successfully address this production system's specific supplementation needs stand to capture incremental market share.
Segmentation Analysis
- By Type
Complete Feed leads the type segment, accounting for 52.0% of global market value in 2026, equivalent to USD 25.22 Billion. Its leadership reflects complete feed's widespread use in feedlot finishing operations seeking predictable, balanced nutrition for efficient weight gain. Concentrates represent a significant, established feed category used to supplement forage-based diets. Feed Additives & Supplements represent the fastest-growing type category through 2033, driven by growing producer adoption of targeted performance and health-supporting products.
- By Production System
Feedlot/Finishing Operations form the leading production-system segment, representing 57.0% of global demand in 2026, or USD 27.65 Billion, reflecting the concentrated, purchased-feed-intensive nature of finishing operations relative to pasture-based production stages. Cow-Calf & Pasture-Based Operations represent the fastest-growing production-system category, propelled by increasing adoption of supplementation and mineral programs to improve herd performance.
Regional Insights
- North America
North America holds the largest regional share, at 33.0% of the global market in 2026, equivalent to USD 16.01 Billion. The region's leadership reflects its large-scale, highly intensive feedlot finishing industry and substantial beef cattle production base across the United States and Canada.
- Latin America
Latin America accounts for 26.0% of the global market in 2026, valued at USD 12.61 Billion. Brazil anchors regional demand as one of the world's largest beef cattle producers and exporters, supported by an expanding feedlot finishing sector alongside its traditional pasture-based production base.
- Asia Pacific
Asia Pacific represents 21.0% of the global market in 2026, or USD 10.19 Billion. Growth is underpinned by rising beef consumption and expanding domestic cattle production capacity across China, Australia, and other regional markets.
- Europe
Europe contributes 14.0% of the global market in 2026, equivalent to USD 6.79 Billion. Demand is supported by established beef cattle production across major European producing countries alongside sustained regional beef consumption.
- Middle East & Africa
Middle East & Africa holds 6.0% of the global market in 2026, valued at USD 2.91 Billion. Growth remains gradual, tied to expanding cattle production capacity and rising beef consumption across the region.
Competitive Landscape
The global beef cattle feed market is moderately fragmented, with a mix of large diversified agribusiness and animal nutrition companies holding broad beef cattle feed portfolios alongside regional and cooperative feed manufacturers serving local producer bases. Competition centers on feed formulation efficiency supporting cost-effective weight gain, regional distribution and service network strength, and the ability to provide technical support across varying production system types. Companies are increasingly differentiating through expanded feed additive integration and production-system-specific formulations rather than competing on commodity feed pricing alone.
Key Market Players
- Cargill, Incorporated
- Archer-Daniels-Midland Company
- Land O'Lakes, Inc.
- Charoen Pokphand Foods PCL
- Alltech, Inc.
- De Heus Animal Nutrition
- ForFarmers N.V.
- Nutreco N.V.
- Kent Nutrition Group
- J.D. Heiskell & Co.
Market Segmentation
By Type
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
By Production System
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
By Form
- Pellets
- Mash
- Blocks & Liquid Supplements
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Beef Cattle Feed Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Beef Cattle Feed Market Outlook, 2020 - 2033
- Global Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Global Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Global Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Global Beef Cattle Feed Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- North America Beef Cattle Feed Market Outlook, 2020 - 2033
- North America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- North America Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- North America Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- North America Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Type, 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Europe Beef Cattle Feed Market Outlook, 2020 - 2033
- Europe Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Europe Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Europe Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Europe Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Form, 2020-2033
- France Beef Cattle Feed Market Outlook, by Type, 2020-2033
- France Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- France Beef Cattle Feed Market Outlook, by Form, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Type, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Asia Pacific Beef Cattle Feed Market Outlook, 2020 - 2033
- Asia Pacific Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Asia Pacific Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Asia Pacific Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Asia Pacific Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Beef Cattle Feed Market Outlook, by Type, 2020-2033
- China Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- China Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Form, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Type, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Form, 2020-2033
- India Beef Cattle Feed Market Outlook, by Type, 2020-2033
- India Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- India Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Latin America Beef Cattle Feed Market Outlook, 2020 - 2033
- Latin America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Latin America Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Latin America Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Latin America Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Beef Cattle Feed Market Outlook, 2020 - 2033
- Middle East & Africa Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Middle East & Africa Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Middle East & Africa Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Middle East & Africa Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Type, 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Form, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Type, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Cargill, Incorporated
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Archer-Daniels-Midland Company
- Land O'Lakes, Inc.
- Charoen Pokphand Foods PCL
- Alltech, Inc.
- De Heus Animal Nutrition
- ForFarmers N.V.
- Nutreco N.V.
- Kent Nutrition Group
- J.D. Heiskell & Co.
- Cargill, Incorporated
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Type
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
By Production System
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
By Form
- Pellets
- Mash
- Blocks & Liquid Supplements
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global beef cattle feed market is valued at USD 48.50 Billion in 2026, reflecting sustained global beef production and consumption.
The market is projected to grow at a CAGR of 4.3%, reaching USD 65.13 Billion by 2033, driven by production intensification and expanding feed additive adoption.
Complete Feed leads with a 52.0% share in 2026, reflecting its widespread use in feedlot finishing operations for predictable, efficient weight gain.
North America leads with a 33.0% share in 2026, supported by its large-scale, intensive feedlot finishing industry.
The largest opportunity lies in cow-calf and pasture-based operations, growing alongside increasing adoption of supplementation and mineral programs.
Related Reports
Rice Bran Oil Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global rice bran oil market is valued at US$2.47 billion in 2026, reaching US$4.75 billion by 2033, growing at a 9.8% CAGR
Gum Arabic Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global gum arabic market is valued at US$0.516 billion in 2026, reaching US$0.791 billion by 2033, growing at a 6.3% CAGR
Guar Gum Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global guar gum market is valued at US$1.49 billion in 2026, reaching US$2.33 billion by 2033, growing at a 6.6% CAGR
Cheddar Cheese Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global cheddar cheese market is valued at US$17.33 billion in 2026, reaching US$24.70 billion by 2033, growing at a 5.2% CAGR
Algae Protein Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global algae protein market is valued at US$4.72 billion in 2026, reaching US$9.55 billion by 2033, growing at a 10.6% CAGR
Digestive Health Drinks Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global digestive health drinks market is valued at US$64.8 billion in 2026, reaching US$111.1 billion by 2033, growing at an 8.0% CAGR