


Discrete Analyzers Market
Discrete Analyzers Market Insights, Competitive Landscape, and Market Forecast 2033
Market Overview
Discrete analyzers are clinical chemistry instruments that process each patient sample and test individually within separate reaction vessels, supporting high-throughput, flexible biochemical testing across hospital and diagnostic laboratory settings. As clinical laboratory testing volume has continued growing alongside sustained demand for rapid, accurate diagnostic results, discrete analyzer technology has maintained its established position as the predominant clinical chemistry testing platform across global healthcare systems.
Demand growth through the 2026-2033 window is closely tied to sustained global growth in clinical laboratory testing volume across routine biochemical and specialty diagnostic panels, growing hospital and laboratory investment in automated testing infrastructure supporting improved workflow efficiency, and continued analyzer technology advancement improving throughput, accuracy, and menu flexibility. Growing point-of-care and portable analyzer development continues to expand discrete analyzer technology beyond traditional centralized laboratory settings.
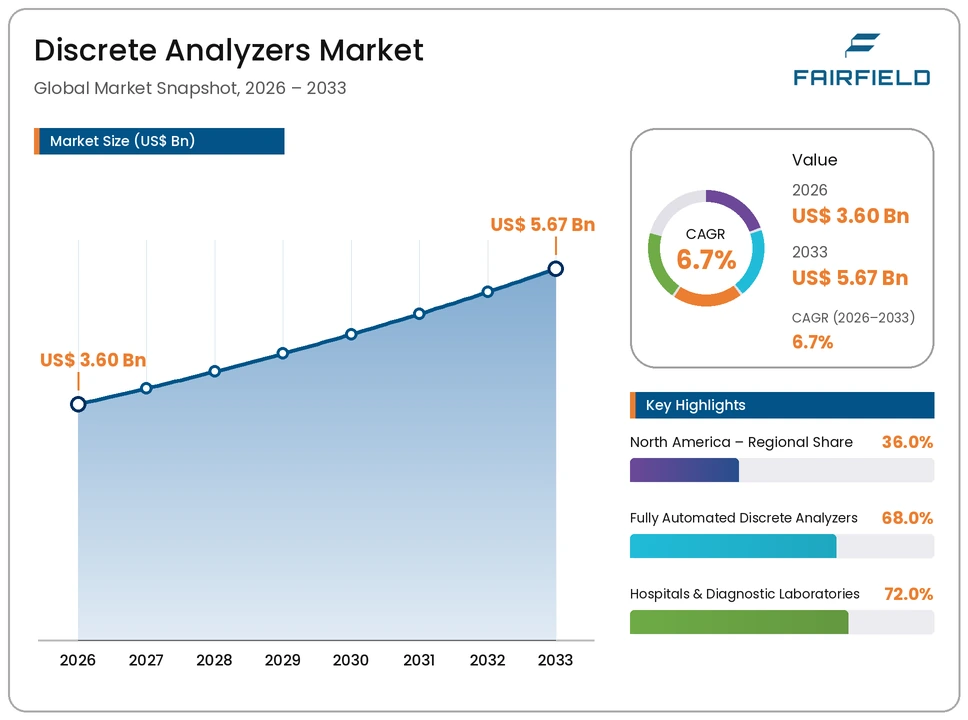
The market is valued at USD 3.60 Billion in 2026, with manufacturers directing investment toward improved automation and menu flexibility that supports increasingly diverse and high-volume clinical testing requirements. By 2033, the market is forecast to reach USD 5.67 Billion, reflecting steady growth across established fully automated analyzer applications alongside expanding portable and point-of-care analyzer adoption.
Key Highlights
- The global discrete analyzers market is valued at USD 3.60 Billion in 2026 and is projected to reach USD 5.67 Billion by 2033, expanding at a CAGR of 6.7% across the 2026-2033 forecast period.
- Fully Automated Discrete Analyzers lead the product-type segment with a 68.0% share in 2026, equivalent to USD 2.45 Billion.
- Hospitals & Diagnostic Laboratories remain the dominant end-user segment, accounting for 72.0% of global demand, or USD 2.59 Billion, in 2026.
- North America commands the largest regional share at 36.0% of the global market in 2026.
- Research institutions are emerging as the fastest-growing end-user segment through 2033.
Market Dynamics
Key Growth Drivers
Growth in the discrete analyzers market is driven primarily by sustained global growth in clinical laboratory testing volume, as expanding routine biochemical and specialty diagnostic testing continues to drive demand for reliable, high-throughput discrete analyzer platforms.
A second driver is growing hospital and laboratory investment in automated testing infrastructure, as healthcare providers increasingly prioritize workflow efficiency improvements that reduce manual processing and turnaround time for clinical test results.
Key Restraints
The substantial capital investment required for fully automated discrete analyzer systems creates budget constraints for smaller laboratories and healthcare facilities, particularly in developing markets with limited capital availability.
Additionally, ongoing reagent and consumable cost considerations create total cost of ownership challenges for laboratories, as recurring reagent expenses represent a substantial portion of overall analyzer operating costs.
Market Opportunities
The expansion of research institution applications presents a substantial opportunity, as growing biomedical research activity requiring flexible biochemical testing capability continues to expand demand beyond traditional clinical diagnostic settings.
A second opportunity lies in continued development of portable and point-of-care discrete analyzer technology that extends testing capability beyond centralized laboratory infrastructure. Companies that successfully advance this portable technology stand to capture growing demand as healthcare systems continue prioritizing decentralized, accessible diagnostic testing.
Segmentation Analysis
By Product Type
Fully Automated Discrete Analyzers lead the product-type segment, accounting for 68.0% of global market value in 2026, equivalent to USD 2.45 Billion. Their leadership reflects fully automated systems' superior throughput and workflow efficiency for high-volume clinical laboratory testing. Semi-Automated Discrete Analyzers represent a significant, established product-type category. Portable & Point-of-Care Discrete Analyzers represent the fastest-growing product-type category through 2033, driven by growing demand for decentralized diagnostic testing capability.
By End User
Hospitals & Diagnostic Laboratories form the leading end-user segment, representing 72.0% of global demand in 2026, or USD 2.59 Billion, reflecting these facilities' substantial routine clinical testing volume. Research Institutions represents the fastest-growing end-user category, propelled by expanding biomedical research testing activity.
Regional Insights
North America
North America holds the largest regional share, at 36.0% of the global market in 2026, equivalent to USD 1.30 Billion. The region's leadership reflects substantial clinical laboratory testing volume and strong automated testing infrastructure investment across the United States and Canada.
Europe
Europe accounts for 28.0% of the global market in 2026, valued at USD 1.01 Billion. Demand is supported by established clinical laboratory infrastructure and strong automated testing adoption across major European markets.
Asia Pacific
Asia Pacific represents 26.0% of the global market in 2026, or USD 0.94 Billion. Growth is underpinned by expanding healthcare infrastructure investment and growing clinical laboratory testing volume across China, Japan, and India.
Latin America
Latin America contributes 6.0% of the global market in 2026, equivalent to USD 0.22 Billion. Growth is linked to expanding clinical laboratory infrastructure development in Brazil and Mexico.
Middle East & Africa
Middle East & Africa holds 4.0% of the global market in 2026, valued at USD 0.14 Billion. Growth remains gradual, tied to expanding regional healthcare infrastructure investment.
Competitive Landscape
The global discrete analyzers market is moderately concentrated, with a mix of large diversified diagnostics companies and specialized clinical chemistry equipment manufacturers competing for hospital and laboratory adoption. Competition centers on analyzer throughput and automation capability, breadth of test menu flexibility, and the strength of relationships with clinical laboratories and hospital networks. Companies are increasingly differentiating through expanded portable and point-of-care analyzer capability rather than competing on conventional laboratory-based systems alone.
Key Market Players
- Roche Diagnostics International Ltd.
- Abbott Laboratories
- Siemens Healthineers AG
- Beckman Coulter, Inc.
- Thermo Fisher Scientific Inc.
- Horiba, Ltd.
- Randox Laboratories Ltd.
- Mindray Medical International Limited
- Sysmex Corporation
- ELITechGroup S.A.
Market Segmentation
By Product Type
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
By End User
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
By Application
- Clinical Chemistry
- Specialty Biochemical Testing
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Discrete Analyzers Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Discrete Analyzers Market Outlook, 2020 - 2033
- Global Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- Global Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- Global Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- Global Discrete Analyzers Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- North America Discrete Analyzers Market Outlook, 2020 - 2033
- North America Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- North America Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- North America Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- North America Discrete Analyzers Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- U.S. Discrete Analyzers Market Outlook, by End User, 2020-2033
- U.S. Discrete Analyzers Market Outlook, by Application, 2020-2033
- Canada Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Canada Discrete Analyzers Market Outlook, by End User, 2020-2033
- Canada Discrete Analyzers Market Outlook, by Application, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Europe Discrete Analyzers Market Outlook, 2020 - 2033
- Europe Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- Europe Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- Europe Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- Europe Discrete Analyzers Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Germany Discrete Analyzers Market Outlook, by End User, 2020-2033
- Germany Discrete Analyzers Market Outlook, by Application, 2020-2033
- Italy Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Italy Discrete Analyzers Market Outlook, by End User, 2020-2033
- Italy Discrete Analyzers Market Outlook, by Application, 2020-2033
- France Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- France Discrete Analyzers Market Outlook, by End User, 2020-2033
- France Discrete Analyzers Market Outlook, by Application, 2020-2033
- U.K. Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- U.K. Discrete Analyzers Market Outlook, by End User, 2020-2033
- U.K. Discrete Analyzers Market Outlook, by Application, 2020-2033
- Spain Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Spain Discrete Analyzers Market Outlook, by End User, 2020-2033
- Spain Discrete Analyzers Market Outlook, by Application, 2020-2033
- Russia Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Russia Discrete Analyzers Market Outlook, by End User, 2020-2033
- Russia Discrete Analyzers Market Outlook, by Application, 2020-2033
- Rest of Europe Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Rest of Europe Discrete Analyzers Market Outlook, by End User, 2020-2033
- Rest of Europe Discrete Analyzers Market Outlook, by Application, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Asia Pacific Discrete Analyzers Market Outlook, 2020 - 2033
- Asia Pacific Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- Asia Pacific Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- Asia Pacific Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- Asia Pacific Discrete Analyzers Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- China Discrete Analyzers Market Outlook, by End User, 2020-2033
- China Discrete Analyzers Market Outlook, by Application, 2020-2033
- Japan Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Japan Discrete Analyzers Market Outlook, by End User, 2020-2033
- Japan Discrete Analyzers Market Outlook, by Application, 2020-2033
- South Korea Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- South Korea Discrete Analyzers Market Outlook, by End User, 2020-2033
- South Korea Discrete Analyzers Market Outlook, by Application, 2020-2033
- India Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- India Discrete Analyzers Market Outlook, by End User, 2020-2033
- India Discrete Analyzers Market Outlook, by Application, 2020-2033
- Southeast Asia Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Southeast Asia Discrete Analyzers Market Outlook, by End User, 2020-2033
- Southeast Asia Discrete Analyzers Market Outlook, by Application, 2020-2033
- Rest of SAO Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Rest of SAO Discrete Analyzers Market Outlook, by End User, 2020-2033
- Rest of SAO Discrete Analyzers Market Outlook, by Application, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Latin America Discrete Analyzers Market Outlook, 2020 - 2033
- Latin America Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- Latin America Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- Latin America Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- Latin America Discrete Analyzers Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Brazil Discrete Analyzers Market Outlook, by End User, 2020-2033
- Brazil Discrete Analyzers Market Outlook, by Application, 2020-2033
- Mexico Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Mexico Discrete Analyzers Market Outlook, by End User, 2020-2033
- Mexico Discrete Analyzers Market Outlook, by Application, 2020-2033
- Argentina Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Argentina Discrete Analyzers Market Outlook, by End User, 2020-2033
- Argentina Discrete Analyzers Market Outlook, by Application, 2020-2033
- Rest of LATAM Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Rest of LATAM Discrete Analyzers Market Outlook, by End User, 2020-2033
- Rest of LATAM Discrete Analyzers Market Outlook, by Application, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Discrete Analyzers Market Outlook, 2020 - 2033
- Middle East & Africa Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
- Middle East & Africa Discrete Analyzers Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
- Middle East & Africa Discrete Analyzers Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Clinical Chemistry
- Specialty Biochemical Testing
- Middle East & Africa Discrete Analyzers Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- GCC Discrete Analyzers Market Outlook, by End User, 2020-2033
- GCC Discrete Analyzers Market Outlook, by Application, 2020-2033
- South Africa Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- South Africa Discrete Analyzers Market Outlook, by End User, 2020-2033
- South Africa Discrete Analyzers Market Outlook, by Application, 2020-2033
- Egypt Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Egypt Discrete Analyzers Market Outlook, by End User, 2020-2033
- Egypt Discrete Analyzers Market Outlook, by Application, 2020-2033
- Nigeria Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Nigeria Discrete Analyzers Market Outlook, by End User, 2020-2033
- Nigeria Discrete Analyzers Market Outlook, by Application, 2020-2033
- Rest of Middle East Discrete Analyzers Market Outlook, by Product Type, 2020-2033
- Rest of Middle East Discrete Analyzers Market Outlook, by End User, 2020-2033
- Rest of Middle East Discrete Analyzers Market Outlook, by Application, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Discrete Analyzers Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Roche Diagnostics International Ltd.
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Abbott Laboratories
- Siemens Healthineers AG
- Beckman Coulter, Inc.
- Thermo Fisher Scientific Inc.
- Horiba, Ltd.
- Randox Laboratories Ltd.
- Mindray Medical International Limited
- Sysmex Corporation
- ELITechGroup S.A.
- Roche Diagnostics International Ltd.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Product Type
- Fully Automated Discrete Analyzers
- Semi-Automated Discrete Analyzers
- Portable & Point-of-Care Discrete Analyzers
- Others
By End User
- Hospitals & Diagnostic Laboratories
- Research Institutions
- Others
By Application
- Clinical Chemistry
- Specialty Biochemical Testing
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global discrete analyzers market is valued at USD 3.60 Billion in 2026, reflecting sustained clinical laboratory testing volume growth.
The market is projected to grow at a CAGR of 6.7%, reaching USD 5.67 Billion by 2033, driven by automation investment and portable analyzer development.
Fully Automated Discrete Analyzers lead with a 68.0% share in 2026, reflecting their superior throughput and workflow efficiency.
North America leads with a 36.0% share in 2026, reflecting substantial clinical laboratory testing volume.
The largest opportunity lies in research institutions, expanding alongside growing biomedical research testing activity.
Related Reports
2,4-Dichloro-5-Fluorobenzoic Acid Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global 2,4-dichloro-5-fluorobenzoic acid market is valued at US$0.09 billion in 2026, reaching US$0.12 billion by 2033, at a 4.2% CAGR
1,5-Hexadiene Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global 1,5-hexadiene market is valued at US$0.14 billion in 2026, reaching US$0.22 billion by 2033, growing at a 6.7% CAGR
Automotive NVH Materials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive NVH materials market is valued at US$13.8 billion in 2026, reaching US$20.5 billion by 2033, growing at a 5.82% CAGR
Acrylonitrile Butadiene Styrene Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acrylonitrile butadiene styrene market is valued at US$27.4 billion in 2026, reaching US$38.6 billion by 2033, growing at a 5.02% CAGR
Tank Mix Adjuvants Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global tank mix adjuvants market is valued at US$4.3 billion in 2026, reaching US$6.6 billion by 2033, growing at a 6.3% CAGR
Glass Flake Coatings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The glass flake coatings market is projected to grow from US$0.64 billion in 2026 to US$0.96 billion by 2033, at a 5.96% CAGR