


GLP-1 and CGM Convergence Market
GLP-1 and CGM Convergence Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
GLP-1 and CGM convergence refers to the emerging integration of continuous glucose monitoring technology with GLP-1 receptor agonist therapy management, combining real-time glucose and metabolic data with GLP-1 treatment tracking to provide patients and clinicians with a more comprehensive view of treatment response and metabolic health during weight loss and diabetes management. As GLP-1 therapy has expanded dramatically across both diabetes and weight management populations, device and digital health companies have increasingly explored integrated platforms that combine continuous glucose data with medication tracking and personalized coaching support.
Demand growth through the 2026-2033 window is closely tied to explosive growth in GLP-1 therapy adoption across both diabetic and non-diabetic weight management populations, growing clinical and consumer interest in real-time metabolic data supporting treatment personalization and outcome tracking, and continued digital health platform innovation combining device data with behavioral coaching and treatment adherence support. Expanding integration between CGM device manufacturers and telehealth or digital coaching platforms continues to shape this rapidly emerging convergence category.
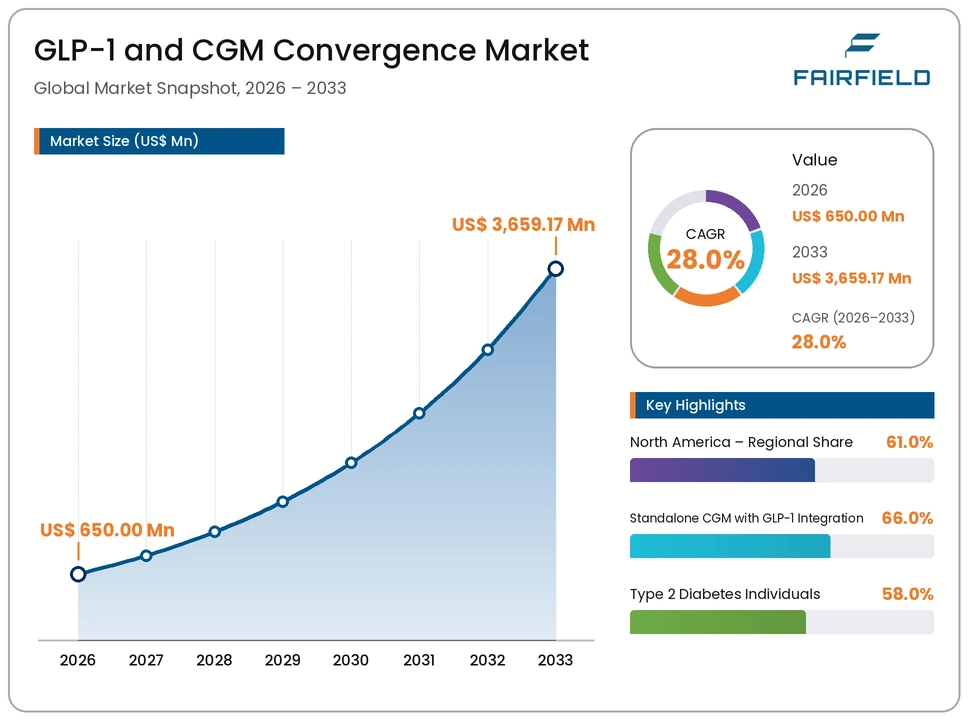
The market is valued at USD 650.00 Million in 2026, with device and digital health companies directing substantial investment toward integrated platforms that combine glucose monitoring data with GLP-1 treatment tracking and personalized insights. By 2033, the market is forecast to reach USD 3,659.17 Million, reflecting rapid growth across established diabetic patient applications alongside accelerating adoption among non-diabetic weight management patients.
Key Highlights
- The global GLP-1 and CGM convergence market is valued at USD 650.00 Million in 2026 and is projected to reach USD 3,659.17 Million by 2033, expanding at a CAGR of 28.0% across the 2026-2033 forecast period.
- Standalone CGM Devices with GLP-1 Data Integration lead the product-type segment with a 66.0% share in 2026, equivalent to USD 429.00 Million.
- Individuals with Type 2 Diabetes remain the dominant end-user segment, accounting for 58.0% of global demand, or USD 377.00 Million, in 2026.
- North America commands the largest regional share at 61.0% of the global market in 2026.
- Weight management patients without diabetes are emerging as the fastest-growing end-user segment through 2033.
Key Growth Drivers
Growth in the GLP-1 and CGM convergence market is driven primarily by explosive growth in GLP-1 therapy adoption, as rapidly expanding GLP-1 prescribing across both diabetes management and weight loss populations creates a growing base of patients for whom integrated metabolic monitoring offers meaningful treatment insight and engagement value.
A second driver is growing clinical and consumer interest in real-time metabolic data, as both prescribers and patients increasingly value continuous glucose data as a tool for understanding treatment response and supporting sustained lifestyle and medication adherence during GLP-1 therapy.
Key Restraints
The relative novelty of this convergence category creates limited clinical evidence specifically validating the incremental benefit of combined GLP-1 and CGM data platforms relative to either technology used independently, requiring continued outcomes research to support broader clinical endorsement.
Additionally, reimbursement pathways for continuous glucose monitoring among non-diabetic weight management patients remain limited in many markets, creating a cost barrier that can affect broader adoption of integrated platforms among this rapidly growing patient population.
Market Opportunities
The expansion of adoption among non-diabetic weight management patients presents a substantial opportunity, as the rapidly growing population using GLP-1 therapy specifically for weight loss, without a diabetes diagnosis, represents a significant and largely untapped market for integrated metabolic monitoring platforms.
A second opportunity lies in continued development of digital coaching and behavioral support platforms that combine device data with personalized guidance, improving treatment adherence and outcomes. Companies that successfully build comprehensive, validated integrated platforms stand to capture significant share as this convergence category matures from an emerging trend toward established clinical practice.
Segmentation Analysis
- By Product Type
Standalone CGM Devices with GLP-1 Data Integration lead the product-type segment, accounting for 66.0% of global market value in 2026, equivalent to USD 429.00 Million. Their leadership reflects the established commercial availability and clinical familiarity of continuous glucose monitoring devices now incorporating GLP-1 treatment tracking features. Integrated GLP-1/CGM Digital Platforms represent the fastest-growing product-type category through 2033, driven by growing demand for unified digital health platforms combining device data with comprehensive treatment support.
- By End User
Individuals with Type 2 Diabetes form the leading end-user segment, representing 58.0% of global demand in 2026, or USD 377.00 Million, reflecting this population's established use of both GLP-1 therapy and continuous glucose monitoring as standard diabetes management tools. Weight Management Patients (Non-Diabetic) represent the fastest-growing end-user category, propelled by rapidly expanding GLP-1 use for weight loss among patients without a diabetes diagnosis.
Regional Insights
- North America
North America holds the largest regional share, at 61.0% of the global market in 2026, equivalent to USD 396.50 Million. The region's dominance reflects the scale of GLP-1 therapy adoption and well-established continuous glucose monitoring infrastructure across the United States and Canada.
- Europe
Europe accounts for 22.0% of the global market in 2026, valued at USD 143.00 Million. Demand is supported by growing GLP-1 therapy adoption and established diabetes technology infrastructure across major European markets.
- Asia Pacific
Asia Pacific represents 12.0% of the global market in 2026, or USD 78.00 Million. Growth is underpinned by expanding GLP-1 therapy availability and growing diabetes technology adoption across China, Japan, and South Korea.
- Latin America
Latin America contributes 3.0% of the global market in 2026, equivalent to USD 19.50 Million. Growth remains at an early stage, tied to gradual GLP-1 therapy and diabetes technology access expansion in Brazil and Mexico.
- Middle East & Africa
Middle East & Africa holds 2.0% of the global market in 2026, valued at USD 13.00 Million. Growth remains limited, tied to gradual expansion of advanced diabetes technology access across the region.
Competitive Landscape
The global GLP-1 and CGM convergence market is fragmented, with a mix of established continuous glucose monitoring device manufacturers, pharmaceutical companies developing GLP-1 therapies, and digital health platforms building integrated tracking and coaching solutions. Competition centers on device accuracy and integration sophistication, breadth of behavioral coaching and treatment support features, and the ability to build clinical evidence supporting combined platform value. Companies are increasingly differentiating through comprehensive digital platform integration rather than competing on device hardware alone.
Key Market Players
- Dexcom, Inc.
- Abbott Laboratories
- Novo Nordisk A/S
- Eli Lilly and Company
- Medtronic plc
- Senseonics Holdings, Inc.
- Roche Holding AG
- Tandem Diabetes Care, Inc.
- Insulet Corporation
- Signos, Inc.
Market Segmentation
By Product Type
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
By End User
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
By Distribution Channel
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global GLP-1 and CGM Convergence Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- Global GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- Global GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- Global GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- Global GLP-1 and CGM Convergence Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- North America GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- North America GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- North America GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- North America GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- North America GLP-1 and CGM Convergence Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- U.S. GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- U.S. GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Canada GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Canada GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Canada GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Europe GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- Europe GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- Europe GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- Europe GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- Europe GLP-1 and CGM Convergence Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Germany GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Germany GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Italy GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Italy GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Italy GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- France GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- France GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- France GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- U.K. GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- U.K. GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- U.K. GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Spain GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Spain GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Spain GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Russia GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Russia GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Russia GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Rest of Europe GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Rest of Europe GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Rest of Europe GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- China GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- China GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Japan GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Japan GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Japan GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- South Korea GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- South Korea GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- South Korea GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- India GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- India GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- India GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Southeast Asia GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Southeast Asia GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Southeast Asia GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Rest of SAO GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Rest of SAO GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Rest of SAO GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Latin America GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- Latin America GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- Latin America GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- Latin America GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- Latin America GLP-1 and CGM Convergence Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Brazil GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Brazil GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Mexico GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Mexico GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Mexico GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Argentina GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Argentina GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Argentina GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Rest of LATAM GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Rest of LATAM GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Rest of LATAM GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, 2020 - 2033
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, Value (US$ Mn), 2020-2033
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- GCC GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- GCC GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- South Africa GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- South Africa GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- South Africa GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Egypt GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Egypt GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Egypt GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Nigeria GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Nigeria GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Nigeria GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- Rest of Middle East GLP-1 and CGM Convergence Market Outlook, by Product Type, 2020-2033
- Rest of Middle East GLP-1 and CGM Convergence Market Outlook, by End User, 2020-2033
- Rest of Middle East GLP-1 and CGM Convergence Market Outlook, by Distribution Channel, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa GLP-1 and CGM Convergence Market Outlook, by Product Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Dexcom, Inc.
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Abbott Laboratories
- Novo Nordisk A/S
- Eli Lilly and Company
- Medtronic plc
- Senseonics Holdings, Inc.
- Roche Holding AG
- Tandem Diabetes Care, Inc.
- Insulet Corporation
- Signos, Inc.
- Dexcom, Inc.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Product Type
- Integrated GLP-1/CGM Digital Platforms
- Standalone CGM Devices with GLP-1 Data Integration
- Others
By End User
- Individuals with Type 2 Diabetes
- Weight Management Patients (Non-Diabetic)
- Others
By Distribution Channel
- Direct-to-Consumer/Telehealth
- Clinical/Provider-Prescribed
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global GLP-1 and CGM convergence market is valued at USD 650.00 Million in 2026, reflecting the early stage of this rapidly emerging integrated health technology category.
The market is projected to grow at a CAGR of 28.0%, reaching USD 3,659.17 Million by 2033, driven by explosive GLP-1 therapy adoption and growing demand for integrated metabolic monitoring.
Standalone CGM Devices with GLP-1 Data Integration lead with a 66.0% share in 2026, reflecting established commercial availability of continuous glucose monitoring devices.
North America leads with a 61.0% share in 2026, driven by the scale of GLP-1 therapy adoption and established CGM infrastructure.
The largest opportunity lies in non-diabetic weight management patients, a rapidly growing population using GLP-1 therapy for weight loss.
Related Reports
2D Barcode Reader Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global 2D barcode reader market is valued at US$4.8 billion in 2026, reaching US$8.6 billion by 2033, growing at an 8.7% CAGR
Tunnel Construction Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global tunnel construction market is valued at US$29.52 billion in 2026, reaching US$47.09 billion by 2033, growing at a 6.9% CAGR
Sports Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global sports analytics market is valued at US$7.06 billion in 2026, reaching US$23.15 billion by 2033, growing at an 18.5% CAGR
Distributed Acoustic Sensing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global distributed acoustic sensing market is valued at US$0.565 billion in 2026, reaching US$1.173 billion by 2033, growing at an 11.0% CAGR
Secure Flash Drive Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global secure flash drive market is valued at US$0.8 billion in 2026, reaching US$1.1 billion by 2033, growing at a 4.7% CAGR
Optical I/O for AI Chips Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global optical I/O for AI chips market is valued at US$1.6 billion in 2026, reaching US$14.5 billion by 2033, growing at a 37.01% CAGR