


GNSS IC Market
GNSS IC Market Insights, Competitive Landscape, and Market Forecast 2033
Market Overview
GNSS integrated circuits provide the chip-level positioning capability that processes signals from global navigation satellite constellations, including GPS and GLONASS, enabling location determination across smartphones, automotive systems, and industrial and surveying equipment. As location-based services and applications have continued expanding across an increasingly broad range of consumer, automotive, and industrial use cases, GNSS chip demand has grown substantially beyond its traditional consumer navigation device origins.
Demand growth through the 2026-2033 window is closely tied to sustained smartphone and consumer electronics production requiring integrated positioning capability, rapidly expanding automotive GNSS integration supporting navigation, advanced driver assistance, and autonomous vehicle applications, and continued growth in industrial and surveying applications requiring high-precision positioning capability. Growing multi-constellation and multi-frequency GNSS chip capability continues to improve positioning accuracy and reliability across increasingly demanding application requirements.
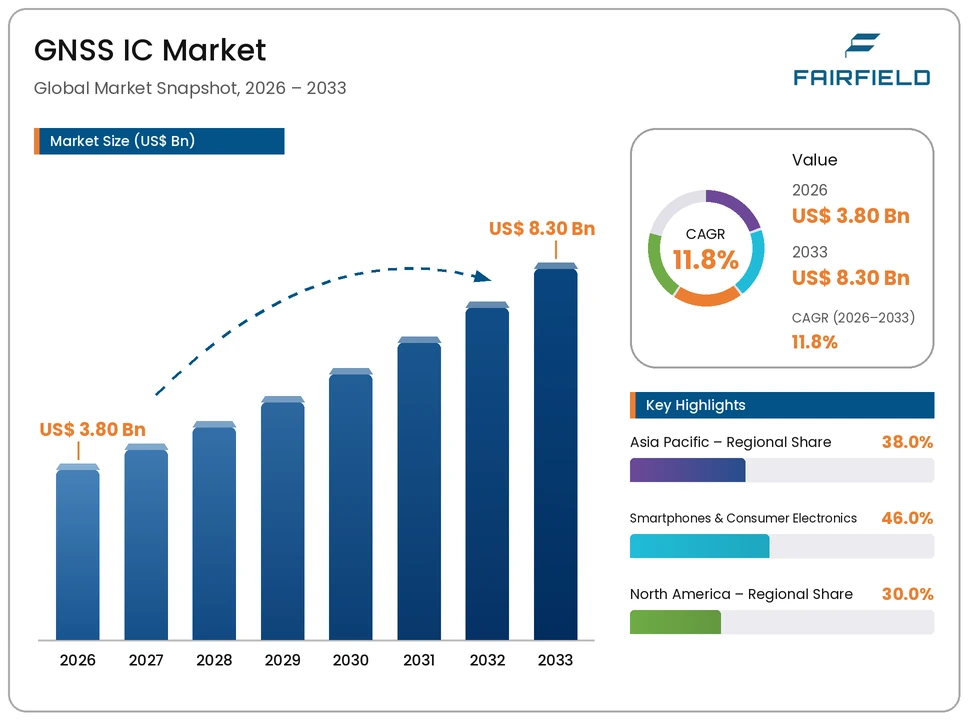
The market is valued at USD 3.80 Billion in 2026, with chip manufacturers directing substantial investment toward improved positioning accuracy and multi-constellation capability that supports increasingly sophisticated automotive and industrial applications. By 2033, the market is forecast to reach USD 8.30 Billion, reflecting steady growth across established smartphone and consumer electronics applications alongside accelerating automotive adoption.
Key Highlights
- The global GNSS IC market is valued at USD 3.80 Billion in 2026 and is projected to reach USD 8.30 Billion by 2033, expanding at a CAGR of 11.8% across the 2026-2033 forecast period.
- Smartphones & Consumer Electronics lead the application segment with a 46.0% share in 2026, equivalent to USD 1.75 Billion.
- North America commands the largest regional share at 30.0% of the global market in 2026.
- Asia Pacific represents the second-largest regional market at 38.0% of global demand in 2026.
- Automotive applications are emerging as the fastest-growing application through 2033.
Market Dynamics
Key Growth Drivers
Growth in the GNSS IC market is driven primarily by sustained smartphone and consumer electronics production, as continued global smartphone and wearable device manufacturing volume requires integrated positioning capability supporting an expanding range of location-based applications and services.
A second driver is rapidly expanding automotive GNSS integration, as growing navigation, advanced driver assistance, and autonomous vehicle system adoption across vehicle segments requires increasingly sophisticated, high-precision positioning chip capability.
Key Restraints
Intensifying price competition among GNSS chip manufacturers, driven by growing manufacturing scale and market maturity, creates margin pressure across the competitive landscape, particularly within the high-volume smartphone and consumer electronics segment.
Additionally, semiconductor supply chain volatility creates production planning challenges for GNSS chip manufacturers, as broader chip availability constraints have periodically affected component supply chains across the electronics industry.
Market Opportunities
The expansion of automotive applications presents a substantial opportunity, as growing advanced driver assistance system and autonomous vehicle development creates demand for increasingly sophisticated, high-precision GNSS chip capability beyond conventional navigation applications.
A second opportunity lies in continued advancement of multi-constellation and multi-frequency GNSS chip capability, improving positioning accuracy and reliability for increasingly demanding applications. Companies that successfully advance this technical capability stand to capture growing demand as positioning accuracy requirements continue to increase across automotive and industrial applications.
Segmentation Analysis
By Application
Smartphones & Consumer Electronics lead the application segment, accounting for 46.0% of global market value in 2026, equivalent to USD 1.75 Billion. Their leadership reflects the substantial scale of global smartphone and consumer electronics production requiring integrated positioning capability. Industrial & Surveying represents a significant, established application category. Automotive represents the fastest-growing application category through 2033, driven by growing advanced driver assistance and autonomous vehicle system adoption.
Regional Insights
Asia Pacific
Asia Pacific holds the largest regional share, at 38.0% of the global market in 2026, equivalent to USD 1.44 Billion. The region’s dominance reflects the concentration of global smartphone and consumer electronics manufacturing capacity across China, Taiwan, and South Korea.
North America
North America accounts for 30.0% of the global market in 2026, valued at USD 1.14 Billion. Demand is supported by substantial automotive and industrial GNSS chip design activity and adoption across the United States and Canada.
Europe
Europe represents 24.0% of the global market in 2026, or USD 0.91 Billion. Growth is underpinned by strong automotive GNSS integration and industrial surveying application adoption across major European markets.
Latin America
Latin America contributes 4.0% of the global market in 2026, equivalent to USD 0.15 Billion. Growth is linked to expanding consumer electronics and automotive GNSS chip adoption in Brazil and Mexico.
Middle East & Africa
Middle East & Africa holds 4.0% of the global market in 2026, valued at USD 0.15 Billion. Growth remains gradual, tied to expanding GNSS chip adoption across the region.
Competitive Landscape
The global GNSS IC market is moderately concentrated, with a mix of large diversified semiconductor companies and specialized positioning chip manufacturers competing for smartphone, automotive, and industrial equipment manufacturer adoption. Competition centers on positioning accuracy and multi-constellation capability, power efficiency for battery-powered devices, and manufacturing scale supporting competitive pricing. Companies are increasingly differentiating through expanded automotive-grade positioning capability rather than competing on conventional consumer navigation chips alone.
Key Market Players
- Qualcomm Incorporated
- Broadcom Inc.
- u-blox Holding AG
- STMicroelectronics N.V.
- MediaTek Inc.
- Texas Instruments Incorporated
- Infineon Technologies AG
- Furuno Electric Co., Ltd.
- Septentrio N.V.
- Trimble Inc.
Market Segmentation
By Technology
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
By Application
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
By Chip Type
- Standalone GNSS Chips
- Integrated SoC-Based Chips
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global GNSS IC Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global GNSS IC Market Outlook, 2020 - 2033
- Global GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- Global GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- Global GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- Global GNSS IC Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- North America GNSS IC Market Outlook, 2020 - 2033
- North America GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- North America GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- North America GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- North America GNSS IC Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. GNSS IC Market Outlook, by Technology, 2020-2033
- U.S. GNSS IC Market Outlook, by Application, 2020-2033
- U.S. GNSS IC Market Outlook, by Chip Type, 2020-2033
- Canada GNSS IC Market Outlook, by Technology, 2020-2033
- Canada GNSS IC Market Outlook, by Application, 2020-2033
- Canada GNSS IC Market Outlook, by Chip Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- Europe GNSS IC Market Outlook, 2020 - 2033
- Europe GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- Europe GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- Europe GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- Europe GNSS IC Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany GNSS IC Market Outlook, by Technology, 2020-2033
- Germany GNSS IC Market Outlook, by Application, 2020-2033
- Germany GNSS IC Market Outlook, by Chip Type, 2020-2033
- Italy GNSS IC Market Outlook, by Technology, 2020-2033
- Italy GNSS IC Market Outlook, by Application, 2020-2033
- Italy GNSS IC Market Outlook, by Chip Type, 2020-2033
- France GNSS IC Market Outlook, by Technology, 2020-2033
- France GNSS IC Market Outlook, by Application, 2020-2033
- France GNSS IC Market Outlook, by Chip Type, 2020-2033
- U.K. GNSS IC Market Outlook, by Technology, 2020-2033
- U.K. GNSS IC Market Outlook, by Application, 2020-2033
- U.K. GNSS IC Market Outlook, by Chip Type, 2020-2033
- Spain GNSS IC Market Outlook, by Technology, 2020-2033
- Spain GNSS IC Market Outlook, by Application, 2020-2033
- Spain GNSS IC Market Outlook, by Chip Type, 2020-2033
- Russia GNSS IC Market Outlook, by Technology, 2020-2033
- Russia GNSS IC Market Outlook, by Application, 2020-2033
- Russia GNSS IC Market Outlook, by Chip Type, 2020-2033
- Rest of Europe GNSS IC Market Outlook, by Technology, 2020-2033
- Rest of Europe GNSS IC Market Outlook, by Application, 2020-2033
- Rest of Europe GNSS IC Market Outlook, by Chip Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- Asia Pacific GNSS IC Market Outlook, 2020 - 2033
- Asia Pacific GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- Asia Pacific GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- Asia Pacific GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- Asia Pacific GNSS IC Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China GNSS IC Market Outlook, by Technology, 2020-2033
- China GNSS IC Market Outlook, by Application, 2020-2033
- China GNSS IC Market Outlook, by Chip Type, 2020-2033
- Japan GNSS IC Market Outlook, by Technology, 2020-2033
- Japan GNSS IC Market Outlook, by Application, 2020-2033
- Japan GNSS IC Market Outlook, by Chip Type, 2020-2033
- South Korea GNSS IC Market Outlook, by Technology, 2020-2033
- South Korea GNSS IC Market Outlook, by Application, 2020-2033
- South Korea GNSS IC Market Outlook, by Chip Type, 2020-2033
- India GNSS IC Market Outlook, by Technology, 2020-2033
- India GNSS IC Market Outlook, by Application, 2020-2033
- India GNSS IC Market Outlook, by Chip Type, 2020-2033
- Southeast Asia GNSS IC Market Outlook, by Technology, 2020-2033
- Southeast Asia GNSS IC Market Outlook, by Application, 2020-2033
- Southeast Asia GNSS IC Market Outlook, by Chip Type, 2020-2033
- Rest of SAO GNSS IC Market Outlook, by Technology, 2020-2033
- Rest of SAO GNSS IC Market Outlook, by Application, 2020-2033
- Rest of SAO GNSS IC Market Outlook, by Chip Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- Latin America GNSS IC Market Outlook, 2020 - 2033
- Latin America GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- Latin America GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- Latin America GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- Latin America GNSS IC Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil GNSS IC Market Outlook, by Technology, 2020-2033
- Brazil GNSS IC Market Outlook, by Application, 2020-2033
- Brazil GNSS IC Market Outlook, by Chip Type, 2020-2033
- Mexico GNSS IC Market Outlook, by Technology, 2020-2033
- Mexico GNSS IC Market Outlook, by Application, 2020-2033
- Mexico GNSS IC Market Outlook, by Chip Type, 2020-2033
- Argentina GNSS IC Market Outlook, by Technology, 2020-2033
- Argentina GNSS IC Market Outlook, by Application, 2020-2033
- Argentina GNSS IC Market Outlook, by Chip Type, 2020-2033
- Rest of LATAM GNSS IC Market Outlook, by Technology, 2020-2033
- Rest of LATAM GNSS IC Market Outlook, by Application, 2020-2033
- Rest of LATAM GNSS IC Market Outlook, by Chip Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- Middle East & Africa GNSS IC Market Outlook, 2020 - 2033
- Middle East & Africa GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
- Middle East & Africa GNSS IC Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
- Middle East & Africa GNSS IC Market Outlook, by Chip Type, Value (US$ Mn), 2020-2033
- Standalone GNSS Chips
- Integrated SoC-Based Chips
- Middle East & Africa GNSS IC Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC GNSS IC Market Outlook, by Technology, 2020-2033
- GCC GNSS IC Market Outlook, by Application, 2020-2033
- GCC GNSS IC Market Outlook, by Chip Type, 2020-2033
- South Africa GNSS IC Market Outlook, by Technology, 2020-2033
- South Africa GNSS IC Market Outlook, by Application, 2020-2033
- South Africa GNSS IC Market Outlook, by Chip Type, 2020-2033
- Egypt GNSS IC Market Outlook, by Technology, 2020-2033
- Egypt GNSS IC Market Outlook, by Application, 2020-2033
- Egypt GNSS IC Market Outlook, by Chip Type, 2020-2033
- Nigeria GNSS IC Market Outlook, by Technology, 2020-2033
- Nigeria GNSS IC Market Outlook, by Application, 2020-2033
- Nigeria GNSS IC Market Outlook, by Chip Type, 2020-2033
- Rest of Middle East GNSS IC Market Outlook, by Technology, 2020-2033
- Rest of Middle East GNSS IC Market Outlook, by Application, 2020-2033
- Rest of Middle East GNSS IC Market Outlook, by Chip Type, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa GNSS IC Market Outlook, by Technology, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Qualcomm Incorporated
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Broadcom Inc.
- u-blox Holding AG
- STMicroelectronics N.V.
- MediaTek Inc.
- Texas Instruments Incorporated
- Infineon Technologies AG
- Furuno Electric Co., Ltd.
- Septentrio N.V.
- Trimble Inc.
- Qualcomm Incorporated
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Technology
- GPS
- GLONASS
- Multi-Constellation/Multi-GNSS
- Others
By Application
- Smartphones & Consumer Electronics
- Automotive
- Industrial & Surveying
- Others
By Chip Type
- Standalone GNSS Chips
- Integrated SoC-Based Chips
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global GNSS IC market is valued at USD 3.80 Billion in 2026, reflecting expanding location-based application demand across industries.
The market is projected to grow at a CAGR of 11.8%, reaching USD 8.30 Billion by 2033, driven by automotive integration and consumer electronics demand.
Smartphones & Consumer Electronics lead with a 46.0% share in 2026, reflecting substantial global device manufacturing volume.
Asia Pacific leads with a 38.0% share in 2026, reflecting the concentration of global electronics manufacturing capacity.
The largest opportunity lies in automotive applications, expanding alongside growing advanced driver assistance system adoption.
Related Reports
Tunnel Construction Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global tunnel construction market is valued at US$29.52 billion in 2026, reaching US$47.09 billion by 2033, growing at a 6.9% CAGR
Sports Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global sports analytics market is valued at US$7.06 billion in 2026, reaching US$23.15 billion by 2033, growing at an 18.5% CAGR
Distributed Acoustic Sensing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global distributed acoustic sensing market is valued at US$0.565 billion in 2026, reaching US$1.173 billion by 2033, growing at an 11.0% CAGR
Secure Flash Drive Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global secure flash drive market is valued at US$0.8 billion in 2026, reaching US$1.1 billion by 2033, growing at a 4.7% CAGR
Optical I/O for AI Chips Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global optical I/O for AI chips market is valued at US$1.6 billion in 2026, reaching US$14.5 billion by 2033, growing at a 37.01% CAGR
Foldable Drones Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global foldable drones market is valued at US$3.76 billion in 2026 and is projected to reach US$7.57 billion by 2033, growing at a 10.5% CAGR.