


Military Training Aircraft Market
Military Training Aircraft Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
Military training aircraft are purpose-built platforms used to prepare pilots for operational military aviation service, spanning basic trainer aircraft for initial flight instruction through advanced jet trainers and lead-in fighter trainers that bridge the gap between training and frontline combat aircraft. These aircraft are engineered to replicate key handling and systems characteristics of operational aircraft while offering lower operating costs and enhanced safety margins suited to pilot instruction.
Demand growth through the 2026-2033 window is closely tied to sustained global defense spending supporting military pilot training pipeline investment, ongoing fleet modernization programs replacing aging trainer aircraft across established air forces, and expanding pilot training requirements among nations building or expanding domestic air force capabilities. Rising complexity of modern combat aircraft systems continues to increase the importance of advanced and lead-in fighter trainer aircraft that better prepare pilots for the demands of frontline platforms.
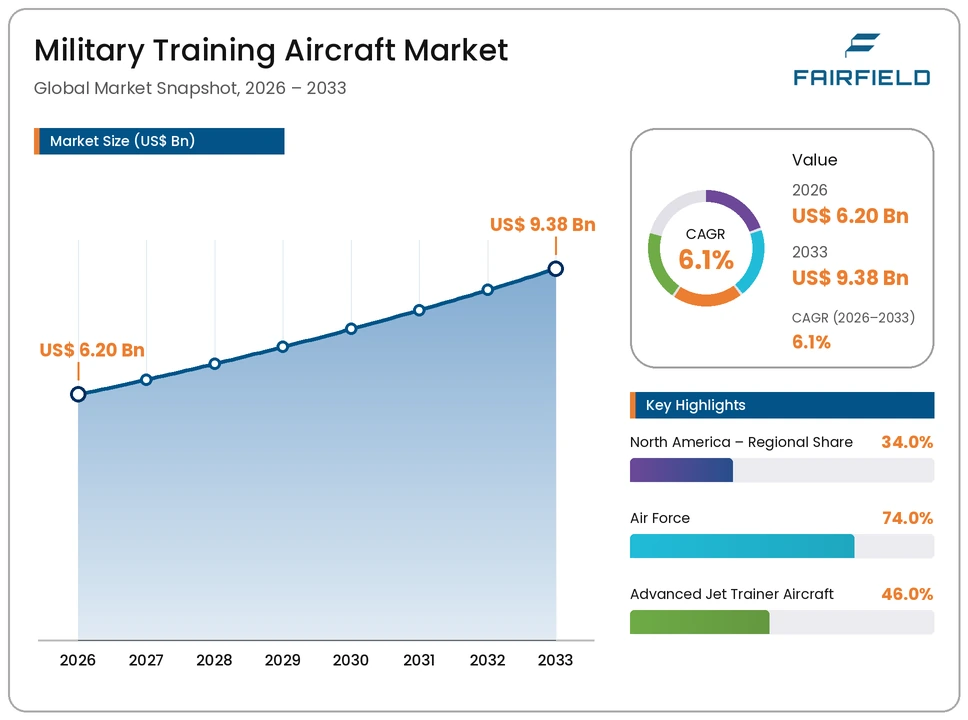
The market is valued at USD 6.20 Billion in 2026, with manufacturers directing investment toward advanced avionics and simulation integration that improves training effectiveness while managing per-flight-hour training costs. By 2033, the market is forecast to reach USD 9.38 Billion, reflecting sustained fleet modernization across established air forces alongside expanding naval aviation training requirements.
Key Highlights
- The global military training aircraft market is valued at USD 6.20 Billion in 2026 and is projected to reach USD 9.38 Billion by 2033, expanding at a CAGR of 6.1% across the 2026-2033 forecast period.
- Advanced Jet Trainer Aircraft lead the type segment with a 46.0% share in 2026, equivalent to USD 2.85 Billion.
- Air Force remains the dominant end-user segment, accounting for 74.0% of global demand, or USD 4.59 Billion, in 2026.
- North America commands the largest regional share at 34.0% of the global market in 2026.
- Naval end-user demand is emerging as the fastest-growing segment through 2033.
Key Growth Drivers
Growth in the military training aircraft market is driven primarily by sustained global defense spending supporting military pilot training pipeline investment, as air forces worldwide continue to prioritize training capacity to maintain adequate pilot readiness levels amid ongoing geopolitical tensions and modernization priorities.
A second driver is ongoing fleet modernization programs, as many air forces operate trainer aircraft fleets that have reached or are approaching the end of their service life, creating sustained replacement demand for next-generation trainer platforms with improved avionics and reduced operating costs.
Key Restraints
The substantial procurement and lifecycle costs associated with advanced military trainer aircraft programs create significant budgetary constraints for many air forces, particularly smaller nations balancing training aircraft investment against other defense procurement priorities.
Additionally, lengthy defense procurement and certification processes across most nations extend program timelines from initial requirement definition through aircraft delivery, creating extended development and sales cycles for manufacturers relative to commercial aviation programs.
Market Opportunities
The expansion of naval aviation training requirements presents a substantial opportunity, as naval air forces increasingly invest in dedicated carrier-capable and maritime patrol training programs distinct from traditional land-based air force training pipelines.
A second opportunity lies in the integration of advanced simulation and synthetic training technology alongside physical trainer aircraft, allowing air forces to optimize the balance between live flight hours and simulator-based instruction. Manufacturers that successfully combine aircraft platforms with sophisticated training system integration stand to differentiate their offerings in competitive procurement programs.
Segmentation Analysis
- By Type
Advanced Jet Trainer Aircraft lead the type segment, accounting for 46.0% of global market value in 2026, equivalent to USD 2.85 Billion. Their leadership reflects their central role in bridging basic flight instruction and operational fighter aircraft qualification across most air force training pipelines. Basic Trainer Aircraft represent a significant, foundational category. Lead-In Fighter Trainer Aircraft represent the fastest-growing type category through 2033, driven by rising complexity of modern combat aircraft systems requiring more sophisticated pre-operational training platforms.
- By End User
Air Force forms the leading end-user segment, representing 74.0% of global demand in 2026, or USD 4.59 Billion, reflecting air forces' role as the primary operator of dedicated pilot training pipelines across nearly all nations. Navy represents the fastest-growing end-user category, propelled by expanding carrier-capable and maritime aviation training program investment.
Regional Insights
- North America
North America holds the largest regional share, at 34.0% of the global market in 2026, equivalent to USD 2.11 Billion. The region's leadership reflects substantial defense spending and ongoing trainer aircraft fleet modernization programs across the United States and Canada.
- Asia Pacific
Asia Pacific accounts for 29.0% of the global market in 2026, valued at USD 1.80 Billion. Growth is underpinned by expanding air force training capacity across China, India, South Korea, and other nations building domestic aviation training infrastructure.
- Europe
Europe represents 22.0% of the global market in 2026, or USD 1.36 Billion. Demand is supported by ongoing trainer aircraft fleet modernization programs across major European air forces and multinational training initiatives.
- Middle East & Africa
Middle East & Africa contributes 9.0% of the global market in 2026, equivalent to USD 0.56 Billion. Growth is linked to sustained defense modernization investment across Gulf nations expanding domestic air force training capability.
- Latin America
Latin America holds 6.0% of the global market in 2026, valued at USD 0.37 Billion. Growth remains gradual, tied to ongoing but limited defense modernization budgets across the region.
Competitive Landscape
The global military training aircraft market is moderately concentrated, with a limited number of established defense and aerospace manufacturers holding strong positions supported by long-standing government relationships and proven trainer aircraft platforms. Competition centers on aircraft performance and reliability track record, avionics and simulation system integration, and the ability to offer comprehensive training system packages beyond the aircraft platform alone. Manufacturers are increasingly differentiating through integrated live-virtual-constructive training solutions rather than competing on airframe pricing alone.
Key Market Players
- Textron Aviation Inc.
- Leonardo S.p.A.
- Korea Aerospace Industries, Ltd.
- Pilatus Aircraft Ltd.
- Boeing Company
- Lockheed Martin Corporation
- Turkish Aerospace Industries
- Diamond Aircraft Industries
- Elbit Systems Ltd.
- Aviation Industry Corporation of China
Market Segmentation
By Type
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Lead-In Fighter Trainer Aircraft
By End User
- Air Force
- Navy
- Others
By Platform
- Fixed-Wing
- Rotary-Wing
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Military Training Aircraft Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Military Training Aircraft Market Outlook, 2020 - 2033
- Global Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Global Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- Global Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- Global Military Training Aircraft Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- North America Military Training Aircraft Market Outlook, 2020 - 2033
- North America Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- North America Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- North America Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- North America Military Training Aircraft Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Military Training Aircraft Market Outlook, by Type, 2020-2033
- U.S. Military Training Aircraft Market Outlook, by End User, 2020-2033
- U.S. Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Canada Military Training Aircraft Market Outlook, by Type, 2020-2033
- Canada Military Training Aircraft Market Outlook, by End User, 2020-2033
- Canada Military Training Aircraft Market Outlook, by Platform, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Europe Military Training Aircraft Market Outlook, 2020 - 2033
- Europe Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Europe Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- Europe Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- Europe Military Training Aircraft Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Military Training Aircraft Market Outlook, by Type, 2020-2033
- Germany Military Training Aircraft Market Outlook, by End User, 2020-2033
- Germany Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Italy Military Training Aircraft Market Outlook, by Type, 2020-2033
- Italy Military Training Aircraft Market Outlook, by End User, 2020-2033
- Italy Military Training Aircraft Market Outlook, by Platform, 2020-2033
- France Military Training Aircraft Market Outlook, by Type, 2020-2033
- France Military Training Aircraft Market Outlook, by End User, 2020-2033
- France Military Training Aircraft Market Outlook, by Platform, 2020-2033
- U.K. Military Training Aircraft Market Outlook, by Type, 2020-2033
- U.K. Military Training Aircraft Market Outlook, by End User, 2020-2033
- U.K. Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Spain Military Training Aircraft Market Outlook, by Type, 2020-2033
- Spain Military Training Aircraft Market Outlook, by End User, 2020-2033
- Spain Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Russia Military Training Aircraft Market Outlook, by Type, 2020-2033
- Russia Military Training Aircraft Market Outlook, by End User, 2020-2033
- Russia Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Rest of Europe Military Training Aircraft Market Outlook, by Type, 2020-2033
- Rest of Europe Military Training Aircraft Market Outlook, by End User, 2020-2033
- Rest of Europe Military Training Aircraft Market Outlook, by Platform, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Asia Pacific Military Training Aircraft Market Outlook, 2020 - 2033
- Asia Pacific Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Asia Pacific Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- Asia Pacific Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- Asia Pacific Military Training Aircraft Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Military Training Aircraft Market Outlook, by Type, 2020-2033
- China Military Training Aircraft Market Outlook, by End User, 2020-2033
- China Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Japan Military Training Aircraft Market Outlook, by Type, 2020-2033
- Japan Military Training Aircraft Market Outlook, by End User, 2020-2033
- Japan Military Training Aircraft Market Outlook, by Platform, 2020-2033
- South Korea Military Training Aircraft Market Outlook, by Type, 2020-2033
- South Korea Military Training Aircraft Market Outlook, by End User, 2020-2033
- South Korea Military Training Aircraft Market Outlook, by Platform, 2020-2033
- India Military Training Aircraft Market Outlook, by Type, 2020-2033
- India Military Training Aircraft Market Outlook, by End User, 2020-2033
- India Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Southeast Asia Military Training Aircraft Market Outlook, by Type, 2020-2033
- Southeast Asia Military Training Aircraft Market Outlook, by End User, 2020-2033
- Southeast Asia Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Rest of SAO Military Training Aircraft Market Outlook, by Type, 2020-2033
- Rest of SAO Military Training Aircraft Market Outlook, by End User, 2020-2033
- Rest of SAO Military Training Aircraft Market Outlook, by Platform, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Latin America Military Training Aircraft Market Outlook, 2020 - 2033
- Latin America Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Latin America Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- Latin America Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- Latin America Military Training Aircraft Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Military Training Aircraft Market Outlook, by Type, 2020-2033
- Brazil Military Training Aircraft Market Outlook, by End User, 2020-2033
- Brazil Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Mexico Military Training Aircraft Market Outlook, by Type, 2020-2033
- Mexico Military Training Aircraft Market Outlook, by End User, 2020-2033
- Mexico Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Argentina Military Training Aircraft Market Outlook, by Type, 2020-2033
- Argentina Military Training Aircraft Market Outlook, by End User, 2020-2033
- Argentina Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Rest of LATAM Military Training Aircraft Market Outlook, by Type, 2020-2033
- Rest of LATAM Military Training Aircraft Market Outlook, by End User, 2020-2033
- Rest of LATAM Military Training Aircraft Market Outlook, by Platform, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Military Training Aircraft Market Outlook, 2020 - 2033
- Middle East & Africa Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Middle East & Africa Military Training Aircraft Market Outlook, by End User, Value (US$ Mn), 2020-2033
- Air Force
- Navy
- Others
- Middle East & Africa Military Training Aircraft Market Outlook, by Platform, Value (US$ Mn), 2020-2033
- Fixed-Wing
- Rotary-Wing
- Middle East & Africa Military Training Aircraft Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Military Training Aircraft Market Outlook, by Type, 2020-2033
- GCC Military Training Aircraft Market Outlook, by End User, 2020-2033
- GCC Military Training Aircraft Market Outlook, by Platform, 2020-2033
- South Africa Military Training Aircraft Market Outlook, by Type, 2020-2033
- South Africa Military Training Aircraft Market Outlook, by End User, 2020-2033
- South Africa Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Egypt Military Training Aircraft Market Outlook, by Type, 2020-2033
- Egypt Military Training Aircraft Market Outlook, by End User, 2020-2033
- Egypt Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Nigeria Military Training Aircraft Market Outlook, by Type, 2020-2033
- Nigeria Military Training Aircraft Market Outlook, by End User, 2020-2033
- Nigeria Military Training Aircraft Market Outlook, by Platform, 2020-2033
- Rest of Middle East Military Training Aircraft Market Outlook, by Type, 2020-2033
- Rest of Middle East Military Training Aircraft Market Outlook, by End User, 2020-2033
- Rest of Middle East Military Training Aircraft Market Outlook, by Platform, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Military Training Aircraft Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Textron Aviation Inc.
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Leonardo S.p.A.
- Korea Aerospace Industries, Ltd.
- Pilatus Aircraft Ltd.
- Boeing Company
- Lockheed Martin Corporation
- Turkish Aerospace Industries
- Diamond Aircraft Industries
- Elbit Systems Ltd.
- Aviation Industry Corporation of China
- Textron Aviation Inc.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Type
- Basic Trainer Aircraft
- Advanced Jet Trainer Aircraft
- Lead-In Fighter Trainer Aircraft
By End User
- Air Force
- Navy
- Others
By Platform
- Fixed-Wing
- Rotary-Wing
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global military training aircraft market is valued at USD 6.20 Billion in 2026, reflecting sustained defense investment in pilot training pipelines.
The market is projected to grow at a CAGR of 6.1%, reaching USD 9.38 Billion by 2033, driven by fleet modernization and expanding training requirements.
Advanced Jet Trainer Aircraft lead with a 46.0% share in 2026, reflecting their central role in bridging basic instruction and fighter qualification.
North America leads with a 34.0% share in 2026, supported by substantial defense spending and ongoing fleet modernization.
The largest opportunity lies in naval end-user demand, expanding alongside growing carrier-capable and maritime aviation training investment.
Related Reports
Automotive Alternator and Starter Motor Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive alternator and starter motor market is valued at US$32.0 billion in 2026, reaching US$38.0 billion by 2033, at a 2.5% CAGR
Automotive Start-Stop Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Hybrid Electric Vehicle (EV) Conversion Kit Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global hybrid EV conversion kit market will reach US$ 1.42 Bn by 2033, growing at 11.09% CAGR from 2026-2033, driven by cost-effective electrification
Passenger Vehicles HVAC Services Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The passenger vehicles HVAC services market, valued at US$ 48.6 billion in 2026, and projected to reach US$ 73.4 billion by 2033, growing at 6.1% CAGR
Automotive 48-Volt Electronic Junction Box and Power Distribution Center Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive 48-volt junction box and power distribution center market will reach US$ 4.55 Bn by 2033, growing at 11.68% CAGR from 2026-2033
Ultra-Fast EV Charging (350kW+) Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global Ultra-Fast EV charging systems market will grow from US$ 7.1 billion in 2026 to US$ 34.5 billion by 2033, at a 25.3% CAGR. Discover key trends