


Sulfone Polymers Market
Sulfone Polymers Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
Sulfone polymers, comprising polysulfone (PSU), polyethersulfone (PES), and polyphenylsulfone (PPSU), are high-performance amorphous thermoplastics valued for their exceptional thermal stability, hydrolytic resistance, and mechanical strength at elevated temperatures. These properties make sulfone polymers well suited to demanding applications spanning membrane filtration, medical device components, and aerospace and electronics parts that must withstand repeated sterilization, chemical exposure, or continuous high-temperature operation.
Demand growth through the 2026-2033 window is closely tied to the expansion of membrane-based water treatment and industrial filtration processes, rising use of sulfone polymers in reusable and single-use medical device components, and growing adoption in lightweight aerospace and electronics parts seeking to replace metal components without sacrificing thermal or mechanical performance. Regulatory emphasis on water reuse and stricter effluent standards in several regions is further reinforcing demand for sulfone-based membrane materials.
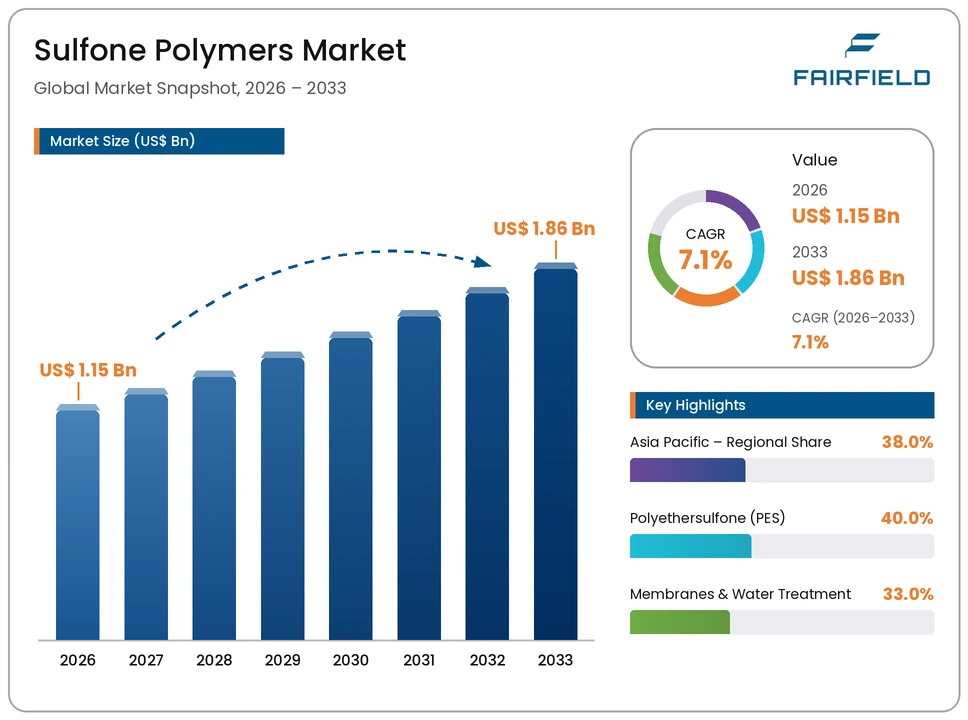
The market is valued at USD 1.15 Billion in 2026, with polymer producers directing investment toward expanding capacity for medical-grade and membrane-grade resin formulations. By 2033, the market is forecast to reach USD 1.86 Billion, reflecting steady growth across established filtration and medical applications alongside emerging aerospace and electronics adoption.
Key Highlights
- The global sulfone polymers market is valued at USD 1.15 Billion in 2026 and is projected to reach USD 1.86 Billion by 2033, expanding at a CAGR of 7.1% across the 2026-2033 forecast period.
- Polyethersulfone (PES) leads the type segment with a 40.0% share in 2026, equivalent to USD 0.46 Billion.
- Membranes & Water Treatment remains the dominant application, accounting for 33.0% of global demand, or USD 0.38 Billion, in 2026.
- Asia Pacific commands the largest regional share at 38.0% of the global market in 2026.
- Medical device applications are emerging as the fastest-growing demand pocket through 2033.
Key Growth Drivers
Growth in the sulfone polymers market is driven primarily by the expansion of membrane-based water and wastewater treatment infrastructure, as polyethersulfone and polysulfone membranes are widely used in ultrafiltration and nanofiltration systems valued for their chemical resistance and durability under repeated cleaning cycles. Rising global investment in water reuse infrastructure continues to support steady membrane material demand.
A second driver is increasing use of sulfone polymers in medical device components, including surgical instruments, dialysis equipment, and reusable device housings, where the material's ability to withstand repeated steam sterilization without degradation offers a durability advantage over alternative engineering plastics in healthcare settings requiring frequent reprocessing.
Key Restraints
The relatively high cost of sulfone polymers compared with more common engineering plastics limits their use to applications where performance requirements clearly justify the premium, restricting broader adoption in cost-sensitive general industrial applications where lower-cost alternatives can meet performance needs.
Additionally, processing sulfone polymers requires specialized equipment capable of handling their high melt temperatures, creating a barrier for converters without existing high-temperature processing capability and adding capital investment requirements for manufacturers seeking to enter sulfone polymer component production.
Market Opportunities
The growing adoption of sulfone polymers in single-use and reusable medical device components presents a substantial opportunity, as healthcare providers increasingly favor materials that combine sterilization durability with the transparency and design flexibility needed for diagnostic and surgical device applications.
A second opportunity lies in aerospace and electronics component applications, where sulfone polymers offer a lightweight alternative to metal parts without compromising thermal stability or mechanical strength. Producers that develop formulations tailored to these weight-sensitive, high-performance applications stand to capture incremental demand as manufacturers pursue lightweighting objectives.
Segmentation Analysis
- By Type
Polyethersulfone (PES) leads the type segment, accounting for 40.0% of global market value in 2026, equivalent to USD 0.46 Billion. Its leadership reflects widespread use in membrane filtration and medical device applications requiring high hydrolytic stability. Polysulfone (PSU) holds the second-largest share, commonly used in food-contact and plumbing applications given its regulatory approval history and mechanical properties. Polyphenylsulfone (PPSU) represents the fastest-growing type category through 2033, driven by rising adoption in aerospace interior components and medical device housings requiring superior impact resistance.
- By Application
Membranes & Water Treatment forms the leading application segment, representing 33.0% of global demand in 2026, or USD 0.38 Billion, reflecting sustained investment in filtration infrastructure across municipal and industrial water treatment. Medical Devices forms the second-largest segment and represents the fastest-growing application category, propelled by rising use in sterilizable device components. Aerospace & Automotive Components and Electrical & Electronics represent steady, mature application areas.
Regional Insights
- Asia Pacific
Asia Pacific holds the largest regional share, at 38.0% of the global market in 2026, equivalent to USD 0.44 Billion. The region's leadership reflects its large and expanding membrane manufacturing base, particularly in China and Japan, alongside growing medical device production capacity across the region.
- North America
North America accounts for 26.0% of the global market in 2026, valued at USD 0.30 Billion. Demand is supported by strong medical device and aerospace manufacturing activity in the United States, alongside established water treatment infrastructure investment.
- Europe
Europe represents 24.0% of the global market in 2026, or USD 0.28 Billion. The region's advanced medical device industry and stringent water quality standards sustain steady demand for sulfone-based membrane and device materials.
- Latin America
Latin America contributes 7.0% of the global market in 2026, equivalent to USD 0.08 Billion. Growth is linked to gradual expansion of water treatment infrastructure and medical device assembly operations in Brazil and Mexico.
- Middle East & Africa
Middle East & Africa holds 5.0% of the global market in 2026, valued at USD 0.06 Billion. Demand is concentrated in water treatment and desalination-adjacent applications within Gulf Cooperation Council countries investing in water infrastructure.
Competitive Landscape
The global sulfone polymers market is moderately concentrated, with a limited number of established specialty polymer producers holding strong positions supported by long-standing manufacturing expertise and regulatory approval histories for medical and food-contact applications. Competition centers on resin purity, consistency across production batches, and the ability to support customers through application-specific formulation development. Producers are increasingly differentiating through membrane-grade and medical-grade specialty formulations rather than competing on general-purpose resin pricing alone.
Key Market Players
- Solvay S.A.
- BASF SE
- SABIC
- Sumitomo Chemical Co., Ltd.
- Victrex plc
- Ensinger GmbH
- Röchling SE & Co. KG
- Mitsubishi Chemical Advanced Materials
- RTP Company
- Avient Corporation
Market Segmentation
By Type
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
By Application
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
By Form
- Resins & Pellets
- Films & Membranes
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Sulfone Polymers Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Sulfone Polymers Market Outlook, 2020 - 2033
- Global Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- Global Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- Global Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- Global Sulfone Polymers Market Outlook, by Region, Value (US$ Bn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- North America Sulfone Polymers Market Outlook, 2020 - 2033
- North America Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- North America Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- North America Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- North America Sulfone Polymers Market Outlook, by Country, Value (US$ Bn), 2020-2033
- U.S. Sulfone Polymers Market Outlook, by Type, 2020-2033
- U.S. Sulfone Polymers Market Outlook, by Application, 2020-2033
- U.S. Sulfone Polymers Market Outlook, by Form, 2020-2033
- Canada Sulfone Polymers Market Outlook, by Type, 2020-2033
- Canada Sulfone Polymers Market Outlook, by Application, 2020-2033
- Canada Sulfone Polymers Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Europe Sulfone Polymers Market Outlook, 2020 - 2033
- Europe Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- Europe Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- Europe Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- Europe Sulfone Polymers Market Outlook, by Country, Value (US$ Bn), 2020-2033
- Germany Sulfone Polymers Market Outlook, by Type, 2020-2033
- Germany Sulfone Polymers Market Outlook, by Application, 2020-2033
- Germany Sulfone Polymers Market Outlook, by Form, 2020-2033
- Italy Sulfone Polymers Market Outlook, by Type, 2020-2033
- Italy Sulfone Polymers Market Outlook, by Application, 2020-2033
- Italy Sulfone Polymers Market Outlook, by Form, 2020-2033
- France Sulfone Polymers Market Outlook, by Type, 2020-2033
- France Sulfone Polymers Market Outlook, by Application, 2020-2033
- France Sulfone Polymers Market Outlook, by Form, 2020-2033
- U.K. Sulfone Polymers Market Outlook, by Type, 2020-2033
- U.K. Sulfone Polymers Market Outlook, by Application, 2020-2033
- U.K. Sulfone Polymers Market Outlook, by Form, 2020-2033
- Spain Sulfone Polymers Market Outlook, by Type, 2020-2033
- Spain Sulfone Polymers Market Outlook, by Application, 2020-2033
- Spain Sulfone Polymers Market Outlook, by Form, 2020-2033
- Russia Sulfone Polymers Market Outlook, by Type, 2020-2033
- Russia Sulfone Polymers Market Outlook, by Application, 2020-2033
- Russia Sulfone Polymers Market Outlook, by Form, 2020-2033
- Rest of Europe Sulfone Polymers Market Outlook, by Type, 2020-2033
- Rest of Europe Sulfone Polymers Market Outlook, by Application, 2020-2033
- Rest of Europe Sulfone Polymers Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Asia Pacific Sulfone Polymers Market Outlook, 2020 - 2033
- Asia Pacific Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- Asia Pacific Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- Asia Pacific Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- Asia Pacific Sulfone Polymers Market Outlook, by Country, Value (US$ Bn), 2020-2033
- China Sulfone Polymers Market Outlook, by Type, 2020-2033
- China Sulfone Polymers Market Outlook, by Application, 2020-2033
- China Sulfone Polymers Market Outlook, by Form, 2020-2033
- Japan Sulfone Polymers Market Outlook, by Type, 2020-2033
- Japan Sulfone Polymers Market Outlook, by Application, 2020-2033
- Japan Sulfone Polymers Market Outlook, by Form, 2020-2033
- South Korea Sulfone Polymers Market Outlook, by Type, 2020-2033
- South Korea Sulfone Polymers Market Outlook, by Application, 2020-2033
- South Korea Sulfone Polymers Market Outlook, by Form, 2020-2033
- India Sulfone Polymers Market Outlook, by Type, 2020-2033
- India Sulfone Polymers Market Outlook, by Application, 2020-2033
- India Sulfone Polymers Market Outlook, by Form, 2020-2033
- Southeast Asia Sulfone Polymers Market Outlook, by Type, 2020-2033
- Southeast Asia Sulfone Polymers Market Outlook, by Application, 2020-2033
- Southeast Asia Sulfone Polymers Market Outlook, by Form, 2020-2033
- Rest of SAO Sulfone Polymers Market Outlook, by Type, 2020-2033
- Rest of SAO Sulfone Polymers Market Outlook, by Application, 2020-2033
- Rest of SAO Sulfone Polymers Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Latin America Sulfone Polymers Market Outlook, 2020 - 2033
- Latin America Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- Latin America Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- Latin America Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- Latin America Sulfone Polymers Market Outlook, by Country, Value (US$ Bn), 2020-2033
- Brazil Sulfone Polymers Market Outlook, by Type, 2020-2033
- Brazil Sulfone Polymers Market Outlook, by Application, 2020-2033
- Brazil Sulfone Polymers Market Outlook, by Form, 2020-2033
- Mexico Sulfone Polymers Market Outlook, by Type, 2020-2033
- Mexico Sulfone Polymers Market Outlook, by Application, 2020-2033
- Mexico Sulfone Polymers Market Outlook, by Form, 2020-2033
- Argentina Sulfone Polymers Market Outlook, by Type, 2020-2033
- Argentina Sulfone Polymers Market Outlook, by Application, 2020-2033
- Argentina Sulfone Polymers Market Outlook, by Form, 2020-2033
- Rest of LATAM Sulfone Polymers Market Outlook, by Type, 2020-2033
- Rest of LATAM Sulfone Polymers Market Outlook, by Application, 2020-2033
- Rest of LATAM Sulfone Polymers Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Middle East & Africa Sulfone Polymers Market Outlook, 2020 - 2033
- Middle East & Africa Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
- Middle East & Africa Sulfone Polymers Market Outlook, by Application, Value (US$ Bn), 2020-2033
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
- Middle East & Africa Sulfone Polymers Market Outlook, by Form, Value (US$ Bn), 2020-2033
- Resins & Pellets
- Films & Membranes
- Middle East & Africa Sulfone Polymers Market Outlook, by Country, Value (US$ Bn), 2020-2033
- GCC Sulfone Polymers Market Outlook, by Type, 2020-2033
- GCC Sulfone Polymers Market Outlook, by Application, 2020-2033
- GCC Sulfone Polymers Market Outlook, by Form, 2020-2033
- South Africa Sulfone Polymers Market Outlook, by Type, 2020-2033
- South Africa Sulfone Polymers Market Outlook, by Application, 2020-2033
- South Africa Sulfone Polymers Market Outlook, by Form, 2020-2033
- Egypt Sulfone Polymers Market Outlook, by Type, 2020-2033
- Egypt Sulfone Polymers Market Outlook, by Application, 2020-2033
- Egypt Sulfone Polymers Market Outlook, by Form, 2020-2033
- Nigeria Sulfone Polymers Market Outlook, by Type, 2020-2033
- Nigeria Sulfone Polymers Market Outlook, by Application, 2020-2033
- Nigeria Sulfone Polymers Market Outlook, by Form, 2020-2033
- Rest of Middle East Sulfone Polymers Market Outlook, by Type, 2020-2033
- Rest of Middle East Sulfone Polymers Market Outlook, by Application, 2020-2033
- Rest of Middle East Sulfone Polymers Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Sulfone Polymers Market Outlook, by Type, Value (US$ Bn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Solvay S.A.
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- BASF SE
- SABIC
- Sumitomo Chemical Co., Ltd.
- Victrex plc
- Ensinger GmbH
- Röchling SE & Co. KG
- Mitsubishi Chemical Advanced Materials
- RTP Company
- Avient Corporation
- Solvay S.A.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Type
- Polysulfone (PSU)
- Polyethersulfone (PES)
- Polyphenylsulfone (PPSU)
By Application
- Membranes & Water Treatment
- Medical Devices
- Aerospace & Automotive Components
- Electrical & Electronics
- Others
By Form
- Resins & Pellets
- Films & Membranes
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global sulfone polymers market is valued at USD 1.15 Billion in 2026, reflecting steady demand across filtration, medical, and specialty industrial applications.
The market is projected to grow at a CAGR of 7.1%, reaching USD 1.86 Billion by 2033, driven by membrane filtration expansion and rising medical device use.
Polyethersulfone (PES) leads with a 40.0% share in 2026, supported by its widespread use in membrane filtration and medical applications.
Asia Pacific leads with a 38.0% share in 2026, driven by its large membrane manufacturing and medical device production base.
The largest opportunity lies in medical device components, where sulfone polymers' sterilization durability supports growing adoption in reusable and diagnostic devices.
Related Reports
Automotive NVH Materials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive NVH materials market is valued at US$13.8 billion in 2026, reaching US$20.5 billion by 2033, growing at a 5.82% CAGR
Acrylonitrile Butadiene Styrene Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acrylonitrile butadiene styrene market is valued at US$27.4 billion in 2026, reaching US$38.6 billion by 2033, growing at a 5.02% CAGR
Tank Mix Adjuvants Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global tank mix adjuvants market is valued at US$4.3 billion in 2026, reaching US$6.6 billion by 2033, growing at a 6.3% CAGR
Glass Flake Coatings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The glass flake coatings market is projected to grow from US$0.64 billion in 2026 to US$0.96 billion by 2033, at a 5.96% CAGR
Paint Protection Films Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global paint protection films market is valued at US$1.05 billion in 2026 and is projected to reach US$2.25 billion by 2033, growing at 11.5% CAGR
Electrical Steel Coatings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The electrical steel coatings market, valued at US$ 1.42 billion in 2026, and forecast to reach US$ 2.41 billion by 2033, growing at a 7.85% CAGR