


Agriculture Drone Market
Agriculture Drone Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Agriculture Drone Market Size and Trend Analysis
What drives agricultural drone purchases and services?
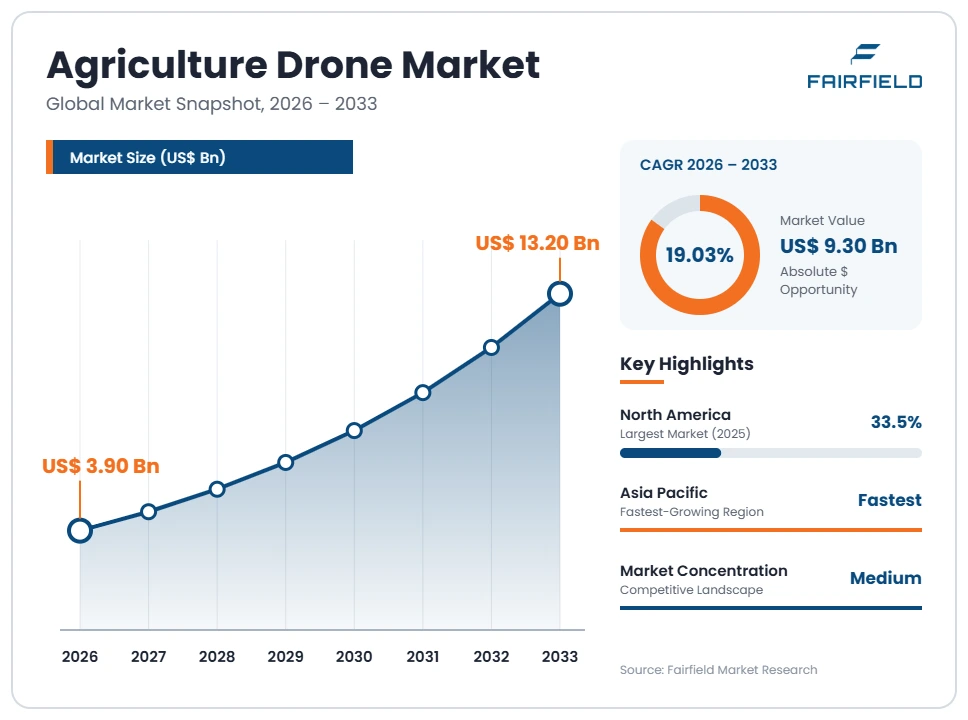
The global Agriculture Drone market size is expected to be valued at US$3.90 billion in 2026 and projected to reach US$13.20 billion by 2033, growing at a CAGR of 19.03% between 2026 and 2033. Demand concerns agricultural unmanned aircraft, directly associated software, and attributable services. Customers assess field tasks, operating conditions, support, and utilization before choosing ownership or a service arrangement rather than assume every farm needs identical equipment.
During 2020–2025, suppliers expanded application aircraft and connections between field information and operating tasks. A comparable historical CAGR is unavailable; the selected benchmark values 2025 at US$3.40 billion. Crop observation, suitable application work, and service-provider models support demand. Weather, permissions, training, and logistics can constrain adoption. The outlook depends on usable field capacity and accepted customer work, with chemicals, general farm machinery, and the value of harvested crops excluded from direct agriculture drone revenue comparison.
Key Report Takeaways
- By Field Task: Observation Missions gather agricultural information, Application Missions deliver material, and Mixed-Task Systems cover inseparable purchased functions. Comparable shares are unavailable for this independent allocation. Flight capability, payload, and data workflow should be assessed against the actual field job.
- By Purchasing Model: Grower Ownership and Service-Provider Ownership separate the principal buyer of equipment. Purchased Field Services covers customer payments for contracted drone work. Equipment and downstream service transactions require clear boundaries to avoid repeatedly counting the same commercial activity without identifying the deliverable.
- By Operational Package: Aircraft Systems, Digital Workflow Products, and Operational Services distinguish equipment, software, and directly related deployment support. Comparable leadership and growth rankings are unavailable. Bundles need allocation, and the entire precision-farming software estate should not automatically enter the drone market.
- By Geography: North America led the selected benchmark in 2025, while Asia Pacific has its fastest-growth direction. The historical leadership year is retained. Country rankings and universal operating permissions are not inferred from product launches, dealer announcements, or broad agricultural activity.
- By Competition: DJI, XAG, Hylio, Pyka, and Yamaha Motor document agricultural unmanned-aircraft capabilities. Their platforms differ in scale and use. Buyers should verify current local availability, support, and intended operation rather than compare entire company revenues as agriculture drone shares.
Global Agriculture Drone Market Trends and Insights
Drivers Impact Analysis
Ratings reflect analyst judgement about purchasing mechanisms, without assigning unsupported numerical contributions to the forecast.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Field observation linked to operating decisions | High | Agricultural production regions | Short term (≤2 years) |
| Suitable aerial application and service workflows | High | Markets with supported operations | Medium term (2–4 years) |
Agriculture Drone Observation Gains Value Through Actionable Workflows
Field observation supports drone demand when customers can turn collected information into a useful agricultural task. Images or maps alone do not establish a purchasing benefit. A grower or service provider needs a clear objective, suitable collection conditions, and a way to interpret the output. The commercial requirement therefore extends from flight planning to data handling and the customer’s decision process. Buyers should assess the complete workflow rather than assume more sensors guarantee results.
XAG’s documented collaboration with PIX4D connects prescription maps with agricultural drone functions. This establishes an integration example without proving universal input savings or yield improvement. Suppliers can differentiate through compatible data products and practical support. Customers need to confirm which information is required and how it will be used. Revenue should distinguish aircraft, mapping software, and professional interpretation, preventing every digital-farming expense from being allocated to the drone merely because aerial information forms one input.
Agriculture Drone Application Demand Depends on Practical Field Delivery
Application work creates demand where an unmanned aircraft can perform a suitable field task within the customer’s operating constraints. Purchasing depends on more than payload capacity. Charging, replenishment, field access, weather, staff, and maintenance influence the usable work completed during an operating window. Customers should therefore compare complete field workflows rather than a single advertised flight rate. A larger aircraft can be useful for one operation and unsuitable for another, making the actual crop, terrain, and service arrangement important procurement inputs.
DJI, XAG, Hylio, and Pyka document agricultural application aircraft. Their offerings demonstrate available approaches, not interchangeable performance or blanket permission for every task. Buyers should verify local product status and supported use. Suppliers can improve proposals through realistic demonstrations and continuing support. Commercial demand becomes more concrete when expected utilization and service logistics are established, keeping aircraft sales and contracted application work distinct from chemical purchases or crop value.
Restraints Impact Analysis
Utilization, operating requirements, and support can restrict adoption even where customers identify a useful agricultural task.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Seasonal utilization and field logistics | High | Growers and service operators | Short term (≤2 years) |
| Permissions, training, and support obligations | Medium | Jurisdiction-specific deployments | Medium term (2–4 years) |
Agriculture Drone Economics Depend on Seasonal Utilization
Seasonal utilization can limit purchasing when an aircraft is needed intensively for short periods but remains underused otherwise. Travel, setup, charging, replenishment, maintenance, and unsuitable weather reduce the time available for paid field work. A nominal equipment capacity does not capture those constraints. Buyers therefore need a realistic operating calendar and customer pipeline before estimating ownership economics. The commercial issue is whether sufficient suitable work can be completed and paid for, beyond a successful demonstration.
Supplier portfolios from DJI, XAG, and Hylio show different system choices, but do not establish one universal cost per hectare. Specific expenses include batteries, charging equipment, replacement parts, staff, transport, and technical support. Service providers also need to coordinate customers whose work windows may overlap. Buyers should assess utilization and continuing costs together. Suppliers can support adoption through transparent equipment packages and training, while keeping modeled productivity separate from documented results under customer conditions.
Agriculture Drone Operating Requirements Can Delay Commercial Use
Operating requirements can delay adoption when a product launch is mistaken for authorization to perform the intended task. Aircraft operation, agricultural application, and the material being applied can involve separate requirements. Customers also need training and suitable maintenance support. These factors differ by location and configuration, so a broad claim about global product availability is insufficient for procurement. Buyers should confirm the exact intended operation before assuming immediate commercial usability.
The Federal Aviation Administration publishes specific guidance for dispensing chemicals and agricultural products with unmanned aircraft under Part 137. This provides one documented United States context rather than a universal international rule. Costs can include training, application-related procedures, documentation, and technical support. Suppliers should distinguish product capabilities from customer operating responsibilities. A clear deployment plan can reduce uncertainty, but it should not promise that aircraft purchase alone establishes all permissions or removes the need to verify local operating conditions.
Market Opportunities
Agriculture Drone Contract Services Can Reach Customers Without Ownership
Contract services create opportunities where growers have suitable tasks but insufficient utilization or resources to justify aircraft ownership. Providers can earn revenue from defined field work, planning, and associated reporting. The commercial offer should specify the task and conditions rather than promise a universal agronomic result. Customers need to understand scheduling, exclusions, and what happens when weather or field access changes. The provider’s opportunity depends on executable work and service density, beyond the number of farms.
Manufacturers, dealers, and independent operators can support this model through equipment, training, and maintenance. Hylio and other agricultural aircraft suppliers document relevant products, while broader platforms support different field tasks. Providers should assess travel, charging, replenishment, and overlapping customer windows. Buyers can compare service access with their own ownership requirements. Revenue reporting should distinguish equipment sales from contracted field activity, making the service opportunity visible without adding aircraft value repeatedly for each assignment.
Agriculture Drone Data Integration Can Support Repeatable Application Planning
Data integration creates opportunities for software and service providers that connect agricultural observations with a compatible operating plan. Customers may need field boundaries, prescription maps, or consistent records across repeated tasks. The commercial offer can include software access, setup, and technical enablement around a specific workflow. It should not be presented as proof that an aircraft or map can determine every farm decision. Customers retain responsibility for field operations, interpretation, and applied materials.
XAG and PIX4D documented prescription-map integration in October 2024, providing a concrete development supporting this opportunity. Suppliers can pursue growers and service operators with repeatable data needs and compatible aircraft. Buyers should assess file compatibility, update practices, and local support before committing. Contracts can separate software, mapping, and application services. This creates measurable digital revenue while preventing the entire value of farm-management platforms or inputs from being counted as agriculture drone software through data exchange alone.
Segment Analysis
- By Field Task: Agriculture Drone Observation and Application Need Different Evidence
Observation Missions covers purchased drone functions primarily collecting agricultural data. Application Missions covers functions primarily delivering material during the field task. Mixed-Task Systems covers inseparable purchased capabilities serving both purposes, with module-level allocation used where values are disclosed. Classification follows the purchased function rather than assuming one airframe represents several complete market transactions whenever its payload or software changes.
Comparable shares and fastest-growth rates are unavailable. XAG documents multiple agricultural functions, while DJI, Hylio, and Pyka establish application-aircraft examples. Observation buyers need suitable data and interpretation, while application buyers need a practical field-delivery workflow. Neither requires a universal aircraft architecture. Suppliers should demonstrate the actual task, operating limits, and support. Buyers should compare complete mission economics and responsibilities, keeping claims about imagery, application rate, or crop outcomes connected to the specific configuration and evidence rather than a broad category label alone.
- By Purchasing Model: Agriculture Drone Service Use Differs From Equipment Ownership
Grower Ownership covers aircraft systems purchased by the agricultural producer for its operations. Service-Provider Ownership covers equipment purchased by organizations delivering work to other customers. Purchased Field Services covers the final customer’s separately contracted drone activity. The model therefore distinguishes equipment buyers from service users rather than presenting ownership and service fees as directly comparable installed-unit shares. Each transaction requires an identified deliverable and reporting boundary.
Consistent leadership and growth rankings are unavailable for this independent structure. A grower can use contracted services while also owning equipment, so revenue must be allocated by the actual purchase. Suppliers should evaluate utilization, customer density, and continuing support. Service operators need scheduling and logistics capabilities beyond aircraft ownership. Buyers should compare suitable local service with complete ownership costs, avoiding the assumption that every farm needs its own drone or that outsourced field work automatically removes all customer planning and operational responsibilities.
- By Operational Package: Agriculture Drone Bundles Need Transparent Allocation
Aircraft Systems includes agricultural unmanned aircraft and directly associated equipment supplied as the operating system. Digital Workflow Products includes separately priced software or data functions attributable to drone tasks. Operational Services includes separately purchased setup, training, technical support, and contracted field work. Contracted field work is identified within the purchasing-model analysis and allocated consistently, preventing a complete bundle from being repeatedly counted across equipment, software, service, and ownership categories.
Comparable package shares and fastest-growth rates are unavailable. DJI and XAG document agricultural systems, while the PIX4D integration establishes a directly relevant software context. Buyers should identify which equipment, updates, accessories, and services are included. A nominal aircraft price can exclude items needed for actual operation. Suppliers should explain the complete package and recurring costs, keeping agricultural drone revenue separate from chemicals, general farm-management software, transport vehicles, and unrelated machinery that may be used alongside the system in customer operations.
Geography Analysis
- Which Region Is Leading the Agriculture Drone Market?
North America led the selected benchmark with 33.5% revenue share in 2025. The United States provides supplier examples through Hylio and Pyka, while Canada is another agricultural customer setting. The historical share is not relabeled as a current estimate. Buyers need to verify the actual aircraft, intended task, and local operating requirements rather than infer permission or availability from a general product announcement.
Opportunities include suitable contracted field work and data-linked workflows. Seasonal demand, logistics, training, and maintenance can constrain utilization. Suppliers should support realistic demonstrations and complete equipment packages. Customers should distinguish purchased capacity from usable field output, making service coverage and operating economics central to procurement rather than relying on payload or advertised application performance.
- Agriculture Drone European Purchases Require Local Task Fit
Europe offers agricultural drone opportunities across field observation and suitable application work. Germany, France, Spain, and the United Kingdom provide varied customer settings. XAG’s Agritechnica presentation supplies a documented product-development example, not evidence of uniform authorization across Europe. Crop type, field conditions, local requirements, and service support affect the commercial case, and comparable national revenue rankings are not adopted here.
Opportunities include data integration and defined service packages. Buyers should assess whether the proposed task and aircraft are locally supportable before purchasing. Weather, seasonal scheduling, and training can constrain utilization. Suppliers can improve proposals through compatible workflows and clear recurring costs. Regional assessment should follow actual customer tasks and contracts, keeping product exhibition, distribution availability, and accepted commercial use distinct.
- Which Region Is Growing Fastest in the Agriculture Drone Market?
Asia Pacific has the fastest-growth direction in the selected benchmark. China, India, Japan, and Australia provide different agricultural customer environments. DJI, XAG, and Yamaha Motor document relevant unmanned-aircraft capabilities. Their participation establishes supplier experience, while current local product status requires confirmation. No uniform national growth ranking or operating permission is inferred from the regional outlook.
Opportunities include application services, observation workflows, and technical support. Field scale, charging logistics, training, and seasonal utilization can constrain adoption. Suppliers should match systems to actual customer tasks rather than assume the largest payload is always preferable. Buyers should compare ownership and services using realistic work windows. Market opportunity becomes more concrete through supported aircraft, compatible digital processes, and contracted field activity rather than general farm acreage alone.
- Agriculture Drone Latin American Services Depend on Field Logistics
Latin America offers opportunities across agricultural observation and suitable application work. Brazil, Mexico, and Argentina provide relevant customer settings. DJI’s regional distribution announcements and Pyka’s documented agricultural activity establish commercial contexts without supplying national market shares. Aircraft availability should still be distinguished from permission for every task, and regional acreage does not directly measure drone-equipment revenue.
Constraints include customer dispersion, transport, maintenance, weather, and operating budgets. Service providers can create opportunities by organizing practical work schedules and technical support. Buyers should assess the task, timing, and complete service arrangement. Suppliers need to distinguish aircraft sales from downstream field-service receipts, avoiding repeated allocation of chemical purchases, crop value, or unrelated farm equipment to the agricultural drone market simply because those activities occur during the same operation.
- Agriculture Drone Middle East & Africa Needs Practical Support Models
Middle East & Africa presents selective opportunities in agricultural observation, research-linked field work, and suitable application services. South Africa, Morocco, and Saudi Arabia are potential customer-development settings rather than verified regional share leaders. Buyers should establish the actual crop, field task, operating environment, and local product support before treating general agricultural modernization spending as addressable drone demand.
Barriers include equipment cost, training, maintenance, charging logistics, and seasonal utilization. Providers can pursue defined tasks through partners capable of continuing support and realistic scheduling. Customers should compare services with ownership and confirm intended-use requirements. Opportunities are most assessable when an aircraft and workflow solve a documented field problem, with clear deliverables and operating responsibilities rather than a promise that aerial technology alone guarantees higher yields or universally lower agricultural input expenditure.
Competitive Landscape
Competition combines agricultural drone manufacturers, specialist application-aircraft suppliers, software providers, and service operators. Medium overall concentration is an analyst judgement reflecting different task and geographic markets, rather than a measured company-share calculation. DJI, XAG, Hylio, Pyka, and Yamaha Motor have documented agricultural unmanned-aircraft capabilities. Their wider revenues and platform architectures are not directly comparable agriculture drone shares. Current product availability and service coverage should be verified locally rather than inferred from historical participation or a global portfolio description.
Buyers compare task suitability, usable field capacity, logistics, data workflow, and continuing support. New entrants can address regional service or specialist tasks, but need aircraft access, trained staff, and dependable maintenance. Manufacturers likewise need to show how equipment fits actual work windows. An advertised capacity or exhibition demonstration is commercially incomplete if charging, replenishment, field access, and support are not included in the operating model proposed to the customer.
Documented developments show continued attention to aircraft and software integration. XAG and PIX4D announced prescription-map integration in October 2024. DJI introduced its Agras T100, T70P, and T25P globally in July 2025. XAG presented the P150 Max at Agritechnica in November 2025. These developments establish product activity, not identical local availability, operating permission, or agronomic outcomes across every customer market.
Strategic differentiation should connect a supported aircraft with a usable agricultural workflow. Suppliers can strengthen proposals through realistic task demonstrations, training, and transparent packages. Buyers should distinguish equipment, digital products, technical support, and contracted field work. Competitive analysis should follow verified capabilities and commercial scope, avoiding predicted winners or market-share rankings from broader company revenue. This also prevents chemicals, crop value, and unrelated precision-farming infrastructure from inflating the drone opportunity when they are merely adjacent inputs or customer activities.
Recent Industry Developments
- October 2024: XAG and PIX4D introduced prescription-map integration for agricultural drones, connecting field data with compatible application workflows.
- July 2025: DJI globally launched Agras T100, T70P, and T25P, extending its documented agricultural aircraft portfolio.
- November 2025: XAG presented P150 Max at Agritechnica, alongside a ground rover that remains outside the drone-equipment boundary.
Companies Covered in the Report
DJI; XAG; Hylio; Pyka; Yamaha Motor; PIX4D. Software participation is distinguished from aircraft manufacturing, and broader group activity is excluded from direct agriculture drone revenue comparison.
Agriculture Drone Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$3.90 Billion |
| Market Size 2033 | US$13.20 Billion |
| CAGR 2026–2033 | 19.03% |
| Absolute Dollar Opportunity | US$9.30 Billion |
| Largest Market | North America, 2025 benchmark leadership |
| Fastest-Growing Market | Asia Pacific, selected outlook |
| Market Concentration | Medium overall, analyst judgement |
| Major Players | DJI, XAG, Hylio, Pyka, Yamaha Motor |
Agriculture Drone Market Segmentation
Field Task
- Observation Missions
- Application Missions
- Mixed-Task Systems
Purchasing Model
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
Operational Package
- Aircraft Systems
- Digital Workflow Products
- Operational Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Agriculture Drone Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Agriculture Drone Observation Gains Value Through Actionable Workflows
- Agriculture Drone Application Demand Depends on Practical Field Delivery
- Restraints
- Agriculture Drone Economics Depend on Seasonal Utilization
- Agriculture Drone Operating Requirements Can Delay Commercial Use
- Market Opportunities
- Agriculture Drone Contract Services Can Reach Customers Without Ownership
- Agriculture Drone Data Integration Can Support Repeatable Application Planning
- Drivers
- Global Agriculture Drone Market Outlook, 2020–2033
- Global Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- Global Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- Global Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- Global Agriculture Drone Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- North America Agriculture Drone Market Outlook, 2020–2033
- North America Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- North America Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- North America Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- North America Agriculture Drone Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Agriculture Drone Market Outlook, by Field Task, 2020–2033
- United States Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- United States Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Canada Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Canada Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Canada Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- North America Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Europe Agriculture Drone Market Outlook, 2020–2033
- Europe Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- Europe Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- Europe Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- Europe Agriculture Drone Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Germany Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Germany Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- France Agriculture Drone Market Outlook, by Field Task, 2020–2033
- France Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- France Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Spain Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Spain Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Spain Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- United Kingdom Agriculture Drone Market Outlook, by Field Task, 2020–2033
- United Kingdom Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- United Kingdom Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Europe Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Asia Pacific Agriculture Drone Market Outlook, 2020–2033
- Asia Pacific Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- Asia Pacific Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- Asia Pacific Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- Asia Pacific Agriculture Drone Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Agriculture Drone Market Outlook, by Field Task, 2020–2033
- China Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- China Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- India Agriculture Drone Market Outlook, by Field Task, 2020–2033
- India Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- India Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Japan Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Japan Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Japan Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Australia Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Australia Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Australia Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Asia Pacific Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Latin America Agriculture Drone Market Outlook, 2020–2033
- Latin America Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- Latin America Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- Latin America Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- Latin America Agriculture Drone Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Brazil Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Brazil Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Mexico Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Mexico Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Mexico Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Argentina Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Argentina Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Argentina Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Latin America Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Middle East & Africa Agriculture Drone Market Outlook, 2020–2033
- Middle East & Africa Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Observation Missions
- Application Missions
- Mixed-Task Systems
- Middle East & Africa Agriculture Drone Market Outlook, by Purchasing Model, Value (US$ Billion), 2020–2033
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
- Middle East & Africa Agriculture Drone Market Outlook, by Operational Package, Value (US$ Billion), 2020–2033
- Aircraft Systems
- Digital Workflow Products
- Operational Services
- Middle East & Africa Agriculture Drone Market Outlook, by Country, Value (US$ Billion), 2020–2033
- South Africa Agriculture Drone Market Outlook, by Field Task, 2020–2033
- South Africa Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- South Africa Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Morocco Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Morocco Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Morocco Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Saudi Arabia Agriculture Drone Market Outlook, by Field Task, 2020–2033
- Saudi Arabia Agriculture Drone Market Outlook, by Purchasing Model, 2020–2033
- Saudi Arabia Agriculture Drone Market Outlook, by Operational Package, 2020–2033
- Middle East & Africa Agriculture Drone Market Outlook, by Field Task, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- DJI
- XAG
- Hylio
- Pyka
- Yamaha Motor
- PIX4D
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Field Task
- Observation Missions
- Application Missions
- Mixed-Task Systems
Purchasing Model
- Grower Ownership
- Service-Provider Ownership
- Purchased Field Services
Operational Package
- Aircraft Systems
- Digital Workflow Products
- Operational Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Agriculture Drone Market is estimated at US$3.90 billion in 2026, covering defined agricultural aircraft, directly associated digital products, enablement, and attributable field services.
The market is projected to reach US$13.20 billion by 2033, implying 19.03% annual growth and US$9.30 billion additional opportunity within the defined commercial scope.
A comparable field-task leader is unavailable; Observation Missions, Application Missions, and Mixed-Task Systems require different aircraft, data workflows, operating conditions, and support arrangements.
Asia Pacific has the fastest-growth direction in the selected benchmark, with opportunities depending on suitable field tasks, service models, technical support, and practical utilization.
North America led the selected benchmark with 33.5% revenue share in 2025; the historical observation is not presented as a current regional estimate.
Related Reports
LED Drivers and Power Supplies for Horticulture Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global LED drivers and power supplies for horticulture market is valued at US$1.15 billion in 2026, reaching US$2.51 billion by 2033, growing at an 11.8% CAGR
Inkjet Printers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global inkjet printers market is valued at US$50.4 billion in 2026, reaching US$58.8 billion by 2033, growing at a 2.2% CAGR
LED Lighting Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The LED lighting market is projected to grow from US$84.0 billion in 2026 to US$112.0 billion by 2033 at a 4.2% CAGR. Explore segments and trends.
LTE Advanced Pro Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The LTE Advanced Pro market is forecast to grow from US$ 22.30 billion in 2026 to US$ 42.91 billion by 2033 at a 9.8% CAGR.
Advanced Semiconductor Cooling Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The advanced semiconductor cooling systems market is projected to grow from US$ 6.8 billion in 2026 to US$ 24.9 billion by 2033 at a 20.4% CAGR.
Plastic Transistors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global plastic transistors market is valued at US$0.4 billion in 2026, reaching US$0.9 billion by 2033, growing at a 12.3% CAGR