


Feed Binders Market
Feed Binders Market Insights, Competitive Landscape, and Market Forecast 2033
Market Overview
Feed binders are additives incorporated into animal feed formulations to improve pellet durability, reduce fines generation during handling and transport, and maintain feed structural integrity through the pelleting and distribution process. As feed manufacturers increasingly rely on pelleted feed formats for their handling and nutritional consistency advantages, binders have become an essential formulation component ensuring pellets withstand the mechanical stress of production, transport, and on-farm handling without excessive breakage.
Demand growth through the 2026-2033 window is closely tied to expanding global aquaculture production, where pellet durability is particularly critical given feed's exposure to water during consumption, sustained growth in pelleted poultry feed adoption seeking improved feed conversion efficiency, and rising feed manufacturer focus on reducing fines-related feed waste across the value chain. Growing scale and mechanization of feed manufacturing operations globally continues to reinforce demand for reliable, consistent-performing binder additives.
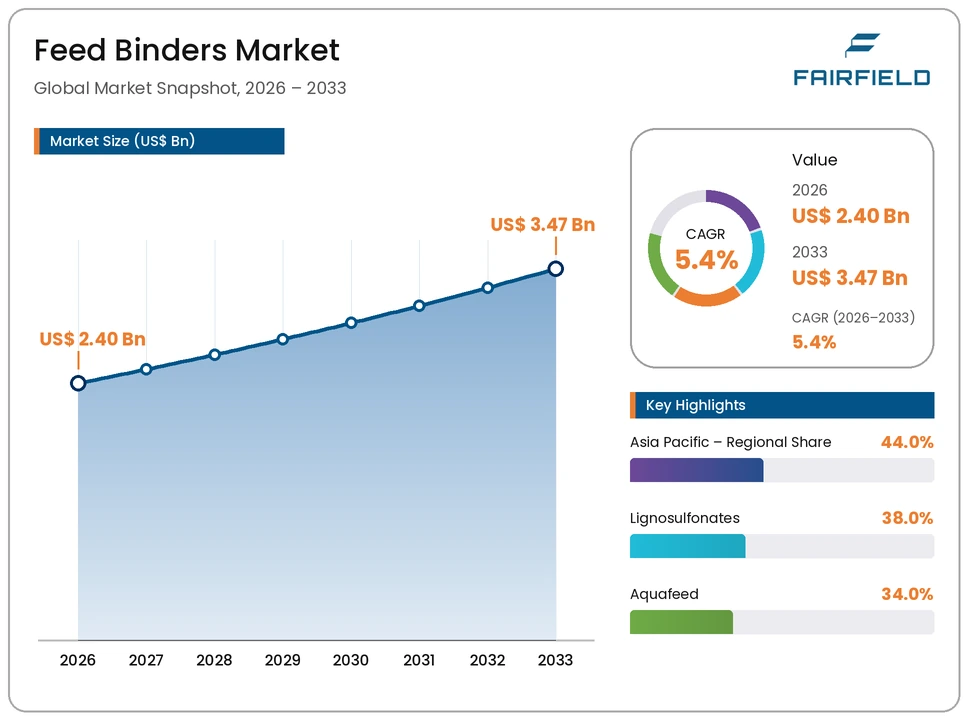
The market is valued at USD 2.40 Billion in 2026, with ingredient manufacturers directing investment toward natural and clean-label binder formulations that meet evolving feed ingredient transparency expectations while maintaining pellet quality performance. By 2033, the market is forecast to reach USD 3.47 Billion, reflecting steady growth across established aquafeed applications alongside expanding poultry feed adoption.
Key Highlights
- The global feed acidifiers market is valued at USD 3.90 Billion in 2026 and is projected to reach USD 6.06 Billion by 2033, expanding at a CAGR of 6.5% across the 2026-2033 forecast period.
- Organic Acid Blends lead the type segment with a 51.0% share in 2026, equivalent to USD 1.99 Billion.
- Poultry remains the dominant livestock segment, accounting for 41.0% of global demand, or USD 1.60 Billion, in 2026.
- Europe commands the largest regional share at 32.0% of the global market in 2026.
- Aquaculture applications are emerging as the fastest-growing livestock segment through 2033.
Market Dynamics
Key Growth Drivers
Growth in the feed acidifiers market is driven primarily by continued global phase-out of antibiotic growth promoters, as regulatory restrictions across an increasing number of countries require livestock producers to adopt alternative approaches to maintaining gut health and production performance, with feed acidifiers representing one of the most established and widely validated alternatives available.
A second driver is growing producer awareness of feed acidifiers' documented benefits for feed conversion efficiency, as improved nutrient digestibility translates directly into production cost savings that provide a measurable return on investment beyond the animal health benefits alone, strengthening the economic case for acidifier adoption across cost-conscious livestock operations.
Key Restraints
Handling and storage considerations for acidic feed additives, including potential corrosion of feed manufacturing equipment and safety precautions required for concentrated acid products, create operational complexity for feed manufacturers that must be managed through appropriate equipment and handling protocols.
Additionally, variable efficacy across different livestock species and production conditions requires careful product selection and dosing optimization, creating a technical barrier for producers without access to adequate nutritional consulting support to determine the most appropriate acidifier formulation for their specific operation.
Market Opportunities
The expansion of feed acidifier use in aquaculture presents a substantial opportunity, as growing global aquaculture production increasingly seeks non-antibiotic approaches to managing pathogen pressure in intensive farming systems, an application area that has historically received less acidifier product development attention than poultry and swine.
A second opportunity lies in the development of encapsulated and targeted-release acidifier formulations that improve delivery to specific regions of the digestive tract, allowing manufacturers to develop more precisely targeted products addressing particular pathogen or digestive health challenges rather than relying on broad-spectrum acidification alone.
Segmentation Analysis
- By Type
Lignosulfonates lead the type segment, accounting for 38.0% of global market value in 2026, equivalent to USD 0.91 Billion. Their leadership reflects their strong binding performance and cost-effectiveness across a broad range of feed formulations. Molasses-Based Binders hold a significant secondary share, valued for their palatability benefits alongside binding function. Starch-Based Binders represent the fastest-growing type category through 2033, driven by growing demand for natural, clean-label binder alternatives.
- By Application
Aquafeed forms the leading application segment, representing 34.0% of global demand in 2026, or USD 0.82 Billion, reflecting the critical importance of pellet water stability in aquaculture feeding applications. Swine Feed and Cattle Feed represent significant, established application areas. Poultry Feed represents the fastest-growing application category, propelled by continued global transition toward pelleted poultry feed formats.
Regional Insights
- Asia Pacific
Asia Pacific holds the largest regional share, at 44.0% of the global market in 2026, equivalent to USD 1.06 Billion. The region's dominance reflects its position as the world's largest aquaculture and poultry feed production region, led by China, India, and Southeast Asian countries with substantial aquaculture industries.
- Europe
Europe accounts for 24.0% of the global market in 2026, valued at USD 0.58 Billion. Demand is supported by the region's established feed manufacturing industry and growing focus on natural binder formulations aligned with feed ingredient transparency trends.
- North America
North America represents 20.0% of the global market in 2026, or USD 0.48 Billion. Steady demand is supported by mature poultry and livestock feed manufacturing across the United States and Canada.
- Latin America
Latin America contributes 8.0% of the global market in 2026, equivalent to USD 0.19 Billion. Brazil anchors regional demand, supported by its large poultry and aquaculture production base.
- Middle East & Africa
Middle East & Africa holds 4.0% of the global market in 2026, valued at USD 0.10 Billion. Growth remains gradual, tied to limited regional aquaculture and feed manufacturing capacity relative to other regions.
Competitive Landscape
The global feed binders market is moderately fragmented, with a mix of large diversified ingredient companies offering broad binder portfolios and specialized manufacturers focused on specific binder chemistries such as lignosulfonates or starch-based products. Competition centers on binding performance consistency, formulation compatibility across diverse feed ingredient bases, and the ability to provide technical support for pelleting process optimization. Manufacturers are increasingly differentiating through natural and clean-label binder formulations rather than competing on commodity pricing alone.
Key Market Players
- Cargill, Incorporated
- Archer-Daniels-Midland Company
- Ingredion Incorporated
- Roquette Frères
- Kemin Industries, Inc.
- Borregaard ASA
- Novus International, Inc.
- Balchem Corporation
- CP Kelco (J.M. Huber Corporation)
- Tate & Lyle PLC
Market Segmentation
By Type
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
By Application
- Aquafeed
- Poultry Feed
- Swine Feed
- Cattle Feed
- Others
By Form
- Dry/Powder Form
- Liquid Form
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Feed Binders Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Feed Binders Market Outlook, 2020 - 2033
- Global Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- Global Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- Global Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- Global Feed Binders Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- North America Feed Binders Market Outlook, 2020 - 2033
- North America Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- North America Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- North America Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- North America Feed Binders Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Feed Binders Market Outlook, by Type, 2020-2033
- U.S. Feed Binders Market Outlook, by Application, 2020-2033
- U.S. Feed Binders Market Outlook, by Form, 2020-2033
- Canada Feed Binders Market Outlook, by Type, 2020-2033
- Canada Feed Binders Market Outlook, by Application, 2020-2033
- Canada Feed Binders Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Europe Feed Binders Market Outlook, 2020 - 2033
- Europe Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- Europe Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- Europe Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- Europe Feed Binders Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Feed Binders Market Outlook, by Type, 2020-2033
- Germany Feed Binders Market Outlook, by Application, 2020-2033
- Germany Feed Binders Market Outlook, by Form, 2020-2033
- Italy Feed Binders Market Outlook, by Type, 2020-2033
- Italy Feed Binders Market Outlook, by Application, 2020-2033
- Italy Feed Binders Market Outlook, by Form, 2020-2033
- France Feed Binders Market Outlook, by Type, 2020-2033
- France Feed Binders Market Outlook, by Application, 2020-2033
- France Feed Binders Market Outlook, by Form, 2020-2033
- U.K. Feed Binders Market Outlook, by Type, 2020-2033
- U.K. Feed Binders Market Outlook, by Application, 2020-2033
- U.K. Feed Binders Market Outlook, by Form, 2020-2033
- Spain Feed Binders Market Outlook, by Type, 2020-2033
- Spain Feed Binders Market Outlook, by Application, 2020-2033
- Spain Feed Binders Market Outlook, by Form, 2020-2033
- Russia Feed Binders Market Outlook, by Type, 2020-2033
- Russia Feed Binders Market Outlook, by Application, 2020-2033
- Russia Feed Binders Market Outlook, by Form, 2020-2033
- Rest of Europe Feed Binders Market Outlook, by Type, 2020-2033
- Rest of Europe Feed Binders Market Outlook, by Application, 2020-2033
- Rest of Europe Feed Binders Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Asia Pacific Feed Binders Market Outlook, 2020 - 2033
- Asia Pacific Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- Asia Pacific Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- Asia Pacific Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- Asia Pacific Feed Binders Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Feed Binders Market Outlook, by Type, 2020-2033
- China Feed Binders Market Outlook, by Application, 2020-2033
- China Feed Binders Market Outlook, by Form, 2020-2033
- Japan Feed Binders Market Outlook, by Type, 2020-2033
- Japan Feed Binders Market Outlook, by Application, 2020-2033
- Japan Feed Binders Market Outlook, by Form, 2020-2033
- South Korea Feed Binders Market Outlook, by Type, 2020-2033
- South Korea Feed Binders Market Outlook, by Application, 2020-2033
- South Korea Feed Binders Market Outlook, by Form, 2020-2033
- India Feed Binders Market Outlook, by Type, 2020-2033
- India Feed Binders Market Outlook, by Application, 2020-2033
- India Feed Binders Market Outlook, by Form, 2020-2033
- Southeast Asia Feed Binders Market Outlook, by Type, 2020-2033
- Southeast Asia Feed Binders Market Outlook, by Application, 2020-2033
- Southeast Asia Feed Binders Market Outlook, by Form, 2020-2033
- Rest of SAO Feed Binders Market Outlook, by Type, 2020-2033
- Rest of SAO Feed Binders Market Outlook, by Application, 2020-2033
- Rest of SAO Feed Binders Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Latin America Feed Binders Market Outlook, 2020 - 2033
- Latin America Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- Latin America Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- Latin America Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- Latin America Feed Binders Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Feed Binders Market Outlook, by Type, 2020-2033
- Brazil Feed Binders Market Outlook, by Application, 2020-2033
- Brazil Feed Binders Market Outlook, by Form, 2020-2033
- Mexico Feed Binders Market Outlook, by Type, 2020-2033
- Mexico Feed Binders Market Outlook, by Application, 2020-2033
- Mexico Feed Binders Market Outlook, by Form, 2020-2033
- Argentina Feed Binders Market Outlook, by Type, 2020-2033
- Argentina Feed Binders Market Outlook, by Application, 2020-2033
- Argentina Feed Binders Market Outlook, by Form, 2020-2033
- Rest of LATAM Feed Binders Market Outlook, by Type, 2020-2033
- Rest of LATAM Feed Binders Market Outlook, by Application, 2020-2033
- Rest of LATAM Feed Binders Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Feed Binders Market Outlook, 2020 - 2033
- Middle East & Africa Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
- Middle East & Africa Feed Binders Market Outlook, by Application, Value (US$ Mn), 2020-2033
- Aquafeed
- Aquafeed
- Swine Feed
- Cattle Feed
- Others
- Middle East & Africa Feed Binders Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Dry/Powder Form
- Liquid Form
- Middle East & Africa Feed Binders Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Feed Binders Market Outlook, by Type, 2020-2033
- GCC Feed Binders Market Outlook, by Application, 2020-2033
- GCC Feed Binders Market Outlook, by Form, 2020-2033
- South Africa Feed Binders Market Outlook, by Type, 2020-2033
- South Africa Feed Binders Market Outlook, by Application, 2020-2033
- South Africa Feed Binders Market Outlook, by Form, 2020-2033
- Egypt Feed Binders Market Outlook, by Type, 2020-2033
- Egypt Feed Binders Market Outlook, by Application, 2020-2033
- Egypt Feed Binders Market Outlook, by Form, 2020-2033
- Nigeria Feed Binders Market Outlook, by Type, 2020-2033
- Nigeria Feed Binders Market Outlook, by Application, 2020-2033
- Nigeria Feed Binders Market Outlook, by Form, 2020-2033
- Rest of Middle East Feed Binders Market Outlook, by Type, 2020-2033
- Rest of Middle East Feed Binders Market Outlook, by Application, 2020-2033
- Rest of Middle East Feed Binders Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Feed Binders Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Cargill, Incorporated
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Archer-Daniels-Midland Company
- Ingredion Incorporated
- Roquette Frères
- Kemin Industries, Inc.
- Borregaard ASA
- Novus International, Inc.
- Balchem Corporation
- CP Kelco (J.M. Huber Corporation)
- Tate & Lyle PLC
- Cargill, Incorporated
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Type
- Lignosulfonates
- Starch-Based Binders
- Molasses-Based Binders
- Others
By Application
- Aquafeed
- Poultry Feed
- Swine Feed
- Cattle Feed
- Others
By Form
- Dry/Powder Form
- Liquid Form
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global feed binders market is valued at USD 2.40 Billion in 2026, reflecting sustained demand for pellet quality across livestock and aquafeed manufacturing.
The market is projected to grow at a CAGR of 5.4%, reaching USD 3.47 Billion by 2033, driven by expanding aquaculture and poultry feed pelleting adoption.
Lignosulfonates lead with a 38.0% share in 2026, reflecting their strong binding performance and cost-effectiveness across feed formulations.
Asia Pacific leads with a 44.0% share in 2026, driven by its position as the world's largest aquaculture and poultry feed production region.
The largest opportunity lies in poultry feed applications, as pelleted feed adoption continues to expand into markets that have historically used mash feed.
Related Reports
Plant Based Meals Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The plant-based meals market is valued at US$19.4 billion in 2026 and is projected to reach US$29.2 billion by 2033, growing at 6.02% CAGR
Grain Alcohol Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global grain alcohol market is valued at US$13.2 billion in 2026 and is projected to reach US$20.1 billion by 2033, growing at 6.2% CAGR
Nixtamalized Corn Flour Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The nixtamalized corn flour market is projected to grow from US$6.2 billion in 2026 to US$9.1 billion by 2033, at a 5.63% CAGR
Fruit-flavour Drink Compounds Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The fruit-flavour drink compounds market is projected to grow from US$7.4 billion in 2026 to US$11.9 billion by 2033, at a 7.0% CAGR
Protein Fat-Mimic Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The protein fat-mimic systems market, valued at US$ 2.2 billion in 2026 and projected to reach US$ 4.48 billion by 2033, growing at a 10.7% CAGR
Additive-Free Dairy Powders Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The additive-Free Dairy Powders Market is valued at US$ 1.50 billion in 2026 and projected to reach US$ 2.83 billion by 2033, growing at a 9.5% CAGR