


General Aviation Market
General Aviation Market Insights, Competitive Landscape, and Market Forecast - 2033
Market Overview
General aviation encompasses all civil aircraft operations outside scheduled commercial airline and military service, spanning personal and recreational flying, business and corporate transportation, flight training, and other specialized applications. The category includes a broad range of aircraft types from single-engine piston aircraft through turboprops, business jets, and rotorcraft, serving individual pilots, corporate flight departments, flight schools, and specialized commercial operators across a diverse set of use cases.
Demand growth through the 2026-2033 window is closely tied to sustained corporate and business travel demand favoring the flexibility and time efficiency of private aviation over scheduled commercial service, a well-documented global pilot shortage driving substantial investment in flight training aircraft and infrastructure, and continued high-net-worth individual and corporate interest in business jet ownership and fractional ownership programs. Manufacturers introducing more fuel-efficient and technologically advanced aircraft models continue to support fleet renewal and expansion across owner and operator segments.
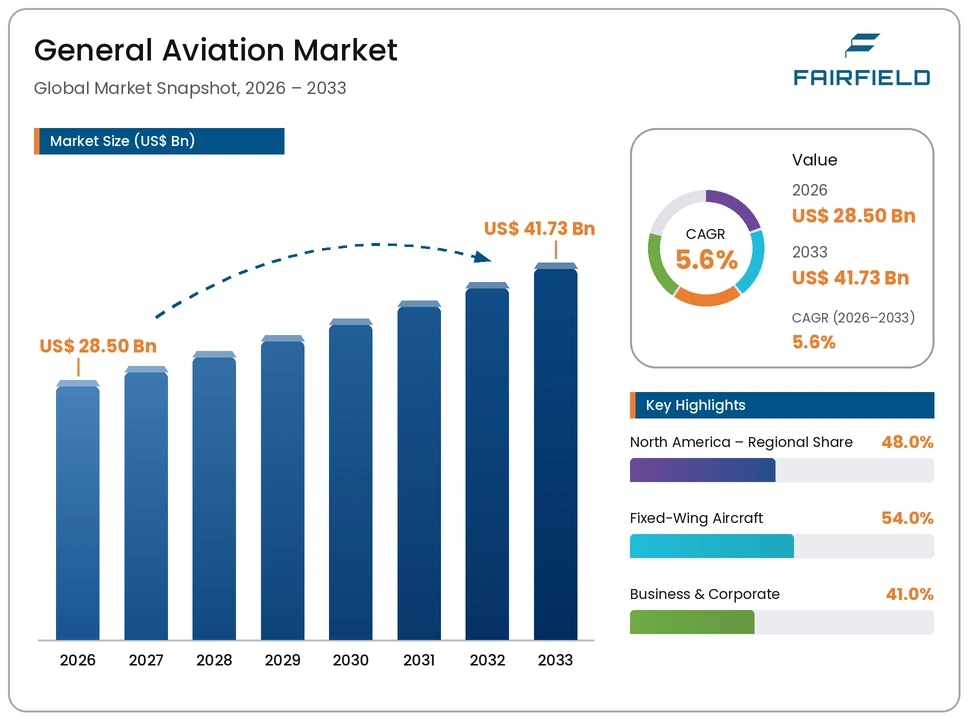
The market is valued at USD 28.50 Billion in 2026, with manufacturers directing investment toward advanced avionics integration and improved fuel efficiency across both piston and turbine-powered aircraft categories. By 2033, the market is forecast to reach USD 41.73 Billion, reflecting steady growth across established business and corporate applications alongside rapidly expanding flight training aircraft demand.
Key Highlights
- The global general aviation market is valued at USD 28.50 Billion in 2026 and is projected to reach USD 41.73 Billion by 2033, expanding at a CAGR of 5.6% across the 2026-2033 forecast period.
- Fixed-Wing Aircraft lead the aircraft-type segment with a 54.0% share in 2026, equivalent to USD 15.39 Billion.
- Business & Corporate remains the dominant application, accounting for 41.0% of global demand, or USD 11.69 Billion, in 2026.
- North America commands the largest regional share at 48.0% of the global market in 2026.
- Flight training applications are emerging as the fastest-growing application through 2033.
Key Growth Drivers
Growth in the general aviation market is driven primarily by sustained corporate and business travel demand, as companies and high-net-worth individuals continue to value the scheduling flexibility, time savings, and access to smaller airports that business aviation provides relative to scheduled commercial air travel.
A second driver is the well-documented global pilot shortage, which is driving substantial investment in flight training aircraft and infrastructure by flight schools and airlines seeking to expand pilot training capacity to meet long-term workforce requirements across both general aviation and commercial aviation career paths.
Key Restraints
The substantial capital investment required for aircraft ownership, including purchase price, maintenance, insurance, and hangar costs, creates a significant barrier to entry for individual and smaller corporate buyers, limiting general aviation aircraft ownership to a relatively narrow segment of the population and business community.
Additionally, regulatory certification requirements for new aircraft designs and modifications involve lengthy approval timelines and substantial compliance costs, creating a barrier to rapid introduction of new aircraft models and technologies relative to less regulated transportation categories.
Market Opportunities
The expansion of flight training aircraft demand presents a substantial opportunity, as flight schools and airline-affiliated training programs continue to invest in fleet expansion to address the pilot shortage, creating sustained demand for reliable, cost-effective training aircraft across both piston and turboprop categories.
A second opportunity lies in the continued development of more fuel-efficient and technologically advanced aircraft, including improved avionics and engine technology that reduces operating costs for owners and operators. Manufacturers that successfully advance these efficiency and technology improvements stand to capture fleet renewal demand as older aircraft are retired.
Segmentation Analysis
- By Aircraft Type
Fixed-Wing Aircraft lead the aircraft-type segment, accounting for 54.0% of global market value in 2026, equivalent to USD 15.39 Billion. Their leadership reflects the broad range of piston, turboprop, and business jet fixed-wing aircraft serving the majority of general aviation applications. Rotorcraft/Helicopters represent a significant, established aircraft-type category. Business Jets represent the fastest-growing aircraft-type category through 2033, driven by sustained corporate travel demand and fractional ownership program expansion.
- By Application
Business & Corporate forms the leading application segment, representing 41.0% of global demand in 2026, or USD 11.69 Billion, reflecting sustained corporate reliance on private aviation for time-efficient business travel. Personal/Recreational flying represents a significant, established application area. Flight Training represents the fastest-growing application category, propelled by the global pilot shortage driving fleet expansion among flight schools and airline training programs.
Regional Insights
- North America
North America holds the largest regional share, at 48.0% of the global market in 2026, equivalent to USD 13.68 Billion. The region's leadership reflects its position as the world's largest general aviation market, supported by extensive private airport infrastructure, established business aviation culture, and substantial flight training capacity across the United States and Canada.
- Europe
Europe accounts for 24.0% of the global market in 2026, valued at USD 6.84 Billion. Demand is supported by well-established business aviation activity and growing flight training investment addressing regional pilot shortages.
- Asia Pacific
Asia Pacific represents 18.0% of the global market in 2026, or USD 5.13 Billion. Growth is underpinned by rising corporate wealth and expanding flight training infrastructure investment across China, India, and Southeast Asia.
- Latin America
Latin America contributes 6.0% of the global market in 2026, equivalent to USD 1.71 Billion. Growth is linked to expanding business aviation activity and agricultural aviation applications in Brazil and Mexico.
- Middle East & Africa
Middle East & Africa holds 4.0% of the global market in 2026, valued at USD 1.14 Billion. Growth remains at an early stage, tied to gradual expansion of private aviation infrastructure across the region.
Competitive Landscape
The global general aviation market is moderately concentrated, with a limited number of established aircraft manufacturers holding strong positions supported by extensive product portfolios spanning piston, turboprop, and business jet categories, alongside long-standing dealer and service networks. Competition centers on aircraft performance and fuel efficiency, avionics technology sophistication, and the strength of after-sales support and maintenance networks. Manufacturers are increasingly differentiating through advanced avionics integration and expanded flight training aircraft offerings rather than competing on airframe pricing alone.
Key Market Players
- Textron Aviation Inc.
- Embraer S.A.
- Cirrus Aircraft
- Daher
- Piper Aircraft, Inc.
- Diamond Aircraft Industries
- Gulfstream Aerospace Corporation
- Bombardier Inc.
- Honda Aircraft Company
- Pilatus Aircraft Ltd.
Market Segmentation
By Aircraft Type
- Fixed-Wing Aircraft
- Rotorcraft/Helicopters
- Business Jets
By Application
- Personal/Recreational
- Business & Corporate
- Flight Training
- Others
By Engine Type
- Piston Engine
- Turboprop Engine
- Turbofan/Turbojet Engine
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Beef Cattle Feed Market Snapshot
- Future Projections
- Key Market Trends
- Regional Snapshot, by Value, 2026
- Analyst Recommendations
- Market Overview
- Market Definitions and Segmentations
- Market Dynamics
- Drivers
- Restraints
- Market Opportunities
- Value Chain Analysis
- COVID-19 Impact Analysis
- Porter's Five Forces Analysis
- Impact of Russia-Ukraine Conflict
- PESTLE Analysis
- Regulatory Analysis
- Price Trend Analysis
- Current Prices and Future Projections, 2025-2033
- Price Impact Factors
- Global Beef Cattle Feed Market Outlook, 2020 - 2033
- Global Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Global Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Global Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Global Beef Cattle Feed Market Outlook, by Region, Value (US$ Mn), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- North America Beef Cattle Feed Market Outlook, 2020 - 2033
- North America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- North America Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- North America Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- North America Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Type, 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- U.S. Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Canada Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- North America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Europe Beef Cattle Feed Market Outlook, 2020 - 2033
- Europe Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Europe Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Europe Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Europe Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Germany Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Italy Beef Cattle Feed Market Outlook, by Form, 2020-2033
- France Beef Cattle Feed Market Outlook, by Type, 2020-2033
- France Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- France Beef Cattle Feed Market Outlook, by Form, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Type, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- U.K. Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Spain Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Russia Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of Europe Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Europe Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Asia Pacific Beef Cattle Feed Market Outlook, 2020 - 2033
- Asia Pacific Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Asia Pacific Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Asia Pacific Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Asia Pacific Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- China Beef Cattle Feed Market Outlook, by Type, 2020-2033
- China Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- China Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Japan Beef Cattle Feed Market Outlook, by Form, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Type, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- South Korea Beef Cattle Feed Market Outlook, by Form, 2020-2033
- India Beef Cattle Feed Market Outlook, by Type, 2020-2033
- India Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- India Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Southeast Asia Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of SAO Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Asia Pacific Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Latin America Beef Cattle Feed Market Outlook, 2020 - 2033
- Latin America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Latin America Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Latin America Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Latin America Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Brazil Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Mexico Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Argentina Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of LATAM Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Latin America Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Middle East & Africa Beef Cattle Feed Market Outlook, 2020 - 2033
- Middle East & Africa Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Complete Feed
- Concentrates
- Feed Additives & Supplements
- Others
- Middle East & Africa Beef Cattle Feed Market Outlook, by Production System, Value (US$ Mn), 2020-2033
- Feedlot/Finishing Operations
- Cow-Calf & Pasture-Based Operations
- Others
- Middle East & Africa Beef Cattle Feed Market Outlook, by Form, Value (US$ Mn), 2020-2033
- Pellets
- Mash
- Blocks & Liquid Supplements
- Middle East & Africa Beef Cattle Feed Market Outlook, by Country, Value (US$ Mn), 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Type, 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- GCC Beef Cattle Feed Market Outlook, by Form, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Type, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- South Africa Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Egypt Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Nigeria Beef Cattle Feed Market Outlook, by Form, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Type, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Production System, 2020-2033
- Rest of Middle East Beef Cattle Feed Market Outlook, by Form, 2020-2033
- BPS Analysis/Market Attractiveness Analysis
- Middle East & Africa Beef Cattle Feed Market Outlook, by Type, Value (US$ Mn), 2020-2033
- Competitive Landscape
- Company Vs Segment Heatmap
- Company Market Share Analysis, 2025
- Competitive Dashboard
- Company Profiles
- Cargill, Incorporated
- Company Overview
- Product Portfolio
- Financial Overview
- Business Strategies and Developments
- Archer-Daniels-Midland Company
- Land O'Lakes, Inc.
- Charoen Pokphand Foods PCL
- Alltech, Inc.
- De Heus Animal Nutrition
- ForFarmers N.V.
- Nutreco N.V.
- Kent Nutrition Group
- J.D. Heiskell & Co.
- Cargill, Incorporated
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
By Aircraft Type
- Fixed-Wing Aircraft
- Rotorcraft/Helicopters
- Business Jets
By Application
- Personal/Recreational
- Business & Corporate
- Flight Training
- Others
By Engine Type
- Piston Engine
- Turboprop Engine
- Turbofan/Turbojet Engine
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global general aviation market is valued at USD 28.50 Billion in 2026, reflecting sustained demand across business, personal, and flight training applications.
The market is projected to grow at a CAGR of 5.6%, reaching USD 41.73 Billion by 2033, driven by business travel demand and pilot training expansion.
Fixed-Wing Aircraft lead with a 54.0% share in 2026, reflecting their broad range of applications across piston, turboprop, and business jet categories.
North America leads with a 48.0% share in 2026, supported by extensive private airport infrastructure and established business aviation culture.
The largest opportunity lies in flight training applications, expanding rapidly as the global pilot shortage drives fleet investment among training providers.
Related Reports
Automotive Alternator and Starter Motor Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive alternator and starter motor market is valued at US$32.0 billion in 2026, reaching US$38.0 billion by 2033, at a 2.5% CAGR
Automotive Start-Stop Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Hybrid Electric Vehicle (EV) Conversion Kit Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global hybrid EV conversion kit market will reach US$ 1.42 Bn by 2033, growing at 11.09% CAGR from 2026-2033, driven by cost-effective electrification
Passenger Vehicles HVAC Services Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The passenger vehicles HVAC services market, valued at US$ 48.6 billion in 2026, and projected to reach US$ 73.4 billion by 2033, growing at 6.1% CAGR
Automotive 48-Volt Electronic Junction Box and Power Distribution Center Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive 48-volt junction box and power distribution center market will reach US$ 4.55 Bn by 2033, growing at 11.68% CAGR from 2026-2033
Ultra-Fast EV Charging (350kW+) Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global Ultra-Fast EV charging systems market will grow from US$ 7.1 billion in 2026 to US$ 34.5 billion by 2033, at a 25.3% CAGR. Discover key trends