


Tunnel Construction Market
Tunnel Construction Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Tunnel Construction Market Size and Trend Analysis
How Fast Is the Tunnel Construction Market Growing?
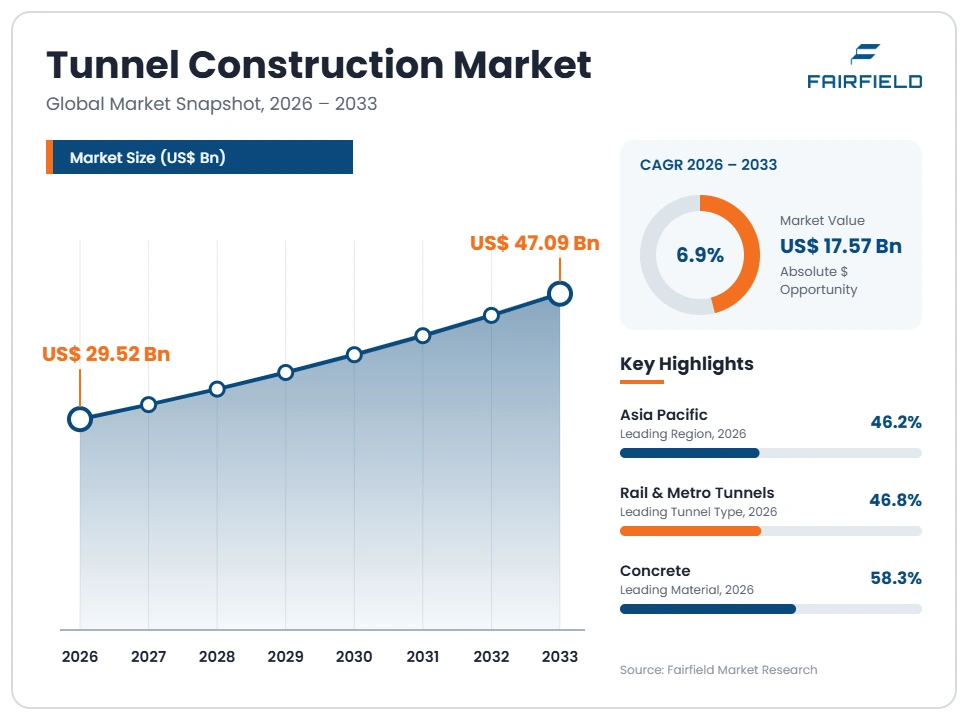
The global tunnel construction market size is expected to be valued at US$ 29.52 billion in 2026 and projected to reach US$ 47.09 billion by 2033, growing at a CAGR of 6.9% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 5.6%, recovering from pandemic-era site shutdowns as many delayed metro and rail packages restarted in sequence. Three main factors now support growth: rapid metro rail construction in Asian cities, long base tunnels for high-speed and cross-border rail in Europe, and rising investment in sewer, water, and power cable tunnels. The market is moving toward mechanized excavation with tunnel boring machines, precast lining segments, and digital monitoring that reduces geological and schedule risk on large underground infrastructure projects.
Key Report Takeaways
- By Tunnel Type: Rail & Metro Tunnels held 46.8% share in 2026, while Utility & Water Tunnels are projected to expand at a 7.9% CAGR through 2033, driven by sewer overflow programs and urban power cable routes.
- By Construction Method: TBM Method held 41.6% share in 2026, while Immersed Tube is projected to expand at an 8.2% CAGR through 2033, driven by sea crossings such as the Fehmarnbelt link.
- By Material: Concrete held 58.3% share in 2026, while Composite Materials are projected to expand at a 9.0% CAGR through 2033, driven by fiber-reinforced lining segments that cut steel use and corrosion.
- By Application: Government Construction held 71.4% share in 2026, while Commercial Construction is projected to expand at a 7.6% CAGR through 2033, driven by private mining, hydropower, and public-private partnership road tunnels.
- By Region: Asia Pacific held 46.2% share in 2026, while India is projected to expand at a 9.4% CAGR through 2033, driven by metro rail programs in more than 20 cities and Himalayan highway tunnels.
Global Tunnel Construction Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on tunnel construction demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Urban metro rail expansion | High | Asia Pacific, Middle East & Africa | Long term (≥4 years) |
| High-speed and cross-border rail base tunnels | Medium | Europe, Asia Pacific | Long term (≥4 years) |
Metro Rail Expansion in Asian Cities Is Driving Tunnel Construction Volumes
Metro rail expansion is the largest single source of new tunnel construction demand. Dense cities cannot widen roads or run elevated lines through historic centers, so transit agencies place stations and running tunnels underground. Each new line needs bored tunnels, stations, and shafts, creating multi-year contractor work.
The mechanism is urban population growth combined with government transit funding. India has approved metro systems in more than 20 cities, and new underground sections continue to start. In January 2025, a tunnel boring machine was commissioned for the Transport Nagar station package of the Kanpur Metro. China keeps adding urban rail lines in second-tier cities, while Saudi Arabia and the United Arab Emirates fund new metro networks. These programs give contractors a steady pipeline of tunnel boring machine drives and station excavation packages.
High-Speed and Cross-Border Rail Is Creating Long Base Tunnels in the Tunnel Construction Market
Long-distance rail projects are lifting demand for very long, high-value tunnel contracts. High-speed lines need gentle gradients and wide curves, so they pass through mountains and hills rather than around them. These base tunnels often run for tens of kilometers.
The evidence is visible across Europe and Asia Pacific. The Lyon–Turin rail link includes a 57.5 km base tunnel between France and Italy, with a €1.43 billion French section awarded to Vinci Construction and Webuild. In the United Kingdom, the Align joint venture completed the HS2 Chiltern Tunnel in August 2025, the longest tunnel on the route at about 16 km. China reached about 47,000 km of operating high-speed railway by the end of 2024, and many new lines in its mountainous west are tunnel-heavy.
Restraints Impact Analysis
Two restraints limit how quickly tunnel construction projects move from approval to completion.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Geological risk and safety incidents | Medium | Global, strongest in Asia Pacific | Medium term (2–4 years) |
| Cost overruns and funding delays | Medium | North America, Europe | Long term (≥4 years) |
Unpredictable Ground Conditions Raise Safety Risk in Tunnel Construction
Unpredictable geology slows tunnel construction and raises safety risk. Fault zones, water inflows, and weak rock can stop a boring machine or trigger collapses, which delays schedules and forces costly redesign. Contractors must then add ground improvement, extra support, and additional site investigation.
The underlying cause is limited knowledge of deep ground before excavation begins. In November 2023, part of the Silkyara Bend–Barkot highway tunnel in Uttarakhand collapsed and trapped 41 workers for about 16 days. The National Highways Authority of India then announced a safety audit of 29 tunnels under construction. Such events increase costs for probe drilling, geophysical surveys, emergency escape pipes, and real-time monitoring. They also make insurers and project lenders more cautious, which raises premiums and slows approvals for projects in fragile mountain terrain.
Cost Overruns and Long Approval Cycles Delay Tunnel Construction Projects
Cost overruns and long approval cycles are restraining project starts in mature markets. When estimates rise sharply, governments pause, rescope, or cancel tunnels, leaving contractors with idle equipment and teams. Political reviews can add years before excavation begins.
The specific cost sources are land acquisition, utility diversion, environmental mitigation, and inflation in steel, cement, and skilled labor. The BART Silicon Valley Phase II extension in San Jose is estimated at more than US$ 12 billion for about 6 miles of new line, including 5 miles underground. Its custom Herrenknecht boring machine alone cost about US$ 76 million. In the United Kingdom, repeated cost revisions on HS2 led to reduced scope. These pressures push agencies toward design-and-build contracts that shift more risk to contractors, which squeezes margins.
Market Opportunities
Sewer, Water, and Power Cable Tunnels Open a New Revenue Pool in Tunnel Construction
Utility tunnels for sewage, stormwater, drinking water, and high-voltage cables form a fast-emerging revenue pool. Ageing combined sewer systems overflow during heavy rain, and cities now prefer deep storage tunnels to surface works. Grid operators also need underground routes to bring renewable power into city centers without new overhead lines.
Specialist contractors and smaller-diameter boring machine makers are well placed to capture this demand. Water utilities, environmental regulators, and transmission companies are the main customers. London's Thames Tideway Tunnel, a 25 km super sewer under the River Thames, shows the scale of these programs. Similar storage and conveyance tunnels are planned in North America and Europe to meet stricter river-quality rules. Cable tunnel work is also rising as offshore wind connections reach coastal cities, creating repeat work for microtunneling and pipe-jacking specialists.
Digital Tunneling and Automation Create a Services Opportunity in Tunnel Construction
Digital services for tunnel construction represent a new, higher-margin revenue pool. Tunnel owners increasingly want real-time data on ground movement, machine performance, and segment quality to cut risk and prove progress. This creates steady demand for digital twins, ground sensors, predictive analytics, and automated machine guidance.
Technology-focused contractors, boring machine makers, and engineering software firms can capture this opportunity. Acciona launched DigiTunnel, which combines digital twins, automated machinery control, and predictive analytics for tunneling. Equipment makers such as Herrenknecht offer remote monitoring of boring machines, while engineering groups such as Systra have expanded tunneling expertise through acquisitions. Public owners in Europe and Asia Pacific increasingly require building information modeling and digital handover, which makes these services part of the contract scope rather than an optional extra.
Segment Analysis
- By Tunnel Type: Rail & Metro Tunnels Lead While Utility & Water Tunnels Gain Ground
Rail & Metro Tunnels held 46.8% share in 2026. Metro rail construction in China, India, and the Gulf states, together with high-speed rail base tunnels in Europe, generates the largest and most valuable contracts with long delivery periods.
Utility & Water Tunnels are the fastest-growing tunnel type, expanding at a 7.9% CAGR through 2033. Cities need deep sewer storage to meet river-quality rules, and grid operators need underground cable routes for renewable power. These projects use smaller-diameter boring machines and microtunneling, which opens the market to mid-sized specialists and regional equipment rental firms. For the broader market, utility work smooths demand because it depends on regulated utility budgets rather than transport funding cycles.
- By Construction Method: TBM Method Dominates as Immersed Tube Builds Momentum
TBM Method held 41.6% share in 2026. A tunnel boring machine excavates and installs lining segments in one cycle, which improves safety and reduces surface disruption in cities. Metro and long rail tunnels increasingly specify boring machines, and suppliers such as Herrenknecht and China Railway Engineering Equipment Group build machines tailored to local geology.
Immersed Tube is the fastest-growing method, expanding at an 8.2% CAGR through 2033. Precast tunnel elements are floated into position and sunk into a dredged trench, which suits sea and river crossings. The Fehmarnbelt link between Denmark and Germany, at about 18 km, is among the largest projects of this type. The business implication is that marine construction skills, casting yards, and dredging capacity are becoming strategic assets for large contractors.
- By Material: Concrete Leads While Composite Materials Accelerate
Concrete held 58.3% share in 2026. Precast concrete lining segments, shotcrete, and cast-in-place linings are used in almost every tunnel. Concrete is durable, fire-resistant, and widely available, which makes it the default material for tunnel lining segments and station boxes.
Composite Materials are the fastest-growing material, expanding at a 9.0% CAGR through 2033. Fiber-reinforced concrete and glass-fiber reinforcement bars reduce or remove conventional steel in lining segments. This lowers corrosion risk in wet ground and cuts embodied carbon, which matters as public owners in Europe add carbon limits to tenders. For the market, composite adoption supports lower lifetime maintenance and gives suppliers of specialty fibers and admixtures a growing role in rock excavation and lining work.
- By Application: Government Construction Dominates While Commercial Construction Expands
Government Construction held 71.4% share in 2026. Transport ministries, metro corporations, and water authorities fund most tunnels because these assets serve public needs and take decades to pay back.
Commercial Construction is the fastest-growing application, expanding at a 7.6% CAGR through 2033. Mining companies need access tunnels and declines to reach deeper ore bodies as shallow reserves deplete, and pumped-storage hydropower developers need headrace and tailrace tunnels. Public-private partnerships for toll road tunnels also bring private finance into the market. These clients value speed and fixed-price delivery, which suits contractors with strong project controls and proven experience in hard rock. For the industry, rising private demand diversifies revenue and reduces dependence on government budget cycles.
Geography Analysis
- North America Rebuilds Transit and Water Networks in Tunnel Construction
North America is a mature region where demand comes from transit extensions and water infrastructure. The United States leads, with projects such as the BART Silicon Valley Phase II extension in San Jose, which will use one of the world's largest single-bore transit boring machines. Federal infrastructure funding supports transit and water projects, while combined sewer overflow programs keep utility tunnel demand active. Canada adds demand through subway expansions in Toronto and transit tunnels in Vancouver. High labor costs and long environmental reviews hold back growth. One opportunity is the gradual shift toward progressive design-build contracts, which allows earlier contractor input and better risk sharing on complex underground infrastructure.
- Europe Builds Base Tunnels for High-Speed Rail in Tunnel Construction
Europe is a major market led by long rail tunnels and urban metro work. France hosts the Lyon–Turin base tunnel and the Grand Paris Express metro, one of the largest urban rail programs in the region. The United Kingdom completed the HS2 Chiltern Tunnel in 2025, while Germany and Denmark are building the Fehmarnbelt immersed tunnel. Italy and Austria continue work on the Brenner Base Tunnel. Strict safety and environmental rules raise costs but also push adoption of advanced methods. One change shaping the region is the inclusion of carbon limits in tenders, which favors low-carbon concrete and composite lining segments.
- Which Region Is Leading the Tunnel Construction Market?
Asia Pacific is leading the tunnel construction market with a 46.2% share in 2026. China is the largest country market, supported by about 47,000 km of operating high-speed railway and continuous urban metro construction. State-owned contractors such as China Railway Construction Corporation and China Railway Group combine design, construction, and equipment manufacturing, which lowers cost. Japan builds tunnels for the Chuo Shinkansen maglev line, while Australia has major metro and road tunnel programs in Sydney and Melbourne. Mountainous terrain across the region means rail and road links often need tunnels. One opportunity is the export of Chinese boring machines and contracting services along overseas rail corridors.
- Which Country Is Growing Fastest in the Tunnel Construction Market?
India is growing fastest in the tunnel construction market at a 9.4% CAGR through 2033. Metro rail systems are approved in more than 20 cities, and many include underground sections in crowded centers. The Mumbai–Ahmedabad high-speed rail corridor includes an undersea tunnel near Mumbai, and Herrenknecht was selected to supply its boring machines. Himalayan highway projects in Jammu and Kashmir and Uttarakhand add long road tunnels. The Silkyara collapse in 2023 prompted safety audits, which are raising standards for monitoring and escape routes. One opportunity is local manufacturing of boring machines and lining segments, supported by the government's domestic manufacturing push.
- Latin America Advances Metro Projects in Tunnel Construction
Latin America is an emerging region where metro construction drives demand. Brazil, Chile, Colombia, and Peru are extending urban rail networks, including the Lima Metro Line 2 and new lines in Santiago and Bogotá. Mining tunnels in Chile and Peru add commercial demand. Key barriers include fiscal constraints, currency volatility that raises the cost of imported boring machines, and frequent contract renegotiation. Political changes can also delay contract awards by several years. One opportunity is multilateral development bank financing, which supports large transit projects and encourages international contractors to partner with local firms on underground infrastructure.
- Middle East & Africa Invests in Metro and Water Tunnels in Tunnel Construction
Middle East & Africa is a growing region led by Gulf infrastructure spending. Saudi Arabia is building tunnels for the Riyadh Metro and giga-projects, while the United Arab Emirates and Qatar invest in metro extensions and deep sewer tunnels. In Africa, demand comes from hydropower, mining, and water transfer tunnels, including the Lesotho Highlands Water Project. Key barriers include limited local tunneling skills, reliance on foreign contractors, and funding gaps in many African markets. One opportunity is long-term deep tunnel sewerage programs in Gulf cities, which create multi-year work for boring machine operators and lining suppliers.
Competitive Landscape
The tunnel construction market is moderately concentrated. A small group of large contractors wins most mega-projects, including China Railway Construction Corporation, China Railway Group, Vinci Construction, Bouygues Construction, Webuild, and Strabag. Below them, many regional and specialist firms compete for smaller metro, utility, and mining tunnels. Joint ventures are common because single projects can exceed several billion dollars and spread risk across partners.
Contractors compete on technical capability, track record with similar geology, balance sheet strength, and risk management. Access to boring machines, precast segment factories, and experienced crews is a key differentiator. Newer approaches include digital twins, automated segment erection, and remote machine monitoring, which help firms bid more competitively on schedule and safety.
Strategic moves show how competition is evolving. Vinci Construction and Webuild formed a consortium to win the €1.43 billion French section of the Lyon–Turin base tunnel. The Align joint venture of Sir Robert McAlpine, Bouygues Travaux Publics, and VolkerFitzpatrick completed the HS2 Chiltern Tunnel 12 days ahead of the contractual date, strengthening its credentials. Acciona introduced DigiTunnel to differentiate through digital delivery, while Systra acquired Bamser to deepen tunneling engineering capacity in Australia.
Three themes shape vendor strategy. First, contractors are forming joint ventures to share geological and financial risk. Second, they are investing in digital tools and automation to improve safety and productivity. Third, they are seeking more balanced contract models, such as alliance and progressive design-build contracts, that share unforeseen ground risk with owners.
Recent Industry Developments
- August 2025: Align joint venture completed the HS2 Chiltern Tunnel ahead of schedule – strengthens its partners' credentials for long rail tunnel bids.
- January 2025: Uttar Pradesh Metro Rail Corporation commissioned a boring machine for the Kanpur Metro Transport Nagar package – reflects India's expanding underground metro pipeline.
- March 2024: Align achieved the final boring machine breakthrough on the HS2 Chiltern Tunnel – showed long-drive mechanized tunneling capability in the United Kingdom.
Companies Covered in the Report
- China Railway Construction Corporation
- China Railway Group
- Vinci Construction
- Webuild
- Bouygues Construction
- Strabag
- Skanska
- Larsen & Toubro
- Bechtel
- Acciona
- Shanghai Construction Group
- Herrenknecht
Tunnel Construction Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 29.52 Billion |
| Market Size 2033 | US$ 47.09 Billion |
| CAGR 2026–2033 | 6.9% |
| Absolute Dollar Opportunity | US$ 17.57 Billion |
| Largest Market | Asia Pacific |
| Fastest-Growing Market | India |
| Market Concentration | Medium |
| Major Players | China Railway Construction Corporation, China Railway Group, Vinci Construction, Webuild, Bouygues Construction |
Tunnel Construction Market Segmentation
Tunnel Type
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
Construction Method
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
Material
- Concrete
- Steel
- Composite Materials
Application
- Government Construction
- Commercial Construction
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Tunnel Construction Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Metro Rail Expansion in Asian Cities Is Driving Tunnel Construction Volumes
- High-Speed and Cross-Border Rail Is Creating Long Base Tunnels in the Tunnel Construction Market
- Restraints
- Unpredictable Ground Conditions Raise Safety Risk in Tunnel Construction
- Cost Overruns and Long Approval Cycles Delay Tunnel Construction Projects
- Market Opportunities
- Sewer, Water, and Power Cable Tunnels Open a New Revenue Pool in Tunnel Construction
- Digital Tunneling and Automation Create a Services Opportunity in Tunnel Construction
- Drivers
- Global Tunnel Construction Market Outlook, 2020–2033
- Global Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- Global Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- Global Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- Global Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- Global Tunnel Construction Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- North America Tunnel Construction Market Outlook, 2020–2033
- North America Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- North America Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- North America Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- North America Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- North America Tunnel Construction Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- United States Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- United States Tunnel Construction Market Outlook, by Material, 2020–2033
- United States Tunnel Construction Market Outlook, by Application, 2020–2033
- Canada Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Canada Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Canada Tunnel Construction Market Outlook, by Material, 2020–2033
- Canada Tunnel Construction Market Outlook, by Application, 2020–2033
- North America Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Europe Tunnel Construction Market Outlook, 2020–2033
- Europe Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- Europe Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- Europe Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- Europe Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- Europe Tunnel Construction Market Outlook, by Country, Value (US$ Billion), 2020–2033
- France Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- France Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- France Tunnel Construction Market Outlook, by Material, 2020–2033
- France Tunnel Construction Market Outlook, by Application, 2020–2033
- United Kingdom Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- United Kingdom Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- United Kingdom Tunnel Construction Market Outlook, by Material, 2020–2033
- United Kingdom Tunnel Construction Market Outlook, by Application, 2020–2033
- Germany Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Germany Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Germany Tunnel Construction Market Outlook, by Material, 2020–2033
- Germany Tunnel Construction Market Outlook, by Application, 2020–2033
- Denmark Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Denmark Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Denmark Tunnel Construction Market Outlook, by Material, 2020–2033
- Denmark Tunnel Construction Market Outlook, by Application, 2020–2033
- Italy Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Italy Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Italy Tunnel Construction Market Outlook, by Material, 2020–2033
- Italy Tunnel Construction Market Outlook, by Application, 2020–2033
- Austria Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Austria Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Austria Tunnel Construction Market Outlook, by Material, 2020–2033
- Austria Tunnel Construction Market Outlook, by Application, 2020–2033
- Europe Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Asia Pacific Tunnel Construction Market Outlook, 2020–2033
- Asia Pacific Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- Asia Pacific Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- Asia Pacific Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- Asia Pacific Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- Asia Pacific Tunnel Construction Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- China Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- China Tunnel Construction Market Outlook, by Material, 2020–2033
- China Tunnel Construction Market Outlook, by Application, 2020–2033
- Japan Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Japan Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Japan Tunnel Construction Market Outlook, by Material, 2020–2033
- Japan Tunnel Construction Market Outlook, by Application, 2020–2033
- Australia Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Australia Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Australia Tunnel Construction Market Outlook, by Material, 2020–2033
- Australia Tunnel Construction Market Outlook, by Application, 2020–2033
- India Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- India Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- India Tunnel Construction Market Outlook, by Material, 2020–2033
- India Tunnel Construction Market Outlook, by Application, 2020–2033
- Asia Pacific Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Latin America Tunnel Construction Market Outlook, 2020–2033
- Latin America Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- Latin America Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- Latin America Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- Latin America Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- Latin America Tunnel Construction Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Brazil Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Brazil Tunnel Construction Market Outlook, by Material, 2020–2033
- Brazil Tunnel Construction Market Outlook, by Application, 2020–2033
- Chile Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Chile Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Chile Tunnel Construction Market Outlook, by Material, 2020–2033
- Chile Tunnel Construction Market Outlook, by Application, 2020–2033
- Colombia Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Colombia Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Colombia Tunnel Construction Market Outlook, by Material, 2020–2033
- Colombia Tunnel Construction Market Outlook, by Application, 2020–2033
- Peru Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Peru Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Peru Tunnel Construction Market Outlook, by Material, 2020–2033
- Peru Tunnel Construction Market Outlook, by Application, 2020–2033
- Latin America Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Tunnel Construction Market Outlook, 2020–2033
- Middle East & Africa Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
- Middle East & Africa Tunnel Construction Market Outlook, by Construction Method, Value (US$ Billion), 2020–2033
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
- Middle East & Africa Tunnel Construction Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Concrete
- Steel
- Composite Materials
- Middle East & Africa Tunnel Construction Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Government Construction
- Commercial Construction
- Middle East & Africa Tunnel Construction Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Saudi Arabia Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Saudi Arabia Tunnel Construction Market Outlook, by Material, 2020–2033
- Saudi Arabia Tunnel Construction Market Outlook, by Application, 2020–2033
- United Arab Emirates Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- United Arab Emirates Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- United Arab Emirates Tunnel Construction Market Outlook, by Material, 2020–2033
- United Arab Emirates Tunnel Construction Market Outlook, by Application, 2020–2033
- Qatar Tunnel Construction Market Outlook, by Tunnel Type, 2020–2033
- Qatar Tunnel Construction Market Outlook, by Construction Method, 2020–2033
- Qatar Tunnel Construction Market Outlook, by Material, 2020–2033
- Qatar Tunnel Construction Market Outlook, by Application, 2020–2033
- Middle East & Africa Tunnel Construction Market Outlook, by Tunnel Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- China Railway Construction Corporation
- China Railway Group
- Vinci Construction
- Webuild
- Bouygues Construction
- Strabag
- Skanska
- Larsen & Toubro
- Bechtel
- Acciona
- Shanghai Construction Group
- Herrenknecht
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Tunnel Type
- Rail & Metro Tunnels
- Road & Highway Tunnels
- Utility & Water Tunnels
- Hydropower & Mining Tunnels
Construction Method
- TBM Method
- Drill & Blast
- Cut & Cover
- NATM / Sequential Excavation
- Immersed Tube
Material
- Concrete
- Steel
- Composite Materials
Application
- Government Construction
- Commercial Construction
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The tunnel construction market is valued at US$ 29.52 billion in 2026, led by rail and metro tunnel projects across Asian cities.
The market is projected to reach US$ 47.09 billion by 2033, growing at a 6.9% CAGR and adding US$ 17.57 billion.
The TBM Method leads with 41.6% share in 2026, supported by safer, faster excavation and lower surface disruption in dense cities.
India is growing fastest at a 9.4% CAGR through 2033, driven by metro rail programs in more than 20 cities and highway tunnels.
Asia Pacific holds the largest share at 46.2% in 2026, supported by extensive high-speed rail and metro construction in China.
Related Reports
Wearable Cameras Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global wearable cameras market is valued at US$8.80 billion in 2026, reaching US$20.80 billion by 2033, growing at a 13.1% CAGR
Spend Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global spend analytics market is valued at US$3.90 billion in 2026, reaching US$10.40 billion by 2033, growing at a 15.0% CAGR
IoT Security Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global IoT security market is valued at US$21.40 billion in 2026, reaching US$66.60 billion by 2033, growing at a 17.6% CAGR
Insurance Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global insurance analytics market is valued at US$17.30 billion in 2026, reaching US$39.70 billion by 2033, growing at a 12.6% CAGR
Smart Lighting Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The smart lighting market is projected to grow from US$27.52 billion in 2026 to US$97.29 billion by 2033, at a 19.8% CAGR, led by connected lighting demand.
Lit Fiber Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The lit fiber market is projected to grow from US$7.13 billion in 2026 to US$20.52 billion by 2033, at a 16.3% CAGR, driven by AI and cloud connectivity.