



Agricultural Films Market
Agricultural Films Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Agricultural Films Market Size and Trend Analysis
What Is the Growth Outlook for Agricultural Films to 2033?
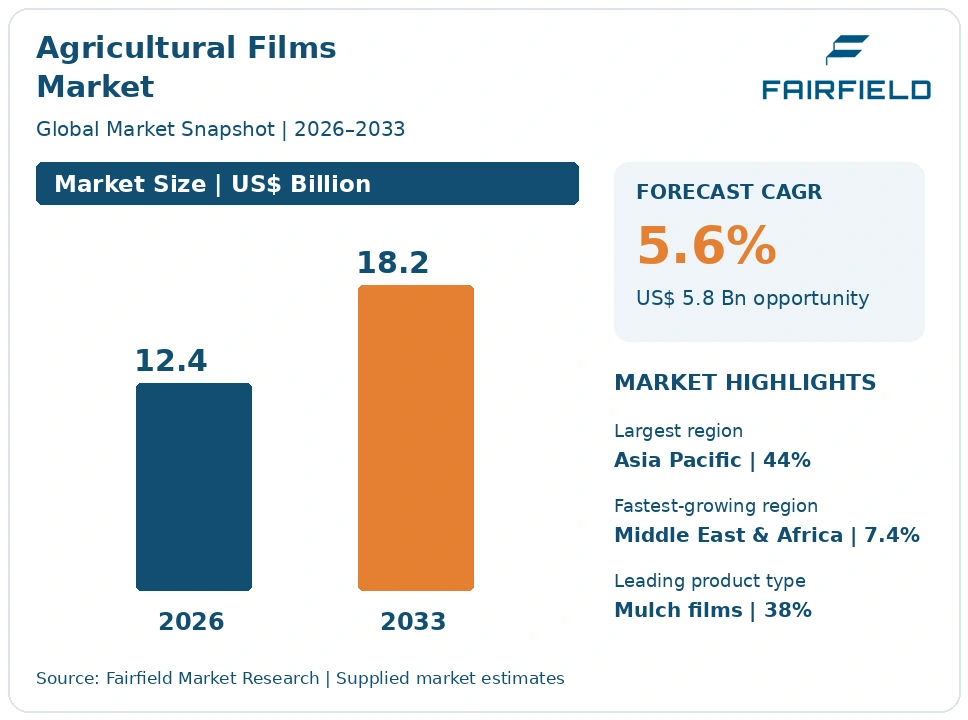
The global agricultural films market size is expected to be valued at US$ 12.4 billion in 2026 and projected to reach US$ 18.2 billion by 2033, growing at a CAGR of 5.6% between 2026 and 2033.
The market grew at an estimated 4.9% CAGR between 2020 and 2025, tracking resin prices and the steady spread of protected cultivation. Three factors drive the forecast. Protected cropping is expanding fastest where water is scarce and horticulture is high value, and every new hectare of greenhouse or tunnel consumes covering film on a replacement cycle. Dairy and livestock intensification lifts demand for silage film, bale wrap and silo bags, because conserved forage quality depends directly on an airtight seal. Certified soil-biodegradable mulch adds value per hectare where film retrieval is costly or restricted. Volume growth is modest; value growth comes from additive packages, co-extrusion and guaranteed service life rather than from extra tonnage.
Key Report Takeaways
- By Product Type: Mulch films held 38% share in 2026, while greenhouse and high-tunnel covering films are projected to expand at a 6.5% CAGR through 2033, driven by protected cropping investment in water-scarce horticulture regions that need controlled growing environments.
- By Resin Type: LLDPE held 36% share in 2026, while biodegradable polymers are projected to expand at a 9.2% CAGR through 2033, driven by certification to the European soil-biodegradable mulch standard and by rules on plastic residues left in soil.
- By Layer Structure: Three-layer co-extruded films held 42% share in 2026, while five-layer and above constructions are projected to expand at a 7.1% CAGR through 2033, driven by growers specifying longer guaranteed service life from a single cover.
- By Crop Application: Fruits and vegetables held 41% share in 2026, while forage and silage crops are projected to expand at a 6.4% CAGR through 2033, driven by larger dairy herds and the shift from clamp storage to wrapped bales.
- By Geography: Asia Pacific held 44% share in 2026, while Middle East & Africa is projected to expand at a 7.4% CAGR through 2033, driven by protected cultivation programmes in Gulf states and export horticulture in Morocco and Kenya.
Global Agricultural Films Market Trends and Insights
Drivers Impact Analysis
The two forces below account for most of the incremental demand expected between 2026 and 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Protected cultivation expanding in water-scarce, high-value horticulture regions | High | Asia Pacific, Middle East & Africa, Europe | Long term ≥4 years |
| Dairy and livestock intensification lifting silage film and bale wrap volumes | Medium | Europe, North America, Latin America | Medium term 2–4 years |
Protected Cultivation Growth Pulls Greenhouse and Tunnel Film Demand Onto a Replacement Cycle
Protected cropping is the strongest demand engine for agricultural films, because a covered hectare consumes film on a fixed replacement cycle for as long as it stays in production. Greenhouses and high tunnels raise yield per hectare several times over open field production, cut irrigation water per kilogram of produce, and extend the harvest window into shoulder seasons when prices are highest. Once a grower covers land, film becomes a recurring input rather than a one-off purchase.
The mechanism is water and value per hectare. Covered cultivation reduces evaporation and allows precise drip irrigation, which makes it the default response to water scarcity in horticulture. China, Spain, Turkey, Morocco, Mexico and the Gulf states have all expanded covered area for tomatoes, peppers, berries and cucumbers. Each installation specifies ultraviolet-stabilised, anti-drip and light-diffusing film rated for a defined number of seasons.
Dairy and Livestock Intensification Expands Silage Film, Bale Wrap and Silo Bag Volumes
Forage conservation is the second demand engine, and it grows with herd size rather than with crop area. Larger dairy and beef units need predictable winter feed of consistent quality, and that depends on excluding oxygen from the stored crop. Stretch bale wrap, silage sheets and silo bags deliver that seal at lower capital cost than permanent concrete clamps, which makes them the practical choice for expanding operations.
The causal mechanism is fermentation chemistry. Anaerobic conditions allow lactic acid bacteria to stabilise the forage, while any oxygen ingress permits moulds and yeasts that destroy dry matter and reduce milk yield. Growers therefore buy on puncture resistance, cling, ultraviolet durability through a storage season and the number of wraps required. Demand follows dairy expansion in New Zealand, Ireland, the United States, Brazil and Poland.
Restraints Impact Analysis
The pressures below are structural to short-life, high-volume field films.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Soil and moisture contamination makes used film collection and recycling expensive | High | Global | Long term ≥4 years |
| Cost premium and field-performance doubts limit soil-biodegradable mulch substitution | Medium | Europe, North America, Asia Pacific | Medium term 2–4 years |
Contaminated End-of-Life Film Makes Collection and Recycling of Agricultural Plastics Expensive
End-of-life handling is the heaviest commercial and regulatory burden on this market. Film lifted from a field after a season carries soil, crop residue, moisture and sometimes agrochemical residue, so the retrieved weight can be several times the weight of polymer originally laid. Collection, baling, transport and washing therefore cost more than the recovered resin is worth in many locations, and a large share of used film has historically been burned, buried or abandoned.
The cost source is contamination, not polymer chemistry. Mechanical recycling requires shredding, intensive washing, water treatment and drying before pelletising, and the resulting recyclate is often downgraded to non-agricultural uses. Thin mulch film tears during lifting, which multiplies handling labour. Regulators have responded with collection obligations, producer responsibility schemes and restrictions on open burning, moving the cost back toward converters and users.
Soil-Biodegradable Mulch Film Costs More Per Hectare and Still Faces Field Performance Doubts
Substitution toward soil-biodegradable mulch is slower than policy direction suggests, because the product costs materially more per hectare than conventional polyethylene at the same gauge. Growers compare that premium against the avoided cost of lifting, storing and disposing of used film, and in regions where disposal is cheap or informal the arithmetic still favours polyethylene. Adoption is therefore concentrated where retrieval is expensive, labour is scarce or landfill is restricted.
Technical doubt compounds the price gap. Biodegradable grades based on polybutylene adipate terephthalate, polylactic acid and starch blends degrade at rates that vary with soil temperature, moisture and microbial activity, so service life can end before harvest in a hot season or persist visibly afterward in a cold one. Certification to EN 17033 addresses ecotoxicity and degradation, but field confidence builds slowly.
Market Opportunities
Two revenue pools sit above the commodity mulch and silage film trade.
Certified Soil-Biodegradable Mulch Opens a Premium Per-Hectare Pool Where Retrieval Is Restricted
Certified soil-biodegradable mulch is the clearest new revenue pool in crop films, because it sells on avoided labour and compliance rather than on price per kilogram. Where collection is mandated, open burning is prohibited or disposal capacity is absent, the grower’s true comparison is film cost plus retrieval cost, and biodegradable grades can win that comparison outright. The product is also sold per hectare on a performance specification, which supports margins that commodity polyethylene cannot.
Capture favours converters who can certify to EN 17033 and demonstrate degradation behaviour in local soils, together with resin suppliers such as BASF SE and Novamont S.p.A. that supply compostable polyester and starch-blend compounds. The demand comes from vegetable, strawberry, melon and specialty crop growers in high-labour-cost regions. Policy scrutiny of plastic left in soil, including the European Union microplastics restriction, underpins the shift.
Long-Life Multi-Layer Greenhouse Films With Light Management Sell on Guaranteed Service Seasons
Long-life, light-managing greenhouse film is the highest-value opportunity in protected cropping, because it converts a commodity cover into a specified agronomic input. Five-layer and seven-layer constructions combining EVA or EBA cores with thermic, anti-drip, anti-dust and diffusing additive packages are sold on a guaranteed number of seasons of ultraviolet exposure and on measurable light transmission and diffusion. Growers pay a premium that is recovered in fewer re-covering operations and better crop uniformity.
The buyers are professional protected-crop operators in Spain, the Netherlands, Turkey, Mexico and the Gulf states, plus turnkey greenhouse builders specifying film as part of a structure package. Capture requires multi-layer co-extrusion capacity, masterbatch formulation skill and accelerated weathering data to support service-life warranties. Rising energy costs strengthen the case for thermic grades that retain night heat.
Segment Analysis
By Product Type: Mulch Films Lead Volume While Greenhouse Covers Grow Faster
Mulch films hold 38% of 2026 revenue, the largest product share, because they are laid on vast open-field vegetable, cotton, maize and strawberry areas and replaced every season. Black, clear, silver and coloured grades control weeds, raise soil temperature and conserve moisture at a low cost per hectare. Greenhouse and high-tunnel covering films are the fastest-growing product type at a 6.5% CAGR through 2033, as protected area expands and growers specify longer-life, higher-specification covers. Low tunnel and direct crop cover films serve early-season protection in field vegetables, while silage films, bale wrap, silage sheets and silo bags form a large, steady business tied to livestock numbers. Fumigation and solarisation films remain a technical niche with strict barrier requirements. Value is migrating from tonnage toward specification, which favours converters with co-extrusion and additive capability.
By Resin Type: LLDPE Anchors the Market While Biodegradable Polymers Expand Quickest
LLDPE accounts for 36% of 2026 revenue, the leading resin position, because its puncture resistance and stretch behaviour suit thin mulch films and bale wrap better than alternatives. It also downgauges well, letting converters cut grammage while holding mechanical strength at the laying speeds machines demand. Biodegradable polymers, including polybutylene adipate terephthalate, polylactic acid and starch blends, are the fastest-growing resin class at a 9.2% CAGR through 2033, albeit from a small base, driven by certification and by rules on plastic residues in soil. LDPE remains the backbone of greenhouse covers, HDPE serves silage sheets and high-strength thin films, and EVA and EBA supply thermic and clarity performance in multi-layer greenhouse constructions. Resin choice is now an agronomic specification decision rather than a procurement one.
By Layer Structure: Three-Layer Co-Extrusion Leads as Five-Layer Constructions Accelerate
Three-layer co-extruded films represent 42% of 2026 revenue, the leading construction, because three layers allow a converter to place ultraviolet stabiliser, anti-drip and mechanical strength where each works best without excessive line complexity. The format has become the default for quality greenhouse film and premium bale wrap. Five-layer and above constructions are the fastest-growing at a 7.1% CAGR through 2033, as growers demand longer guaranteed service life, better light diffusion and thinner total gauge from a single cover. Monolayer film retains a substantial share in low-cost mulch and short-life applications where price dominates. The commercial consequence is capital intensity: multi-layer lines, masterbatch formulation and weathering test capability separate specification suppliers from commodity extruders, and that gap widens as service-life warranties become the basis of sale.
By Crop Application: Fruits and Vegetables Dominate While Forage and Silage Crops Climb
Fruits and vegetables generate 41% of 2026 revenue, the leading application, because horticulture uses mulch, low tunnel, high tunnel and greenhouse films together, often on the same holding, and supports the highest film spend per hectare. Crop value justifies premium additive packages and earlier harvest. Forage and silage crops are the fastest-growing application at a 6.4% CAGR through 2033, as dairy herds consolidate and operators move from clamp storage toward wrapped bales and silo bags that need no permanent infrastructure. Cereals and grains use film mainly for grain storage covers and limited mulching in China. Flowers and ornamentals form a small, high-specification segment where light quality and diffusion matter most. Converters increasingly organise sales teams by crop rather than by product, because specification now follows agronomy.
Geography Analysis
North America Buys on Specification and Faces Rising Film Recovery Expectations
North America holds 16% of 2026 revenue and is expected to grow at roughly a 4.8% CAGR through 2033. The United States dominates, with mulch film on vegetable, strawberry, melon and cotton acreage in California, Florida and Georgia, extensive bale wrap use across dairy states, and growing high-tunnel area supported by federal conservation programmes. Canada and Mexico add protected cropping and berry production under contract to retail buyers.
High labour costs shape purchasing. Retrieval and disposal of used mulch is expensive, which makes soil-biodegradable grades commercially interesting earlier here than in lower-wage regions. State-level restrictions on open burning of agricultural waste and patchy recycling access are pushing growers and cooperatives toward organised collection. The main regional change is the move toward recovery programmes negotiated between retailers, growers and converters.
Europe Sets the Standards That Define Agricultural Film Specification and Recovery
Europe accounts for 24% of 2026 revenue, growing at about a 4.6% CAGR through 2033, and functions as the market’s regulatory reference point. Spain, Italy, France, Turkey and Greece host the largest protected cropping areas, with the plastic-covered horticulture of Almeria among the densest concentrations of greenhouse film anywhere. Ireland, Germany, Poland and the Netherlands anchor silage film and bale wrap demand.
Standards drive specification. EN 17033 defines soil-biodegradable mulch film requirements, the European Union microplastics restriction under the REACH framework has sharpened scrutiny of plastic left in soil, and the Single-Use Plastics framework signals wider policy direction. Extended producer responsibility and organised collection schemes for farm plastics already operate in several countries and continue to spread, which raises compliance cost but also underwrites recyclate supply.
Which Region Is Leading the Agricultural Films Market?
Asia Pacific leads the agricultural films market with 44% of global revenue in 2026, growing at roughly a 6.0% CAGR through 2033. China alone consumes more mulch film than any other country, applying it across cotton, maize, potato, peanut and vegetable areas to raise soil temperature and conserve moisture in dry northern provinces. That single application explains the region’s dominant tonnage position.
India, Japan, South Korea, Vietnam and Australia add demand through polyhouse horticulture, protected vegetable production and expanding silage use as dairy herds commercialise. China has also tightened control of agricultural film quality and residue recovery, requiring thicker, retrievable mulch and promoting collection, which lifts average gauge and value per hectare. The regional opportunity lies in that upgrade: policy is pushing buyers from the thinnest possible film toward specified, recoverable products.
Latin America Expands Protected Horticulture and Silage Film Around Export Agriculture
Latin America represents 10% of 2026 revenue, expanding at about a 5.9% CAGR through 2033. Mexico is the anchor, with extensive shade-house and greenhouse production of tomatoes, peppers and berries grown under contract for export buyers that specify consistent quality and harvest timing. Brazil drives silage film and silo bag demand through large dairy and beef operations, while Chile, Peru and Colombia add table grape, blueberry and flower production.
Barriers are practical. Currency movements affect imported resin and finished film pricing, collection infrastructure for used film is limited outside organised export clusters, and informal disposal remains common. Rural logistics raise delivered cost in inland production zones. The change to watch is the extension of buyer-driven sustainability audits from produce quality into on-farm plastic handling.
Which Region Is Growing Fastest in the Agricultural Films Market?
Middle East & Africa is growing fastest, at a 7.4% CAGR through 2033, from 6% of global revenue in 2026. Growth is driven by water scarcity and food security policy. Gulf states including Saudi Arabia and the United Arab Emirates are funding protected cultivation to produce vegetables locally with a fraction of the irrigation water that open field production needs, and every covered hectare is a recurring film customer.
Morocco, Egypt, Kenya, South Africa and Algeria expand greenhouse and tunnel area for export tomatoes, berries, beans and cut flowers sold into demanding retail buyers. Barriers include high ambient ultraviolet and temperature loads that shorten film life, limited local extrusion capacity, and almost no collection or recycling infrastructure. The clearest opportunity is high-ultraviolet-resistance film engineered for desert conditions, sold with realistic service-life warranties.
Competitive Landscape
The agricultural films market has Low concentration. Film is heavy, bulky and cheap per unit of volume, so freight from plant to farm limits how far a converter can economically sell, and regional extruders hold durable positions against larger groups. The result is several hundred relevant producers worldwide, ranging from single-line mulch extruders serving one growing district to multinational groups running multi-layer lines on several continents. Consolidation has occurred mainly where buyers are themselves consolidated, such as large dairy cooperatives and greenhouse construction contractors, and it usually buys geographic coverage rather than technology.
Competition is decided by the additive package and the guaranteed service life, not by the polymer. A greenhouse film is specified by how many seasons of ultraviolet exposure it survives at a given radiation dose, and a mulch film by its mechanical strength at the thinnest gauge the laying machine can handle without tearing. Vendors therefore compete on masterbatch formulation, co-extrusion capability, accelerated weathering data, downgauging without strength loss, and warranty terms that growers can rely on. Price per kilogram still governs commodity mulch, which keeps margins thin at the low end. New entrants arrive mainly from compostable polymer chemistry and from recycling businesses offering films with recycled content.
Positioning differs by heritage. Berry Global Group, Inc., RKW Group, Trioplast Industrier AB, Coveris and Rani Plast Oy are strongest in silage and stretch film where scale and consistency matter most. Grupo Armando Alvarez, Ginegar Plastic Products Ltd., Plastika Kritis S.A., Polifilm GmbH and Groupe Barbier carry deep greenhouse and mulch film specification expertise, several combining film extrusion with their own masterbatch. BASF SE and Novamont S.p.A. supply the biodegradable polymer chemistry behind certified mulch grades.
Strategic direction is converging on recyclability, recycled content and certified biodegradability, because these are becoming conditions of sale rather than differentiators.
Agricultural Films Industry Leaders
- Berry Global Group, Inc.
- RKW Group
- Grupo Armando Alvarez
- Trioplast Industrier AB
- Ginegar Plastic Products Ltd.
Recent Industry Developments
2018: EN 17033, the European standard setting requirements and test methods for biodegradable mulch films used in agriculture and horticulture, was published – it became the certification reference that lets a soil-biodegradable grade be sold as such rather than claimed informally.
September 2020: China’s administrative measures on agricultural film took effect, tightening quality requirements for mulch film and placing recovery duties on producers, sellers and users – they pushed the world’s largest mulch market away from ultra-thin, unrecoverable film.
July 2021: The main market restrictions of the European Union Single-Use Plastics Directive took effect – they set the policy direction on avoidable plastic that now informs how agricultural plastics are regulated at national level.
September 2023: The European Commission adopted a restriction on intentionally added microplastics under the REACH framework – it sharpened regulatory attention on polymer fragments remaining in soil and strengthened the case for certified soil-biodegradable mulch.
Agricultural Films Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 12.4 Billion |
| Market Size 2033 | US$ 18.2 Billion |
| CAGR 2026–2033 | 5.6% |
| Absolute Dollar Opportunity | US$ 5.8 Billion |
| Largest Market | Asia Pacific – 44% share in 2026 |
| Fastest-Growing Market | Middle East & Africa – 7.4% CAGR |
| Market Concentration | Low |
| Major Players | Berry Global Group, Inc., RKW Group, Grupo Armando Alvarez, Ginegar Plastic Products Ltd. |
This study covers polymer films used in crop production: mulch films including soil-biodegradable grades, greenhouse and high-tunnel covers, low tunnel and direct crop cover films, silage films, bale wrap, silage sheets, silo bags, and fumigation and solarisation films. Food and industrial packaging films, including compostable packaging film, are excluded. The base year is 2025 and the forecast period runs from 2026 to 2033, in US$ Billion.
Agricultural Films Market Segmentation
Product Type
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
Resin Type
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
Layer Structure
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
Crop Application
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Agricultural Films Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Protected Cultivation Growth Pulls Greenhouse and Tunnel Film Demand Onto a Replacement Cycle
- Dairy and Livestock Intensification Expands Silage Film, Bale Wrap and Silo Bag Volumes
- Restraints
- Contaminated End-of-Life Film Makes Collection and Recycling of Agricultural Plastics Expensive
- Soil-Biodegradable Mulch Film Costs More Per Hectare and Still Faces Field Performance Doubts
- Market Opportunities
- Certified Soil-Biodegradable Mulch Opens a Premium Per-Hectare Pool Where Retrieval Is Restricted
- Long-Life Multi-Layer Greenhouse Films With Light Management Sell on Guaranteed Service Seasons
- Drivers
- Global Agricultural Films Market Outlook, 2020–2033
- Global Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- Global Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- Global Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- Global Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- Global Agricultural Films Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Agricultural Films Market Outlook, 2020–2033
- North America Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- North America Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- North America Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- North America Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- North America Agricultural Films Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Agricultural Films Market Outlook, by Product Type, 2020–2033
- United States Agricultural Films Market Outlook, by Resin Type, 2020–2033
- United States Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- United States Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Canada Agricultural Films Market Outlook, by Product Type, 2020–2033
- Canada Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Canada Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Canada Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Mexico Agricultural Films Market Outlook, by Product Type, 2020–2033
- Mexico Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Mexico Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Mexico Agricultural Films Market Outlook, by Crop Application, 2020–2033
- North America Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Agricultural Films Market Outlook, 2020–2033
- Europe Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- Europe Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- Europe Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- Europe Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- Europe Agricultural Films Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Spain Agricultural Films Market Outlook, by Product Type, 2020–2033
- Spain Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Spain Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Spain Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Italy Agricultural Films Market Outlook, by Product Type, 2020–2033
- Italy Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Italy Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Italy Agricultural Films Market Outlook, by Crop Application, 2020–2033
- France Agricultural Films Market Outlook, by Product Type, 2020–2033
- France Agricultural Films Market Outlook, by Resin Type, 2020–2033
- France Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- France Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Turkey Agricultural Films Market Outlook, by Product Type, 2020–2033
- Turkey Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Turkey Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Turkey Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Greece Agricultural Films Market Outlook, by Product Type, 2020–2033
- Greece Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Greece Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Greece Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Ireland Agricultural Films Market Outlook, by Product Type, 2020–2033
- Ireland Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Ireland Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Ireland Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Germany Agricultural Films Market Outlook, by Product Type, 2020–2033
- Germany Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Germany Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Germany Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Poland Agricultural Films Market Outlook, by Product Type, 2020–2033
- Poland Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Poland Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Poland Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Netherlands Agricultural Films Market Outlook, by Product Type, 2020–2033
- Netherlands Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Netherlands Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Netherlands Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Europe Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Agricultural Films Market Outlook, 2020–2033
- Asia Pacific Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- Asia Pacific Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- Asia Pacific Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- Asia Pacific Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- Asia Pacific Agricultural Films Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Agricultural Films Market Outlook, by Product Type, 2020–2033
- China Agricultural Films Market Outlook, by Resin Type, 2020–2033
- China Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- China Agricultural Films Market Outlook, by Crop Application, 2020–2033
- India Agricultural Films Market Outlook, by Product Type, 2020–2033
- India Agricultural Films Market Outlook, by Resin Type, 2020–2033
- India Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- India Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Japan Agricultural Films Market Outlook, by Product Type, 2020–2033
- Japan Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Japan Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Japan Agricultural Films Market Outlook, by Crop Application, 2020–2033
- South Korea Agricultural Films Market Outlook, by Product Type, 2020–2033
- South Korea Agricultural Films Market Outlook, by Resin Type, 2020–2033
- South Korea Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- South Korea Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Vietnam Agricultural Films Market Outlook, by Product Type, 2020–2033
- Vietnam Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Vietnam Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Vietnam Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Australia Agricultural Films Market Outlook, by Product Type, 2020–2033
- Australia Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Australia Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Australia Agricultural Films Market Outlook, by Crop Application, 2020–2033
- New Zealand Agricultural Films Market Outlook, by Product Type, 2020–2033
- New Zealand Agricultural Films Market Outlook, by Resin Type, 2020–2033
- New Zealand Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- New Zealand Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Asia Pacific Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Agricultural Films Market Outlook, 2020–2033
- Latin America Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- Latin America Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- Latin America Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- Latin America Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- Latin America Agricultural Films Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Mexico Agricultural Films Market Outlook, by Product Type, 2020–2033
- Mexico Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Mexico Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Mexico Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Brazil Agricultural Films Market Outlook, by Product Type, 2020–2033
- Brazil Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Brazil Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Brazil Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Chile Agricultural Films Market Outlook, by Product Type, 2020–2033
- Chile Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Chile Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Chile Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Peru Agricultural Films Market Outlook, by Product Type, 2020–2033
- Peru Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Peru Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Peru Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Colombia Agricultural Films Market Outlook, by Product Type, 2020–2033
- Colombia Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Colombia Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Colombia Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Latin America Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Agricultural Films Market Outlook, 2020–2033
- Middle East & Africa Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
- Middle East & Africa Agricultural Films Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
- Middle East & Africa Agricultural Films Market Outlook, by Layer Structure, Value (US$ Billion), 2020–2033
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
- Middle East & Africa Agricultural Films Market Outlook, by Crop Application, Value (US$ Billion), 2020–2033
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
- Middle East & Africa Agricultural Films Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Agricultural Films Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Saudi Arabia Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Saudi Arabia Agricultural Films Market Outlook, by Crop Application, 2020–2033
- United Arab Emirates Agricultural Films Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Agricultural Films Market Outlook, by Resin Type, 2020–2033
- United Arab Emirates Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- United Arab Emirates Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Morocco Agricultural Films Market Outlook, by Product Type, 2020–2033
- Morocco Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Morocco Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Morocco Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Egypt Agricultural Films Market Outlook, by Product Type, 2020–2033
- Egypt Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Egypt Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Egypt Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Kenya Agricultural Films Market Outlook, by Product Type, 2020–2033
- Kenya Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Kenya Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Kenya Agricultural Films Market Outlook, by Crop Application, 2020–2033
- South Africa Agricultural Films Market Outlook, by Product Type, 2020–2033
- South Africa Agricultural Films Market Outlook, by Resin Type, 2020–2033
- South Africa Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- South Africa Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Algeria Agricultural Films Market Outlook, by Product Type, 2020–2033
- Algeria Agricultural Films Market Outlook, by Resin Type, 2020–2033
- Algeria Agricultural Films Market Outlook, by Layer Structure, 2020–2033
- Algeria Agricultural Films Market Outlook, by Crop Application, 2020–2033
- Middle East & Africa Agricultural Films Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Berry Global Group, Inc.
- RKW Group
- Grupo Armando Alvarez
- Trioplast Industrier AB
- Ginegar Plastic Products Ltd.
- Plastika Kritis S.A.
- Coveris
- Rani Plast Oy
- Groupe Barbier
- Polifilm GmbH
- Novamont S.p.A.
- BASF SE
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Mulch films (black, clear, silver, coloured and soil-biodegradable grades)
- Greenhouse and high-tunnel covering films
- Low tunnel and direct crop cover films
- Silage films (bale wrap, silage sheets, silo bags)
- Fumigation and solarisation films
Resin Type
- LDPE
- LLDPE
- HDPE
- EVA and EBA
- Biodegradable polymers (PBAT, PLA, starch blends)
Layer Structure
- Monolayer
- Three-layer co-extruded
- Five-layer and above co-extruded
Crop Application
- Fruits and vegetables
- Cereals and grains
- Flowers and ornamentals
- Forage and silage crops
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 12.4 billion in 2026, covering mulch, greenhouse, tunnel, silage and fumigation films used in crop production.
Revenue reaches US$ 18.2 billion by 2033 at a 5.6% CAGR, an absolute dollar opportunity of US$ 5.8 billion over the forecast period.
Mulch films lead with 38% share in 2026, because they are laid across very large open-field vegetable, cotton and maize areas annually.
Middle East & Africa grows fastest at a 7.4% CAGR through 2033, led by protected cultivation programmes and export horticulture under water scarcity.
Asia Pacific holds the largest share at 44% in 2026, driven mainly by mulch film consumption across cotton, maize and vegetable areas in China.
Related Reports
Unsaturated Polyester Resin Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the unsaturated polyester resin market, forecast to reach US$18.1 billion by 2033 at 4.6% CAGR, with resin, end-use and regional insights.
Renewable Chemicals Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the renewable chemicals market, projected to reach US$379.48 billion by 2033 at 11.2% CAGR, with product, feedstock and regional insights.
Ultra high Molecular Weight Polyethylene Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the UHMWPE market, forecast to reach US$4.8 billion by 2033 at 7.5% CAGR, with insights into grades, applications, regions and leading companies.
Steel Drums & IBCs Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the steel drums & IBCs market, projected to reach US$29.8 billion by 2033 at 4.8% CAGR, with segment, regional and competitive insights.
Semiconductor Gases Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The semiconductor gases market is projected to grow from US$9.6 billion in 2026 to US$16.8 billion by 2033, at an 8.3% CAGR. Explore segments and trends.
Non-load Bearing Walls Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The non-load bearing walls market is projected to grow from US$96.0 billion in 2026 to US$136.0 billion by 2033, at a 5.1% CAGR. Explore key trends.