


Battery Manufacturing Equipment Market
Battery Manufacturing Equipment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Battery Manufacturing Equipment Market Size and Trend Analysis
How Fast Is the Battery Manufacturing Equipment Market Growing?
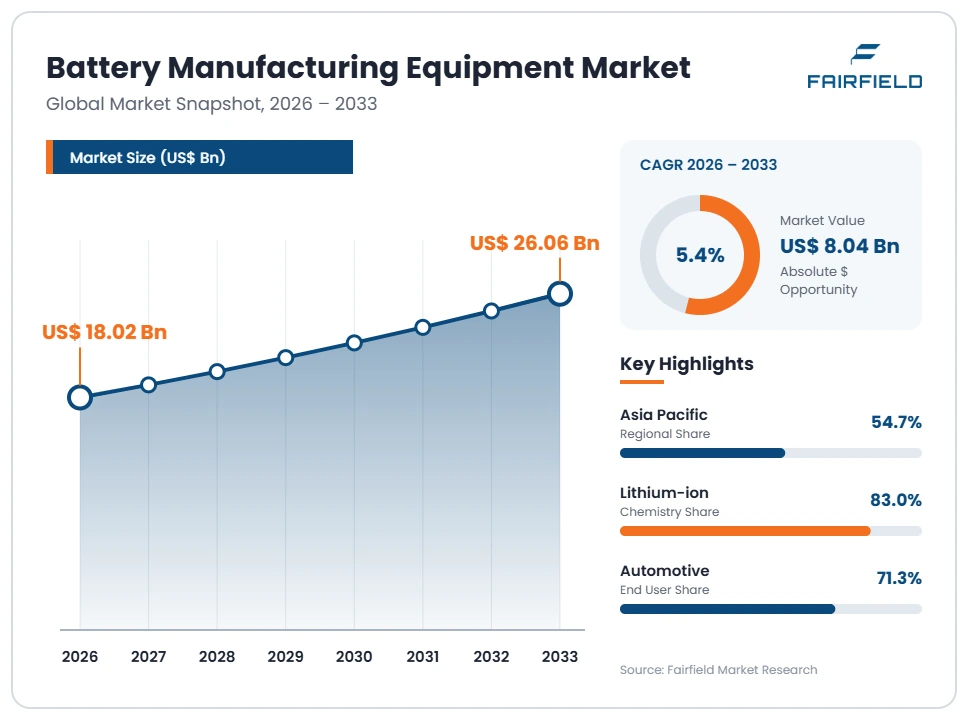
The global battery manufacturing equipment market size is expected to be valued at US$ 18.02 billion in 2026 and projected to reach US$ 26.06 billion by 2033, growing at a CAGR of 5.4% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 14.6%, as a wave of gigafactory projects for electric vehicles drove record equipment orders before slowing in 2024 amid overcapacity. Three factors now support steadier growth: continued cell capacity additions for electric vehicles and energy storage, government incentives that localize production in North America and Europe, and new technologies such as dry electrode and solid-state cells. The market is moving toward higher automation, inline quality inspection, and flexible lines that can switch between cell chemistries and formats.
Key Report Takeaways
- By Chemistry: Lithium-ion held 83.0% share in 2026, while Solid-state is projected to expand at a 30.2% CAGR through 2033, driven by pilot lines in Japan, South Korea, and China preparing for commercial production.
- By Machine Type: Coating & Drying held 18.8% share in 2026, while Formation & Testing is projected to expand at a 12.5% CAGR through 2033, driven by higher quality demands and longer cell aging steps.
- By Automation Level: Fully Automatic held 62.4% share in 2026, while Semi-automatic is projected to expand at a 6.8% CAGR through 2033, driven by pilot lines and smaller specialty cell producers.
- By End User: Automotive held 71.3% share in 2026, while Energy Storage Systems are projected to expand at a 9.8% CAGR through 2033, driven by grid-scale lithium iron phosphate projects.
- By Region: Asia Pacific held 54.7% share in 2026, while North America is projected to expand at a 12.2% CAGR through 2033, driven by federal incentives and new gigafactories in the United States and Canada.
Global Battery Manufacturing Equipment Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on battery manufacturing equipment demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Cell capacity build-out for electric vehicles and storage | High | Global, strongest in Asia Pacific and North America | Medium term (2–4 years) |
| Government incentives for local battery production | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
Gigafactory Capacity Build-Out Keeps Demand for Battery Manufacturing Equipment High
Large-scale cell capacity additions for electric vehicles and energy storage are the primary driver of battery manufacturing equipment demand. Every new gigafactory needs electrode coating machines, calendering presses, slitting systems, cell assembly equipment, and formation and testing lines.
The evidence is the scale of announced capacity. Automakers and cell makers announced about 1.2 TWh of new lithium-ion capacity in 2024, roughly triple the 2023 level. In March 2024, Wuxi Lead Intelligent Equipment became the exclusive equipment supplier for the first phase of American Battery Factory's lithium iron phosphate gigafactory in Tucson, Arizona, described as the largest such order won by a Chinese company in the United States. Energy storage demand is rising fast as utilities add grid batteries. Even with slower electric vehicle growth in some markets, replacement of older lines and new chemistries keep equipment orders flowing.
Government Incentives Are Localizing Battery Manufacturing Equipment Demand
Government incentives that encourage local battery production are reshaping where battery manufacturing equipment is installed. Countries want domestic supply chains for electric vehicles and energy storage to reduce dependence on imports.
The mechanism is direct subsidies, tax credits, and loans. In the United States, production tax credits under the Inflation Reduction Act reward cells and modules made domestically, and the Department of Energy has approved funding for battery projects. Japan set aside a JPY 350 billion subsidy tranche that ring-fenced spending on solid-state pilot lines with domestic tools. Canada offers incentives that have attracted large cell plants, making it the fastest-growing country at about 14.4% CAGR. European Union programs support local gigafactories. These policies create demand for new lines in regions that previously had little battery manufacturing.
Restraints Impact Analysis
Two restraints limit how smoothly battery manufacturing equipment demand can grow.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Overcapacity and project cancellations | High | Europe, North America, Asia Pacific | Short term (≤2 years) |
| High capital cost and slow yield ramp-up | Medium | Europe, North America | Medium term (2–4 years) |
Overcapacity and Project Cancellations Reduce Battery Manufacturing Equipment Orders
Overcapacity in cell production and the cancellation of gigafactory projects reduce battery manufacturing equipment orders. When cell makers delay or abandon plants, equipment suppliers lose expected contracts and face payment risks.
The specific causes are slower electric vehicle sales growth in some markets, falling cell prices, and financial failures. In June 2024, BMW cancelled a US$ 2 billion supply contract with Northvolt. Northvolt filed for bankruptcy protection in the United States in November 2024 and then in Sweden in March 2025, removing one of Europe's largest homegrown cell producers. Equipment maker Manz reported a 23% fall in order intake in the third quarter of 2024. Large cell producers in China also have spare capacity, which slows new orders. These conditions create a cyclical slowdown for equipment suppliers.
High Capital Costs and Slow Yield Ramp-Up Challenge Battery Manufacturing Equipment Buyers
High capital costs and slow production ramp-ups challenge buyers of battery manufacturing equipment, especially new entrants. A full gigafactory line requires very large investment, and it can take years to reach target yields.
The underlying causes are process complexity and limited experience. Electrode coating, drying, calendering, and stacking must be controlled to micrometer precision, and small defects can cause safety problems or scrap. Northvolt's Skellefteå gigafactory struggled to produce beyond about 1 GWh despite a planned 16 GWh capacity. New manufacturers often lack experienced engineers and the detailed process knowledge that Asian leaders built over decades of high-volume production. High scrap rates waste costly materials such as cathode powders, lithium salts, and copper foil. These challenges make investors cautious, slow equipment purchases, and push buyers toward proven suppliers.
Market Opportunities
Dry Electrode and Solid-State Equipment Open a Next-Generation Revenue Pool
Equipment for dry electrode and solid-state battery production creates a high-value, next-generation revenue pool. These technologies promise lower production costs, smaller factory footprints, and higher energy density, but they require new types of machines.
Equipment makers with advanced coating, pressing, and inert-atmosphere expertise are positioned to capture this demand. Tesla spent about US$ 1.8 billion on 4680 dry electrode technology equipment through mid-2024, showing the scale of investment possible. Solid-state lines need precise thin-film deposition, high-pressure lamination, and moisture-free environments. Japan's subsidy program ring-fences funds for solid-state pilot lines using domestic tools. Automakers and cell makers developing next-generation cells are the main customers. Early suppliers can set standards and secure long-term relationships before mass production begins.
Formation, Testing, and Inline Inspection Create a Quality-Driven Revenue Pool
Formation, testing, and inline inspection equipment create a fast-growing, quality-driven revenue pool. Cell makers must prove that every cell is safe and consistent, especially for vehicles and grid storage.
Suppliers of formation and testing equipment, machine vision, and data analytics can capture this demand. Formation is the step where cells are charged for the first time and aged, which takes days and occupies large floor space. Testing equipment checks capacity, internal resistance, and self-discharge before cells leave the factory for module assembly. AI-based vision systems inspect electrodes and welds inline, reducing scrap and recall risk. Formation and testing equipment is expected to grow at a 12.5% CAGR. Cell makers, automakers, and energy storage integrators are the main customers, especially as new safety regulations raise traceability requirements.
Segment Analysis
- By Chemistry: Lithium-ion Dominates While Solid-state Grows Fastest
Lithium-ion held 83.0% share in 2026. Almost all new gigafactories produce lithium-ion cells, including nickel-rich and lithium iron phosphate chemistries, for electric vehicles, energy storage, and consumer electronics. Equipment for these lines is mature and produced at scale by Asian suppliers.
Solid-state is the fastest-growing chemistry, expanding at a 30.2% CAGR through 2033. Automakers and cell makers in Japan, South Korea, China, the United States, and Europe are building pilot lines for solid-state cells with solid electrolytes. These lines need specialized equipment for electrolyte layering, lamination, and dry rooms. Lead-acid and nickel-based equipment is declining. For the broader market, solid-state growth creates new opportunities for suppliers with materials and precision engineering expertise, although volumes remain small during the forecast period.
- By Machine Type: Coating & Drying Leads While Formation & Testing Grows Fastest
Coating & Drying held 18.8% share in 2026. Electrode coating machines apply cathode and anode slurries onto metal foils, and long drying ovens remove solvents. These are among the largest, most expensive machines in a gigafactory and have a major effect on cell quality and energy use.
Formation & Testing is the fastest-growing machine type, expanding at a 12.5% CAGR through 2033. Cell makers are investing in larger and smarter formation and testing systems to improve quality and traceability. Longer aging and more detailed testing are needed for high-energy and fast-charging cells. Calendering presses are growing at about 6.1%, while mixing, slitting, cell assembly equipment, and stacking remain essential. For the market, formation and testing growth shifts value toward electrical and software-intensive systems with recurring upgrade potential.
- By Automation Level: Fully Automatic Leads While Semi-automatic Grows Fastest
Fully Automatic held 62.4% share in 2026. Large gigafactories rely on fully automated lines to produce millions of cells with consistent quality, minimal labor, and high throughput. Robots, conveyors, and integrated control systems link each process step.
Semi-automatic is the fastest-growing automation level, expanding at a 6.8% CAGR through 2033. Pilot lines for solid-state, sodium-ion, and specialty cells often use semi-automatic equipment, which offers flexibility at lower cost. Research institutes, start-ups, and makers of batteries for drones, medical devices, and defense also prefer smaller lines. Manual equipment is limited to laboratories. For the market, semi-automatic growth supports innovation and provides an entry point for equipment suppliers to build relationships with future high-volume customers.
- By End User: Automotive Leads While Energy Storage Systems Grow Fastest
Automotive held 71.3% share in 2026. Electric vehicle cell production accounts for most gigafactory capacity, and automakers and their cell partners are the largest buyers of battery manufacturing equipment. Joint ventures between automakers and cell makers in North America and Europe have driven major orders.
Energy Storage Systems are the fastest-growing end user, expanding at a 9.8% CAGR through 2033. Utilities, renewable developers, and commercial users are deploying large lithium iron phosphate batteries to balance wind and solar power and support grids. Cell makers are converting or adding lines for large prismatic storage cells. Consumer electronics and industrial users remain important. For the market, storage growth helps offset slower electric vehicle demand in some regions and keeps equipment suppliers busy.
Geography Analysis
- Which Region Is Growing Fastest in the Battery Manufacturing Equipment Market?
North America is growing fastest in the battery manufacturing equipment market at a 12.2% CAGR through 2033. The United States is adding gigafactories supported by Inflation Reduction Act production tax credits and Department of Energy funding. Automakers and cell partners are building plants across the Midwest and South, and projects such as American Battery Factory's Arizona plant use Chinese equipment. Canada is the fastest-growing country, at about 14.4% CAGR, after attracting major cell and materials investments. Policy uncertainty around tax credits and project delays remain key risks for suppliers. One opportunity is domestic equipment manufacturing to meet local-content rules.
- Europe Rebuilds Battery Ambitions in the Battery Manufacturing Equipment Market
Europe is a major market where gigafactory ambitions face setbacks but continue to expand. The region accounted for about 21.8% of revenue and is expected to grow at about 8.6% CAGR. Northvolt's bankruptcy in 2025 hurt confidence, yet Europe's battery pipeline is still set to more than double by 2030, largely through Asian cell producers. Germany, Hungary, Poland, and Spain host major cell projects. Established European equipment makers such as Dürr, Manz, Schuler, and Bühler compete closely with Asian suppliers. One opportunity is energy-efficient coating and drying technology that lowers plant emissions.
- Which Region Is Leading the Battery Manufacturing Equipment Market?
Asia Pacific is leading the battery manufacturing equipment market with a 54.7% share in 2026. China dominates global cell production and hosts leading equipment makers such as Wuxi Lead Intelligent Equipment and Yinghe Technology, which supply both domestic and international customers. South Korea and Japan have major global cell makers and equipment suppliers, including Hitachi High-Tech and Hanwha Machinery. Mature supply chains, skilled engineers, and low equipment costs support the region. Growth is slower at about 4.0% because of existing overcapacity in China. One clear opportunity is exporting complete production lines to new gigafactories abroad.
- Latin America Explores Battery Production in the Battery Manufacturing Equipment Market
Latin America is an emerging region that holds about 2.2% of revenue. Mexico attracts interest because of its automotive industry and proximity to the United States, while Brazil is exploring local electric vehicle and battery production. Chile and Argentina hold large lithium reserves and aim to move into higher-value processing. Key barriers include limited battery industrial expertise, high financing costs, and uncertain local demand. Equipment imports from Asia and Europe raise project costs and lead times. One opportunity is energy storage cell and module assembly for regional solar and mining projects, which could start with semi-automatic lines.
- Middle East & Africa Plans Battery Industrial Projects in the Battery Manufacturing Equipment Market
Middle East & Africa is an early-stage region that holds about 2.1% of revenue. Saudi Arabia and the United Arab Emirates are planning battery and electric vehicle projects as part of economic diversification, supported by large sovereign wealth investment. Morocco is attracting battery materials, cathode, and component investment because of its phosphate resources and trade links with Europe. Key barriers include limited advanced manufacturing experience, skilled labor shortages, and small local markets. Most equipment must be imported, which adds cost and long installation timelines. One clear opportunity is lithium iron phosphate cell production for regional energy storage projects.
Competitive Landscape
The battery manufacturing equipment market is moderately concentrated. Chinese suppliers such as Wuxi Lead Intelligent Equipment, Yinghe Technology, and TMAX hold large shares of global orders because of their scale and complete line offerings. Hitachi High-Tech and Komori in Japan, Hanwha Machinery and PNT in South Korea, and Dürr, Manz, Schuler, Bühler, and Andritz in Europe compete in specific process steps. Automation leaders such as Siemens, ABB, and Festo supply control systems.
Suppliers compete on throughput, precision, yield, energy efficiency, delivery time, and price. The ability to deliver complete turnkey lines with process guarantees is a key advantage. Local service engineers and spare parts support are important for new gigafactories outside Asia, where buyers lack in-house expertise.
Strategic moves show how competition is changing. Wuxi Lead Intelligent Equipment won an exclusive supply role for American Battery Factory's Arizona plant in March 2024, showing Chinese suppliers' reach into North America. Manz reported a 23% drop in third-quarter 2024 order intake as European projects slowed. Northvolt's bankruptcy filings in November 2024 and March 2025 affected suppliers with exposure to its plants. Equipment makers are also expanding into dry electrode and solid-state tools to capture the next technology cycle.
Three themes shape vendor strategy. First, suppliers are localizing production and service in North America and Europe. Second, they are investing in next-generation process technologies. Third, they are adding digital quality control and software to differentiate beyond hardware.
Recent Industry Developments
- March 2025: Northvolt filed for bankruptcy in Sweden – reduces near-term equipment orders and raises supplier credit risk in Europe.
- November 2024: Northvolt filed for bankruptcy protection in the United States – signals a slowdown in new European gigafactory projects.
- March 2024: Wuxi Lead Intelligent Equipment became exclusive equipment supplier for American Battery Factory's first-phase Arizona plant – extends Chinese equipment into North America.
Companies Covered in the Report
- Wuxi Lead Intelligent Equipment
- Yinghe Technology
- Dürr
- Hitachi High-Tech
- Manz
- Schuler
- Bühler Group
- Andritz
- Hanwha Machinery
- PNT Group
- TMAX
- Siemens
Battery Manufacturing Equipment Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 18.02 Billion |
| Market Size 2033 | US$ 26.06 Billion |
| CAGR 2026–2033 | 5.4% |
| Absolute Dollar Opportunity | US$ 8.04 Billion |
| Largest Market | Asia Pacific |
| Fastest-Growing Market | North America |
| Market Concentration | Medium |
| Major Players | Wuxi Lead Intelligent Equipment, Yinghe Technology, Dürr, Hitachi High-Tech, Manz |
Battery Manufacturing Equipment Market Segmentation
Chemistry
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
Machine Type
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
Automation Level
- Fully Automatic
- Semi-automatic
- Manual
End User
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Battery Manufacturing Equipment Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Gigafactory Capacity Build-Out Keeps Demand for Battery Manufacturing Equipment High
- Government Incentives Are Localizing Battery Manufacturing Equipment Demand
- Restraints
- Overcapacity and Project Cancellations Reduce Battery Manufacturing Equipment Orders
- High Capital Costs and Slow Yield Ramp-Up Challenge Battery Manufacturing Equipment Buyers
- Market Opportunities
- Dry Electrode and Solid-State Equipment Open a Next-Generation Revenue Pool
- Formation, Testing, and Inline Inspection Create a Quality-Driven Revenue Pool
- Drivers
- Global Battery Manufacturing Equipment Market Outlook, 2020–2033
- Global Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- Global Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- Global Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- Global Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- Global Battery Manufacturing Equipment Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- North America Battery Manufacturing Equipment Market Outlook, 2020–2033
- North America Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- North America Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- North America Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- North America Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- North America Battery Manufacturing Equipment Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- United States Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- United States Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- United States Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Canada Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Canada Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Canada Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Canada Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- North America Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Europe Battery Manufacturing Equipment Market Outlook, 2020–2033
- Europe Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- Europe Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- Europe Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- Europe Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- Europe Battery Manufacturing Equipment Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Germany Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Germany Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Germany Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Hungary Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Hungary Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Hungary Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Hungary Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Poland Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Poland Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Poland Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Poland Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Spain Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Spain Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Spain Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Spain Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Europe Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Asia Pacific Battery Manufacturing Equipment Market Outlook, 2020–2033
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- China Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- China Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- China Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- South Korea Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- South Korea Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- South Korea Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- South Korea Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Japan Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Japan Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Japan Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Japan Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Asia Pacific Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Latin America Battery Manufacturing Equipment Market Outlook, 2020–2033
- Latin America Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- Latin America Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- Latin America Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- Latin America Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- Latin America Battery Manufacturing Equipment Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Mexico Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Mexico Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Mexico Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Mexico Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Brazil Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Brazil Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Brazil Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Brazil Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Chile Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Chile Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Chile Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Chile Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Argentina Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Argentina Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Argentina Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Argentina Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Latin America Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, 2020–2033
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by Machine Type, Value (US$ Billion), 2020–2033
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by Automation Level, Value (US$ Billion), 2020–2033
- Fully Automatic
- Semi-automatic
- Manual
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Saudi Arabia Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Saudi Arabia Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Saudi Arabia Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- United Arab Emirates Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- United Arab Emirates Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- United Arab Emirates Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- United Arab Emirates Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Morocco Battery Manufacturing Equipment Market Outlook, by Chemistry, 2020–2033
- Morocco Battery Manufacturing Equipment Market Outlook, by Machine Type, 2020–2033
- Morocco Battery Manufacturing Equipment Market Outlook, by Automation Level, 2020–2033
- Morocco Battery Manufacturing Equipment Market Outlook, by End User, 2020–2033
- Middle East & Africa Battery Manufacturing Equipment Market Outlook, by Chemistry, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Wuxi Lead Intelligent Equipment
- Yinghe Technology
- Dürr
- Hitachi High-Tech
- Manz
- Schuler
- Bühler Group
- Andritz
- Hanwha Machinery
- PNT Group
- TMAX
- Siemens
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Chemistry
- Lithium-ion
- Solid-state
- Sodium-ion
- Lead-acid & Nickel-based
Machine Type
- Mixing
- Coating & Drying
- Calendering
- Slitting
- Stacking & Winding
- Assembly & Filling
- Formation & Testing
Automation Level
- Fully Automatic
- Semi-automatic
- Manual
End User
- Automotive
- Energy Storage Systems
- Consumer Electronics
- Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The battery manufacturing equipment market is valued at US$ 18.02 billion in 2026, led by lithium-ion lines for electric vehicles.
The market is projected to reach US$ 26.06 billion by 2033, growing at a 5.4% CAGR and adding US$ 8.04 billion.
Formation & Testing is growing fastest at a 12.5% CAGR through 2033, driven by higher quality demands and longer cell aging.
North America is growing fastest at a 12.2% CAGR through 2033, driven by federal incentives and new gigafactories.
Asia Pacific holds the largest share at 54.7% in 2026, supported by China's dominant cell production and leading equipment makers.
Related Reports
Fuel Cell Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Fuel cell market to reach US$ 21.6 billion by 2033 at 17.0% CAGR. Explore technologies, applications, regions and key companies.
Solid-state Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Solid-state battery market to reach US$ 11.7 billion by 2033 at 36.9% CAGR. Explore technologies, applications, regions and key companies.
Perovskite Photovoltaics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Perovskite photovoltaics market to reach US$ 4.8 billion by 2033 at 38.1% CAGR. Explore technologies, regional trends and key companies.
Microgrid Monitoring Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Microgrid monitoring systems market to reach US$ 5.5 billion by 2033 at 14.0% CAGR. Explore components, regional trends and key companies.
Carbon Dioxide Utilization Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Carbon dioxide utilization market to reach US$ 21.6 billion by 2033 at 10.41% CAGR. Explore applications, regions and key companies.
Big Data Analytics in Oil & Gas Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Oil & gas big data analytics market to reach US$ 30.0 billion by 2033 at 12.9% CAGR. Explore segments, regions and key companies.