


Big Data Analytics in Oil & Gas Market
Big Data Analytics in Oil & Gas Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Big Data Analytics in Oil & Gas Market Size and Trend Analysis
How Large Is the Oil and Gas Data Analytics Opportunity?
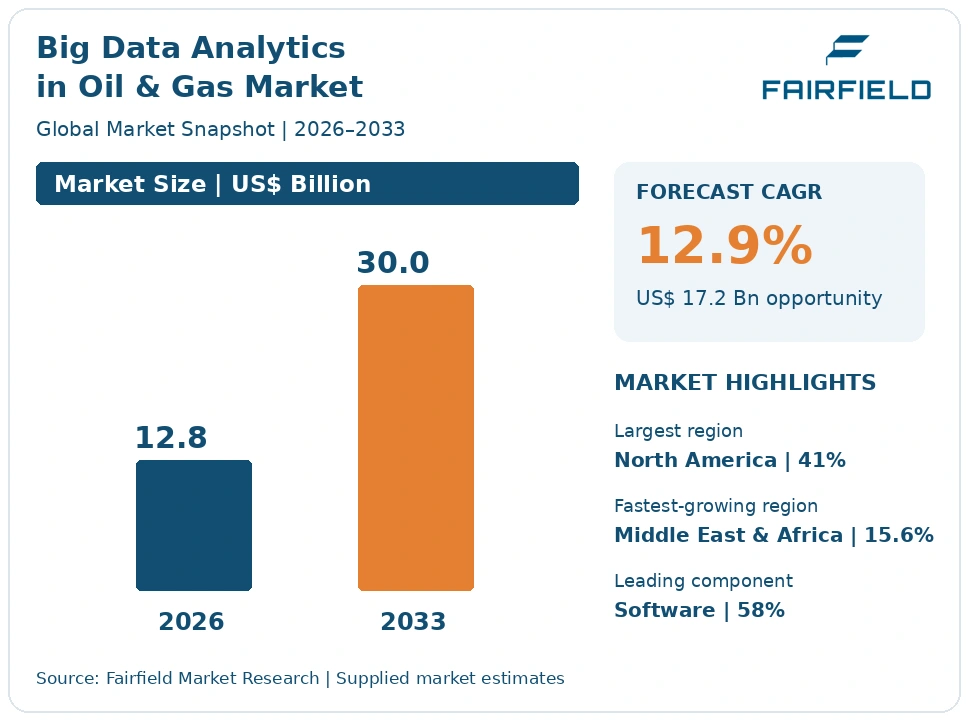
The global Big Data Analytics in Oil & Gas market size is expected to be valued at US$ 12.8 billion in 2026 and projected to reach US$ 30.0 billion by 2033, growing at a CAGR of 12.9% between 2026 and 2033.
Between 2020 and 2025 the market grew at about 9.6% a year, rising from roughly US$ 7.2 billion to US$ 11.4 billion, held back by the capital retrenchment that followed the price collapse of 2020. Growth accelerates from 2026 for three reasons. New methane measurement and reporting obligations in the European Union and the United States create continuous data workloads that did not previously exist. Real-time operations centres have proved measurable savings in drilling and production. Finally, the OSDU Data Platform specification lowers the cost of moving subsurface data between vendors, which makes larger analytics programmes financially defensible.
Key Report Takeaways
- By Component: Software held 58% share in 2026, while Services are projected to expand at a 14.1% CAGR through 2033, as operators hire outside teams to integrate historian data and build models they cannot staff internally.
- By Deployment Mode: On-Premise systems held 48% share in 2026, while Cloud deployment is projected to grow at a 16.4% CAGR through 2033, driven by seismic reprocessing and simulation workloads that need elastic compute for short periods.
- By Application: Production Optimization held 21% share in 2026, while Emissions Monitoring and Reporting is projected to advance at an 18.9% CAGR through 2033, following measurement and leak detection obligations in major producing jurisdictions.
- By Value Chain Segment: Upstream held 52% share in 2026, while Midstream is projected to rise at a 13.9% CAGR through 2033, reflecting pipeline integrity analytics and security directives that changed how operational data is handled.
- By Geography: North America held 41% revenue share in 2026, while Middle East & Africa is projected to record a 15.6% CAGR through 2033, as national oil companies fund large digital programmes.
Global Big Data Analytics in Oil & Gas Market Trends and Insights
Drivers Impact Analysis
Two developments explain most of the incremental analytics spending across the hydrocarbon value chain through 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Methane measurement, reporting and leak detection obligations | High | Europe, North America | Short term ≤2 years |
| Proven savings from real-time drilling and production operations centres | High | Global | Medium term 2–4 years |
Methane Rules Are Creating Continuous Measurement Workloads for Oil and Gas Analytics
Methane regulation has become the clearest new source of analytics demand in the sector. Operators must now detect, quantify, reconcile and report emissions across thousands of dispersed sites, which turns an occasional engineering exercise into a continuous data pipeline. That pipeline needs ingestion from fixed sensors, aerial and satellite surveys and handheld surveys, reconciliation against production records, and auditable retention, all of which sit squarely in the analytics budget rather than the field operations budget.
The mechanism is compliance exposure. The European Union methane regulation for the energy sector imposes measurement, reporting and leak detection and repair duties that extend to imported volumes, and the US Environmental Protection Agency oil and gas methane standards impose similar obligations domestically. Because penalties and market access depend on defensible numbers, operators buy quantification models, reconciliation tooling and verification workflows rather than simple spreadsheets, and they buy them for every asset.
Real-Time Operations Centres Convert Drilling and Production Data Into Measurable Savings
Demonstrated cost savings from real-time operations centres are the second major driver of spending. When an operator can see bit performance, torque and drag, equipment vibration and artificial lift behaviour as they happen, it shortens well delivery times and avoids unplanned deferment. Those gains are measured in days saved and barrels not lost, which makes the analytics investment easy to defend inside a disciplined capital process.
The causal chain is straightforward. High-rate sensor data from drilling rigs, electric submersible pumps and rotating equipment flows to a central centre where models flag deviations before failure. Predictive maintenance on compressors and pumps reduces unplanned downtime, while drilling optimisation reduces non-productive time on each well. Refinery yield and energy optimisation applies the same approach downstream, where small percentage gains on large throughput produce substantial annual value and justify continued platform investment.
Restraints Impact Analysis
Two structural constraints limit how quickly operators convert data into deployed analytics.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Siloed historians, incompatible vendor formats and poor field data quality | High | Global | Long term ≥4 years |
| Operational technology security constraints combined with capital discipline | Medium | North America, Europe | Medium term 2–4 years |
Siloed Historians and Weak Field Data Quality Inflate Oil and Gas Analytics Budgets
Data condition, not algorithm quality, is the main reason analytics projects in this sector overrun. Operators typically hold decades of information across separate process historians, well files, maintenance systems and proprietary subsurface formats, each with its own tag naming and time base. Teams therefore spend most of a project period on extraction, mapping and cleaning, which delays benefit realisation and makes executives sceptical of the next proposal.
The cost source is specific. Legacy field instrumentation often lacks reliable metadata, calibration history and consistent units, so readings cannot be trusted without reconciliation against physical models. Tag dictionaries differ between platforms built by different contractors in different decades. Subsurface interpretation data frequently sits in vendor-specific formats that require licensed software to read. Each of these adds integration labour, and that labour, not software licensing, usually dominates the total programme cost.
Operational Technology Security Rules and Capital Discipline Slow Cloud Analytics Projects
Security requirements and investment screening together restrain the pace of cloud analytics adoption. Operational technology networks that control wells, compressors and pipelines are deliberately segregated, and moving data out of them requires architecture review, one-way gateways and formal approval. Meanwhile, capital allocation committees favour projects with short, provable payback, so analytics proposals compete against drilling and maintenance work with clearer returns.
The underlying causes are regulatory and organisational. TSA pipeline security directives and NIST cybersecurity guidance shape how operational data may be moved, stored and accessed, which adds design effort and recurring assurance costs to any cloud programme. Pipeline operators must also preserve integrity management records under PHMSA rules. At the same time, there is a persistent shortage of staff who understand both petrotechnical work and data science, so even approved projects wait for scarce people.
Market Opportunities
Emissions Measurement and Verification Services Open a Recurring Oil and Gas Data Revenue Pool
Emissions measurement, reporting and verification is emerging as a recurring revenue pool distinct from traditional project analytics. Reporting obligations repeat every year, require reconciliation between site-level measurement and corporate disclosure, and increasingly demand third-party verification. That combination supports annual subscription and managed-service pricing rather than one-off licence sales, and it applies to operators of every size, including those without internal data teams.
Analytics vendors, measurement technology firms and engineering service companies can capture this pool together, since it needs sensors, quantification models and assurance workflows. Demand comes from upstream producers, gathering and processing operators and liquefied natural gas exporters whose buyers now ask for emissions intensity data. The European Union methane regulation supports the pool by extending reporting expectations along the import chain, which pushes the requirement toward producers in exporting countries as well.
OSDU-Aligned Subsurface Platforms Unlock Reprocessing of Legacy Seismic and Well Data
A large revenue pool sits in subsurface data that operators already own but cannot use efficiently. Decades of seismic surveys, well logs and interpretation projects are locked in proprietary formats and tape archives. Once that material is moved onto a standards-aligned platform, it can be reprocessed with modern imaging and machine learning methods, improving prospect evaluation and reducing the need for new acquisition in mature basins.
Cloud providers, subsurface software vendors and specialist data management firms are positioned to capture this work, with national oil companies and mature-basin operators forming the core demand. The OSDU open subsurface data universe specification supports it directly by defining a common data platform, which reduces the switching costs that previously discouraged migration. Carbon storage site screening uses the same datasets, which gives operators a second reason to fund the migration.
Segment Analysis
By Component: Software Leads Revenue While Services Expand at the Quickest Pace
Software accounted for 58% of 2026 revenue, the leading component, because data platforms, historians, interpretation tools and analytics applications form the recurring core of every programme. Licence and subscription spending is also easier to approve than headcount. Services grow fastest at a 14.1% CAGR to 2033, since operators need outside help to integrate historian data, build domain models and run platforms they cannot staff internally, a gap widened by the shortage of combined petrotechnical and data science skills. Hardware and infrastructure, including edge gateways and on-site compute for high-rate sensor data, contributes a smaller but stable share. The business implication is that vendors increasingly lead with service engagements to prove value, then convert successful pilots into multi-year software agreements across additional assets and basins.
By Deployment Mode: On-Premise Systems Retain Scale as Cloud Platforms Grow Quickest
On-Premise deployment held 48% of 2026 revenue because control-adjacent data, including real-time process historian streams, remains inside segregated operational technology networks for security and latency reasons. Many national oil companies also face data residency requirements. Cloud is the fastest-growing mode at a 16.4% CAGR, driven by seismic reprocessing, reservoir simulation and large model training workloads that need very large compute for short periods and would be uneconomic to own. Hybrid architectures, with edge processing at the wellsite and heavy analytics in the cloud, are becoming standard for new programmes. The consequence for vendors is that cloud capability alone no longer wins deals; buyers now evaluate the security architecture connecting plant networks to hosted platforms as closely as they evaluate the analytics itself.
By Application: Production Optimization Leads While Emissions Monitoring Accelerates Fastest
Production Optimization held 21% of 2026 revenue, the largest application share, because artificial lift management, well surveillance and deferment reduction deliver cash benefits that are easy to measure against a declining base. Emissions Monitoring and Reporting is the fastest-growing application at an 18.9% CAGR, as measurement, quantification and leak detection obligations convert an occasional survey into a continuous workload. Exploration and subsurface analytics, drilling optimisation, predictive maintenance for rotating equipment, pipeline integrity and leak detection, refinery and process optimisation, and trading and supply chain analytics make up the balance. The practical implication is that emissions workloads increasingly share infrastructure with production surveillance, so operators prefer platforms that can host both rather than buying a standalone compliance tool for each regulation.
By Value Chain Segment: Upstream Dominates Spending While Midstream Analytics Grows Fastest
Upstream represented 52% of 2026 revenue, reflecting the sheer volume of subsurface, drilling and production data and the high value of each decision made with it. A single development well decision can justify an entire analytics programme. Midstream grows fastest at a 13.9% CAGR, driven by pipeline integrity analytics, leak detection, compressor station monitoring and the record-keeping that integrity management rules require. Downstream spending concentrates on refinery yield, energy optimisation, blending and asset reliability, where gains of even a fraction of a percent across large throughput produce meaningful annual savings and recur every operating year. For vendors, the distinction shapes go-to-market design: upstream buyers want petrotechnical depth and subsurface credibility, while midstream and downstream buyers prioritise reliability engineering, regulatory evidence and integration with existing control systems.
Geography Analysis
Which Region Is Leading the Big Data Analytics in Oil & Gas Market?
North America leads the oil and gas analytics market with 41% revenue share in 2026 and a projected 12.0% CAGR to 2033. The United States supplies most of the value, with Canada adding oil sands and gas processing demand. Unconventional development is the central cause: shale operators drill many similar wells, generate dense comparable datasets, and compete on cost per barrel, which rewards statistical optimisation more than anywhere else. Methane standards from the US Environmental Protection Agency add compliance workloads across a highly fragmented operator base. Pipeline security directives from the TSA and integrity rules from PHMSA push midstream firms toward structured data management. The region also hosts the main oilfield service and cloud vendors, which shortens deployment cycles. The change ahead is consolidation of operator-specific platforms onto shared industry data standards.
Europe Ties Oil and Gas Analytics Spending to Methane Rules and Refinery Efficiency
Europe held 19% of 2026 revenue and should grow at 11.8% annually through 2033. Norway, the United Kingdom, the Netherlands, Germany and Italy account for most spending, split between offshore production and a large refining and petrochemical base. Regulation is the dominant driver here. The methane regulation for the energy sector requires measurement, reporting and leak detection, and its reach into imported volumes makes emissions data a commercial issue for traders as well as producers. Mature offshore fields on the Norwegian continental shelf rely on reservoir and integrity analytics to extend economic life, while refiners use energy optimisation to manage high power and carbon costs. Carbon capture and storage projects reuse subsurface datasets, giving operators an additional reason to modernise their data platforms.
Asia Pacific Builds Analytics Demand Around Refining Capacity and National Oil Companies
Asia Pacific accounted for 20% of 2026 revenue and is forecast to grow at 13.9% a year through 2033. China, India, Malaysia, Indonesia and Australia drive the market. The structure of demand differs from other regions: refining and petrochemical capacity is large and still expanding, so downstream yield, energy optimisation and reliability analytics take a bigger share of budgets. State-owned producers in China, India and Malaysia run centralised digital programmes that standardise platforms across many assets at once. Australia concentrates spending on liquefied natural gas facilities, where plant reliability and emissions intensity both matter to buyers. Data residency rules and preference for domestic cloud providers shape deployment choices, and the main constraint is uneven data quality across older onshore fields with limited instrumentation.
Latin America Concentrates Oil and Gas Analytics in Deepwater and Unconventional Basins
Latin America represented 7% of 2026 revenue with an expected 12.4% CAGR through 2033. Brazil dominates, driven by pre-salt deepwater developments where a single subsea intervention is expensive enough to justify extensive predictive maintenance and flow assurance analytics. Argentina adds unconventional activity in the Vaca Muerta formation, which is generating the kind of repeatable well data that supports drilling optimisation. Guyana, Colombia and Mexico contribute smaller but growing programmes. Barriers are significant: currency volatility complicates multi-year software contracts, connectivity to remote offshore and basin locations can be limited, and specialist data engineering talent is scarce. The clearest opportunity is managed analytics delivered from regional operations centres, which spreads scarce expertise across several operators instead of requiring each to build a team.
Which Region Is Growing Fastest in the Big Data Analytics in Oil & Gas Market?
Middle East & Africa is growing fastest at a 15.6% CAGR between 2026 and 2033, from 13% revenue share in 2026. Saudi Arabia, the United Arab Emirates, Qatar, Kuwait, Oman, Nigeria and Angola drive the expansion. National oil companies in the Gulf fund large, centrally directed digital programmes covering reservoir management, plant reliability and integrated operations centres, and they can commit capital on longer horizons than listed operators. Gas export projects add emissions intensity reporting, since buyers increasingly ask for verified figures. African producers face harder conditions: ageing instrumentation, security risks at remote sites and limited local data engineering capacity. The decisive change is the move from isolated pilot projects to enterprise data platforms, which makes analytics spending recurring rather than episodic.
Competitive Landscape
The oil and gas analytics market is moderately concentrated, and unusually layered. Oilfield service companies, enterprise software vendors, hyperscale cloud providers, industrial automation suppliers and consulting firms all sell into the same budgets, often on the same project. SLB, Halliburton Company and Baker Hughes Company anchor the subsurface and operations side because they own the domain models and the measurement devices that generate the data. Microsoft Corporation, Amazon Web Services, Inc., Google LLC and Oracle Corporation supply the underlying platforms, while International Business Machines Corporation, Accenture plc, SAP SE, AVEVA Group Limited, Honeywell International Inc., Siemens AG and Emerson Electric Co. address integration, operations technology and enterprise workflows. No single firm covers the full chain, so partnership is the normal structure.
Competition turns on domain credibility rather than algorithms. Buyers weigh proven petrotechnical and process knowledge, the ability to connect to legacy historians and proprietary subsurface formats, alignment with the OSDU data platform specification, security architecture acceptable under TSA directives and NIST guidance, and willingness to price against measured outcomes. New entrants arrive from two directions: emissions measurement and quantification specialists, and analytics firms applying generic industrial machine learning to rotating equipment.
Strategic activity follows consistent patterns rather than isolated moves. Service companies have been repositioning proprietary interpretation suites as open, cloud-hosted platforms. Cloud providers build energy-specific reference architectures and partner rather than compete with domain vendors. Automation suppliers extend plant historians upward into analytics. Consulting firms build dedicated energy data practices to capture integration work that software licences alone cannot deliver.
Big Data Analytics in Oil & Gas Industry Leaders
- SLB
- Halliburton Company
- Baker Hughes Company
- International Business Machines Corporation
- Microsoft Corporation
Recent Industry Developments
2024: The European Union adopted Regulation (EU) 2024/1787 on methane emissions reduction in the energy sector – it established measurement, reporting and leak detection and repair duties that reach imported volumes, creating continuous data obligations for producers and traders.
December 2023: The US Environmental Protection Agency finalised new source performance standards OOOOb and emission guidelines OOOOc for the oil and natural gas sector – these obligations converted periodic leak surveys into sustained monitoring and quantification workloads.
July 2021: The US Transportation Security Administration issued its second pipeline security directive for critical pipeline owners and operators – it set architecture and incident response expectations that now shape how midstream operational data may be moved and stored.
2020: The Open Group released the first production version of the OSDU Data Platform – the specification gave the industry a common subsurface data model and reduced the switching costs that had discouraged migration from proprietary formats.
Big Data Analytics in Oil & Gas Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 12.8 Billion |
| Market Size 2033 | US$ 30.0 Billion |
| CAGR 2026–2033 | 12.9% |
| Absolute Dollar Opportunity | US$ 17.2 Billion |
| Largest Market | North America, 41% share in 2026 |
| Fastest-Growing Market | Middle East & Africa, 15.6% CAGR |
| Market Concentration | Medium |
| Major Players | SLB, Halliburton Company, Baker Hughes Company, Microsoft Corporation |
This report covers data platforms and analytics applied across the hydrocarbon value chain, counting software, platforms, supporting hardware and professional and managed services together. Included scope spans subsurface interpretation, drilling and production optimisation, predictive maintenance, pipeline integrity, refinery optimisation, emissions analytics and trading applications. Physical sensors, drilling equipment and process plant are excluded. The base year is 2025, and the forecast period runs from 2026 to 2033, with values in US$ Billion.
Big Data Analytics in Oil & Gas Market Segmentation
Component
- Software
- Services
- Hardware and Infrastructure
Deployment Mode
- On-Premise
- Cloud
- Hybrid
Application
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
Value Chain Segment
- Upstream
- Midstream
- Downstream
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Big Data Analytics in Oil & Gas Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Methane Rules Are Creating Continuous Measurement Workloads for Oil and Gas Analytics
- Real-Time Operations Centres Convert Drilling and Production Data Into Measurable Savings
- Restraints
- Siloed Historians and Weak Field Data Quality Inflate Oil and Gas Analytics Budgets
- Operational Technology Security Rules and Capital Discipline Slow Cloud Analytics Projects
- Market Opportunities
- Emissions Measurement and Verification Services Open a Recurring Oil and Gas Data Revenue Pool
- OSDU-Aligned Subsurface Platforms Unlock Reprocessing of Legacy Seismic and Well Data
- Drivers
- Global Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- Global Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- Global Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- Global Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- Global Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- Global Big Data Analytics in Oil & Gas Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- North America Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- North America Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- North America Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- North America Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- North America Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- North America Big Data Analytics in Oil & Gas Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- United States Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- United States Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- United States Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Canada Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Canada Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Canada Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Canada Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- North America Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Europe Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Norway Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Norway Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Norway Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Norway Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- United Kingdom Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- United Kingdom Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- United Kingdom Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- United Kingdom Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Netherlands Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Netherlands Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Netherlands Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Netherlands Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Germany Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Germany Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Germany Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Germany Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Italy Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Italy Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Italy Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Italy Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Europe Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- China Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- China Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- China Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- India Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- India Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- India Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- India Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Malaysia Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Malaysia Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Malaysia Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Malaysia Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Indonesia Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Indonesia Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Indonesia Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Indonesia Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Australia Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Australia Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Australia Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Australia Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Asia Pacific Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Latin America Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Brazil Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Brazil Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Brazil Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Argentina Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Argentina Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Argentina Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Argentina Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Guyana Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Guyana Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Guyana Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Guyana Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Colombia Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Colombia Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Colombia Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Colombia Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Mexico Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Mexico Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Mexico Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Mexico Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Latin America Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, 2020–2033
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Software
- Services
- Hardware and Infrastructure
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, Value (US$ Billion), 2020–2033
- On-Premise
- Cloud
- Hybrid
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, Value (US$ Billion), 2020–2033
- Upstream
- Midstream
- Downstream
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Saudi Arabia Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Saudi Arabia Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Saudi Arabia Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- United Arab Emirates Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- United Arab Emirates Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- United Arab Emirates Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- United Arab Emirates Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Qatar Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Qatar Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Qatar Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Qatar Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Kuwait Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Kuwait Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Kuwait Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Kuwait Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Oman Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Oman Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Oman Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Oman Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Nigeria Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Nigeria Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Nigeria Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Nigeria Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Angola Big Data Analytics in Oil & Gas Market Outlook, by Component, 2020–2033
- Angola Big Data Analytics in Oil & Gas Market Outlook, by Deployment Mode, 2020–2033
- Angola Big Data Analytics in Oil & Gas Market Outlook, by Application, 2020–2033
- Angola Big Data Analytics in Oil & Gas Market Outlook, by Value Chain Segment, 2020–2033
- Middle East & Africa Big Data Analytics in Oil & Gas Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- SLB
- Halliburton Company
- Baker Hughes Company
- International Business Machines Corporation
- Microsoft Corporation
- Amazon Web Services, Inc.
- Google LLC
- Oracle Corporation
- SAP SE
- Accenture plc
- Siemens AG
- Honeywell International Inc.
- AVEVA Group Limited
- Emerson Electric Co.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Component
- Software
- Services
- Hardware and Infrastructure
Deployment Mode
- On-Premise
- Cloud
- Hybrid
Application
- Exploration and Subsurface Analytics
- Drilling Optimization
- Production Optimization
- Predictive Maintenance
- Pipeline Integrity and Leak Detection
- Refinery and Process Optimization
- Emissions Monitoring and Reporting
- Trading and Supply Chain Analytics
Value Chain Segment
- Upstream
- Midstream
- Downstream
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 12.8 billion in 2026, covering analytics software, data platforms, supporting infrastructure and related professional and managed services.
Revenue is projected to reach US$ 30.0 billion by 2033 at a 12.9% CAGR, representing US$ 17.2 billion of absolute dollar opportunity.
Production Optimization leads with 21% share in 2026, because well surveillance and artificial lift management deliver cash benefits that operators can measure directly.
Emissions Monitoring and Reporting grows fastest at an 18.9% CAGR, while Middle East & Africa leads regional growth at a 15.6% CAGR.
North America holds 41% share in 2026, and the market is moderately concentrated across service companies, cloud providers, automation suppliers and consulting firms.
Related Reports
Enhanced Oil Recovery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global enhanced oil recovery market is valued at US$46.5 billion in 2026, reaching US$58.9 billion by 2033, growing at a 3.43% CAGR
Biochar Gasification Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global biochar gasification market is valued at US$0.6 billion in 2026, reaching US$1.4 billion by 2033, growing at a 12.87% CAGR
AC-Coupled Energy Storage Inverter Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The AC-coupled energy storage inverter market is forecast to grow from US$ 4.2 billion in 2026 to US$ 10.5 billion by 2033 at a 13.99% CAGR.
Steam Turbine Aftermarket Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The Steam Turbine Aftermarket is projected to rise from US$ 4.56 billion in 2026 to US$ 6.29 billion by 2033 at a 4.7% CAGR. Explore key service trends.
Power EPC Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Power EPC Market is projected to rise from US$ 780.56 billion in 2026 to US$ 1,220.97 billion by 2033 at a 6.6% CAGR. Explore generation and project trends.
Port Electrification Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the port electrification market, valued at US$ 6.8 billion in 2026 and forecast to reach US$ 16.4 billion by 2033, growing at a 13.4% CAGR.