


Carbon Dioxide Utilization Market
Carbon Dioxide Utilization Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Carbon Dioxide Utilization Market Size and Trend Analysis
How Big Is the Carbon Dioxide Utilization Market in 2026?
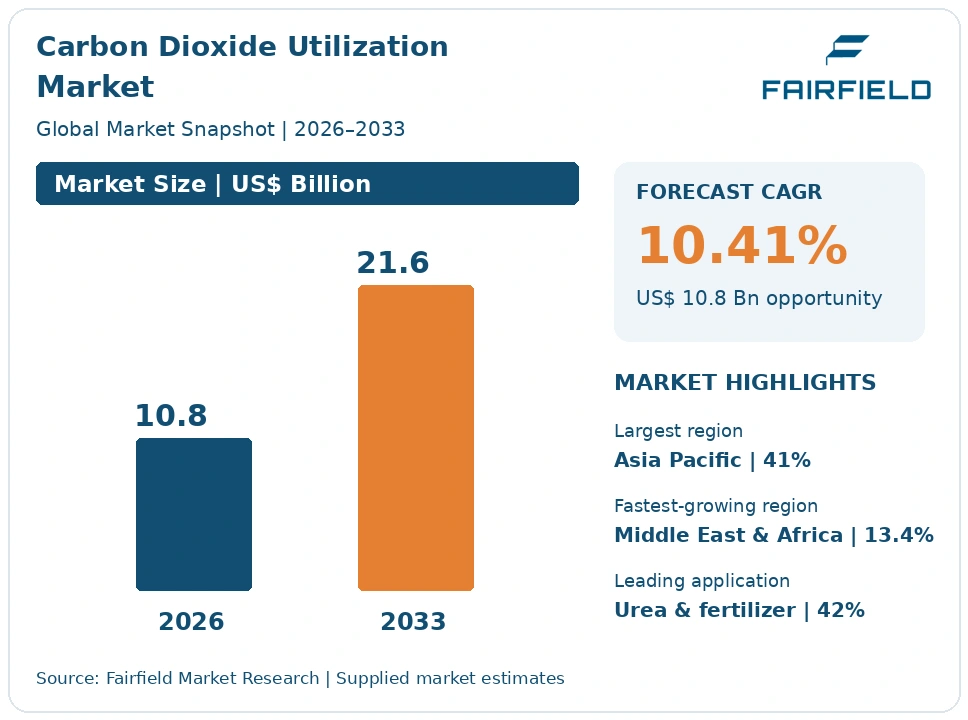
The global Carbon Dioxide Utilization market size is expected to be valued at US$ 10.8 billion in 2026 and projected to reach US$ 21.6 billion by 2033, growing at a CAGR of 10.41% between 2026 and 2033.
The market grew at roughly a 9.6% CAGR between 2020 and 2025, recovering from pandemic-era merchant carbon dioxide shortages and absorbing new ammonia-urea capacity in China, India and the Gulf states. Three forces shape the outlook. Conventional industrial demand, chiefly urea synthesis, enhanced oil recovery and beverage carbonation, still sets the baseline volume and the bulk of revenue. Carbon pricing under the European Union Emissions Trading System and the United States 45Q credit is now pulling capital toward routes that keep carbon chemically bound. Carbonate mineralisation in concrete is moving from demonstration to commercial supply. Growth should stay steady rather than explosive, because the largest uses are mature processes with slow replacement cycles.
Key Report Takeaways
- By Application: Urea & Fertilizer Synthesis held 42.0% share in 2026, while Construction Materials & Mineralization is projected to expand at an 18.9% CAGR through 2033, driven by procurement rules that reward lower-embodied-carbon concrete in public infrastructure.
- By CO2 Source: Ammonia & Hydrogen Plants held 38.0% share in 2026, while Direct Air Capture is projected to expand at a 24.5% CAGR through 2033, because atmospheric CO2 carries no fossil origin and simplifies product claims.
- By Conversion Route: Chemical Conversion held 48.0% share in 2026, while Electrochemical Conversion is projected to expand at a 23.8% CAGR through 2033, helped by falling renewable power prices and improved membrane electrode durability.
- By Carbon Retention Profile: Open-Cycle Utilization held 91.5% share in 2026, while Durable Utilization is projected to expand at a 19.8% CAGR through 2033, supported by certification rules that recognise carbon stored inside long-lived products.
- By Geography: Asia Pacific held 41.0% share in 2026, while Middle East & Africa is projected to expand at a 13.4% CAGR through 2033, reflecting new low-carbon ammonia complexes and large CO2 flood projects in the region.
Global Carbon Dioxide Utilization Market Trends and Insights
Drivers Impact Analysis
The following drivers have the strongest measurable effect on CO2 utilization demand through the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Nitrogen fertiliser output anchoring captive CO2 consumption | High | Asia Pacific, Middle East & Africa | Long term ≥4 years |
| Carbon pricing and tax credits rewarding durable CO2 use | Medium | Europe, North America | Medium term 2–4 years |
Nitrogen Fertiliser Output Anchors the Largest Block of CO2 Utilization Demand
Urea synthesis consumes more captured carbon dioxide than every emerging route combined, and it keeps the utilisation market large and stable. Ammonia plants strip CO2 from syngas and feed it directly into the urea reactor on the same site. Because global urea output sits near 190 million tonnes a year, this single application absorbs well over 100 million tonnes of CO2 annually. That captive demand is contracted, predictable and insensitive to climate policy.
The mechanism is agronomic rather than environmental. Rising nitrogen application rates in India, Indonesia and Brazil, combined with government fertiliser subsidies, keep urea capacity utilisation high. New ammonia-urea trains commissioned in Nigeria, Egypt and Saudi Arabia add captive CO2 consumption with every expansion. Methanol and salicylic acid synthesis follow the same captive logic, giving the carbon capture and utilization sector a revenue floor that does not depend on voluntary carbon markets.
Carbon Pricing and 45Q Credits Shift Capital Toward Durable CO2 Utilization
Carbon pricing is changing which utilisation routes attract investment, and it is lifting the value of projects that lock carbon into solid products. Allowance prices in the European Union Emissions Trading System have made avoided surrender obligations material for cement and lime producers. In the United States, the 45Q credit pays a defined per-tonne amount for qualified carbon utilisation, which converts a waste stream into a contracted revenue line for ethanol and ammonia operators.
The causal chain runs through compliance accounting. Revised Emissions Trading System rules allow an installation to deduct CO2 that becomes permanently chemically bound in a product, so a cement plant selling carbonated aggregate reduces its own liability. Regulation (EU) 2024/3012 adds a certification route for carbon stored in products. Together these instruments give CO2-based building materials a documented, auditable value that engineering estimates alone could never support.
Restraints Impact Analysis
Two structural constraints hold back faster conversion of captured carbon into higher-value products.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Credit and policy design favouring geological storage over utilisation | High | North America | Medium term 2–4 years |
| Unsettled life cycle accounting for net emission benefit | Medium | Europe, Asia Pacific | Long term ≥4 years |
Policy Design Favouring Geological Storage Caps Carbon Dioxide Utilization Returns
Utilisation projects earn less public support per tonne than storage projects, and that gap suppresses final investment decisions. The United States 45Q credit pays a lower rate for carbon utilisation than for secure geological storage from the same industrial source. A developer weighing a mineralisation plant against a saline aquifer injection well therefore starts from a structurally weaker revenue case, even when capital costs are comparable.
The cost source is specific rather than general. Utilisation requires purification to beverage or chemical grade, compression, liquefaction and road or rail distribution to dispersed customers, whereas a storage project pipes a single stream to one wellhead. Conditioning and logistics commonly add more cost per tonne than the capture step itself for small volumes. Where credit revenue is lower and delivered cost is higher, only applications with an existing product price, such as merchant carbon dioxide supply, clear the hurdle.
Unsettled Life Cycle Accounting Slows Buyer Acceptance of CO2-Derived Products
Buyers cannot always confirm that a utilisation route reduces net emissions, and that uncertainty delays procurement commitments. Converting CO2 into fuels or chemicals is energy intensive, and if the electricity or hydrogen input is fossil-derived the product can carry a higher footprint than the incumbent it replaces. Corporate purchasers and public tender authorities increasingly ask for evidence before paying a green premium.
The underlying cause is methodological. ISO 14067 and related life cycle assessment standards leave scope for different system boundaries, allocation methods and assumptions about counterfactual CO2 fate. Two credible assessments of the same carbonated concrete product can differ because one credits avoided cement and the other does not. Until boundary rules harden, auditors apply conservative assumptions, and the claimed benefit of many carbon dioxide recycling routes is discounted or rejected outright in reporting.
Market Opportunities
Carbonated Aggregate and Concrete Curing Open a Durable-Carbon Revenue Pool
Mineral carbonation is the clearest route to a utilisation product that stores carbon for centuries, and it opens a revenue pool that conventional gas sales cannot reach. Injecting CO2 into fresh concrete or reacting it with steel slag and recycled fines produces stable calcium and magnesium carbonates. Producers can then sell both the material and a verifiable storage attribute, creating two income streams from one process.
Ready-mix producers, precast manufacturers and aggregate recyclers are best placed to capture this. Demand comes from public infrastructure buyers applying embodied-carbon limits to tenders, and from developers chasing green building certification. Regulation (EU) 2024/3012 supports the model by recognising carbon storage in products within a certification framework, while national procurement rules in Canada and several United States states already set concrete carbon intensity thresholds for funded projects.
Certified Carbon Storage in Products Creates a Tradable Attribute for Utilisation Operators
Certification of stored carbon turns a technical claim into a sellable instrument, and that is a genuinely new revenue pool for utilisation operators. Historically a CO2 user sold only the physical product. Under emerging frameworks, an operator whose process holds carbon in a product for a qualifying period can issue a certified unit, sell it separately, and recover part of the capture and conditioning cost that the product price alone will not cover.
Polymer producers, carbonate mineral suppliers and specialty chemical firms with long-lived outputs stand to benefit most. Demand comes from compliance buyers managing Emissions Trading System exposure and from corporates with inventory-based climate targets. The European Union certification framework for carbon removals and carbon farming provides the legal architecture, while monitoring, reporting and verification practice borrowed from established crediting programmes supplies the operational detail.
Segment Analysis
By Application: Urea Synthesis Leads While Construction Materials Gain Momentum
Urea & Fertilizer Synthesis held 42.0% of the CO2 utilization market in 2026, because ammonia plants generate and consume carbon dioxide on the same site with no transport cost. Enhanced oil recovery followed at 21.0%, concentrated in mature United States and Middle East fields. Food & Beverage accounted for 14.0%, covering carbonation, modified atmosphere packaging and cryogenic chilling. Other Industrial Uses, including welding shield gas, fire suppression, water treatment, greenhouse enrichment and metalworking, together represented 13.0%.
Construction Materials & Mineralization is the fastest-growing application at an 18.9% CAGR through 2033, from a small 4.0% base. Growth reflects embodied-carbon limits in public procurement and the fact that carbonation improves early compressive strength. The business implication is a widening split: conventional applications supply the revenue, while mineralisation supplies the growth narrative and the only durable carbon claim.
By CO2 Source: Ammonia Plants Dominate Supply as Direct Air Capture Accelerates
Ammonia & Hydrogen Plants supplied 38.0% of utilised carbon dioxide in 2026, because steam methane reforming produces a concentrated, low-cost stream that needs minimal separation. Ethanol & Fermentation contributed 22.0%, prized for near-pure CO2 that reaches beverage grade cheaply. Natural Gas Processing added 18.0%, Power Generation flue gas 12.0%, and Cement & Steel 9.5%, where dilute streams raise conditioning costs sharply.
Direct Air Capture is the fastest-growing source at a 24.5% CAGR through 2033, despite holding only 0.5% share. Atmospheric CO2 avoids questions about fossil origin, which matters for synthetic fuel and food-grade claims in Europe and North America. The practical implication is that source choice is becoming a marketing variable, not only an engineering one, and purity premiums are starting to appear in merchant carbon dioxide contracts.
By Conversion Route: Chemical Conversion Holds Scale While Electrochemical Routes Scale Fastest
Chemical Conversion accounted for 48.0% of the market in 2026, driven almost entirely by urea and methanol synthesis using established thermocatalytic reactors. Non-Conversion physical use followed closely at 44.0%, covering enhanced oil recovery, carbonation, inerting and refrigeration, where the molecule is used unchanged. Mineral Carbonation held 4.5% and Biological Conversion, including algae cultivation and microbial fermentation, held 2.0%.
Electrochemical Conversion is the fastest-expanding route at a 23.8% CAGR through 2033 from a 1.5% base. Falling renewable electricity prices, better gas diffusion electrodes and improved membrane durability have cut cell degradation rates materially. Pilot units now produce carbon monoxide, formic acid and ethylene at kilogram scale. For the broader carbon capture and utilization sector, electrochemistry matters because it couples CO2 conversion directly to intermittent renewable supply without an intermediate hydrogen plant.
By Carbon Retention Profile: Open-Cycle Use Dominates While Durable Utilization Grows Quickest
Open-Cycle Utilization represented 91.5% of the market in 2026, a figure that deserves emphasis. In enhanced oil recovery, beverage carbonation, greenhouse enrichment, welding and urea applied to fields, the carbon returns to the atmosphere within days to months. These uses are commercially valuable and industrially essential, but they deliver no durable climate benefit on their own. Semi-Durable Utilization, mainly polyols, polycarbonates and other long-lived polymers, held 7.0% and retains carbon for years to decades.
Durable Utilization is the fastest-growing profile at a 19.8% CAGR through 2033 from 1.5% share, covering carbonated concrete, synthetic aggregate and stable carbonate minerals. The implication for strategy teams is direct: buyers paying for climate performance are concentrating spend in a thin slice of the market, so revenue leadership and credibility leadership now sit in different segments.
Geography Analysis
North America Converts Ethanol and Gas-Processing CO2 Into Enhanced Oil Recovery Volume
North America held 26.5% of the CO2 utilization market in 2026 and is expected to grow at a 9.2% CAGR through 2033. The United States dominates, supported by the largest CO2 pipeline network in the world and decades of CO2 flooding in the Permian Basin and Gulf Coast fields. Canada adds capacity through gas processing and fertiliser production in Alberta and Saskatchewan.
Ethanol plants in the Midwest supply high-purity carbon dioxide at low separation cost, which feeds both oil recovery and merchant food-grade demand. The 45Q credit shapes project selection across the region. The main change ahead is state-level procurement: concrete carbon intensity thresholds in California, Colorado and New Jersey are creating the first sizeable regulated demand for mineralised products outside pilot programmes.
Europe Steers Carbon Dioxide Utilization Toward Certified and Durable End Uses
Europe accounted for 17.0% of global utilisation value in 2026 and is forecast to expand at a 10.8% CAGR to 2033. Germany, the Netherlands, Norway and France lead activity. Regional demand is unusual because policy, not oilfield economics, sets the direction. The Emissions Trading System gives installations a direct financial reason to prove that carbon is permanently bound in a product.
Regulation (EU) 2024/3012 and the European Commission industrial carbon management agenda together push operators toward auditable, long-duration end uses. Regional fertiliser capacity has contracted under high gas prices, trimming conventional captive demand. The offsetting change is construction: cement producers facing free-allocation phase-out are testing carbonated aggregate and recycled concrete fines as a compliance tool rather than a sustainability gesture.
Which Region Leads the Carbon Dioxide Utilization Market?
Asia Pacific leads the carbon dioxide utilization market with 41.0% share in 2026, growing at a 10.4% CAGR through 2033. The position rests on fertiliser manufacturing scale rather than climate policy. China, India and Indonesia operate the largest concentration of ammonia-urea complexes anywhere, and each tonne of urea consumes captured carbon dioxide inside the plant boundary.
China also hosts substantial merchant gas demand from electronics, food processing and welding, while Japan and South Korea supply high-purity gas for semiconductor and beverage customers. Coal-based ammonia in China produces concentrated CO2 streams that are cheap to recover. The change worth watching is domestic emissions trading expansion in China to cement and steel, which would create the first large regional pull toward mineralised utilisation products.
Latin America Builds Utilisation Demand From Beverages, Bioethanol and Imported Fertiliser
Latin America held 5.0% of the market in 2026 with a projected 9.5% CAGR to 2033. Brazil dominates regional activity through sugarcane ethanol, which yields fermentation CO2 at high purity, and through a large beverage carbonation industry. Mexico, Argentina and Colombia contribute merchant gas demand for food processing, water treatment and metal fabrication.
The main barrier is structural. The region imports most of its nitrogen fertiliser, so it lacks the captive urea-linked CO2 consumption that anchors demand elsewhere, and liquefaction and distribution infrastructure is thin outside major cities. Carbon pricing remains limited. The opportunity lies in bioethanol: fermentation streams are already concentrated, so recovery costs are low, and Brazil could supply certified biogenic CO2 to food and chemical buyers.
Which Region Is Growing Fastest in the Carbon Dioxide Utilization Market?
Middle East & Africa is growing fastest in the carbon dioxide utilization market, at a 13.4% CAGR through 2033 from a 10.5% share in 2026. New ammonia-urea complexes in Saudi Arabia, Egypt, Nigeria and Qatar add captive CO2 consumption with each commissioning, and low-cost gas keeps these plants running at high utilisation rates.
Large CO2 injection projects in the United Arab Emirates and Saudi Arabia support enhanced oil recovery at commercial scale, backed by national oil company capital rather than subsidy. Barriers remain real: water scarcity limits some conversion routes, grid carbon intensity weakens life cycle claims, and much of Africa lacks industrial gas distribution. The clearest opportunity is export-oriented low-carbon ammonia, which pairs capture with immediate on-site utilisation.
Competitive Landscape
The carbon dioxide utilization market is moderately concentrated, and the structure differs sharply between its conventional and emerging halves. Merchant industrial gas supply is dominated by a small group of global producers with dense pipeline, liquefaction and bulk delivery networks, and that segment behaves like a mature oligopoly with regional pricing power. Fertiliser-linked utilisation is captive and therefore barely contested, since ammonia producers consume their own carbon dioxide internally. Mineralisation, electrochemical conversion and biological routes remain fragmented, populated by venture-funded specialists and licensing-led businesses that have not yet reached commodity scale.
Vendors compete on delivered cost per tonne, purity and reliability of supply rather than on technology novelty in the conventional segment. Food-grade and beverage-grade certification, proximity to the customer, and the ability to guarantee supply during planned ammonia plant turnarounds decide contracts. In emerging routes the basis of competition shifts to verified carbon intensity, licensing terms, and the ability to integrate into an existing production line without halting it. New entrants typically avoid asset ownership and instead license process equipment to ready-mix producers, aggregate recyclers and cement plants, which lowers capital intensity and speeds deployment.
Strategic activity concentrates on securing low-cost, high-purity CO2 streams and on positioning for compliance-driven demand. Industrial gas companies are extending long-term offtake arrangements with ammonia and ethanol producers to lock in supply, while chemical firms evaluate CO2-based polyols and polycarbonates as a route to differentiated materials. Cement and aggregate producers are the most important emerging customer group, because their compliance exposure makes carbon storage in products a cost-avoidance measure rather than a discretionary purchase.
Strategic direction across the sector is converging on verifiability. Firms are investing in monitoring, measurement and life cycle documentation so that utilisation claims survive audit, and they are segmenting portfolios between high-volume conventional supply and lower-volume durable products that carry a certified carbon attribute.
Carbon Dioxide Utilization Industry Leaders
- Linde plc
- Air Liquide
- Air Products and Chemicals, Inc.
- Yara International ASA
- SABIC
Recent Industry Developments
February 2024: The European Commission published its Industrial Carbon Management Strategy, setting out how capture, transport, storage and utilisation should develop together across the European Union – it gave utilisation projects a formal place in industrial policy planning.
May 2023: The revised European Union Emissions Trading System rules under Directive (EU) 2023/959 confirmed that carbon dioxide permanently chemically bound in a product need not be surrendered as an emission – this created the first large compliance-driven pull for durable utilisation routes.
December 2024: Regulation (EU) 2024/3012 established the European Union certification framework for carbon removals and carbon farming, including a category for carbon storage in products – it set minimum durability and monitoring requirements that utilisation operators must now design toward.
August 2022: The United States Inflation Reduction Act reset the 45Q tax credit, retaining a lower per-tonne value for carbon utilisation than for secure geological storage – the differential continues to steer private capital toward storage projects over conversion plants.
Carbon Dioxide Utilization Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 10.8 Billion |
| Market Size 2033 | US$ 21.6 Billion |
| CAGR 2026–2033 | 10.41% |
| Absolute Dollar Opportunity | US$ 10.8 Billion |
| Largest Market | Asia Pacific (41.0% share in 2026) |
| Fastest-Growing Market | Middle East & Africa (13.4% CAGR) |
| Market Concentration | Medium |
| Major Players | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Yara International ASA |
This report covers every commercial use of captured or sourced carbon dioxide, including urea synthesis, enhanced oil recovery, food and beverage, greenhouse enrichment, welding, water treatment, concrete mineralisation, polymers and synthetic fuels. Chemicals and fuels made from carbon dioxide are examined in depth separately, and permanent removal with geological storage is a distinct market, since utilisation does not always store carbon durably. Base year is 2025; the forecast period runs 2026 to 2033 in US$ Billion.
Carbon Dioxide Utilization Market Segmentation
Application
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
CO2 Source
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
Conversion Route
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
Carbon Retention Profile
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Carbon Dioxide Utilization Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Nitrogen Fertiliser Output Anchors the Largest Block of CO2 Utilization Demand
- Carbon Pricing and 45Q Credits Shift Capital Toward Durable CO2 Utilization
- Restraints
- Policy Design Favouring Geological Storage Caps Carbon Dioxide Utilization Returns
- Unsettled Life Cycle Accounting Slows Buyer Acceptance of CO2-Derived Products
- Market Opportunities
- Carbonated Aggregate and Concrete Curing Open a Durable-Carbon Revenue Pool
- Certified Carbon Storage in Products Creates a Tradable Attribute for Utilisation Operators
- Drivers
- Global Carbon Dioxide Utilization Market Outlook, 2020–2033
- Global Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- Global Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- Global Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- Global Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- Global Carbon Dioxide Utilization Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- North America Carbon Dioxide Utilization Market Outlook, 2020–2033
- North America Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- North America Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- North America Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- North America Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- North America Carbon Dioxide Utilization Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- United States Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- United States Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- United States Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Canada Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Canada Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Canada Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Canada Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- North America Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Europe Carbon Dioxide Utilization Market Outlook, 2020–2033
- Europe Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- Europe Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- Europe Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- Europe Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- Europe Carbon Dioxide Utilization Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Germany Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Germany Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Germany Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Netherlands Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Netherlands Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Netherlands Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Netherlands Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Norway Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Norway Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Norway Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Norway Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- France Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- France Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- France Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- France Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Europe Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Asia Pacific Carbon Dioxide Utilization Market Outlook, 2020–2033
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- China Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- China Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- China Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- India Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- India Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- India Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- India Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Indonesia Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Indonesia Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Indonesia Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Indonesia Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Japan Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Japan Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Japan Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Japan Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- South Korea Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- South Korea Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- South Korea Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- South Korea Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Asia Pacific Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Latin America Carbon Dioxide Utilization Market Outlook, 2020–2033
- Latin America Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- Latin America Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- Latin America Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- Latin America Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- Latin America Carbon Dioxide Utilization Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Brazil Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Brazil Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Brazil Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Mexico Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Mexico Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Mexico Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Mexico Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Argentina Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Argentina Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Argentina Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Argentina Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Colombia Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Colombia Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Colombia Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Colombia Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Latin America Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, 2020–2033
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by CO2 Source, Value (US$ Billion), 2020–2033
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by Conversion Route, Value (US$ Billion), 2020–2033
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, Value (US$ Billion), 2020–2033
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Saudi Arabia Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Saudi Arabia Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Saudi Arabia Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Egypt Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Egypt Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Egypt Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Egypt Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Nigeria Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Nigeria Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Nigeria Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Nigeria Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Qatar Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- Qatar Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- Qatar Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- Qatar Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- United Arab Emirates Carbon Dioxide Utilization Market Outlook, by Application, 2020–2033
- United Arab Emirates Carbon Dioxide Utilization Market Outlook, by CO2 Source, 2020–2033
- United Arab Emirates Carbon Dioxide Utilization Market Outlook, by Conversion Route, 2020–2033
- United Arab Emirates Carbon Dioxide Utilization Market Outlook, by Carbon Retention Profile, 2020–2033
- Middle East & Africa Carbon Dioxide Utilization Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Linde plc
- Air Liquide
- Air Products and Chemicals, Inc.
- Messer Group GmbH
- Nippon Sanso Holdings Corporation
- SABIC
- Yara International ASA
- Nutrien Ltd.
- CF Industries Holdings, Inc.
- Covestro AG
- Mitsubishi Heavy Industries, Ltd.
- Occidental Petroleum Corporation
- CarbonCure Technologies Inc.
- Solidia Technologies, Inc.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Application
- Urea & Fertilizer Synthesis
- Enhanced Oil Recovery
- Food & Beverage
- Chemicals & Polymers
- Fuels
- Construction Materials & Mineralization
- Other Industrial Uses
CO2 Source
- Ammonia & Hydrogen Plants
- Ethanol & Fermentation
- Natural Gas Processing
- Power Generation
- Cement & Steel
- Direct Air Capture
Conversion Route
- Non-Conversion
- Chemical Conversion
- Mineral Carbonation
- Biological Conversion
- Electrochemical Conversion
Carbon Retention Profile
- Open-Cycle Utilization
- Semi-Durable Utilization
- Durable Utilization
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 10.8 billion in 2026, counting conventional uses such as urea synthesis and enhanced oil recovery alongside emerging conversion routes.
The market is projected to reach US$ 21.6 billion by 2033, expanding at a 10.41% CAGR and adding US$ 10.8 billion in absolute opportunity.
Urea & Fertilizer Synthesis leads with 42.0% share in 2026, because ammonia plants capture and consume carbon dioxide within the same production site.
Direct Air Capture grows fastest among sources at a 24.5% CAGR, while Construction Materials & Mineralization leads applications at 18.9% through 2033.
Asia Pacific holds 41.0% share in 2026, supported by the world’s largest concentration of ammonia-urea capacity across China, India and Indonesia.
Related Reports
Perovskite Photovoltaics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Perovskite photovoltaics market to reach US$ 4.8 billion by 2033 at 38.1% CAGR. Explore technologies, regional trends and key companies.
Microgrid Monitoring Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Microgrid monitoring systems market to reach US$ 5.5 billion by 2033 at 14.0% CAGR. Explore components, regional trends and key companies.
Big Data Analytics in Oil & Gas Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Oil & gas big data analytics market to reach US$ 30.0 billion by 2033 at 12.9% CAGR. Explore segments, regions and key companies.
AI in Oil & Gas Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
AI in oil and gas market to reach US$15.4 billion by 2033 at 19.6% CAGR. Explore technologies, applications, regional trends and leading companies.
Industrial Boilers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Industrial boilers market to reach US$26.0 billion by 2033 at 4.9% CAGR. Explore product types, fuels, regional trends and leading companies.
Industrial Batteries Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Industrial batteries market to reach US$41.6 billion by 2033 at 7.7% CAGR. Explore battery types, applications, regional trends and key companies.