



Engineering Plastic Compounds Market
Engineering Plastic Compounds Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Engineering Plastic Compounds Market Size and Trend Analysis
How Large Is the Engineering Plastic Compounds Market?
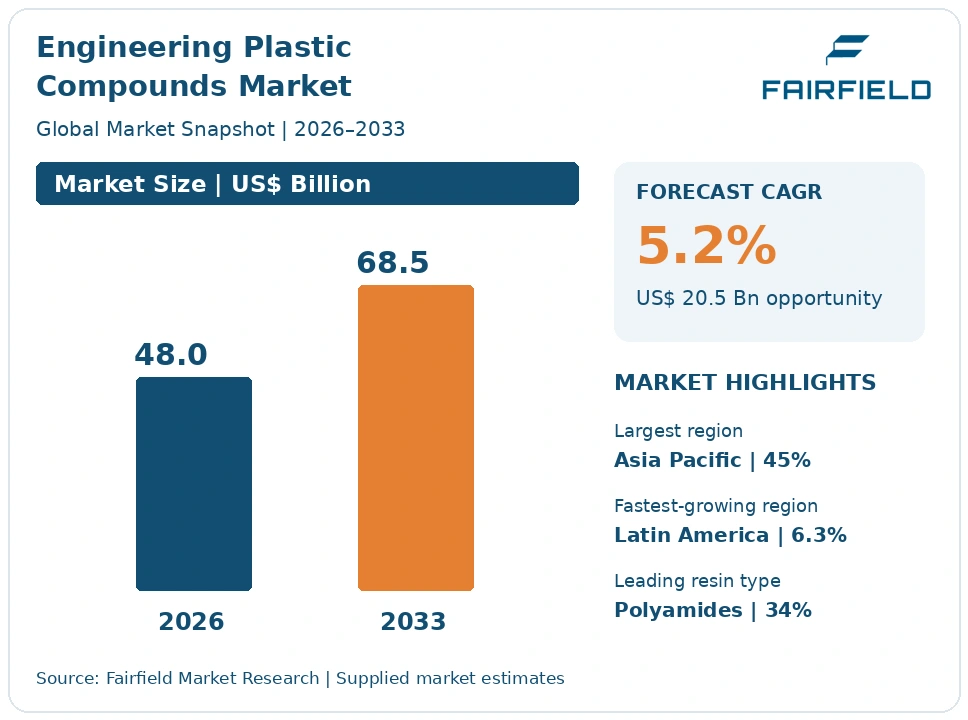
The global engineering plastic compounds market size is expected to be valued at US$ 48.0 billion in 2026 and projected to reach US$ 68.5 billion by 2033, growing at a CAGR of 5.2% between 2026 and 2033.
The market expanded at a historical CAGR of close to 4.0% from 2020 to 2025, interrupted by the semiconductor shortage that cut vehicle build rates and by sharp swings in resin and energy costs. Three forces drive the stronger outlook. Metal replacement continues across powertrain, chassis, appliance and industrial parts. Vehicle electrification is moving the automotive formulation mix toward insulation, flame retardancy and thermal management. Recycled content requirements are turning into written specifications. Growth is measured in compound value rather than resin value, so the forecast reflects formulation complexity and service content more than base polymer pricing, which passes through with a lag.
Key Report Takeaways
- By Resin Type: Polyamides held 34% share in 2026, while polyphenylene sulphide is projected to expand at a 7.2% CAGR through 2033, driven by high-voltage connectors, pumps and thermal management parts in electrified vehicles.
- By Modification Type: Glass and carbon fibre reinforcement held 41% share in 2026, while conductive and shielding additive systems are projected to expand at a 7.5% CAGR through 2033, as electronics enclosures need electromagnetic shielding and static control.
- By End Use Industry: Automotive and transportation held 36% share in 2026, while electrical and electronics is projected to expand at a 6.6% CAGR through 2033, reflecting grid equipment, data centre hardware and connector demand.
- By Content Source: Virgin compounds held 82% share in 2026, while post-consumer recycled content compounds are projected to expand at a 9.5% CAGR through 2033, because vehicle and appliance makers now write recycled percentages into part specifications.
- By Geography: Asia Pacific held 45% share in 2026, while Latin America is projected to expand at a 6.3% CAGR through 2033, supported by nearshored automotive and appliance manufacturing in Mexico.
Global Engineering Plastic Compounds Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the forecast growth in compounded engineering thermoplastics.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Metal replacement in automotive, appliance and industrial parts | High | Global | Long term (≥4 years) |
| Electrification shifting formulations toward insulation, flame retardancy and thermal management | High | Asia Pacific, Europe, North America | Medium term (2–4 years) |
Metal Replacement Keeps Pulling Volume Into Reinforced Thermoplastic Compounds
Metal replacement remains the most durable demand driver for engineering thermoplastic compounds, and it works part by part rather than in waves. Every pump housing, bracket, gear, pedal box or water manifold converted from aluminium or steel moves a kilogram of metal into a compounded polymer that is lighter, quieter, corrosion-free and cheaper to assemble. Those conversions rarely reverse once tooling is paid for.
The mechanism is mechanical performance delivered by formulation. Glass and carbon fibre reinforcement, mineral fillers and coupling chemistry give polyamide, polyphenylene sulphide and polyphthalamide the stiffness and creep resistance that structural metal parts need, while injection moulding consolidates several metal components into one. UL 746 long-term thermal ageing data gives designers the evidence to approve a polymer where temperature is the concern. Fuel economy rules and appliance efficiency targets add a continuing reason to remove mass.
Electrification Rewrites the Automotive Compound Specification
Electrification is changing what the automotive industry buys from compounders rather than how much it buys. Demand is moving away from under-the-bonnet heat and chemical resistance and toward electrical insulation, flame retardancy, tracking resistance and heat dissipation. Battery housings, busbar supports, high-voltage connectors, charging inlets and inverter components all need compounds qualified for electrical safety, and those grades carry higher formulation value than general reinforced polyamide.
The causal chain runs through qualification. High-voltage parts must meet UL 94 flammability classifications, comparative tracking index requirements and glow-wire criteria under IEC 60695, which pushes designers toward halogen-free flame-retarded polyamide, polyester and polyphenylene sulphide compounds. Thermally conductive and electrically insulating grades are being specified for battery modules and power electronics. Each new platform locks in a compound for the vehicle’s production life, so wins compound over time.
Restraints Impact Analysis
Two constraints keep margins thin and growth in mid single digits across compounded thermoplastics.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Resin price volatility passed through with a lag, squeezing compounder margins | High | Global | Short term (≤2 years) |
| Overcapacity and price competition in commodity-grade compounding | Medium | Asia Pacific, Europe | Medium term (2–4 years) |
Resin Price Swings Compress Compounder Margins Before Contracts Reset
Base resin volatility hits compounders harder than it hits resin producers, because purchase prices move monthly while customer prices reset quarterly or annually. Material accounts for the great majority of a compound’s cost, so a sharp move in polyamide, polycarbonate or polyester feedstock can erase a quarter’s margin before any contract adjustment arrives. That lag discourages inventory building and makes earnings volatile.
The specific cost sources are caprolactam, adiponitrile, bisphenol A, purified terephthalic acid and the energy used in extrusion. Flame retardants, glass fibre and specialty additives add their own volatility and are frequently single-sourced. Compounders rarely integrate backward into monomers, so they cannot hedge physically. Formula-based pricing passes resin movements through eventually, yet the indices used typically trail spot markets, and customers resist mid-contract increases on qualified automotive and appliance parts.
Commodity-Grade Overcapacity Holds Down Compound Pricing
Overcapacity in standard reinforced grades caps pricing across a large part of the market. Twin-screw compounding equipment is widely available, technically accessible and inexpensive compared with polymerisation, so capacity has multiplied wherever converters cluster. For glass-filled polyamide and polyester at common loadings, dozens of suppliers can quote, and the specification is easy to match.
The underlying cause is a low technical barrier combined with high regional fragmentation. A line can switch between formulations in hours, so idle capacity chases any available order at marginal cost. Chinese and regional compounders have added lines faster than demand has grown in standard grades, and converters use multiple approved suppliers to keep quotes competitive. Differentiation survives only where documentation, colour matching, flame-retardant qualification or lot-to-lot consistency are difficult, which is why suppliers retreat toward specialty portfolios.
Market Opportunities
Recycled Content Mandates Create a Specification-Led Compound Revenue Pool
Recycled content requirements are turning from preference into written specification, and that creates a revenue pool compounders are better placed to capture than base resin producers. Blending post-consumer and post-industrial material to a stable, documented property set is a formulation and quality-control task, which is exactly what a compounder does. Qualified recycled-content grades price above commodity recyclate and often near virgin levels.
Automotive and appliance makers generate the demand, because their own targets and the proposed recycled plastic requirement in the European Union end-of-life vehicles framework push percentages into part drawings. Electrical and electronics customers follow through RoHS declarations and ecodesign rules. Capture depends on traceability, sorted feedstock agreements and the test data to prove that a recycled grade behaves like the virgin one it replaces across ageing, impact and flame performance.
Halogen-Free Flame-Retarded Grades Open a Higher-Value Electrical Pool
Halogen-free flame-retarded compounds open a premium pool as electrical equipment makers move away from restricted brominated chemistry. These grades are harder to formulate, since phosphorus and nitrogen systems need higher loadings and can reduce mechanical performance and flow, which rewards suppliers that can hold a UL 94 V-0 rating at thin wall without losing tracking resistance. Selling prices sit well above standard reinforced grades.
Appliance, connector, switchgear and photovoltaic component makers create the demand, driven by glow-wire requirements under IEC 60695, comparative tracking index targets and customer restricted-substance lists that run ahead of REACH restrictions on specific flame retardants. Compounders with their own UL yellow card listings and in-house burn laboratories capture the work, because each listed grade is an asset that customers can specify directly without re-testing the finished part.
Segment Analysis
By Resin Type: Polyamides Lead While Polyphenylene Sulphide Grows Fastest
Polyamides, covering PA6, PA66 and high-temperature grades, led with 34% share in 2026, because they combine mechanical strength, chemical resistance and the widest qualified grade range in automotive and industrial parts. Polycarbonate and PC blends held 19%, PBT and PET polyesters 15%, polyoxymethylene 8%, compounded styrenics 8%, modified polyphenylene ether 6%, polysulphones, PEEK and other high-performance polymers 6% and polyphenylene sulphide 4%. Polyphenylene sulphide is the fastest-growing resin at a 7.2% CAGR, because its dimensional stability, inherent flame resistance and resistance to coolants suit high-voltage connectors, electric pumps and thermal management housings. Acrylonitrile butadiene styrene and the individual base resins are examined separately; the value counted here is the compound, not the polymer, so resin substitution between families changes the mix far less than the additive package applied to it.
By Modification Type: Fibre Reinforcement Dominates as Conductive Systems Accelerate
Glass and carbon fibre reinforcement accounted for 41% of compound value in 2026, the largest modification class, because stiffness and strength are the reason most designers choose a compound over a base resin. Flame retardants held 19%, impact modifiers 12%, mineral fillers 10%, colour 7% and lubricants and stabilisers 6%. Conductive and shielding additive systems are the fastest-growing modification at a 7.5% CAGR from a 5% base. Electronics enclosures, charging hardware, sensor housings and fuel system components need electromagnetic shielding, static dissipation or controlled surface resistivity, and carbon black, carbon fibre, carbon nanotube and metal-coated filler systems deliver it. Each added function raises formulation value, which is where compounder margin actually sits, and multi-function packages that combine reinforcement with shielding or flame retardancy are the clearest route to defending price in a crowded supplier field.
By End Use Industry: Automotive Holds the Largest Share While Electronics Expands Quickest
Automotive and transportation held 36% share in 2026, the single largest outlet, because a modern vehicle contains hundreds of compounded parts and because automotive qualification locks suppliers in for a platform lifetime. Industrial and machinery took 16%, consumer appliances 14%, building and construction 8% and medical 5%. Electrical and electronics is the fastest-growing industry at a 6.6% CAGR from a 21% share. Grid equipment, switchgear, data centre power hardware, photovoltaic components and connectors all require flame-retarded, tracking-resistant and dimensionally stable compounds, and electrification is expanding every one of those categories at once. Electronics customers also demand restricted-substance documentation, which favours compounders with established regulatory data packages. The practical implication is that automotive keeps the volume base stable while electrical applications decide which suppliers grow, because the formulation and certification work sits with the compounder rather than with the moulder.
By Content Source: Virgin Grades Dominate While Post-Consumer Recycled Compounds Surge
Virgin compounds held 82% share in 2026, because qualified automotive, electrical and medical parts are specified against virgin property data and requalification is costly. Post-industrial recycled content compounds accounted for 12%, using clean, known-origin scrap that behaves predictably. Bio-based and mass-balance compounds held 2%. Post-consumer recycled content compounds are the fastest-growing source at a 9.5% CAGR from a 4% base, the highest growth rate in the report. Vehicle and appliance makers are writing recycled percentages directly into part specifications rather than treating them as a preference, pushed by the European Union end-of-life vehicles framework and by corporate circularity targets. Qualification remains the brake, since colour, odour and impact consistency must be demonstrated batch after batch, and regulated automotive, electrical and medical parts carry re-testing costs that slow substitution even where the supply of sorted feedstock is adequate.
Geography Analysis
North America Pairs Automotive Qualification With Electrical Infrastructure Demand
North America held 23% of the market in 2026, with the United States supplying most volume and Mexico and Canada adding vehicle and appliance assembly. Demand is weighted toward qualified automotive grades, electrical equipment compounds and medical formulations, which lifts average value per tonne above volume-driven markets. UL listings are the practical gatekeeper for electrical applications, and compounders maintain large portfolios of yellow card grades to shorten customer approval. Grid investment, data centre construction and battery plant projects are adding demand for flame-retarded and thermally conductive compounds. Reshoring of electronics and medical device production supports local compounding capacity. The constraint is a mature vehicle build rate, so growth depends on content per vehicle and specification upgrades rather than unit volumes.
Europe Turns Circularity Rules Into Compound Specifications
Europe accounted for 22% of demand in 2026, concentrated in Germany, France, Italy and the Czech Republic, and shaped more by regulation than by growth in unit output. The end-of-life vehicles framework and its proposed recycled plastic content requirement, together with RoHS, REACH restrictions on specific flame retardants, and ecodesign rules, are written into customer part specifications. That pushes the mix toward halogen-free flame-retarded and recycled-content grades, which compounders can supply more readily than resin producers. Energy costs and weak vehicle output have pressured regional compounding margins, and some commodity-grade volume has shifted elsewhere. The clearest opportunity is documented circular compounds, where traceability and property data carry a genuine price premium and where regional converters cannot easily substitute imports.
Which Region Is Leading the Engineering Plastic Compounds Market?
Asia Pacific leads the engineering plastic compounds market with 45% share in 2026, because the region manufactures most of the world’s vehicles, appliances, connectors and electronic equipment. China alone accounts for a large majority of regional consumption, supported by domestic resin capacity, a dense converter base and a compounding industry that has scaled rapidly. Japan and South Korea contribute high-specification demand in polyphenylene sulphide, polyoxymethylene and high-temperature polyamide for connectors, camera modules and electric powertrains. India is growing quickly from a smaller base as vehicle and appliance production localises. Electric vehicle output concentrated in the region pulls flame-retarded and thermally conductive grades. The structural issue is overcapacity in standard reinforced grades, which keeps commodity pricing under persistent pressure.
Which Region Is Growing Fastest in the Engineering Plastic Compounds Market?
Latin America is the fastest-growing region in the engineering plastic compounds market at a 6.3% CAGR through 2033, from a 5% share in 2026. Mexico drives it: vehicle, wiring harness, connector and appliance manufacturing has expanded as supply chains relocate closer to United States assembly plants, and each new plant qualifies local compound supply to reduce freight and inventory. Brazil contributes through its own vehicle industry, agricultural machinery and electrical equipment production. Argentina and Colombia add smaller industrial volumes. Barriers are significant: limited local resin capacity means most feedstock is imported and dollar-priced, currency swings move compound pricing sharply, and qualification work often still happens at the customer’s headquarters abroad. Local compounding investment is the main change underway.
Middle East & Africa Builds Downstream Compounding on Local Polymer Capacity
Middle East & Africa held 5% of the market in 2026, the smallest regional pool but one with a clear structural logic. Gulf producers hold large polymer capacity and are pushing downstream into conversion and compounding to capture value beyond commodity resin exports, supported by industrial diversification programmes in Saudi Arabia and the United Arab Emirates. Demand comes from appliance assembly, wire and cable, construction products and a growing automotive presence in Morocco and Egypt. Türkiye-linked supply chains serve part of the region. Barriers include a thin base of qualified converters, limited local testing and certification infrastructure, and dependence on imported specialty additives. The opportunity lies in localised compounding for appliance and electrical manufacturers that currently import finished compounds.
Competitive Landscape
The engineering plastic compounds market is moderately concentrated and splits into two different businesses. Integrated chemical producers supply high volumes of their own resins in compounded form, while independent compounders buy resin on the open market and compete on formulation, colour and service. Below them sit hundreds of regional compounders serving local converters. Concentration is high in specialty areas such as polyphenylene sulphide, high-temperature polyamide and medical grades, where qualification data and regulatory documentation are difficult to replicate, and low in standard glass-filled grades, where capacity is abundant. Consolidation has been steady, with specialty portfolios changing hands as diversified chemical groups separate commodity and specialty businesses.
Competition is based on specification and service rather than on material margin. Customers select a supplier for formulation capability, colour matching, the completeness of regulatory and flammability documentation, and above all for the ability to deliver a qualified lot that behaves exactly like the one approved during part validation. Switching is expensive because requalification can require new mould trials, re-testing and sometimes customer audits, so converters change the part before they change the compounder. That stickiness is the industry’s main defence against price competition. New entrants arrive from recyclate processors moving upstream into compounding, and from converters adding in-house lines for captive grades.
Strategic direction across the supplier base is consistent. Vendors are expanding electrification portfolios, adding halogen-free flame-retarded and thermally conductive grades, building recycled-content product families with traceability data, and investing in application laboratories and simulation support that shorten customer development time. Regional capacity is being placed close to automotive and electronics clusters to cut freight and inventory. Several suppliers are narrowing their offer, exiting commodity grades and concentrating on formulations where documentation and qualification create a defensible position.
Engineering Plastic Compounds Industry Leaders
- BASF SE
- SABIC
- Celanese Corporation
- Avient Corporation
- Covestro AG
Recent Industry Developments
July 2023: The European Commission proposed a regulation on circularity requirements for vehicle design and end-of-life vehicle management, including a recycled plastic content requirement for new vehicles – it moves recycled content from a corporate target to a prospective legal specification for automotive compounds.
February 2023: Authorities from five European countries submitted a universal restriction proposal on per- and polyfluoroalkyl substances, published by the European Chemicals Agency – it reaches fluoropolymer compounds and polymer processing aids used in engineering thermoplastics.
July 2024: The European Union Ecodesign for Sustainable Products Regulation entered into force – it creates the legal basis for durability, recyclability and recycled content requirements that will be written into product-level rules affecting compound selection.
March 2019: The restriction on decabromodiphenyl ether in articles took effect under REACH – it accelerated the shift of electrical and electronics compounds toward halogen-free flame-retardant systems.
Engineering Plastic Compounds Market Report Scope
| Metric | Value |
| Study Period (2020–2033) | 14 years of historical and forecast coverage |
| Market Size 2026 | US$ 48.0 Billion |
| Market Size 2033 | US$ 68.5 Billion |
| CAGR 2026–2033 | 5.2% |
| Absolute Dollar Opportunity | US$ 20.5 Billion |
| Largest Market (region) | Asia Pacific, 45% share in 2026 |
| Fastest-Growing Market (region) | Latin America, 6.3% CAGR |
| Market Concentration | Medium |
| Major Players | BASF SE, SABIC, Celanese Corporation, Avient Corporation, Covestro AG |
This report covers compounded and formulated engineering thermoplastics, counting the compound rather than the base resin, since resin economics pass through rather than create value here. Included are polyamides, polycarbonate, polyoxymethylene, polyesters, modified polyphenylene ether, polyphenylene sulphide and high-performance polymers modified with reinforcement, fillers, flame retardants, additives, colour and recycled content. Acrylonitrile butadiene styrene and base polymer production are excluded. Base year 2025, forecast 2026 to 2033, in US$ Billion.
Engineering Plastic Compounds Market Segmentation
Resin Type
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
Modification Type
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
End Use Industry
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
Content Source
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Engineering Plastic Compounds Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Metal Replacement Keeps Pulling Volume Into Reinforced Thermoplastic Compounds
- Electrification Rewrites the Automotive Compound Specification
- Restraints
- Resin Price Swings Compress Compounder Margins Before Contracts Reset
- Commodity-Grade Overcapacity Holds Down Compound Pricing
- Market Opportunities
- Recycled Content Mandates Create a Specification-Led Compound Revenue Pool
- Halogen-Free Flame-Retarded Grades Open a Higher-Value Electrical Pool
- Drivers
- Global Engineering Plastic Compounds Market Outlook, 2020–2033
- Global Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- Global Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- Global Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- Global Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- Global Engineering Plastic Compounds Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- North America Engineering Plastic Compounds Market Outlook, 2020–2033
- North America Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- North America Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- North America Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- North America Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- North America Engineering Plastic Compounds Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- United States Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- United States Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- United States Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Canada Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Canada Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Canada Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Canada Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- North America Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Europe Engineering Plastic Compounds Market Outlook, 2020–2033
- Europe Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- Europe Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- Europe Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- Europe Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- Europe Engineering Plastic Compounds Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Germany Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Germany Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Germany Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- France Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- France Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- France Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- France Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Italy Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Italy Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Italy Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Italy Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Czech Republic Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Czech Republic Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Czech Republic Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Czech Republic Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Europe Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Asia Pacific Engineering Plastic Compounds Market Outlook, 2020–2033
- Asia Pacific Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- Asia Pacific Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- Asia Pacific Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- Asia Pacific Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- Asia Pacific Engineering Plastic Compounds Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- China Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- China Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- China Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Japan Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Japan Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Japan Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Japan Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- South Korea Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- South Korea Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- South Korea Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- South Korea Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- India Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- India Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- India Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- India Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Asia Pacific Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Latin America Engineering Plastic Compounds Market Outlook, 2020–2033
- Latin America Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- Latin America Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- Latin America Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- Latin America Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- Latin America Engineering Plastic Compounds Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Mexico Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Brazil Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Brazil Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Brazil Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Brazil Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Argentina Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Argentina Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Argentina Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Argentina Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Colombia Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Colombia Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Colombia Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Colombia Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Latin America Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Engineering Plastic Compounds Market Outlook, 2020–2033
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by Modification Type, Value (US$ Billion), 2020–2033
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by Content Source, Value (US$ Billion), 2020–2033
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Saudi Arabia Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Saudi Arabia Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Saudi Arabia Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- United Arab Emirates Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- United Arab Emirates Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- United Arab Emirates Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- United Arab Emirates Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Morocco Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Morocco Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Morocco Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Morocco Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Egypt Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Egypt Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Egypt Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Egypt Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Türkiye Engineering Plastic Compounds Market Outlook, by Resin Type, 2020–2033
- Türkiye Engineering Plastic Compounds Market Outlook, by Modification Type, 2020–2033
- Türkiye Engineering Plastic Compounds Market Outlook, by End Use Industry, 2020–2033
- Türkiye Engineering Plastic Compounds Market Outlook, by Content Source, 2020–2033
- Middle East & Africa Engineering Plastic Compounds Market Outlook, by Resin Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- BASF SE
- SABIC
- Covestro AG
- Celanese Corporation
- LyondellBasell Industries N.V.
- Avient Corporation
- DuPont de Nemours, Inc.
- Mitsubishi Engineering-Plastics Corporation
- Asahi Kasei Corporation
- Toray Industries, Inc.
- Polyplastics Co., Ltd.
- RTP Company
- Kingfa Sci. & Tech. Co., Ltd.
- LG Chem Ltd.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Resin Type
- Polyamides
- Polycarbonate and PC blends
- Polyoxymethylene
- PBT and PET polyesters
- Modified polyphenylene ether
- Polyphenylene sulphide
- Polysulphones, PEEK and other high-performance polymers
- Compounded styrenics
Modification Type
- Glass and carbon fibre reinforcement
- Mineral fillers
- Flame retardants
- Impact modifiers
- Conductive and shielding additive systems
- Lubricants and stabilisers
- Colour
End Use Industry
- Automotive and transportation
- Electrical and electronics
- Industrial and machinery
- Consumer appliances
- Medical
- Building and construction
Content Source
- Virgin compounds
- Post-industrial recycled content compounds
- Post-consumer recycled content compounds
- Bio-based and mass-balance compounds
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global engineering plastic compounds market is valued at US$ 48.0 billion in 2026, counting compounded material rather than base resin production.
Compounded engineering thermoplastics are projected to reach US$ 68.5 billion by 2033, a 5.2% CAGR and an absolute dollar opportunity of US$ 20.5 billion.
Polyamides lead with 34% share in 2026, because they combine strength, chemical resistance and the widest qualified grade range across automotive and industrial parts.
Post-consumer recycled content compounds grow fastest at a 9.5% CAGR, as vehicle and appliance makers write recycled percentages directly into part specifications.
Asia Pacific holds 45% share in 2026, because the region manufactures most of the world’s vehicles, appliances, connectors and electronic equipment.
Related Reports
Ethyl Acetate Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The ethyl acetate market is projected to grow from US$4.6 billion in 2026 to US$6.1 billion by 2033, at a CAGR of 4.1%, led by Asia Pacific packaging demand.
Flooring Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The flooring market is projected to grow from US$265.0 billion in 2026 to US$373.0 billion by 2033, at a CAGR of 5.0%, led by renovation and resilient floors.
Roofing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The roofing market is projected to grow from US$142.0 billion in 2026 to US$187.0 billion by 2033, at a CAGR of 4.0%, supported by re-roofing and repair.
Carbon Fiber Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The carbon fiber market is projected to grow from US$16.8 billion in 2026 to US$32.3 billion by 2033, at a CAGR of 9.8%, led by aerospace and wind energy.
Polymer Emulsion Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Polymer emulsion market to grow from US$44.8 Bn in 2026 to US$66.5 Bn by 2033 at 5.8% CAGR. Explore products, applications, end-use industries and regions.
On The Go Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On the go packaging market to grow from US$2.19 Bn in 2026 to US$3.00 Bn by 2033 at 4.6% CAGR. Explore materials, products, applications and regions.