


Foamed Plastic Insulation Products Market
Foamed Plastic Insulation Products Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Foamed Plastic Insulation Products Market Size and Trend Analysis
What Is Driving Foamed Plastic Insulation Market Growth?
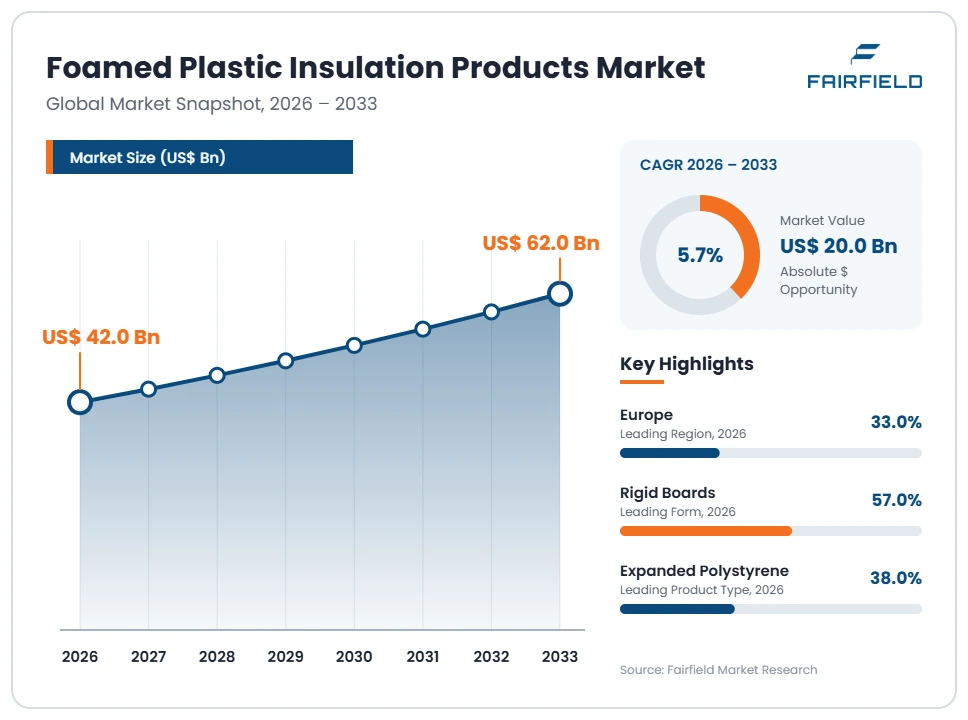
The global Foamed Plastic Insulation Products market size is expected to be valued at US$ 42.0 billion in 2026 and projected to reach US$ 62.0 billion by 2033, growing at a CAGR of 5.7% between 2026 and 2033.
The market grew at roughly a 4.4% CAGR between 2020 and 2025, held back by a construction slowdown in several developed economies and by raw material cost shocks in styrene and isocyanate chains. Three factors lift the forecast. Building energy codes are tightening worldwide, and foamed boards deliver the highest thermal resistance per millimetre of any mainstream insulant. Renovation of existing building stock is becoming a regulated obligation rather than a discretionary upgrade. Cold chain and industrial process insulation continue to expand independently of housing cycles. The direction of travel is clear: volume growth is steady, but product mix is shifting toward higher-specification boards that satisfy both thermal and fire requirements.
Key Report Takeaways
- By Product Type: Expanded polystyrene held 38% share in 2026, while phenolic foam is projected to expand at an 8.1% CAGR through 2033, as specifiers seek low thermal conductivity combined with stronger reaction-to-fire classification in external wall build-ups.
- By Form: Rigid boards held 57% share in 2026, while spray-applied foam is projected to grow at a 6.6% CAGR through 2033, because it seals irregular substrates and air leakage paths that board products cannot address in retrofit work.
- By Application: Walls held 33% share in 2026, while below-grade and foundation insulation is projected to expand at a 6.9% CAGR through 2033, driven by moisture-resistant extruded boards specified in basement and perimeter detailing.
- By End Use: Residential construction held 46% share in 2026, while cold chain and refrigeration is projected to grow at a 7.4% CAGR through 2033, supported by pharmaceutical storage and temperature-controlled logistics capacity additions.
- By Construction Type: New construction held 61% share in 2026, while renovation and retrofit is projected to expand at a 6.7% CAGR through 2033, as minimum energy performance obligations reach the worst-performing existing buildings.
- By Geography: Europe held 33% share in 2026, while Asia Pacific is projected to grow at a 7.3% CAGR through 2033, as building energy codes tighten across China, India, Japan and South Korea.
Global Foamed Plastic Insulation Products Market Trends and Insights
Drivers Impact Analysis
Two regulatory and operational forces account for most incremental demand over the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Tightening building energy performance codes and zero-emission building requirements | High | Europe, North America, Asia Pacific | Long term ≥4 years |
| Space-constrained retrofit where thermal resistance per millimetre is decisive | High | Europe, North America | Medium term 2–4 years |
Zero-Emission Building Rules Lift Specified Insulation Thickness Across Foamed Plastic Products
Energy codes now set the floor for insulation demand rather than merely encouraging it. As required U-values fall, every square metre of wall, roof and floor needs either thicker insulation or a material with lower thermal conductivity. Foamed plastics benefit disproportionately because their conductivity is well below that of fibrous alternatives, so they meet stricter targets without consuming additional floor area or forcing structural redesign.
The regulatory mechanism is explicit in Europe. The recast Energy Performance of Buildings Directive requires new buildings to be zero-emission and obliges member states to improve the worst-performing existing stock. Harmonised product standards give specifiers the certainty to design to those targets: EN 13163 covers expanded polystyrene, EN 13164 extruded polystyrene and EN 13165 polyurethane products. Declared thermal conductivity under these standards is directly comparable, which simplifies substitution decisions during design.
Thin Build-Up Requirements in Retrofit Work Favour High-Performance Foam Boards
Retrofit insulation is constrained by geometry, and that constraint drives material choice toward foam. In an occupied building, internal wall insulation reduces usable room area, external insulation must stay within property boundaries and respect window reveals, and roof upgrades must work beneath existing rafter depth. A board that achieves the same thermal resistance in two-thirds the thickness resolves those conflicts directly, which is why polyisocyanurate and phenolic products are specified for difficult refurbishments.
The underlying change is the growing share of work on existing buildings rather than new plots. Dense urban stock in Germany, France, the United Kingdom and the Netherlands cannot be demolished and rebuilt at scale, so upgrading is the only route to compliance. Insulated plasterboard laminates, over-roof boards and perimeter systems have all been developed specifically for this constrained-space work.
Restraints Impact Analysis
Two persistent issues limit specification breadth and raise the compliance cost of these products.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Fire performance scrutiny in external wall assemblies | High | Europe, North America, Middle East & Africa | Long term ≥4 years |
| Blowing agent transition and flame retardant reformulation costs | Medium | Europe, North America | Short term ≤2 years |
Combustible Insulation Restrictions in Facades Limit Foam Use in Tall Buildings
Fire regulation is the sharpest limit on where foamed plastics can be specified. Following major facade fires, several jurisdictions restricted combustible materials in the external walls of high-rise and high-risk buildings, which removed a significant volume of facade work from polystyrene and polyurethane products and handed it to mineral wool. The restriction is categorical in some codes, so no amount of reformulation restores access to those projects.
The technical cause is classification rather than product quality. Reaction-to-fire performance is assessed under EN 13501-1, and organic foams generally classify below non-combustible mineral products regardless of flame retardant loading. In North America, full-scale assembly testing to NFPA 285 is required for exterior walls of many non-combustible-construction buildings, and qualifying each specific build-up is expensive and slow. That testing burden favours standardised systems over bespoke designs.
Blowing Agent Phase-Down and Flame Retardant Replacement Raise Unit Production Costs
Reformulation has permanently raised the cost base of several foam types. Producers of extruded polystyrene and rigid polyurethane have had to replace high global warming potential blowing agents, re-tune extrusion and foaming lines, and requalify declared thermal conductivity values. Hydrofluoroolefin blowing agents cost considerably more per kilogram than the hydrofluorocarbons they replaced, and that gap passes directly into board pricing.
Two regulatory causes drive this. The European Union F-gas framework phases down high global warming potential fluorinated gases on a fixed schedule, forcing a transition to hydrofluoroolefins. Separately, the listing of hexabromocyclododecane under the Stockholm Convention on persistent organic pollutants ended its use as the standard flame retardant in polystyrene insulation, requiring a shift to polymeric alternatives. Each change consumed capital for line modification and triggered fresh certification work across entire product ranges.
Market Opportunities
Cold Chain and Pharmaceutical Storage Build-Out Opens a Non-Cyclical Revenue Pool
Temperature-controlled infrastructure offers foam producers revenue that is largely uncoupled from the housing cycle. Cold stores, pharmaceutical warehouses, food processing plants and refrigerated transport bodies all require continuous, high-performance insulation, and specification is driven by operating cost and product safety rather than by minimum code compliance. Insulated metal panels with polyurethane or polyisocyanurate cores dominate this work and sell at system prices well above commodity board.
Capture favours producers with panel manufacturing and project engineering capability, not just foam extrusion. The demand comes from logistics operators, grocery retailers and life sciences companies expanding storage capacity, often with cold-chain integrity requirements written into distribution agreements. Rising electricity prices strengthen the case further, because insulation thickness in a cold store pays back through compressor energy savings rather than through regulatory obligation alone.
Closed-Loop Recycling and Recycled-Content Boards Create a Compliance-Led Product Tier
End-of-life performance is becoming a purchasable attribute rather than a reputational one. Public procurement rules, green building rating schemes and developer sustainability commitments increasingly reward insulation with verified recycled content and credible take-back routes. Boards that carry documented recycled polystyrene content or an established site offcut collection scheme can command preference on tenders where price alone would not decide the award.
The customer group is institutional: public housing authorities, infrastructure clients and large contractors with corporate carbon targets. Regulation (EU) 2024/3110 on construction products strengthens this pull by expanding requirements for environmental performance declaration and product information, which gives buyers comparable data to specify against. Producers who already operate dissolution or mechanical recycling routes for polystyrene offcuts are best placed to convert that infrastructure into a differentiated product tier.
Segment Analysis
- By Product Type: Expanded Polystyrene Leads Volume While Phenolic Foam Grows Fastest
Expanded polystyrene held 38% share in 2026, the largest product position, because it offers the lowest cost per unit of thermal resistance and is manufactured close to end markets in hundreds of regional plants. Extruded polystyrene follows, valued for compressive strength and moisture resistance. Polyurethane and polyisocyanurate together form the high-performance tier used where thickness is constrained. Phenolic foam is the fastest-growing product at an 8.1% CAGR through 2033, because it combines very low thermal conductivity with a stronger reaction-to-fire classification under EN 13501-1 than other organic foams, which keeps it specifiable in assemblies where polystyrene is excluded. The implication is a widening two-tier market: commodity boards compete on delivered price and local logistics, while high-specification products compete on certified system performance and the depth of their test evidence.
- By Form: Rigid Boards Dominate Supply as Spray-Applied Foam Advances
Rigid boards accounted for 57% of 2026 revenue because they suit the way buildings are actually built. Boards are dimensionally stable, can be cut on site, carry declared performance values under harmonised standards, and install into standard wall, roof and floor details without specialist equipment. Spray-applied foam is the fastest-growing form at a 6.6% CAGR through 2033. Its advantage is adhesion to irregular substrates and the ability to seal air leakage paths around joists, service penetrations and awkward roof junctions, which matters increasingly as airtightness targets tighten alongside U-value limits. Blocks, moulded shapes and pipe sections serve packaging-adjacent and industrial duties. The business implication is that spray systems pull manufacturers into contractor training, applicator certification and equipment support, which is a service model rather than a product sale.
- By Application: Wall Insulation Holds the Largest Share While Below-Grade Work Expands
Walls held 33% share in 2026, the single largest application, because wall area dominates the thermal envelope of most buildings and because both cavity and external wall systems consume board in volume. Roofing is the second major outlet, where polyisocyanurate flat-roof boards are standard in commercial construction. Below-grade and foundation insulation is the fastest-growing application at a 6.9% CAGR through 2033, reflecting codes that now treat ground-contact heat loss and thermal bridging at the slab perimeter as compliance items rather than optional details. Extruded polystyrene dominates there because it resists water absorption and sustains load under backfill. Flooring and industrial or HVAC insulation complete the picture. For manufacturers, below-grade growth favours those holding EN 13164 certified high-compressive-strength grades in their range.
- By End Use: Residential Construction Leads Volume While Cold Chain Demand Accelerates
Residential construction represented 46% of 2026 value, the largest end use, driven by the sheer number of dwellings built and renovated each year and by energy performance rules that apply most stringently to homes. Commercial construction follows, concentrated in flat-roof and curtain-wall insulation. Cold chain and refrigeration is the fastest-growing end use at a 7.4% CAGR through 2033, supported by pharmaceutical storage capacity, grocery distribution networks and food processing plants that require continuous high-performance envelopes. Industrial and infrastructure insulation adds steady, specification-heavy volume. The implication is that end-use mix determines margin resilience. Producers exposed only to housing follow interest rates and permit volumes closely, while those serving cold chain and industrial clients hold a revenue stream tied to operating economics instead of construction cycles.
- By Construction Type: New Build Still Leads While Renovation Becomes the Growth Engine
New construction held 61% share in 2026, because a new building absorbs its entire insulation requirement at once and specification is straightforward when the envelope is designed from scratch. Renovation and retrofit is the faster-growing category at a 6.7% CAGR through 2033. The driver is regulatory: obligations to improve the worst-performing existing buildings convert voluntary upgrades into required works, and the existing stock vastly outnumbers annual new completions. Retrofit also favours higher-value products, since limited available thickness pushes specifiers toward polyisocyanurate and phenolic boards. The business implication is a channel shift. New build is served through merchants and large contractors on project schedules, while retrofit demand arrives through installers, social housing programmes and smaller contracts that require different distribution, packaging and technical support arrangements.
Geography Analysis
- North America Pairs Energy Code Upgrades With Strict Facade Fire Testing
North America holds 28% share in 2026, the second-largest position in the study. The United States dominates, with Canada adding demand concentrated in cold-climate construction where insulation levels are unusually high. Polyisocyanurate board is the standard commercial roofing insulant across the region, and spray polyurethane foam has a stronger residential position here than almost anywhere else. Model energy codes adopted at state and provincial level continue to raise prescriptive insulation values, particularly for continuous exterior insulation that interrupts thermal bridging through framing. The counterweight is fire regulation: exterior wall assemblies in many building types must demonstrate compliance through full-scale NFPA 285 testing, which constrains bespoke designs and favours pre-tested systems. The change ahead is wider adoption of continuous insulation detailing in low-rise commercial and multifamily buildings, which increases board volume per project.
- Which Region Is Leading the Foamed Plastic Insulation Products Market?
Europe leads the foamed plastic insulation products market with 33% share in 2026, a position built on the strictest energy performance regime anywhere. Germany, France, Italy, Poland and the United Kingdom account for most of the regional total. Three causes sustain the lead. The recast Energy Performance of Buildings Directive sets zero-emission requirements for new buildings and obliges improvement of the worst-performing existing stock, which guarantees baseline demand. Harmonised standards EN 13163, EN 13164 and EN 13165 make declared performance directly comparable, lowering specification risk. A very large, old and poorly insulated building stock supplies decades of renovation work. The constraint is fire policy, since several national codes restrict combustible insulation in tall facades. The opportunity is recycled-content product, reinforced by Regulation (EU) 2024/3110 and its expanded product information requirements.
- Which Region Is Growing Fastest in the Foamed Plastic Insulation Products Market?
Asia Pacific is growing fastest at a 7.3% CAGR between 2026 and 2033, expanding from a 26% share in 2026 and well ahead of every other geography. China, India, Japan, South Korea and Australia drive the expansion. The cause is the simultaneous arrival of three forces. Building energy codes in the region’s largest economies have moved from advisory to mandatory within the past decade, raising insulation from near-zero baselines in many commercial buildings. Urban construction volumes remain the highest in the world, so even modest per-square-metre requirements translate into very large material tonnages. Air conditioning load reduction is a policy priority in hot and humid climates, which makes envelope insulation an electricity-grid issue rather than only a comfort one. Cold chain investment adds a further pull. The main barrier is enforcement consistency, which varies widely between provinces, states and municipalities.
- Latin America Builds Insulation Demand From a Low Base Against Cost and Code Barriers
Latin America accounts for 7% share in 2026, the smaller of the two emerging positions. Brazil, Mexico, Chile and Colombia lead demand, with Chile notable for cold-climate residential insulation requirements in its southern regions. Most construction demand comes from commercial buildings, cold storage and industrial facilities rather than from housing, where masonry construction with minimal insulation remains standard. The barriers are specific: building energy codes are voluntary or weakly enforced in several countries, import duties raise the cost of specialist boards, and high interest rates suppress speculative construction. Thin local manufacturing means supply is partly import-dependent, exposing prices to currency movements. The change worth tracking is cold chain expansion tied to agricultural exports and pharmaceutical distribution, which creates specification-led demand that is insensitive to residential code gaps.
- Middle East & Africa Specifies Insulation for Cooling Loads Rather Than Heating
Middle East & Africa holds 6% share in 2026, the smallest regional position but one with unusual specification logic. Saudi Arabia, the United Arab Emirates, Qatar and South Africa account for most demand. Insulation here is purchased to cut air conditioning electricity consumption, so roof and wall thermal performance is justified on cooling load and peak demand rather than on winter heating. Gulf states have introduced mandatory thermal insulation requirements in connection with electricity connection approvals, which created enforceable baseline demand. Barriers remain significant: limited local manufacturing outside the Gulf, construction practices that treat insulation as an optional finish, and fire code scrutiny of combustible materials in tall buildings after high-profile tower fires. The opportunity lies in large planned urban developments and in industrial and petrochemical process insulation, both of which specify to international standards.
Competitive Landscape
The foamed plastic insulation products market is moderately concentrated, and concentration varies sharply by product type. Expanded polystyrene is highly fragmented because the material is bulky, cheap to foam and uneconomic to ship far, so hundreds of regional converters operate within short delivery radii. Polyisocyanurate board, phenolic foam and insulated panels are far more concentrated, since they require significant capital, continuous lamination lines and extensive fire and thermal certification. BASF SE, Dow Inc., Covestro AG and Huntsman Corporation sit upstream as raw material suppliers, while Kingspan Group plc, Owens Corning, Saint-Gobain S.A., Recticel NV and Carlisle Companies Incorporated compete as system and board manufacturers.
Competition rests on certified performance rather than on material cost alone. Buyers compare declared thermal conductivity, reaction-to-fire classification, compressive strength, dimensional stability and long-term thermal resistance, all evidenced through harmonised standards and third-party certification. Full-scale assembly test evidence is often decisive, because a specifier cannot substitute an uncertified product into a tested build-up. Distribution reach and technical support for installers matter as much as the board itself. New entrants tend to arrive through adjacent capabilities, such as panel fabricators moving upstream or recyclers offering closed-loop polystyrene feedstock.
Strategic activity across the sector concentrates on a few recurring themes: converting plants to low global warming potential blowing agents, adding recycled polystyrene capability, extending from board supply into complete certified wall and roof systems, and building regional capacity close to construction demand to avoid freight on low-density product.
Strategic direction is converging on evidence and systems. Vendors are investing in certification portfolios, environmental product declarations and installer networks, rather than competing primarily on price per cubic metre.
Recent Industry Developments
- May 2013: Hexabromocyclododecane was listed under Annex A of the Stockholm Convention on persistent organic pollutants, with a time-limited exemption for expanded and extruded polystyrene in buildings – forcing the industry-wide shift to polymeric flame retardants in polystyrene insulation.
- February 2024: Regulation (EU) 2024/573 on fluorinated greenhouse gases was adopted, replacing the previous F-gas framework and tightening the phase-down schedule – accelerating the move from hydrofluorocarbon to hydrofluoroolefin blowing agents in extruded polystyrene and rigid polyurethane.
- May 2024: The recast Energy Performance of Buildings Directive, Directive (EU) 2024/1275, entered into force, requiring zero-emission new buildings and obliging member states to improve the worst-performing existing stock – converting renovation insulation from discretionary spend into regulated demand.
- December 2024: Regulation (EU) 2024/3110 laying down harmonised rules for the marketing of construction products was adopted, replacing the earlier construction products regulation – expanding product information and environmental declaration requirements that insulation manufacturers must satisfy.
Companies Covered in the Report
- BASF SE
- Dow Inc.
- Kingspan Group plc
- Owens Corning
- Saint-Gobain S.A.
- Recticel NV
- Covestro AG
- Huntsman Corporation
- Synthos S.A.
- Carlisle Companies Incorporated
- Johns Manville
- Sika AG
- Ravago Group
- SWD Urethane
- Atlas Roofing Corporation
Foamed Plastic Insulation Products Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 42.0 Billion |
| Market Size 2033 | US$ 62.0 Billion |
| CAGR 2026–2033 | 5.7% |
| Absolute Dollar Opportunity | US$ 20.0 Billion |
| Largest Market | Europe (33% share in 2026) |
| Fastest-Growing Market | Asia Pacific (7.3% CAGR) |
| Market Concentration | Medium |
| Major Players | BASF SE, Dow Inc., Kingspan Group plc, Owens Corning, Saint-Gobain S.A. |
Foamed Plastic Insulation Products Market Segmentation
Product Type
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
Form
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
Application
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
End Use
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
Construction Type
- New Construction
- Renovation and Retrofit
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Foamed Plastic Insulation Products Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Zero-Emission Building Rules Lift Specified Insulation Thickness Across Foamed Plastic Products
- Thin Build-Up Requirements in Retrofit Work Favour High-Performance Foam Boards
- Restraints
- Combustible Insulation Restrictions in Facades Limit Foam Use in Tall Buildings
- Blowing Agent Phase-Down and Flame Retardant Replacement Raise Unit Production Costs
- Market Opportunities
- Cold Chain and Pharmaceutical Storage Build-Out Opens a Non-Cyclical Revenue Pool
- Closed-Loop Recycling and Recycled-Content Boards Create a Compliance-Led Product Tier
- Drivers
- Global Foamed Plastic Insulation Products Market Outlook, 2020–2033
- Global Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- Global Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- Global Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- Global Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- Global Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- Global Foamed Plastic Insulation Products Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Foamed Plastic Insulation Products Market Outlook, 2020–2033
- North America Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- North America Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- North America Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- North America Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- North America Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- North America Foamed Plastic Insulation Products Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- United States Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- United States Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- United States Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- United States Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Canada Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Canada Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Canada Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Canada Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Canada Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- North America Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Foamed Plastic Insulation Products Market Outlook, 2020–2033
- Europe Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- Europe Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- Europe Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- Europe Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- Europe Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- Europe Foamed Plastic Insulation Products Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Germany Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Germany Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Germany Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Germany Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- France Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- France Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- France Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- France Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- France Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Italy Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Italy Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Italy Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Italy Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Italy Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Poland Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Poland Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Poland Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Poland Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Poland Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- United Kingdom Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- United Kingdom Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- United Kingdom Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- United Kingdom Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- United Kingdom Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Europe Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, 2020–2033
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- China Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- China Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- China Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- China Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- India Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- India Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- India Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- India Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- India Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Japan Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Japan Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Japan Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Japan Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Japan Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- South Korea Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- South Korea Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- South Korea Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- South Korea Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- South Korea Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Australia Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Australia Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Australia Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Australia Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Australia Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Asia Pacific Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Foamed Plastic Insulation Products Market Outlook, 2020–2033
- Latin America Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- Latin America Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- Latin America Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- Latin America Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- Latin America Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- Latin America Foamed Plastic Insulation Products Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Brazil Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Brazil Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Brazil Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Brazil Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Mexico Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Mexico Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Mexico Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Mexico Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Mexico Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Chile Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Chile Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Chile Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Chile Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Chile Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Colombia Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Colombia Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Colombia Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Colombia Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Colombia Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Latin America Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, 2020–2033
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Construction Type, Value (US$ Billion), 2020–2033
- New Construction
- Renovation and Retrofit
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Saudi Arabia Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Saudi Arabia Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Saudi Arabia Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- United Arab Emirates Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- United Arab Emirates Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- United Arab Emirates Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- United Arab Emirates Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Qatar Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- Qatar Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- Qatar Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- Qatar Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- Qatar Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- South Africa Foamed Plastic Insulation Products Market Outlook, by Product Type, 2020–2033
- South Africa Foamed Plastic Insulation Products Market Outlook, by Form, 2020–2033
- South Africa Foamed Plastic Insulation Products Market Outlook, by Application, 2020–2033
- South Africa Foamed Plastic Insulation Products Market Outlook, by End Use, 2020–2033
- South Africa Foamed Plastic Insulation Products Market Outlook, by Construction Type, 2020–2033
- Middle East & Africa Foamed Plastic Insulation Products Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- BASF SE
- Dow Inc.
- Kingspan Group plc
- Owens Corning
- Saint-Gobain S.A.
- Recticel NV
- Covestro AG
- Huntsman Corporation
- Synthos S.A.
- Carlisle Companies Incorporated
- Johns Manville
- Sika AG
- Ravago Group
- SWD Urethane
- Atlas Roofing Corporation
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Expanded Polystyrene
- Extruded Polystyrene
- Polyurethane and Polyisocyanurate
- Phenolic Foam
Form
- Rigid Boards
- Spray-Applied Foam
- Blocks and Moulded Shapes
- Pipe Sections
Application
- Walls
- Roofing
- Below-Grade and Foundations
- Flooring
- Industrial and HVAC Insulation
End Use
- Residential Construction
- Commercial Construction
- Industrial and Infrastructure
- Cold Chain and Refrigeration
Construction Type
- New Construction
- Renovation and Retrofit
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 42.0 billion in 2026, covering expanded and extruded polystyrene, polyurethane, polyisocyanurate and phenolic foam insulation products.
The market is projected to reach US$ 62.0 billion by 2033, growing at a 5.7% CAGR and adding an absolute opportunity of US$ 20.0 billion.
Expanded polystyrene leads with 38% share in 2026, because it delivers the lowest cost per unit of thermal resistance from locally sited plants.
Phenolic foam grows fastest among products at an 8.1% CAGR, while Asia Pacific leads geographies at a 7.3% CAGR through 2033.
Europe holds 33% share in 2026, supported by the strictest energy performance rules and a very large renovation-ready building stock.
Related Reports
Corrosion Protection Coatings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the corrosion protection coatings market outlook for 2026–2033, including resin trends, application methods, regional demand, and key suppliers.
Coated Abrasives Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The coated abrasives market is projected to grow from US$13.4 billion in 2026 to US$19.0 billion by 2033 at a 5.1% CAGR.
Aerosol Propellants Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The aerosol propellants market is projected to grow from US$11.90 billion in 2026 to US$16.63 billion by 2033 at a 4.9% CAGR.
Marine Oligosaccharides Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The marine oligosaccharides market is projected to grow from US$0.3 billion in 2026 to US$0.6 billion by 2033 at a 10.4% CAGR.
Liquid Crystal Polymer Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global liquid crystal polymer market is valued at US$1.5 billion in 2026, reaching US$2.7 billion by 2033, growing at an 8.8% CAGR
Lignin Based Resins Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global lignin based resins market is valued at US$0.9 billion in 2026, reaching US$1.5 billion by 2033, growing at a 7.6% CAGR