


IoT in Energy Market
IoT in Energy Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
IoT in Energy Market Size and Trend Analysis
How Fast Will Connected Energy Infrastructure Grow Through 2033?
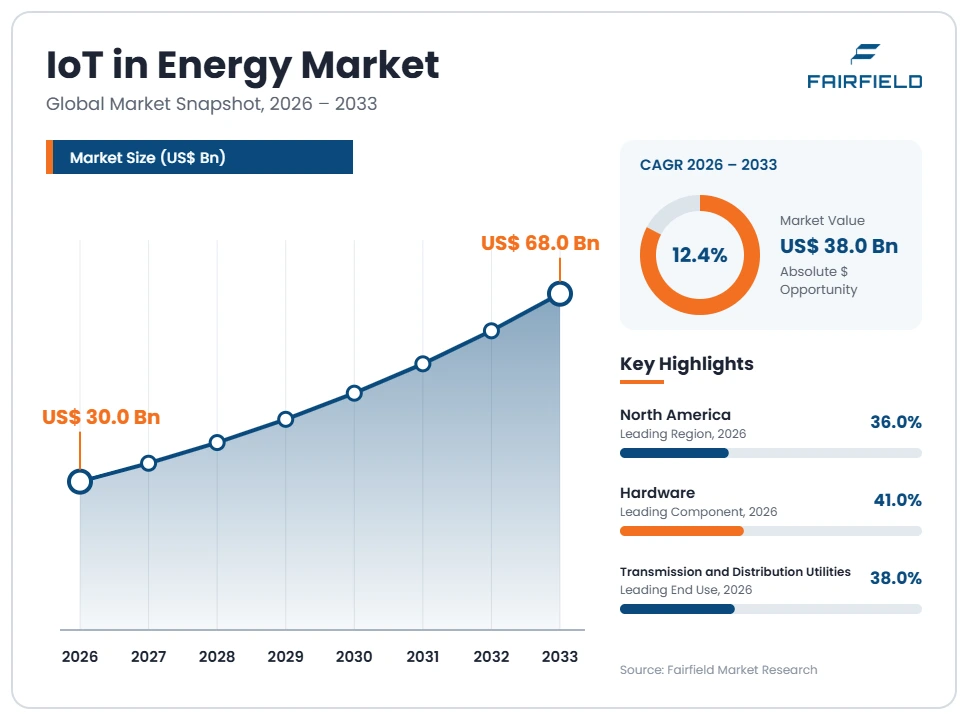
The global IoT in energy market size is expected to be valued at US$ 30.0 billion in 2026 and projected to reach US$ 68.0 billion by 2033, growing at a CAGR of 12.4% between 2026 and 2033. These figures count hardware, connectivity, platform software and services together.
Between 2020 and 2025 the market grew at roughly 11.2% a year, reaching about US$ 26.7 billion. National smart meter rollouts, cheaper cellular modules and utility asset-management programmes carried that period. Three forces now shape the forecast. Grid operators are instrumenting feeders, substations and transformers because power flows run in two directions. Market rules such as FERC Order No. 2222 let aggregated distributed energy resources earn wholesale revenue, and that participation requires telemetry, metering and dispatch control. Oil and gas operators keep automating wellpads and pipelines to cut unplanned downtime. The overall direction is steady compounding rather than a spike, since utility procurement cycles and security reviews pace every deployment.
Key Report Takeaways
- By Component: Hardware held 41% share in 2026, while platform and software is projected to expand at a 14.6% CAGR through 2033, driven by utilities moving analytics and device management into managed cloud environments.
- By Application: Grid monitoring and asset management held 32% share in 2026, while distributed energy resource management and virtual power plants should grow at a 16.2% CAGR, reflecting new aggregation market rules.
- By Connectivity Technology: Cellular held 34% share in 2026, while satellite connectivity is forecast to rise at a 15.8% CAGR through 2033, because remote pipelines and offshore assets lack terrestrial coverage.
- By End Use: Transmission and distribution utilities held 38% share in 2026, while commercial and industrial energy users are set to advance at a 15.3% CAGR, supported by on-site generation and flexibility contracts.
- By Geography: North America held 36% share in 2026, while Asia Pacific is projected to grow at a 15.1% CAGR through 2033, led by metering and feeder automation programmes in China and India.
Global IoT in Energy Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the incremental spending on connected energy assets through 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Market rules opening wholesale participation to distributed energy resource aggregations | High | North America, Europe | Medium term 2–4 years |
| Ageing grid assets pushing utilities toward condition-based maintenance | High | Global | Long term ≥4 years |
Aggregation Market Rules Turn Distributed Energy Telemetry Into a Compliance Purchase
Regulatory access to wholesale markets has converted distributed energy monitoring from an optional upgrade into a revenue requirement. FERC Order No. 2222 obliges United States wholesale market operators to let aggregations of rooftop solar, batteries, electric vehicle chargers and flexible load bid alongside conventional plant. Directive (EU) 2019/944 sets comparable aggregation and demand response rights across member states. An aggregator cannot settle a bid without interval metering, verified telemetry and a dispatch path to every device in the portfolio.
The causal chain runs from settlement rules to hardware. Market operators demand auditable measurement, so aggregators install submeters, gateways and controllers that report at short intervals. Standards such as IEEE 2030.5 define how utilities send set points to inverters and chargers. Each enrolled megawatt therefore carries a fixed cost in sensing, connectivity and platform subscriptions that scales directly with portfolio size.
Ageing Transmission and Distribution Assets Push Utilities Toward Condition-Based Maintenance
Asset age is the second durable source of demand for industrial IoT in power networks. Large portions of the transmission and distribution fleet in North America and Europe were built decades ago, and replacing everything on schedule is financially impossible. Utilities therefore instrument what they already own. Dissolved gas analysers, bushing monitors, line sensors and acoustic partial discharge detectors let planners rank assets by actual condition instead of installation date.
The mechanism is regulatory as much as technical. Rate-regulated utilities must justify capital plans to commissions, and measured condition data supports deferral of replacements that cannot yet be funded. Wildfire liability in the western United States and storm hardening on the eastern seaboard add urgency to conductor and recloser monitoring. IEC 61850 gives substation devices a common data model, which lowers the integration cost of each additional monitored asset.
Restraints Impact Analysis
Two constraints hold realised deployment below what utility pilot programmes suggest is technically possible.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Operational technology cybersecurity obligations lengthening approval cycles | High | Europe, North America | Medium term 2–4 years |
| Integration cost of legacy substation and field equipment | Medium | Global | Long term ≥4 years |
Operational Technology Security Obligations Slow Utility Deployment Schedules
Cybersecurity review has become the longest step between a signed contract and an energised sensor network. The NIS2 Directive (EU) 2022/2555 places incident reporting, supply chain and risk management duties on energy operators, with management liability attached. In the United States, critical infrastructure protection standards govern what may connect to control systems. Every connected device therefore passes a security assessment before it reaches a substation fence.
The underlying cost is not the firewall but the engineering review. Utilities must document network segmentation, certificate lifecycles, firmware signing and patch routes for equipment expected to run for fifteen years. Many field devices were designed for availability rather than authentication, so vendors retrofit secure boot and encrypted transport. Those changes trigger re-approval by the operator, and the resulting cycle commonly adds several quarters to a rollout plan.
Legacy Field and Substation Equipment Raises the True Cost of Connectivity
Integration with installed equipment, not the sensor itself, sets the real price of a connected grid programme. A modern line monitor may cost a few hundred dollars, while bringing its data into an existing supervisory control system, historian and outage management platform costs several times more. Older relays, remote terminal units and meters speak proprietary or serial protocols that predate internet addressing.
The cause is accumulated protocol diversity. A single distribution utility can operate equipment from many vendors across several decades, each with its own register maps and firmware tools. Protocol gateways, data normalisation and point mapping become billable engineering hours rather than product revenue. Communication coverage adds further expense, because rural feeders often lack reliable cellular signal and need mesh radio, fibre or satellite backhaul funded from the same project budget.
Market Opportunities
Virtual Power Plant Orchestration Opens a Recurring Software Revenue Pool
Virtual power plant orchestration is the clearest new revenue pool in connected energy, because it is sold as a subscription rather than a one-time build. Utilities, retailers and independent aggregators need software that forecasts available flexibility, bids it into markets, dispatches thousands of devices and settles payments with customers. That function earns per-device monthly fees plus a share of market revenue, which compounds as portfolios grow.
Platform vendors, inverter manufacturers and energy retailers are all positioned to capture it. Demand comes from residential battery owners, commercial building operators and electric vehicle fleet depots that want to monetise idle capacity. Aggregation rights under Directive (EU) 2019/944 and wholesale access under FERC Order No. 2222 supply the market design, while IEEE 2030.5 supplies the control interface that makes mixed-vendor fleets dispatchable.
Methane and Pipeline Integrity Monitoring Creates a Measurement-Driven Service Market
Continuous methane and pipeline integrity monitoring opens a measurement services pool that barely existed a decade ago. Operators increasingly need emissions data that is measured rather than estimated, which creates demand for fixed point sensors, acoustic leak detection, flow balance analytics and satellite or aerial cross-checks. Revenue arrives as monitoring contracts priced per site per month, not as equipment sales.
Oilfield service companies, sensor manufacturers and analytics specialists can all serve it, often in partnership. The demand base is upstream and midstream operators facing emissions reporting duties, lender scrutiny and gas purchase contracts that reward verified intensity. Remote sites favour low-power wide area networks and satellite backhaul, and the same connectivity layer also carries pressure, vibration and cathodic protection data, which improves the economics of each installed node.
Segment Analysis
- By Component: Hardware Holds the Base While Platform Software Compounds Faster
Hardware accounted for 41% of spending in 2026, the largest share, because every connected energy programme begins with physical devices. Smart meters, line sensors, substation monitors, gateways and remote terminal units must be bought, installed and commissioned before any data exists. Platform and software is the fastest-growing component at a 14.6% CAGR through 2033, as utilities shift device management, analytics and visualisation into managed environments with annual licences. Connectivity and services sit between the two, with services benefiting from the integration work that legacy equipment demands. The implication is a gradual mix shift in revenue quality. Vendors that only sell boxes face hardware price erosion as module costs fall, while those attaching platform subscriptions to installed fleets build recurring income and keep a direct relationship with the grid operator after commissioning ends.
- By Application: Grid Monitoring Leads as Distributed Energy Management Accelerates
Grid monitoring and asset management led applications with 32% share in 2026, reflecting the scale of transmission and distribution networks and the regulated spending that supports them. Condition monitoring of transformers, feeders and switchgear delivers measurable deferral of capital replacement, which makes approval easier. Distributed energy resource management and virtual power plants form the fastest-growing application at a 16.2% CAGR, pushed by aggregation rules and by the rising count of behind-the-meter batteries and chargers. Demand response, renewable generation monitoring and oil and gas field monitoring complete the picture. For suppliers the signal is clear. Asset monitoring supplies dependable volume tied to utility rate cases, while distributed resource orchestration supplies growth and brings software vendors into contact with customer-side devices that utilities historically never touched or controlled.
- By Connectivity Technology: Cellular Networks Dominate While Satellite Links Expand Quickest
Cellular connectivity captured 34% of the market in 2026, the leading technology, because licensed networks already cover most populated service territories and offer managed quality of service. Low-power variants suit metering and sensing duty cycles with multi-year battery life. Satellite is the fastest-growing connectivity technology at a 15.8% CAGR to 2033, as falling terminal prices make remote pipelines, offshore platforms and rural feeders economic to connect for the first time. Low-power wide area networks, radio mesh and wired power line communication retain solid positions in dense metering deployments. The practical consequence is hybrid network design. Utilities and energy operators increasingly specify multiple bearers in one programme, choosing by site economics rather than committing a whole fleet to a single technology that fails at the edges of coverage.
- By End Use: Transmission and Distribution Utilities Lead, Commercial Users Rise Fastest
Transmission and distribution utilities were the largest end-use group at 38% share in 2026, since grid operators own the widest geographic spread of assets and face explicit reliability obligations. Their spending is regulated, predictable and large. Commercial and industrial energy users are growing fastest at a 15.3% CAGR through 2033, driven by on-site solar, storage, electric vehicle depots and flexibility contracts that pay for measured load reduction. Power generation and oil and gas remain substantial, with the latter weighted toward harsh-environment sensing. The business implication concerns go-to-market design. Utility sales require long qualification and framework agreements, while commercial customers buy faster and in smaller increments, so vendors need two distinct commercial motions rather than one enterprise playbook applied to every energy buyer.
Geography Analysis
- Which Region Is Leading the IoT in Energy Market?
North America leads the market with 36% share in 2026, supported by the United States and Canada. Utility spending on grid modernisation is recoverable through rate cases, which gives vendors a funded buyer with multi-year visibility. FERC Order No. 2222 created an explicit market pathway for aggregated distributed resources, and that pathway requires metering and dispatch infrastructure. Wildfire risk in California and other western states has pushed heavy investment in conductor monitoring, weather stations and fast-acting protection settings. Storm hardening along the Gulf and Atlantic coasts supports similar spending on outage detection. Shale operators in Texas and New Mexico add a large installed base of wellpad and pipeline telemetry. The main barrier is critical infrastructure protection compliance, which lengthens approval. The emerging change is interconnection queue pressure, which makes measured hosting capacity data valuable.
- Grid Flexibility Rules and Security Obligations Shape European Demand
Europe holds 27% share in 2026, the second largest position, with Germany, France, the Netherlands, Spain and the Nordic countries driving deployment. Demand is shaped by policy more than by any single technology. Directive (EU) 2019/944 established consumer aggregation and demand response rights, and the subsequent electricity market design reform strengthened flexibility procurement by system operators. The NIS2 Directive (EU) 2022/2555 and the network code on cybersecurity impose documented security duties on energy operators, which raises the specification of every connected device sold into the region. High renewable penetration makes real-time visibility of distribution networks necessary rather than optional. Smart meter penetration is uneven, with some national rollouts largely complete and others still running. The notable change is the growth of local flexibility markets that pay distribution-connected assets for congestion relief.
- Which Region Is Growing Fastest in the IoT in Energy Market?
Asia Pacific is growing fastest at a 15.1% CAGR between 2026 and 2033, from a 25% share in 2026. China drives the largest absolute volume through distribution automation, metering replacement and the sheer scale of new solar and wind capacity needing monitoring. India is expanding rapidly as state distribution companies install prepaid and communicating meters to cut commercial losses, with feeder-level monitoring following. Japan and South Korea focus on resilience, substation automation and demand response after supply tightness, while Australia has one of the highest rooftop solar densities anywhere, which forces visibility into low-voltage networks. Local manufacturing keeps hardware pricing competitive and supports volume rollouts. The constraint is uneven data governance and procurement capability across utilities. The opportunity is standardised rollouts that let vendors replicate one design across many distribution companies.
- Latin American Utilities Target Loss Reduction With Connected Metering
Latin America represents 6% of the market in 2026, with Brazil, Mexico, Chile and Colombia accounting for most activity. The commercial case here is unusually direct. Non-technical losses from theft and unbilled consumption remain high in several networks, so communicating meters and distribution transformer monitors pay back through recovered revenue rather than through efficiency alone. Brazil combines large distribution concessions with regulatory quality targets that reward reduced outage duration. Chile adds strong solar growth that requires monitoring of distribution-connected generation. Barriers are real: currency volatility raises the cost of imported hardware, financing terms are tighter, and tariff frameworks do not always allow fast recovery of digital investment. The change worth watching is the use of loss reduction savings to fund further metering phases, which turns one successful project into a repeatable programme.
- Oil, Gas and Desalination Assets Anchor Middle East & Africa Adoption
Middle East & Africa accounts for 6% of 2026 revenue, concentrated in Saudi Arabia, the United Arab Emirates, Qatar and South Africa. Hydrocarbon operations anchor demand, with extensive pipeline, wellpad and terminal telemetry already installed and expanding into emissions and integrity monitoring. Gulf utilities are adding large solar capacity alongside desalination and district cooling loads, all of which need coordinated measurement. South Africa presents a different case, where supply shortfalls have driven rapid uptake of commercial solar and storage plus monitoring to manage load curtailment. Barriers include limited communication coverage across sparsely populated areas, skills shortages in operational technology security and procurement that often favours large integrated contracts over specialist vendors. The opportunity lies in new industrial and city developments, where sensing and control can be specified at design stage instead of retrofitted later.
Competitive Landscape
The market is moderately concentrated, with a medium concentration rating that reflects two different competitive layers. Large automation and grid equipment suppliers such as Siemens AG, Schneider Electric SE, ABB Ltd. and Hitachi Energy Ltd. hold strong positions because they already supply the substations, switchgear and control systems that connected devices attach to. Metering specialists including Itron, Inc. and Landis+Gyr Group AG control a large installed communicating meter base. Around them sits a long tail of sensor makers, connectivity providers and analytics startups, which keeps the overall structure from becoming tight. Consolidation has generally taken the form of large vendors absorbing software and analytics capability rather than merging with each other.
Competition turns on a narrow set of factors. Buyers weigh interoperability with existing systems, security documentation, device lifetime and field serviceability, and the credibility of the vendor over a fifteen-year asset life. Support for IEC 61850 and IEEE 2030.5 is close to mandatory in grid tenders. New entrants arrive from adjacent directions: cloud providers offering managed data platforms, telecommunications operators bundling connectivity with device management, and inverter manufacturers that already hold a control channel into customer-owned equipment.
Strategic activity concentrates on building recurring software revenue around installed hardware, forming partnerships between connectivity providers and platform vendors, and adding cybersecurity capability to meet operator obligations. Vendors are also investing in open interfaces, because utilities increasingly refuse designs that lock data inside one supplier’s system. The common direction is a shift from selling devices toward selling measured outcomes such as avoided outages, verified flexibility or confirmed emissions reduction, with the hardware treated as the delivery mechanism rather than the product.
Recent Industry Developments
- September 2020: The Federal Energy Regulatory Commission issued Order No. 2222, requiring regional transmission organisations and independent system operators to allow distributed energy resource aggregations into wholesale markets – it created a settlement-grade telemetry requirement that underpins virtual power plant deployments.
- June 2024: The European Union adopted its electricity market design reform package, strengthening demand response, flexibility procurement and consumer aggregation provisions alongside Directive (EU) 2019/944 – it widens the addressable base for distributed resource management platforms across member states.
- June 2024: Commission Delegated Regulation (EU) 2024/1366, the network code on cybersecurity aspects of cross-border electricity flows, entered into force – it standardises security expectations that grid-connected devices and platforms must satisfy in Europe.
- October 2024: The transposition deadline for the NIS2 Directive (EU) 2022/2555 passed, extending risk management, supply chain and incident reporting duties to energy operators – it raised the security documentation burden on every connected energy product sold into the region.
Companies Covered in the Report
- Siemens AG
- Schneider Electric SE
- ABB Ltd.
- Hitachi Energy Ltd.
- General Electric Vernova Inc.
- Itron, Inc.
- Landis+Gyr Group AG
- Cisco Systems, Inc.
- Honeywell International Inc.
- Emerson Electric Co.
- Eaton Corporation plc
- Robert Bosch GmbH
IoT in Energy Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 30.0 Billion |
| Market Size 2033 | US$ 68.0 Billion |
| CAGR 2026–2033 | 12.4% |
| Absolute Dollar Opportunity | US$ 38.0 Billion |
| Largest Market | North America (36% share in 2026) |
| Fastest-Growing Market | Asia Pacific (15.1% CAGR 2026–2033) |
| Market Concentration | Medium |
| Major Players | Siemens AG, Schneider Electric SE, ABB Ltd., Itron, Inc., Cisco Systems, Inc. |
IoT in Energy Market Segmentation
Component
- Hardware
- Connectivity
- Platform and Software
- Services
Application
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
Connectivity Technology
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
End Use
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global IoT in Energy Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Aggregation Market Rules Turn Distributed Energy Telemetry Into a Compliance Purchase
- Ageing Transmission and Distribution Assets Push Utilities Toward Condition-Based Maintenance
- Restraints
- Operational Technology Security Obligations Slow Utility Deployment Schedules
- Legacy Field and Substation Equipment Raises the True Cost of Connectivity
- Market Opportunities
- Virtual Power Plant Orchestration Opens a Recurring Software Revenue Pool
- Methane and Pipeline Integrity Monitoring Creates a Measurement-Driven Service Market
- Drivers
- Global IoT in Energy Market Outlook, 2020–2033
- Global IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- Global IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- Global IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- Global IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- Global IoT in Energy Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- North America IoT in Energy Market Outlook, 2020–2033
- North America IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- North America IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- North America IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- North America IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- North America IoT in Energy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States IoT in Energy Market Outlook, by Component, 2020–2033
- United States IoT in Energy Market Outlook, by Application, 2020–2033
- United States IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- United States IoT in Energy Market Outlook, by End Use, 2020–2033
- Canada IoT in Energy Market Outlook, by Component, 2020–2033
- Canada IoT in Energy Market Outlook, by Application, 2020–2033
- Canada IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Canada IoT in Energy Market Outlook, by End Use, 2020–2033
- North America IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Europe IoT in Energy Market Outlook, 2020–2033
- Europe IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- Europe IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- Europe IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- Europe IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- Europe IoT in Energy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany IoT in Energy Market Outlook, by Component, 2020–2033
- Germany IoT in Energy Market Outlook, by Application, 2020–2033
- Germany IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Germany IoT in Energy Market Outlook, by End Use, 2020–2033
- France IoT in Energy Market Outlook, by Component, 2020–2033
- France IoT in Energy Market Outlook, by Application, 2020–2033
- France IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- France IoT in Energy Market Outlook, by End Use, 2020–2033
- Netherlands IoT in Energy Market Outlook, by Component, 2020–2033
- Netherlands IoT in Energy Market Outlook, by Application, 2020–2033
- Netherlands IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Netherlands IoT in Energy Market Outlook, by End Use, 2020–2033
- Spain IoT in Energy Market Outlook, by Component, 2020–2033
- Spain IoT in Energy Market Outlook, by Application, 2020–2033
- Spain IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Spain IoT in Energy Market Outlook, by End Use, 2020–2033
- Nordic countries IoT in Energy Market Outlook, by Component, 2020–2033
- Nordic countries IoT in Energy Market Outlook, by Application, 2020–2033
- Nordic countries IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Nordic countries IoT in Energy Market Outlook, by End Use, 2020–2033
- Europe IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Asia Pacific IoT in Energy Market Outlook, 2020–2033
- Asia Pacific IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- Asia Pacific IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- Asia Pacific IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- Asia Pacific IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- Asia Pacific IoT in Energy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China IoT in Energy Market Outlook, by Component, 2020–2033
- China IoT in Energy Market Outlook, by Application, 2020–2033
- China IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- China IoT in Energy Market Outlook, by End Use, 2020–2033
- India IoT in Energy Market Outlook, by Component, 2020–2033
- India IoT in Energy Market Outlook, by Application, 2020–2033
- India IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- India IoT in Energy Market Outlook, by End Use, 2020–2033
- Japan IoT in Energy Market Outlook, by Component, 2020–2033
- Japan IoT in Energy Market Outlook, by Application, 2020–2033
- Japan IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Japan IoT in Energy Market Outlook, by End Use, 2020–2033
- South Korea IoT in Energy Market Outlook, by Component, 2020–2033
- South Korea IoT in Energy Market Outlook, by Application, 2020–2033
- South Korea IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- South Korea IoT in Energy Market Outlook, by End Use, 2020–2033
- Australia IoT in Energy Market Outlook, by Component, 2020–2033
- Australia IoT in Energy Market Outlook, by Application, 2020–2033
- Australia IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Australia IoT in Energy Market Outlook, by End Use, 2020–2033
- Asia Pacific IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Latin America IoT in Energy Market Outlook, 2020–2033
- Latin America IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- Latin America IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- Latin America IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- Latin America IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- Latin America IoT in Energy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil IoT in Energy Market Outlook, by Component, 2020–2033
- Brazil IoT in Energy Market Outlook, by Application, 2020–2033
- Brazil IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Brazil IoT in Energy Market Outlook, by End Use, 2020–2033
- Mexico IoT in Energy Market Outlook, by Component, 2020–2033
- Mexico IoT in Energy Market Outlook, by Application, 2020–2033
- Mexico IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Mexico IoT in Energy Market Outlook, by End Use, 2020–2033
- Chile IoT in Energy Market Outlook, by Component, 2020–2033
- Chile IoT in Energy Market Outlook, by Application, 2020–2033
- Chile IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Chile IoT in Energy Market Outlook, by End Use, 2020–2033
- Colombia IoT in Energy Market Outlook, by Component, 2020–2033
- Colombia IoT in Energy Market Outlook, by Application, 2020–2033
- Colombia IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Colombia IoT in Energy Market Outlook, by End Use, 2020–2033
- Latin America IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Middle East & Africa IoT in Energy Market Outlook, 2020–2033
- Middle East & Africa IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Connectivity
- Platform and Software
- Services
- Middle East & Africa IoT in Energy Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
- Middle East & Africa IoT in Energy Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
- Middle East & Africa IoT in Energy Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
- Middle East & Africa IoT in Energy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia IoT in Energy Market Outlook, by Component, 2020–2033
- Saudi Arabia IoT in Energy Market Outlook, by Application, 2020–2033
- Saudi Arabia IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Saudi Arabia IoT in Energy Market Outlook, by End Use, 2020–2033
- United Arab Emirates IoT in Energy Market Outlook, by Component, 2020–2033
- United Arab Emirates IoT in Energy Market Outlook, by Application, 2020–2033
- United Arab Emirates IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- United Arab Emirates IoT in Energy Market Outlook, by End Use, 2020–2033
- Qatar IoT in Energy Market Outlook, by Component, 2020–2033
- Qatar IoT in Energy Market Outlook, by Application, 2020–2033
- Qatar IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- Qatar IoT in Energy Market Outlook, by End Use, 2020–2033
- South Africa IoT in Energy Market Outlook, by Component, 2020–2033
- South Africa IoT in Energy Market Outlook, by Application, 2020–2033
- South Africa IoT in Energy Market Outlook, by Connectivity Technology, 2020–2033
- South Africa IoT in Energy Market Outlook, by End Use, 2020–2033
- Middle East & Africa IoT in Energy Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Siemens AG
- Schneider Electric SE
- ABB Ltd.
- Hitachi Energy Ltd.
- General Electric Vernova Inc.
- Itron, Inc.
- Landis+Gyr Group AG
- Cisco Systems, Inc.
- Honeywell International Inc.
- Emerson Electric Co.
- Eaton Corporation plc
- Robert Bosch GmbH
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Component
- Hardware
- Connectivity
- Platform and Software
- Services
Application
- Grid Monitoring and Asset Management
- Distributed Energy Resource Management and Virtual Power Plants
- Demand Response and Energy Management
- Renewable Generation Monitoring
- Oil and Gas Field and Pipeline Monitoring
Connectivity Technology
- Cellular
- Low-Power Wide Area Network
- Radio Mesh and Wi-Fi
- Wired and Power Line Communication
- Satellite
End Use
- Power Generation
- Transmission and Distribution Utilities
- Oil and Gas
- Commercial and Industrial Energy Users
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 30.0 billion in 2026, covering hardware, connectivity, platform software and services across the global energy value chain.
The market is projected to reach US$ 68.0 billion by 2033, growing at a 12.4% CAGR and adding US$ 38.0 billion over the forecast period.
Hardware leads with 41% share in 2026, because sensors, meters, gateways and monitors must be installed before any energy data can be collected.
Asia Pacific grows fastest at a 15.1% CAGR to 2033, led by metering and distribution automation programmes in China, India and Australia.
Concentration is medium: large automation and metering suppliers hold strong positions, while many sensor, connectivity and analytics specialists compete around them.
Related Reports
Power EPC Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Power EPC Market is projected to rise from US$ 780.56 billion in 2026 to US$ 1,220.97 billion by 2033 at a 6.6% CAGR. Explore generation and project trends.
Port Electrification Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the port electrification market, valued at US$ 6.8 billion in 2026 and forecast to reach US$ 16.4 billion by 2033, growing at a 13.4% CAGR.
Polycrystalline Solar Cell Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the polycrystalline solar cell market, valued at US$ 5.4 billion in 2026 and projected to reach US$ 6.6 billion by 2033, growing at 2.9% CAGR.
Synchronous Condenser Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global synchronous condenser market is valued at US$1.20 billion in 2026, reaching US$1.50 billion by 2033, growing at a 3.2% CAGR
Water and Wastewater Treatment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Water and wastewater treatment market to reach US$ 508.0 billion by 2033 from US$ 345.0 billion in 2026 at a 5.7% CAGR. Explore trends, segments and regions.
Vehicle-to-Grid Technology Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the vehicle-to-grid technology market, forecast to reach US$6.9 billion by 2033 at 28.4% CAGR, with component, application and regional insights.