


Lubricants in Power Generation Market
Lubricants in Power Generation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Lubricants in Power Generation Market Size and Trend Analysis
How Fast Is the Lubricants in Power Generation Market Growing?
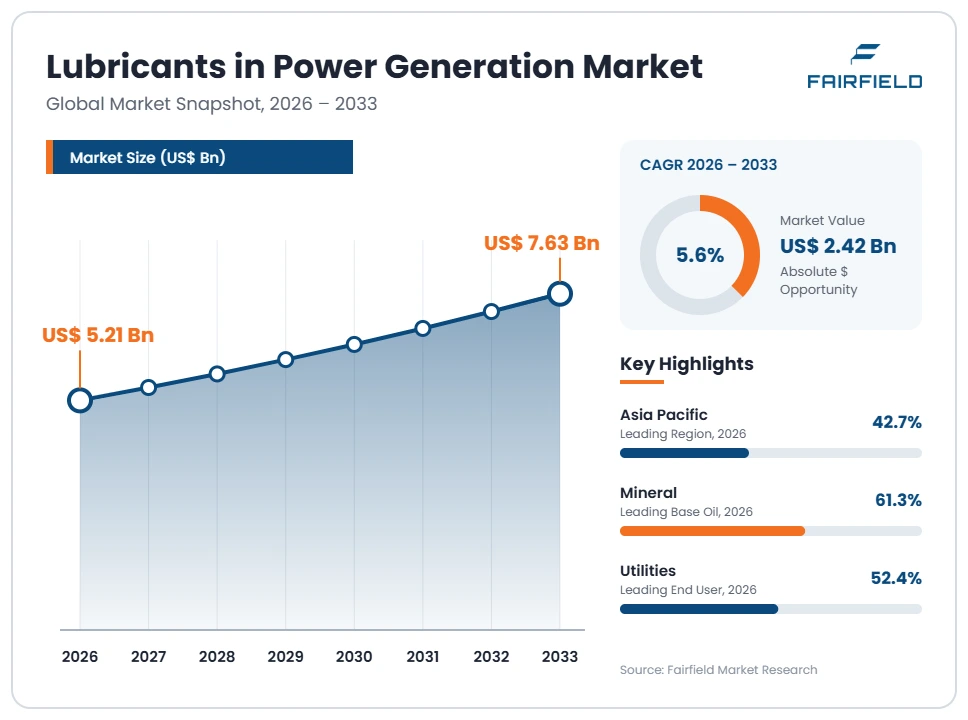
The global lubricants in power generation market size is expected to be valued at US$ 5.21 billion in 2026 and projected to reach US$ 7.63 billion by 2033, growing at a CAGR of 5.6% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 3.8%, as global electricity demand recovered after the pandemic and wind capacity additions accelerated. Three factors now support growth: rapid expansion of wind power, rising electricity demand that keeps gas turbine fleets running harder, and wider use of synthetic lubricants that protect high-value equipment. The market is shifting away from high-volume mineral oils for coal plants toward premium turbine oil, wind turbine gear oil, and condition monitoring services that extend equipment life and reduce unplanned outages.
Key Report Takeaways
- By Product Type: Turbine Oil held 44.6% share in 2026, while Gear Oil is projected to expand at a 7.2% CAGR through 2033, driven by larger wind gearboxes needing micropitting-resistant oils.
- By Base Oil: Mineral held 61.3% share in 2026, while Synthetic is projected to expand at a 7.6% CAGR through 2033, driven by longer drain intervals and better performance at extreme temperatures.
- By Power Plant Type: Steam Turbine Plants held 36.2% share in 2026, while Wind Power is projected to expand at a 9.1% CAGR through 2033, driven by record onshore and offshore capacity additions.
- By End User: Utilities held 52.4% share in 2026, while Independent Power Producers are projected to expand at a 6.8% CAGR through 2033, driven by private wind, hybrid, and gas peaking projects.
- By Region: Asia Pacific held 42.7% share in 2026, while India is projected to expand at a 7.4% CAGR through 2033, driven by new thermal, gas, and renewable capacity to meet fast-rising demand.
Global Lubricants in Power Generation Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on lubricant demand in power generation during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rapid wind power capacity expansion | High | Asia Pacific, Europe, North America | Long term (≥4 years) |
| Rising electricity demand and gas turbine utilization | Medium | Global, strongest in North America and Middle East & Africa | Medium term (2–4 years) |
Wind Power Expansion Is Lifting Demand for Gear Oils and Greases in Power Generation
Rapid growth in wind power is the strongest growth driver for lubricants in power generation. Every wind turbine needs gear oil for its gearbox and specialized greases for main bearings, pitch bearings, and yaw systems. As turbines grow larger, lubricant volumes and performance requirements both increase.
The evidence is record capacity growth. International Renewable Energy Agency data show global installed wind capacity reached 1,133 GW by the end of 2024, after 113 GW was added during the year, an increase of 11.1% over 2023. Offshore turbines face salt and difficult access, so operators prefer long-life synthetic lubricants. In August 2024, Klüber Lubrication introduced a gear oil booster and a rescue grease for wind turbine gearboxes and bearings, showing how suppliers are tailoring products to this fast-growing fleet.
Rising Electricity Demand Keeps Gas Turbines Running and Raises Turbine Oil Consumption
Rising electricity demand is increasing the operating hours of gas and steam turbine fleets, which lifts turbine oil consumption. Higher utilization means more oil top-ups, more frequent oil analysis, and earlier replacement when oils degrade. New gas plants also need large initial fills.
The cause is broad growth in power use. The International Energy Agency reported that global electricity demand rose 4.3% in 2024 and expects growth close to 4% a year through 2027, driven by industry, air conditioning, electric vehicles, and data centers. Gas turbines provide flexible capacity that balances variable wind and solar output, so they often run in demanding cycling modes. Frequent starts and stops raise oil temperatures and oxidation stress. This favors high-performance turbine oil with strong oxidation stability, which carries higher prices than standard grades.
Restraints Impact Analysis
Two restraints limit lubricant volume growth in the power generation sector.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Coal plant retirements in mature markets | Medium | Europe, North America | Long term (≥4 years) |
| Base oil and additive cost volatility | Medium | Global | Short term (≤2 years) |
Coal Plant Retirements Reduce Lubricant Volumes in Power Generation
The retirement of coal-fired power plants reduces lubricant demand in mature markets. Coal plants use large volumes of turbine oil, gear oil for coal handling and pulverizers, and greases for conveyors and fans. When these plants close, their lubricant demand disappears.
The underlying cause is decarbonization policy. In September 2024, Uniper closed the Ratcliffe-on-Soar power station, ending coal-fired power generation in the United Kingdom. Many countries in Europe have set coal phase-out dates, and United States utilities keep retiring older units. Renewable plants such as solar farms use very little lubricant, and wind turbines need smaller volumes per megawatt than coal plants. Longer drain intervals from synthetic lubricants also lower volume demand. These shifts mean suppliers must grow revenue through higher-value products rather than volume.
Base Oil and Additive Cost Volatility Squeezes Margins in Power Generation Lubricants
Volatile costs for base oils and additives squeeze margins for power generation lubricant suppliers. Utilities often sign long-term supply contracts with fixed or slowly adjusting prices, while raw material costs can change quickly.
The specific cost sources are crude oil prices, refinery base oil supply, specialty additives, and trade policy. Group II and Group III base oils and synthetic stocks such as polyalphaolefins depend on refinery and petrochemical capacity. Anti-oxidant, anti-wear, and anti-foam additives come from a small group of suppliers. Tariffs on imported base oils and additives have raised costs in some markets, with notable effects on turbine lubricants in Asia Pacific and Europe. Shipping disruptions add further cost. Suppliers must either absorb these increases or renegotiate contracts, which can strain relationships with large utility customers.
Market Opportunities
Lubricant Condition Monitoring Services Open a Value-Added Revenue Pool in Power Generation
Lubricant condition monitoring services create a growing, higher-margin revenue pool. Power plants want to detect oil degradation, contamination, and varnish before they cause turbine trips or bearing failures. Continuous monitoring helps them extend oil life and plan maintenance with greater confidence.
Lubricant suppliers, testing laboratories, and sensor companies can capture this demand. Online sensors now track moisture, particles, oxidation, and viscosity in real time, and AI analytics turn this data into maintenance alerts. Some suppliers are testing sensor-based monitoring for hydro generators and other critical assets. Utilities, independent power producers, and wind farm operators are the main customers, especially where unplanned outages are costly. By bundling oils with monitoring, varnish removal, and filtration services, suppliers can shift from selling barrels to selling uptime, which raises customer loyalty and margins.
Environmentally Acceptable Lubricants Create a New Revenue Pool for Hydro and Offshore Power
Environmentally acceptable lubricants create an emerging revenue pool for hydropower and offshore wind. These biodegradable, low-toxicity products sharply reduce environmental risk if oil leaks into rivers, reservoirs, or the sea.
Specialty lubricant makers and major oil companies with ester and bio-based technology can capture this opportunity. Hydropower plants operate turbines, wicket gates, and bearings in direct contact with water, so leaks can harm aquatic ecosystems. Offshore wind farms face similar concerns. Suppliers are piloting plant-based turbine oils for wind farms, with field tests reporting longer service cycles and good corrosion protection. Hydro operators, offshore developers, and regulators focused on water quality are the main customers. Stricter environmental permits in Europe and North America encourage the switch, and these products sell at significant premiums to conventional mineral oils.
Segment Analysis
- By Product Type: Turbine Oil Leads While Gear Oil Expands Fastest
Turbine Oil held 44.6% share in 2026. Steam, gas, and hydro turbines all depend on turbine oil to lubricate bearings, cool components, and operate control systems. Large turbines hold thousands of liters of oil, and operators replace or top up oil regularly to maintain performance.
Gear Oil is the fastest-growing product type, expanding at a 7.2% CAGR through 2033. Wind turbine gearboxes face high loads, variable speeds, and difficult maintenance access, so they need gear oils that resist micropitting, foaming, and water contamination. Larger turbines need larger gearboxes and higher oil volumes. Transformer oil, compressor oil, and engine oil also serve power plants. For the market, gear oil growth shifts value toward premium synthetic products with strong technical support.
- By Base Oil: Mineral Leads While Synthetic Lubricants Grow Fastest
Mineral held 61.3% share in 2026. Refined Group I and Group II mineral oils remain the standard for many turbine and transformer applications because they are well understood, widely available, and lower in cost. Large coal, gas, and hydro plants use them in high volumes.
Synthetic is the fastest-growing base oil type, expanding at a 7.6% CAGR through 2033. Synthetic lubricants based on polyalphaolefins and esters offer better oxidation stability, wider temperature ranges, and longer drain intervals. These benefits matter in wind turbines, offshore sites, and gas turbines that cycle frequently. Although synthetics cost more per liter, they reduce maintenance visits and downtime. Bio-based oils are a smaller but growing niche. For the broader market, synthetic adoption raises average selling prices even as total volumes grow slowly.
- By Power Plant Type: Steam Turbine Plants Lead While Wind Power Grows Fastest
Steam Turbine Plants held 36.2% share in 2026. Coal and nuclear plants use large steam turbines and extensive auxiliary equipment, including pumps, fans, pulverizers, and conveyors. These plants consume high volumes of turbine oil, gear oil, and grease, especially in China and India, where coal remains central to power supply.
Wind Power is the fastest-growing plant type, expanding at a 9.1% CAGR through 2033. Global wind capacity passed 1,133 GW by the end of 2024, and new offshore projects use larger turbines with higher lubricant demand per unit. Gearboxes, bearings, pitch systems, and yaw drives all need specialized lubricants. For the market, wind growth offsets coal retirements in mature regions and rewards suppliers with proven wind turbine gear oil and grease products.
- By End User: Utilities Lead While Independent Power Producers Expand Fastest
Utilities held 52.4% share in 2026. State-owned and investor-owned utilities operate most of the world's large coal, nuclear, hydro, and gas plants. They buy through long-term framework contracts and require turbine maker approvals and on-site technical support.
Independent Power Producers are the fastest-growing end user, expanding at a 6.8% CAGR through 2033. Private developers build much of the new wind, gas peaking, and hybrid capacity under long-term power purchase agreements. These operators focus on availability and operating cost, so they favor long-life synthetic lubricants and condition monitoring that reduce site visits. Captive plants at factories and data centers add further demand. For the market, the rise of private producers increases competition among suppliers and rewards those offering bundled lubrication and service packages.
Geography Analysis
- North America Balances Gas Growth and Coal Retirements in Power Generation Lubricants
North America is a mature market where gas, wind, and nuclear power shape lubricant demand. The United States has a large gas turbine fleet that runs more often as electricity demand rises from data centers and electrification. Wind capacity in Texas, Iowa, and other states adds demand for gear oil and greases. Coal retirements in the Midwest and Southeast steadily reduce volumes of turbine oil and greases. Canada relies heavily on hydropower, which needs turbine oil and environmentally acceptable lubricants. One change shaping the region is utilities' use of condition monitoring to extend oil life and avoid costly outages in aging plants.
- Europe Shifts Toward Wind and Hydro in Power Generation Lubricants
Europe is a mature market moving away from coal toward wind, solar, hydro, and gas. The United Kingdom ended coal power when Uniper closed Ratcliffe-on-Soar in September 2024. Germany, Spain, Denmark, and the Netherlands all have large onshore and offshore wind fleets that require premium gear oils and greases. France operates a large nuclear fleet with strict, safety-driven lubricant specifications. Hydropower in Norway, Sweden, and the Alps drives demand for biodegradable products near sensitive waterways. One opportunity is offshore wind growth in the North Sea, which favors long-life synthetic lubricants.
- Which Region Is Leading the Lubricants in Power Generation Market?
Asia Pacific is leading the lubricants in power generation market with a 42.7% share in 2026. China has the world's largest coal, wind, and hydro fleets, and continues to add capacity across all three. Large coal plants consume high volumes of turbine oil and greases, while wind expansion boosts gear oil demand. Sinopec and PetroChina supply much of the domestic market. Japan and South Korea add demand from gas and nuclear plants. Southeast Asian countries are building new gas and coal capacity. One opportunity is supplying premium synthetic lubricants to new offshore wind projects in China, Taiwan, and South Korea.
- Which Country Is Growing Fastest in the Lubricants in Power Generation Market?
India is growing fastest in the lubricants in power generation market at a 7.4% CAGR through 2033. Electricity demand is rising quickly with industrial growth, urbanization, and air conditioning use. India is adding coal capacity to meet peak demand while rapidly expanding wind and solar. Wind farms in Gujarat and Tamil Nadu need gear oils and greases. State utilities and private producers are investing in plant upgrades, flexible operation, and new hydro and pumped-storage projects. Domestic suppliers such as Indian Oil Corporation compete with global brands. One opportunity is condition monitoring services for aging thermal plants seeking higher reliability.
- Latin America Builds on Hydropower in Power Generation Lubricants
Latin America is a developing region where hydropower and new wind capacity shape lubricant demand. Brazil relies very heavily on its large hydro plants, such as Itaipu, and has a fast-growing wind sector in the northeast. Chile and Mexico are steadily adding wind, solar, and gas capacity. Key barriers include currency volatility that raises the cost of imported premium lubricants, limited local blending capacity, and budget constraints at state utilities. Long distances to remote wind farms raise service and delivery costs considerably for suppliers. One opportunity is supplying environmentally acceptable lubricants to hydro plants facing stricter water protection rules.
- Middle East & Africa Expands Gas and Renewable Capacity in Power Generation Lubricants
Middle East & Africa is a growing region led by gas-fired power and new renewables. Saudi Arabia, the United Arab Emirates, and Qatar operate large gas turbine fleets in hot climates, where high temperatures stress turbine oils. These countries are also adding solar and some wind capacity. In Africa, South Africa relies on coal and is adding renewables, while Egypt and Morocco are building wind farms. Key barriers include harsh desert and coastal operating conditions, limited technical support in remote areas, and funding gaps. One opportunity is high-temperature synthetic turbine oils for Gulf gas plants.
Competitive Landscape
The lubricants in power generation market is moderately concentrated. Major integrated oil companies, including Shell, ExxonMobil, TotalEnergies, Chevron, and BP through Castrol, supply a large share of turbine and gear oils worldwide. Sinopec and PetroChina lead in China, while Indian Oil Corporation is strong in India. Specialists such as Fuchs, Klüber Lubrication, and Lubrizol focus on high-performance and niche power applications.
Suppliers compete on product performance, original equipment manufacturer approvals, technical service, and global supply reliability. Approvals from turbine makers are especially critical because operators rarely risk unapproved oils in high-value equipment. Condition monitoring, oil analysis laboratories, and on-site services increasingly differentiate suppliers in long utility tenders.
Strategic moves show how competition is changing. Klüber Lubrication introduced a gear oil booster and rescue grease for wind turbines in August 2024, targeting the growing wind maintenance market. ExxonMobil secured approval for Mobil SHC Gear 320 WT across all GE wind turbines, which strengthens its position in wind gearbox lubrication. Suppliers are also piloting plant-based turbine oils and sensor-based monitoring. These moves show companies building portfolios around renewable power rather than relying on coal-related volumes.
Three main themes now shape vendor strategy. First, suppliers are expanding synthetic and bio-based product lines for wind, hydro, and offshore assets. Second, they are bundling lubricants with monitoring, filtration, and varnish control services. Third, they are strengthening partnerships with turbine makers to secure approvals early in new turbine designs.
Recent Industry Developments
- March 2025: International Renewable Energy Agency reported global wind capacity of 1,133 GW at the end of 2024 – confirms a fast-growing base for wind lubricants.
- September 2024: Uniper closed the Ratcliffe-on-Soar coal plant, ending coal power in the United Kingdom – illustrates the decline of coal-related lubricant volumes.
- August 2024: Klüber Lubrication introduced a gear oil booster and rescue grease for wind turbines – targets maintenance needs of aging wind gearboxes.
Companies Covered in the Report
- Shell
- ExxonMobil
- TotalEnergies
- Chevron
- BP (Castrol)
- Sinopec
- PetroChina
- Idemitsu Kosan
- Fuchs
- Klüber Lubrication
- Lubrizol
- Indian Oil Corporation
Lubricants in Power Generation Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 5.21 Billion |
| Market Size 2033 | US$ 7.63 Billion |
| CAGR 2026–2033 | 5.6% |
| Absolute Dollar Opportunity | US$ 2.42 Billion |
| Largest Market | Asia Pacific |
| Fastest-Growing Market | India |
| Market Concentration | Medium |
| Major Players | Shell, ExxonMobil, TotalEnergies, Chevron, Sinopec |
Lubricants in Power Generation Market Segmentation
Product Type
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
End User
- Utilities
- Independent Power Producers
- Captive & Industrial Power
Base Oil
- Mineral
- Synthetic
- Bio-based
Power Plant Type
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Lubricants in Power Generation Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Wind Power Expansion Is Lifting Demand for Gear Oils and Greases in Power Generation
- Rising Electricity Demand Keeps Gas Turbines Running and Raises Turbine Oil Consumption
- Restraints
- Coal Plant Retirements Reduce Lubricant Volumes in Power Generation
- Base Oil and Additive Cost Volatility Squeezes Margins in Power Generation Lubricants
- Market Opportunities
- Lubricant Condition Monitoring Services Open a Value-Added Revenue Pool in Power Generation
- Environmentally Acceptable Lubricants Create a New Revenue Pool for Hydro and Offshore Power
- Drivers
- Global Lubricants in Power Generation Market Outlook, 2020–2033
- Global Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- Global Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- Global Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- Global Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- Global Lubricants in Power Generation Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Lubricants in Power Generation Market Outlook, 2020–2033
- North America Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- North America Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- North America Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- North America Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- North America Lubricants in Power Generation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- United States Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- United States Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- United States Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Canada Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Canada Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Canada Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Canada Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- North America Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Lubricants in Power Generation Market Outlook, 2020–2033
- Europe Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- Europe Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- Europe Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- Europe Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- Europe Lubricants in Power Generation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Kingdom Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- United Kingdom Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- United Kingdom Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- United Kingdom Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Germany Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Germany Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Germany Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Germany Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Spain Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Spain Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Spain Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Spain Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Denmark Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Denmark Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Denmark Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Denmark Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Netherlands Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Netherlands Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Netherlands Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Netherlands Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- France Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- France Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- France Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- France Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Norway Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Norway Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Norway Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Norway Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Sweden Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Sweden Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Sweden Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Sweden Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Europe Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Lubricants in Power Generation Market Outlook, 2020–2033
- Asia Pacific Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- Asia Pacific Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- Asia Pacific Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- Asia Pacific Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- Asia Pacific Lubricants in Power Generation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- China Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- China Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- China Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Japan Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Japan Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Japan Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Japan Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- South Korea Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- South Korea Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- South Korea Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- South Korea Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Taiwan Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Taiwan Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Taiwan Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Taiwan Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- India Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- India Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- India Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- India Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Asia Pacific Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Lubricants in Power Generation Market Outlook, 2020–2033
- Latin America Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- Latin America Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- Latin America Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- Latin America Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- Latin America Lubricants in Power Generation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Brazil Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Brazil Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Brazil Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Chile Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Chile Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Chile Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Chile Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Mexico Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Mexico Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Mexico Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Mexico Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Latin America Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Lubricants in Power Generation Market Outlook, 2020–2033
- Middle East & Africa Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
- Middle East & Africa Lubricants in Power Generation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Utilities
- Independent Power Producers
- Captive & Industrial Power
- Middle East & Africa Lubricants in Power Generation Market Outlook, by Base Oil, Value (US$ Billion), 2020–2033
- Mineral
- Synthetic
- Bio-based
- Middle East & Africa Lubricants in Power Generation Market Outlook, by Power Plant Type, Value (US$ Billion), 2020–2033
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
- Middle East & Africa Lubricants in Power Generation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Saudi Arabia Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Saudi Arabia Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- United Arab Emirates Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- United Arab Emirates Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- United Arab Emirates Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Qatar Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Qatar Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Qatar Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Qatar Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- South Africa Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- South Africa Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- South Africa Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- South Africa Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Egypt Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Egypt Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Egypt Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Egypt Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Morocco Lubricants in Power Generation Market Outlook, by Product Type, 2020–2033
- Morocco Lubricants in Power Generation Market Outlook, by End User, 2020–2033
- Morocco Lubricants in Power Generation Market Outlook, by Base Oil, 2020–2033
- Morocco Lubricants in Power Generation Market Outlook, by Power Plant Type, 2020–2033
- Middle East & Africa Lubricants in Power Generation Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Shell
- ExxonMobil
- TotalEnergies
- Chevron
- BP (Castrol)
- Sinopec
- PetroChina
- Idemitsu Kosan
- Fuchs
- Klüber Lubrication
- Lubrizol
- Indian Oil Corporation
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Turbine Oil
- Gear Oil
- Transformer Oil
- Compressor Oil
- Engine Oil
- Greases
End User
- Utilities
- Independent Power Producers
- Captive & Industrial Power
Base Oil
- Mineral
- Synthetic
- Bio-based
Power Plant Type
- Steam Turbine Plants
- Gas Turbine Plants
- Hydropower
- Wind Power
- Diesel & Gas Engine Plants
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The lubricants in power generation market is valued at US$ 5.21 billion in 2026, led by turbine oil for steam and gas turbines.
The market is projected to reach US$ 7.63 billion by 2033, growing at a 5.6% CAGR and adding US$ 2.42 billion.
Turbine Oil leads with 44.6% share in 2026, supported by its use in bearings and control systems of steam, gas, and hydro turbines.
Wind Power is growing fastest at a 9.1% CAGR through 2033, driven by record onshore and offshore wind capacity additions.
Asia Pacific holds the largest share at 42.7% in 2026, supported by large coal, wind, and hydro fleets in China.
Related Reports
Smart Hydraulics Fluid Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global smart hydraulics fluid market is valued at US$5.28 billion in 2026, reaching US$7.89 billion by 2033, growing at a 5.9% CAGR
Battery Manufacturing Equipment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global battery manufacturing equipment market is valued at US$18.02 billion in 2026, reaching US$26.06 billion by 2033, growing at a 5.4% CAGR
Transformer Oil Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global transformer oil market is valued at US$3.5 billion in 2026, reaching US$5.5 billion by 2033, growing at a 6.7% CAGR
Impact Investing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Impact Investing Market to reach US$612 Bn by 2033, growing at 11.5% CAGR, driven by sustainable finance, climate projects, and institutional investment.
Carbon Credit Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Carbon Credit Market to reach US$9.8 Bn by 2033, growing at 20.9% CAGR, driven by aviation offsets, carbon removals, and climate regulations.
Redox Flow Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Redox Flow Battery Market to reach US$5.8 Bn by 2033, growing at 26.8% CAGR, driven by long-duration storage, grid stability, and clean energy adoption.