


Mechanical Ventilators Market
Mechanical Ventilators Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Mechanical Ventilators Market Size and Trend Analysis
How Fast Is the Mechanical Ventilators Market Growing?
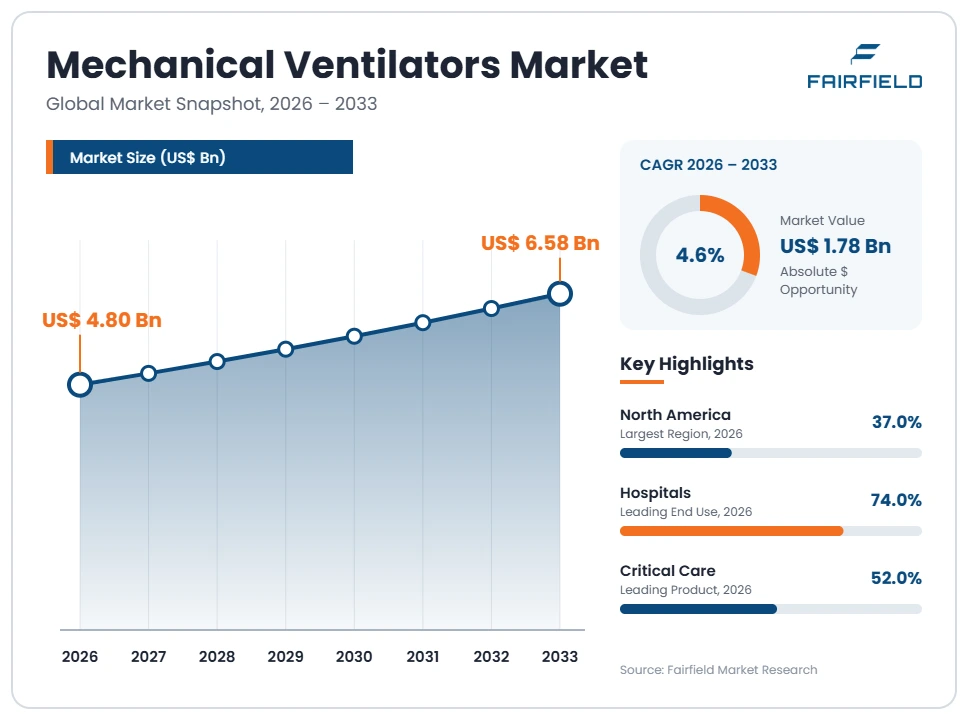
The global mechanical ventilators market size is expected to be valued at US$ 4.80 billion in 2026 and projected to reach US$ 6.58 billion by 2033, growing at a CAGR of 4.6% between 2026 and 2033.
Between 2020 and 2025, the market was highly volatile: sales surged in 2020 as governments bought huge numbers of ventilators during the COVID-19 pandemic, then fell sharply as stockpiles filled and demand normalized. Mechanical ventilators support or replace breathing for patients with respiratory failure caused by lung disease, injury, surgery, or infection. Three factors now drive steady growth: aging populations with chronic lung and heart disease, the expansion of intensive care units in emerging economies, and the move toward home ventilation for patients with long-term breathing problems. The market is shifting toward smart critical care ventilation with automated weaning, closed-loop oxygen control, and large touchscreens, portable units for transport and emergencies, and non-invasive ventilation that avoids breathing tubes. Product recalls in 2026 at Philips and React Health show how important safety and quality have become.
Key Report Takeaways
- By Product: Critical Care held 52.0% share in 2026, while Transport and Portable is projected to expand at a 6.0% CAGR through 2033, driven by emergency medical services, patient transfers, and home use.
- By Ventilation Mode: Invasive held 63.0% share in 2026, while Non-Invasive is projected to expand at a 5.8% CAGR through 2033, driven by the use of masks and high-flow therapy to avoid intubation.
- By End Use: Hospitals held 74.0% share in 2026, while Home Healthcare is projected to expand at a 6.6% CAGR through 2033, driven by chronic respiratory disease and neuromuscular conditions.
- By Region: North America held 37.0% share in 2026, while Asia Pacific is projected to expand at a 6.3% CAGR through 2033, driven by intensive care expansion in China, India, and Indonesia.
Global Mechanical Ventilators Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on mechanical ventilators demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising chronic respiratory disease and aging | High | Global | Long term (≥4 years) |
| Expansion of intensive care capacity | High | Asia Pacific, Latin America, Middle East & Africa | Medium term (2–4 years) |
Chronic Respiratory Disease Is Driving the Mechanical Ventilators Market
Rising chronic respiratory disease and aging populations are the strongest driver of the mechanical ventilators market. More patients need breathing support.
The mechanism is the link between age, disease, and respiratory failure. Chronic obstructive pulmonary disease is one of the leading causes of death worldwide, and many patients need ventilation during flare-ups or as the disease progresses. Older adults are more likely to need ventilation after major surgery, heart attacks, strokes, and severe infections such as pneumonia and influenza. Premature babies often need specialized neonatal ventilators for weeks. Air pollution and smoking continue to raise lung disease rates in Asia Pacific, Middle East & Africa, and other regions. Neuromuscular diseases such as ALS and muscular dystrophy require long-term home ventilation. These factors create steady replacement and new demand for ventilators in hospitals and homes.
Intensive Care Expansion Is Expanding the Mechanical Ventilators Market
The expansion of intensive care capacity is expanding the mechanical ventilators market. Many countries are adding critical care beds after the pandemic exposed shortages.
The cause is investment in health system resilience. Governments in India, China, Indonesia, Brazil, Saudi Arabia, and other countries are building new hospitals and intensive care units, each needing critical care ventilation. Pandemic preparedness plans call for reserve capacity, oxygen supply, and modern equipment. Hospitals in wealthy countries are gradually replacing older ventilators bought before or during the pandemic with smarter models. New ventilators offer automated weaning, lung-protective modes, and integration with hospital monitoring systems. Hamilton Medical premiered a reinvented HAMILTON-C6 in 2025. Training programs and simulation centers help staff use advanced features safely. These trends support growth in both emerging and mature markets.
Restraints Impact Analysis
Two restraints limit how quickly the mechanical ventilators market grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Post-pandemic oversupply and budget limits | High | North America, Europe | Short term (≤2 years) |
| Product recalls and strict regulation | Medium | Global | Medium term (2–4 years) |
Post-Pandemic Oversupply Slows the Mechanical Ventilators Market
Post-pandemic oversupply and budget limits slow the mechanical ventilators market. Many hospitals and governments already own large numbers of ventilators.
The specific causes are pandemic buying and tight budgets. During 2020 and 2021, governments bought tens of thousands of ventilators, and many remain in storage or lightly used. This reduces the need for new purchases in the short term, especially in North America and Europe. Hospital budgets are under pressure from labor costs and inflation, and capital spending often goes to other priorities. Some emergency ventilators bought during the pandemic were basic models that hospitals do not want to use daily. Low-cost producers in China have added strong price competition. Some hospitals also extend the life of existing ventilators through service and refurbishment rather than buying new ones. These factors slow replacement cycles in mature markets.
Recalls and Regulation Restrict the Mechanical Ventilators Market
Product recalls and strict regulation restrict the mechanical ventilators market. Ventilators are life-support devices, and failures can be fatal.
The underlying causes are high safety standards and recent quality problems. Philips recalled millions of breathing devices, including ventilators, after 2021 because of foam that could break down, leading to large costs and a consent decree with US regulators. In April 2026, Philips issued another recall notice for Trilogy Evo ventilators, and in May 2026, React Health issued a Class I recall of VOCSN ventilators. Regulators require extensive testing, cybersecurity protections, and close post-market monitoring of field problems. Supply chain problems for chips and parts after 2020 also delayed production for some makers. Hospitals now ask for stronger evidence of quality before buying. These factors raise costs, delay launches, and can damage brand trust.
Market Opportunities
Home Ventilation Opens a Chronic Care Revenue Pool
Home ventilation opens a chronic care revenue pool in the mechanical ventilators market. More patients with long-term breathing problems are treated at home.
Manufacturers of compact, quiet, and connected ventilators can capture this opportunity. Patients with COPD, ALS, muscular dystrophy, spinal cord injuries, and obesity-related breathing problems can live at home with ventilators instead of staying in hospitals or care facilities. Home care lowers costs for health systems and improves quality of life for patients and families. Remote monitoring lets clinicians check settings, usage, and alarms from a distance. ResMed, Philips, and Breas Medical offer home ventilators. Rental and service models add recurring revenue. Insurers increasingly pay for home ventilation programs. Training for families and caregivers is an added service that suppliers can offer. Aging populations in Japan, Europe, and North America will keep demand rising.
Smart and Automated Ventilation Creates a Premium Revenue Pool
Smart and automated ventilation creates a premium revenue pool in the mechanical ventilators market. Hospitals want ventilators that reduce workload and improve outcomes.
Companies with advanced software can capture this opportunity. Closed-loop systems automatically adjust oxygen and pressure based on real-time patient data, and automated weaning helps patients come off ventilators sooner. Integration with hospital records and monitoring systems reduces charting errors and saves nurse time. AI tools can predict when patients are ready to breathe on their own, shortening ICU stays. Staff shortages in intensive care units make automation valuable. Premium ventilators carry higher prices and service contracts. Software upgrades sold after purchase add revenue. Remote fleet management lets hospitals track ventilator use, maintenance, and alarms across many units, improving efficiency.
Segment Analysis
- By Product: Critical Care Leads While Transport and Portable Grows Fastest
Critical Care held 52.0% share in 2026. Critical care ventilators are used in intensive care units and offer advanced modes for adults, children, and complex patients. They are the most expensive and feature-rich devices on the market. Drägerwerk, Hamilton Medical, Getinge, Medtronic, and GE HealthCare lead this segment.
Transport and Portable is the fastest-growing product, expanding at a 6.0% CAGR through 2033. Portable ventilators are used in ambulances, helicopters, emergency rooms, and patient transfers, and some are used at home. Battery life, durability, and light weight are key features. Neonatal ventilators serve newborn intensive care units with very gentle breathing support. Military and disaster response agencies also buy rugged portable ventilators. For the market, portable growth widens use outside the ICU.
- By Ventilation Mode: Invasive Leads While Non-Invasive Grows Fastest
Invasive held 63.0% share in 2026. Invasive ventilation delivers air through a breathing tube in the windpipe and is used for the sickest patients, including those in surgery and severe respiratory failure. Critical care units rely on invasive ventilation, and anesthesia machines in operating rooms also provide invasive support during surgery. Lung-protective modes reduce injury from long-term ventilation.
Non-Invasive is the fastest-growing mode, expanding at a 5.8% CAGR through 2033. Non-invasive ventilation uses masks or high-flow nasal systems to support breathing without a tube, reducing infection risk and sedation needs. It is widely used for COPD flare-ups, heart failure, and at home. Fisher & Paykel Healthcare and ResMed are leaders. For the market, non-invasive growth supports home and ward use.
- By End Use: Hospitals Lead While Home Healthcare Grows Fastest
Hospitals held 74.0% share in 2026. Hospitals use ventilators in intensive care units, operating rooms, emergency departments, step-down wards, and neonatal units. They buy nearly all critical care and transport models, usually through tenders with long service contracts. Teaching hospitals often adopt the newest features first.
Home Healthcare is the fastest-growing end use, expanding at a 6.6% CAGR through 2033. Patients with chronic conditions increasingly use ventilators at home rather than in hospitals, supported by remote monitoring and home care nurses. Long-term care facilities and rehabilitation centers are other users. Home care companies rent ventilators and provide respiratory therapists who visit patients. For the market, home care growth adds recurring revenue.
Geography Analysis
- Which Region Is Leading the Mechanical Ventilators Market?
North America is leading the mechanical ventilators market with a 37.0% share in 2026. The United States has a large number of intensive care beds, high spending on critical care, and strong use of home ventilation. Medtronic, GE HealthCare, ResMed, ZOLL Medical, and React Health are major players in the region. The Strategic National Stockpile holds reserve ventilators. Canada and Mexico add demand. Home ventilation is widely covered by Medicare and private insurers for qualifying patients. Key barriers include oversupply after the pandemic and recalls. One change shaping the region is replacement with smart ventilators.
- Europe Builds the Mechanical Ventilators Market Through Engineering Leadership
Europe is a major mechanical ventilators market. Germany hosts Drägerwerk, Switzerland hosts Hamilton Medical, and Sweden hosts Getinge. France, the United Kingdom, Italy, and Spain have large hospital systems with aging patients and high rates of chronic lung disease. The new EU Medical Device Regulation has raised testing and documentation requirements for all ventilator makers. National health systems in Germany and France fund home ventilation for many patients with chronic disease. Hospitals are replacing older units with models that offer automated modes. Key barriers include budget pressure in public health systems. One opportunity is home ventilation.
- Which Region Is Growing Fastest in the Mechanical Ventilators Market?
Asia Pacific is growing fastest in the mechanical ventilators market at a 6.3% CAGR through 2033. China is expanding intensive care capacity and has strong local makers such as Mindray, and India is building new hospitals and critical care units. Japan has an aging population and Nihon Kohden. Indonesia and Vietnam are adding ICU beds. Australia and New Zealand host Fisher & Paykel Healthcare. Government health insurance programs in India and China are expanding access to hospital care, increasing ventilator use. Key barriers include price competition and limited trained staff. One change shaping the region is ICU expansion.
- Latin America Grows the Mechanical Ventilators Market Through Hospital Investment
Latin America is a growing mechanical ventilators market. Brazil and Mexico have large public and private hospital systems and are replacing older equipment, and Argentina, Chile, and Colombia are expanding intensive care in major cities. Many ventilators bought during the pandemic now need servicing, upgrades, or replacement. Private hospital groups in Brazil and Mexico invest in premium models, while public hospitals often buy through government tenders that favor low prices. Peru, Ecuador, and Uruguay are adding ICU beds and training critical care staff. Key barriers include limited budgets and currency swings. One opportunity is ICU upgrades.
- Middle East & Africa Expands the Mechanical Ventilators Market Through Critical Care Investment
Middle East & Africa is an emerging mechanical ventilators market. Saudi Arabia and the United Arab Emirates are building new hospitals with modern intensive care units and neonatal units. South Africa, Egypt, and Nigeria have limited ICU capacity, especially in public hospitals. Hospitals in Qatar, Kuwait, and Oman have well-equipped intensive care units and modern neonatal care. International aid programs have supplied ventilators, oxygen plants, and training to hospitals in Kenya, Ethiopia, and other countries. Key barriers include limited funding and few trained staff. One opportunity is equipping new hospitals and neonatal units.
Competitive Landscape
The mechanical ventilators market is moderately concentrated. Drägerwerk, Hamilton Medical, Getinge, Medtronic, GE HealthCare, and Koninklijke Philips lead in critical care, while ResMed, Fisher & Paykel Healthcare, Breas Medical, and React Health are strong in home and non-invasive ventilation. Mindray and Nihon Kohden are major Asian suppliers, and ZOLL Medical focuses on transport ventilators.
Companies compete mainly on reliability, safety, ease of use, advanced modes, software, battery life, service networks, and price. Hospitals strongly value long-term service and training, which favors established brands with local support teams. Asian makers such as Mindray compete strongly on price, especially in emerging markets. Software features such as automated weaning and closed-loop oxygen control set premium products apart in large hospitals. Quality problems and recalls in recent years have shifted some market share among leading brands, giving firms with strong safety records an advantage.
Strategic moves show how competition is changing in this market. In September 2025, Hamilton Medical premiered a reinvented HAMILTON-C6 at the ESICM Congress. In April 2026, Philips issued a recall notice for Trilogy Evo ventilators with a software fix. In May 2026, React Health issued a Class I recall of VOCSN ventilators. These moves show competition shaped by innovation, safety, quality control, and trust.
Three themes shape vendor strategy. First, companies are adding automation and closed-loop control. Second, they are strengthening quality systems after recalls. Third, they are growing home ventilation with remote monitoring.
Recent Industry Developments
- May 2026: React Health issued a Class I recall of VOCSN ventilators over a manufacturing configuration error that could cause oxygen leaks – highlights safety demands in home ventilation.
- April 2026: Philips issued a recall notice for Trilogy Evo ventilators, with a software update as the remedy – shows ongoing quality pressure on ventilator makers.
- September 2025: Hamilton Medical premiered a reinvented HAMILTON-C6 ventilator with a large detachable touchscreen for adult, pediatric, and neonatal patients – advances smart critical care ventilation.
Companies Covered in the Report
- Drägerwerk
- Hamilton Medical
- Getinge
- Medtronic
- ResMed
- Koninklijke Philips
- GE HealthCare
- Fisher & Paykel Healthcare
- Mindray
- Nihon Kohden
- ZOLL Medical
- React Health
Mechanical Ventilators Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 4.80 Billion |
| Market Size 2033 | US$ 6.58 Billion |
| CAGR 2026–2033 | 4.6% |
| Absolute Dollar Opportunity | US$ 1.78 Billion |
| Largest Market | North America |
| Fastest-Growing Market | Asia Pacific |
| Market Concentration | Moderate |
| Major Players | Drägerwerk, Hamilton Medical, Getinge, Medtronic, ResMed |
Mechanical Ventilators Market Segmentation
Product
- Critical Care
- Neonatal
- Transport and Portable
- Others
Ventilation Mode
- Invasive
- Non-Invasive
End Use
- Hospitals
- Home Healthcare
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Mechanical Ventilators Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Chronic Respiratory Disease Is Driving the Mechanical Ventilators Market
- Intensive Care Expansion Is Expanding the Mechanical Ventilators Market
- Restraints
- Post-Pandemic Oversupply Slows the Mechanical Ventilators Market
- Recalls and Regulation Restrict the Mechanical Ventilators Market
- Market Opportunities
- Home Ventilation Opens a Chronic Care Revenue Pool
- Smart and Automated Ventilation Creates a Premium Revenue Pool
- Drivers
- Global Mechanical Ventilators Market Outlook, 2020-2033
- Global Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- Global Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- Global Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- Global Mechanical Ventilators Market Outlook, by Region, Value (US$ Billion), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- North America Mechanical Ventilators Market Outlook, 2020-2033
- North America Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- North America Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- North America Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- North America Mechanical Ventilators Market Outlook, by Country, Value (US$ Billion), 2020-2033
- United States Mechanical Ventilators Market Outlook, by Product, 2020-2033
- United States Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- United States Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Canada Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Canada Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Canada Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- North America Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Europe Mechanical Ventilators Market Outlook, 2020-2033
- Europe Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- Europe Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- Europe Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- Europe Mechanical Ventilators Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Germany Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Germany Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Germany Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Switzerland Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Switzerland Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Switzerland Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Sweden Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Sweden Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Sweden Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- France Mechanical Ventilators Market Outlook, by Product, 2020-2033
- France Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- France Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- United Kingdom Mechanical Ventilators Market Outlook, by Product, 2020-2033
- United Kingdom Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- United Kingdom Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Italy Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Italy Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Italy Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Spain Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Spain Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Spain Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Europe Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Asia Pacific Mechanical Ventilators Market Outlook, 2020-2033
- Asia Pacific Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- Asia Pacific Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- Asia Pacific Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- Asia Pacific Mechanical Ventilators Market Outlook, by Country, Value (US$ Billion), 2020-2033
- China Mechanical Ventilators Market Outlook, by Product, 2020-2033
- China Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- China Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- India Mechanical Ventilators Market Outlook, by Product, 2020-2033
- India Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- India Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Japan Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Japan Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Japan Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Indonesia Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Indonesia Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Indonesia Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Vietnam Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Vietnam Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Vietnam Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Australia Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Australia Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Australia Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- New Zealand Mechanical Ventilators Market Outlook, by Product, 2020-2033
- New Zealand Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- New Zealand Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Asia Pacific Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Latin America Mechanical Ventilators Market Outlook, 2020-2033
- Latin America Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- Latin America Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- Latin America Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- Latin America Mechanical Ventilators Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Brazil Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Brazil Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Brazil Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Mexico Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Argentina Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Argentina Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Argentina Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Chile Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Chile Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Chile Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Colombia Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Colombia Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Colombia Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Peru Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Peru Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Peru Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Ecuador Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Ecuador Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Ecuador Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Uruguay Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Uruguay Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Uruguay Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Latin America Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Middle East & Africa Mechanical Ventilators Market Outlook, 2020-2033
- Middle East & Africa Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Critical Care
- Neonatal
- Transport and Portable
- Others
- Middle East & Africa Mechanical Ventilators Market Outlook, by Ventilation Mode, Value (US$ Billion), 2020-2033
- Invasive
- Non-Invasive
- Middle East & Africa Mechanical Ventilators Market Outlook, by End Use, Value (US$ Billion), 2020-2033
- Hospitals
- Home Healthcare
- Others
- Middle East & Africa Mechanical Ventilators Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Saudi Arabia Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Saudi Arabia Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Saudi Arabia Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- United Arab Emirates Mechanical Ventilators Market Outlook, by Product, 2020-2033
- United Arab Emirates Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- United Arab Emirates Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- South Africa Mechanical Ventilators Market Outlook, by Product, 2020-2033
- South Africa Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- South Africa Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Egypt Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Egypt Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Egypt Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Nigeria Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Nigeria Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Nigeria Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Qatar Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Qatar Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Qatar Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Kuwait Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Kuwait Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Kuwait Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Oman Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Oman Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Oman Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Kenya Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Kenya Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Kenya Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Ethiopia Mechanical Ventilators Market Outlook, by Product, 2020-2033
- Ethiopia Mechanical Ventilators Market Outlook, by Ventilation Mode, 2020-2033
- Ethiopia Mechanical Ventilators Market Outlook, by End Use, 2020-2033
- Middle East & Africa Mechanical Ventilators Market Outlook, by Product, Value (US$ Billion), 2020-2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Drägerwerk
- Hamilton Medical
- Getinge
- Medtronic
- ResMed
- Koninklijke Philips
- GE HealthCare
- Fisher & Paykel Healthcare
- Mindray
- Nihon Kohden
- ZOLL Medical
- React Health
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product
- Critical Care
- Neonatal
- Transport and Portable
- Others
Ventilation Mode
- Invasive
- Non-Invasive
End Use
- Hospitals
- Home Healthcare
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The mechanical ventilators market is valued at US$ 4.80 billion in 2026, led by critical care ventilators and North America.
The market is projected to reach US$ 6.58 billion by 2033, growing at a 4.6% CAGR and adding US$ 1.78 billion.
Home healthcare is growing fastest at a 6.6% CAGR through 2033, driven by chronic respiratory disease and neuromuscular conditions.
Asia Pacific is growing fastest at a 6.3% CAGR through 2033, driven by intensive care expansion in China, India, and Indonesia.
North America holds the largest share at 37.0% in 2026, supported by large ICU capacity and strong home ventilation use.
Related Reports
Drugs of Abuse Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global drugs of abuse testing market is valued at US$6.80 billion in 2026, reaching US$14.60 billion by 2033, growing at an 11.5% CAGR
Brain Health Devices Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global brain health devices market is valued at US$8.60 billion in 2026, reaching US$13.10 billion by 2033, growing at a 6.2% CAGR
Biohazard Bags Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global biohazard bags market is valued at US$380.4 million in 2026, reaching US$660.4 million by 2033, growing at an 8.2% CAGR
Biohacking Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global biohacking market is valued at US$27.50 billion in 2026, reaching US$84.53 billion by 2033, growing at a 17.4% CAGR
Antimicrobial Susceptibility Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global antimicrobial susceptibility testing market is valued at US$6.60 billion in 2026, reaching US$10.46 billion by 2033, growing at a 6.8% CAGR
3D Bioprinting Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The 3D bioprinting market is projected to grow from US$3.20 Bn in 2026 to US$8.50 Bn by 2033, at a CAGR of 15.0% during 2026–2033.