


Protective Fabrics Market
Protective Fabrics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Protective Fabrics Market Size and Trend Analysis
What Is the Growth Outlook for Protective Fabrics?
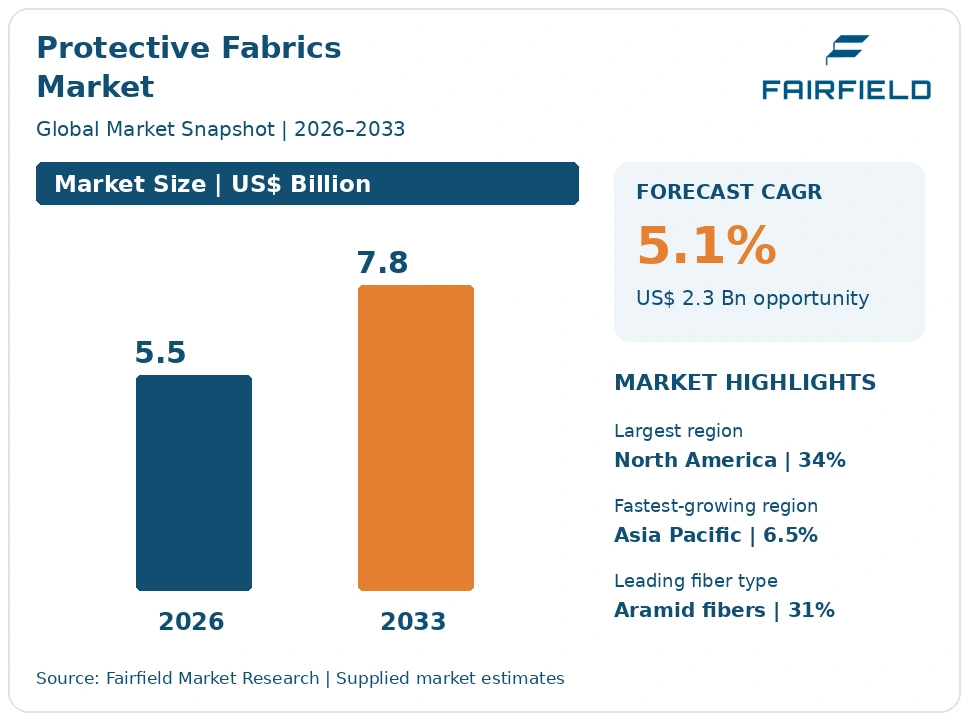
The global protective fabrics market size is expected to be valued at US$ 5.5 billion in 2026 and projected to reach US$ 7.8 billion by 2033, growing at a CAGR of 5.1% between 2026 and 2033.
The market grew at a historical CAGR of close to 4.6% between 2020 and 2025, lifted first by medical and barrier fabric demand and then by industrial restocking. Three factors support the forecast. Electrification of grids, data centres and vehicle fleets is widening the population of workers exposed to arc flash. Fibre makers have brought lighter ballistic and cut-resistant constructions to market, raising value per square metre. Enforcement of certified personal protective equipment is tightening in industrialising economies. Volumes track industrial employment, so growth stays in mid single digits, while mix moves steadily toward inherently flame-resistant and multi-hazard fabrics that carry higher prices than treated cotton.
Key Report Takeaways
- By Fiber Type: Aramid fibers held 31% share in 2026, while ultra-high-molecular-weight polyethylene is projected to expand at a 7.3% CAGR through 2033, driven by lighter soft armour panels and cut-resistant glove yarns.
- By Protection Type: Fire and heat protective clothing held 33% share in 2026, while electrical arc flash and high-visibility workwear is projected to expand at a 7.1% CAGR through 2033, as grid and renewable work expands the exposed workforce.
- By End Use Industry: Fire services and defence held 29% share in 2026, while utilities and electrical work is projected to expand at a 7.4% CAGR through 2033, reflecting mandatory arc rating programmes for line and substation crews.
- By Fabric Construction: Woven fabrics held 58% share in 2026, while coated and laminated composites are projected to expand at a 6.8% CAGR through 2033, because barrier and breathability requirements increasingly demand a membrane layer.
- By Geography: North America held 34% share in 2026, while Asia Pacific is projected to expand at a 6.5% CAGR through 2033, supported by enforcement of certified workwear in heavy industry.
Global Protective Fabrics Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the forecast growth in technical protective textiles.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Certification-led procurement written against named test standards | High | North America, Europe | Long term (≥4 years) |
| Electrification of grids, transport and industry widening arc flash exposure | High | North America, Europe, Asia Pacific | Medium term (2–4 years) |
Test Standards Act as the Product Specification in Protective Fabric Tenders
Purchasing in protective textiles is written against named standards, which makes certification the single strongest demand driver. A fabric that cannot certify cannot be sold at any price, so every revision of a standard forces re-testing, re-qualification and, often, replacement of inventory in the field. That converts safety regulation into a predictable, recurring order stream rather than a one-off compliance cost.
The mechanism runs through conformity assessment. Under the Personal Protective Equipment Regulation, Regulation (EU) 2016/425, garments protecting against heat, flame, chemicals and electrical risk fall into category III and need notified body involvement plus ongoing production control. Tenders then cite EN ISO 11612 for heat and flame, EN ISO 11611 for welding, EN 1149 for electrostatic properties and EN 388 with ISO 13997 for cut resistance. In the United States, NFPA 2112 performs the same role for industrial flame-resistant garments.
Electrification Expands the Workforce That Needs Arc-Rated Fabric
Electrification is adding workers to the arc flash population faster than any other force in industrial safety. Grid reinforcement, substation upgrades, battery plants, data centre power rooms and high-voltage vehicle service all create live-work exposure in places that previously had none. Each of those workers needs daily wear rated for incident energy, which is a repeat-purchase fabric category rather than an occasional issue.
The causal chain is specific. NFPA 70E requires employers to assess incident energy and issue clothing with a matching arc rating, and IEC 61482 provides the test methods used internationally. Higher fault levels on reinforced networks push required arc ratings upward, which means heavier or more sophisticated fabric constructions. Utilities also move crews from task-based protection to arc-rated daily wear, multiplying the garment count per worker and the square metres of fabric consumed each year.
Restraints Impact Analysis
Two constraints hold certified protective textile demand below its theoretical potential.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Price gap between high-performance fibres and treated cotton in open tenders | High | Asia Pacific, Latin America, Middle East & Africa | Short term (≤2 years) |
| Heat stress and comfort penalty causing non-compliance by wearers | Medium | Global | Medium term (2–4 years) |
Fibre Cost Keeps Treated Cotton in Place on Price-Driven Tenders
The cost gap between high-performance fibres and flame-resistant treated cotton keeps a large part of the addressable market on the cheapest compliant option. Para-aramid, polybenzimidazole and ultra-high-molecular-weight polyethylene can cost many times more per kilogram than chemically treated cotton, and a purchasing officer scored on unit price will specify the minimum that passes the test.
The cost sources are structural rather than cyclical. Para-aramid production needs polymerisation in aggressive solvents, solvent recovery and solution spinning, all capital-intensive and energy-hungry. Polybenzimidazole volumes are tiny, so fixed costs spread thinly. Treated cotton, by contrast, uses commodity yarn and a finishing chemistry applied on existing textile lines. Buyers who replace garments annually find the lower first cost difficult to argue against, even when inherently flame-resistant fabric survives more laundering cycles and lasts longer.
Comfort and Heat Stress Limit Real-World Use of Protective Clothing
Protective fabric that workers find unbearable gets removed, unzipped or layered incorrectly, which caps effective demand for the heaviest constructions. Heat strain is a genuine safety hazard in hot climates and in multi-layer ensembles, and site supervisors know that an uncomfortable garment produces non-compliance. Buyers respond by specifying lighter fabrics, which lowers the grams per square metre and with it the revenue per garment.
The underlying cause is a physics conflict. Thermal and barrier protection relies on insulation and on closing the fabric structure, while comfort relies on moisture vapour transfer and air permeability. Membranes that block chemicals and liquids also impede evaporative cooling. Multi-layer structural firefighting ensembles built to NFPA 1971 requirements illustrate the trade-off, since the thermal barrier that protects against flashover also traps metabolic heat during long incidents.
Market Opportunities
Multi-Hazard Fabrics That Certify Against Several Standards Open a Premium Pool
Fabrics that carry several certifications at once open a revenue pool that single-hazard materials cannot reach. A worker in a refinery may face flash fire, arc flash, static discharge and molten splash in one shift, and buying four garments is costly and unworkable. A single construction certified to heat and flame, arc thermal, electrostatic and chemical splash requirements commands a clear price premium and reduces the customer’s inventory.
Mills with in-house finishing and test capability are best placed to capture it, because multi-certification requires controlled blends and repeatable production rather than a new fibre. Oil and gas, petrochemical and utility operators create the demand, since their hazard assessments already list several risks per role. The combination of EN ISO 11612, IEC 61482 and EN 1149 in one specification is becoming the normal starting point for refinery workwear tenders.
PFAS Restriction Creates a Replacement Market for Repellent and Membrane Layers
Restrictions on per- and polyfluoroalkyl substances open a replacement opportunity across every protective fabric that relies on a durable water repellent finish or a fluoropolymer membrane. Liquid repellency is a certification requirement in chemical, firefighting and medical protection, so the layer cannot simply be deleted. Whoever qualifies a compliant alternative first captures re-specification across entire garment ranges.
Fibre producers, finishing chemical suppliers and laminators share this pool. Fire services, healthcare systems and chemical processors generate the demand because their purchasing is already screening for restricted substances, and several public buyers have set internal deadlines ahead of any legal one. The universal restriction proposal under review in the European Union makes the direction clear, and silicone, polyurethane and non-fluorinated polymer chemistries are being tested against EN ISO 11612 and penetration requirements.
Segment Analysis
By Fiber Type: Aramid Holds the Largest Share While UHMWPE Expands Quickest
Aramid fibers led with 31% share in 2026, because para-aramid and meta-aramid cover the two largest certified uses, ballistic protection and thermal protective clothing, and have decades of accepted test data behind them. Flame-resistant treated cotton and blends held 22%, modacrylic and inherently flame-resistant blends 14%, PTFE and polyurethane membranes and coated fabrics 12%, glass, basalt and ceramic fibre fabrics 9%, ultra-high-molecular-weight polyethylene 8% and polybenzimidazole and other high-performance fibres 4%. Ultra-high-molecular-weight polyethylene is the fastest-growing fibre at a 7.3% CAGR, because its strength-to-weight ratio allows lighter soft armour panels and because gel-spun yarns now dominate high-level cut protection. Fibre choice decides both certification and comfort, so it sets the ceiling on what a converter can sell and on the price a mill can defend in a tender.
By Protection Type: Fire and Heat Clothing Leads as Arc Flash Workwear Accelerates
Fire and heat protective clothing accounted for 33% of demand in 2026, the largest single pool, because firefighting, foundry, welding and refinery work all require thermal protection and because those garments are replaced on fixed cycles. Ballistic and stab-resistant armour fabrics held 21%, cut-resistant fabrics and glove textiles 19% and chemical and biological protective suits 13%. Electrical arc flash and high-visibility workwear is the fastest-growing protection type at a 7.1% CAGR from a 14% share. Grid investment, renewable connection work and battery manufacturing have widened the number of roles requiring an arc rating, and employers are shifting from task-specific gear to arc-rated daily wear. That change raises garment counts per worker, favours lighter inherently flame-resistant blends, and pulls spending toward fabrics that certify for thermal and electrical risk together.
By End Use Industry: Fire Services and Defence Lead While Utilities Grow Fastest
Fire services and defence together held 29% share in 2026, the result of large organised fleets, mandatory ensemble standards and scheduled replacement budgets that do not depend on industrial cycles. Oil and gas and petrochemicals took 19%, manufacturing 16%, construction 13%, healthcare 8% and law enforcement 5%. Utilities and electrical work is the fastest-growing end use at a 7.4% CAGR from a 10% base. Network operators are expanding line crews, substation teams and contractor pools to deliver grid reinforcement, and each new worker enters a mandatory arc-rated clothing programme. Utility procurement is also unusually standards-literate, which favours certified mills over commodity suppliers and supports stable pricing across multi-year framework agreements. For fabric producers, utility programmes are the most reliable repeat volume in the market, because clothing is issued, laundered, inspected and replaced on a managed cycle rather than bought project by project.
By Fabric Construction: Woven Structures Dominate While Coated Composites Advance Fastest
Woven fabrics held 58% share in 2026, because woven constructions deliver the tensile strength, abrasion resistance and dimensional stability that garment standards assume, and because most certified thermal and arc fabrics are woven. Knitted fabrics accounted for 18%, used mainly in cut-resistant gloves and comfort layers, and nonwovens 9%, concentrated in limited-life chemical and medical protection. Coated and laminated composites are the fastest-growing construction at a 6.8% CAGR from a 15% share. These are counted here as fabric because the coating or membrane is applied at the textile stage and sold by the metre. Barrier requirements for chemical splash, liquid penetration and firefighting moisture control increasingly demand a membrane, which raises value per metre well above greige woven cloth.
Geography Analysis
Which Region Is Leading the Protective Fabrics Market?
North America leads the protective fabrics market with 34% share in 2026, driven by the strictest enforcement of garment standards and the highest spend per worker anywhere. The National Fire Protection Association framework, including NFPA 2112 for industrial flame-resistant clothing, NFPA 1971 for structural firefighting ensembles and NFPA 70E for electrical safety, gives buyers an unambiguous specification and gives mills a defensible position. The United States accounts for most regional demand through fire services, defence procurement, oil and gas, and a large utility sector now expanding line crews. Canada mirrors those requirements in provincial occupational safety rules. Domestic fibre and fabric manufacturing is substantial, and defence purchasing rules favour local supply chains. The main change ahead is the search for replacements for fluorinated repellent finishes.
Europe Converts Regulation Into a High-Value Certified Fabric Mix
Europe held 27% of the market in 2026 and has the most structured conformity regime, which lifts average selling prices above volume-led regions. The Personal Protective Equipment Regulation, Regulation (EU) 2016/425, places heat, flame, chemical and electrical protection in category III, requiring notified body examination and continuing production surveillance. Germany, France, Italy and the Nordic countries supply most demand through chemicals, metals, utilities and emergency services. Harmonised standards such as EN ISO 11612, EN ISO 11611, EN 1149 and EN 388 are written into tenders by reference, so mills invest heavily in test capability. The region also hosts major aramid and membrane production. Restriction of per- and polyfluoroalkyl substances is the live issue, forcing reformulation of repellent finishes and membranes across certified ranges.
Which Region Is Growing Fastest in the Protective Fabrics Market?
Asia Pacific is the fastest-growing region in the protective fabrics market at a 6.5% CAGR through 2033, from a 26% share in 2026. Growth comes from enforcement rather than from new hazards: factory inspection regimes in China, India, Vietnam and Indonesia increasingly require certified protective clothing in metals, chemicals, shipbuilding and construction, replacing uncertified workwear. Japan and South Korea behave as mature, high-specification buyers with their own fibre producers. Regional fibre capacity for aramid and gel-spun polyethylene has expanded, lowering delivered cost and shortening qualification time for local mills. Defence modernisation adds ballistic fabric demand. The constraint is price sensitivity in open tenders, which keeps treated cotton dominant in general industry even as certified inherently flame-resistant fabric gains share in regulated sites.
Latin America Builds Demand Around Mining, Oil and Utility Safety Rules
Latin America accounted for 7% of the market in 2026, with Brazil and Mexico the main buyers and Chile, Peru and Colombia significant through mining. Brazilian occupational safety regulation for electrical work has created one of the region’s most consistent arc-rated clothing programmes, and national oil and mining operators apply international specifications across their contractor base. Mexican demand is supported by industrial investment and by automotive and appliance manufacturing. Barriers are familiar: imported high-performance fibre is priced in dollars, currency swings move garment budgets sharply, and enforcement outside large operators and formal employment is uneven. Local weaving and garment conversion are growing, which shortens lead times. The opportunity lies in contractor-level enforcement, where compliance still lags that of asset owners.
Middle East & Africa Demand Concentrates in Hydrocarbon and Utility Operations
Middle East & Africa held 6% of the market in 2026, with demand concentrated in oil, gas and petrochemical operations in Saudi Arabia, the United Arab Emirates, Qatar and Kuwait, and in mining across South Africa. National energy operators specify international standards for their own staff and contractors, which keeps the certified segment strong despite a small industrial base. Extreme ambient heat makes the comfort and heat-stress trade-off the central purchasing question, pushing buyers toward lighter inherently flame-resistant fabrics and ventilated constructions. Barriers include dependence on imported fibre and fabric, limited local testing infrastructure, and patchy enforcement outside major operators. New refining, petrochemical and grid capacity in the Gulf is the clearest growth opportunity, since each project adds a contractor workforce under the owner’s safety rules.
Competitive Landscape
The protective fabrics market is highly concentrated at the fibre layer and more fragmented at the weaving and finishing layer. A small number of producers control para-aramid, meta-aramid, gel-spun polyethylene, polybenzimidazole and fluoropolymer membrane supply, and their qualification data underpins most certified fabrics. Below them sit specialist mills that weave, dye, finish and certify, and below those are garment makers. Barriers to entry are unusually high because a new fabric must complete certification testing, satisfy notified body or accredited laboratory review, and then survive field trials before a buyer will switch. Qualification cycles of two to four years are normal, which protects incumbents and makes the market slow-moving.
Vendors compete on certification breadth, consistency of certified lots, weight at a given protection level, comfort and colour fastness, and on technical service to garment makers and end users. Price matters mainly within a certified class, not across classes. Branded fibre and fabric names carry real pull-through because safety managers specify them by name. New approaches are arriving from blend engineering rather than from new polymers: mills are combining modacrylic, aramid, lyocell and antistatic filaments to reach multiple certifications at lower weight, and non-fluorinated finish suppliers are pushing into repellency.
Strategic direction is consistent across the supplier base. Firms are building multi-hazard portfolios that certify against several standards at once, lightening ballistic and arc-rated constructions, qualifying replacements for fluorinated chemistry, and localising fabric supply near defence and utility customers that prefer domestic sourcing. Several are investing in their own accredited testing to shorten qualification. Recycled and traceable fibre content is appearing in tenders, though certification always takes precedence over sustainability claims.
Protective Fabrics Industry Leaders
- DuPont de Nemours, Inc.
- Teijin Limited
- Honeywell International Inc.
- Milliken & Company
- W. L. Gore & Associates, Inc.
Recent Industry Developments
April 2018: The Personal Protective Equipment Regulation, Regulation (EU) 2016/425, became applicable across the European Union, replacing the earlier directive – it moved most protective clothing into category III with notified body conformity assessment and continuing production control.
February 2023: Authorities from five European countries submitted a universal restriction proposal on per- and polyfluoroalkyl substances, published by the European Chemicals Agency – it put durable water repellent finishes and fluoropolymer membranes used in protective clothing on notice.
2023: The National Institute of Justice published Standard 0101.07 for ballistic resistance of body armor, replacing the long-standing earlier revision – it changed test and conditioning requirements that ballistic fabric suppliers must design against.
2025: The National Fire Protection Association consolidated structural firefighting ensemble requirements previously held in NFPA 1971 into a combined emergency responder protective equipment standard – it aligns ensemble, station wear and respiratory requirements in one document for fabric qualification.
Protective Fabrics Market Report Scope
| Metric | Value |
| Study Period (2020–2033) | 14 years of historical and forecast coverage |
| Market Size 2026 | US$ 5.5 Billion |
| Market Size 2033 | US$ 7.8 Billion |
| CAGR 2026–2033 | 5.1% |
| Absolute Dollar Opportunity | US$ 2.3 Billion |
| Largest Market (region) | North America, 34% share in 2026 |
| Fastest-Growing Market (region) | Asia Pacific, 6.5% CAGR |
| Market Concentration | High |
| Major Players | DuPont de Nemours, Inc., Teijin Limited, Honeywell International Inc., Milliken & Company, W. L. Gore & Associates, Inc. |
This report covers engineered textiles for personal protection: aramid, ultra-high-molecular-weight polyethylene, flame-resistant treated cotton, modacrylic blends, polybenzimidazole, membranes, coated fabrics and inorganic fibre cloth. It counts the fabric and textile layer, with coated and laminated composites included at the fabric stage. Finished garments, complete armour systems, hard plates and helmets are excluded. The base year is 2025, the forecast runs 2026 to 2033, in US$ Billion.
Protective Fabrics Market Segmentation
Fiber Type
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
Protection Type
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
End Use Industry
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
Fabric Construction
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Protective Fabrics Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Test Standards Act as the Product Specification in Protective Fabric Tenders
- Electrification Expands the Workforce That Needs Arc-Rated Fabric
- Restraints
- Fibre Cost Keeps Treated Cotton in Place on Price-Driven Tenders
- Comfort and Heat Stress Limit Real-World Use of Protective Clothing
- Market Opportunities
- Multi-Hazard Fabrics That Certify Against Several Standards Open a Premium Pool
- PFAS Restriction Creates a Replacement Market for Repellent and Membrane Layers
- Drivers
- Global Protective Fabrics Market Outlook, 2020–2033
- Global Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- Global Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- Global Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- Global Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- Global Protective Fabrics Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- North America Protective Fabrics Market Outlook, 2020–2033
- North America Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- North America Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- North America Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- North America Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- North America Protective Fabrics Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- United States Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- United States Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- United States Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Canada Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Canada Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Canada Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Canada Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- North America Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Europe Protective Fabrics Market Outlook, 2020–2033
- Europe Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- Europe Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- Europe Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- Europe Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- Europe Protective Fabrics Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Germany Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Germany Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Germany Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- France Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- France Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- France Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- France Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Italy Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Italy Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Italy Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Italy Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Nordic countries Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Nordic countries Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Nordic countries Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Nordic countries Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Europe Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Asia Pacific Protective Fabrics Market Outlook, 2020–2033
- Asia Pacific Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- Asia Pacific Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- Asia Pacific Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- Asia Pacific Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- Asia Pacific Protective Fabrics Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- China Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- China Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- China Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- India Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- India Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- India Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- India Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Vietnam Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Vietnam Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Vietnam Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Vietnam Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Indonesia Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Indonesia Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Indonesia Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Indonesia Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Japan Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Japan Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Japan Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Japan Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- South Korea Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- South Korea Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- South Korea Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- South Korea Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Asia Pacific Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Latin America Protective Fabrics Market Outlook, 2020–2033
- Latin America Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- Latin America Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- Latin America Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- Latin America Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- Latin America Protective Fabrics Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Brazil Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Brazil Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Brazil Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Mexico Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Mexico Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Mexico Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Mexico Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Chile Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Chile Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Chile Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Chile Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Peru Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Peru Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Peru Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Peru Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Colombia Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Colombia Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Colombia Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Colombia Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Latin America Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Protective Fabrics Market Outlook, 2020–2033
- Middle East & Africa Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
- Middle East & Africa Protective Fabrics Market Outlook, by Protection Type, Value (US$ Billion), 2020–2033
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
- Middle East & Africa Protective Fabrics Market Outlook, by End Use Industry, Value (US$ Billion), 2020–2033
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
- Middle East & Africa Protective Fabrics Market Outlook, by Fabric Construction, Value (US$ Billion), 2020–2033
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
- Middle East & Africa Protective Fabrics Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Saudi Arabia Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Saudi Arabia Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Saudi Arabia Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- United Arab Emirates Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- United Arab Emirates Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- United Arab Emirates Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- United Arab Emirates Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Qatar Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Qatar Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Qatar Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Qatar Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Kuwait Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- Kuwait Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- Kuwait Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- Kuwait Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- South Africa Protective Fabrics Market Outlook, by Fiber Type, 2020–2033
- South Africa Protective Fabrics Market Outlook, by Protection Type, 2020–2033
- South Africa Protective Fabrics Market Outlook, by End Use Industry, 2020–2033
- South Africa Protective Fabrics Market Outlook, by Fabric Construction, 2020–2033
- Middle East & Africa Protective Fabrics Market Outlook, by Fiber Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- DuPont de Nemours, Inc.
- Teijin Limited
- Toyobo Co., Ltd.
- Honeywell International Inc.
- Avient Corporation
- Milliken & Company
- TenCate Protective Fabrics
- W. L. Gore & Associates, Inc.
- Lenzing AG
- Kaneka Corporation
- PBI Performance Products, Inc.
- Glen Raven, Inc.
- Klopman International
- Hyosung Advanced Materials
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Fiber Type
- Aramid fibers
- Ultra-high-molecular-weight polyethylene
- Flame-resistant treated cotton and blends
- Modacrylic and inherently flame-resistant blends
- Polybenzimidazole and other high-performance fibres
- PTFE and polyurethane membranes and coated fabrics
- Glass, basalt and ceramic fibre fabrics
Protection Type
- Fire and heat protective clothing
- Ballistic and stab-resistant armour fabrics
- Chemical and biological protective suits
- Electrical arc flash and high-visibility workwear
- Cut-resistant fabrics and glove textiles
End Use Industry
- Fire services and defence
- Oil and gas and petrochemicals
- Utilities and electrical work
- Construction
- Manufacturing
- Healthcare
- Law enforcement
Fabric Construction
- Woven fabrics
- Knitted fabrics
- Nonwovens
- Coated and laminated composites
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The global protective fabrics market is valued at US$ 5.5 billion in 2026, counting the fabric and textile layer rather than finished garments or complete armour systems.
Protective textiles are projected to reach US$ 7.8 billion by 2033, a 5.1% CAGR and an absolute dollar opportunity of US$ 2.3 billion across the forecast period.
Aramid fibers lead with 31% share in 2026, because para-aramid and meta-aramid cover both ballistic protection and thermal protective clothing with accepted certification data.
Electrical arc flash and high-visibility workwear grows fastest at a 7.1% CAGR, as electrification widens the number of roles needing arc-rated daily wear.
North America holds 34% share in 2026, reflecting strict enforcement of garment standards, high spend per worker and large fire service and utility programmes.
Related Reports
Isopropyl Alcohol Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global isopropyl alcohol market is valued at US$5.2 billion in 2026, reaching US$6.6 billion by 2033, growing at a 3.5% CAGR
Organic Peroxide Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The organic peroxide market is projected to reach US$2.76 billion by 2033. Explore demand across polymers, rubber, coatings, adhesives, and key regions.
Nitrile Butadiene Rubber (NBR) Latex Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The NBR latex market is projected to reach US$6.09 billion by 2033. Explore demand for nitrile gloves, carboxylated latex, and growth in Asia Pacific.
Nanopesticides Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The nanopesticides market is projected to reach US$2.35 billion by 2033. Explore nanoinsecticides, nanoherbicides, and regional demand for crop protection.
Mono-Ethanolamine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The mono-ethanolamine market is projected to reach US$1.90 billion by 2033. Explore demand in gas treatment, personal care, and key regional markets.
Moisture Curing Adhesive Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The moisture curing adhesive market is projected to reach US$12.04 billion by 2033. Explore growth in polyurethane, automotive bonding, and Asia Pacific.