


Solar Shading Systems Market
Solar Shading Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Solar Shading Systems Market Size and Trend Analysis
Why is the solar shading systems market growing?
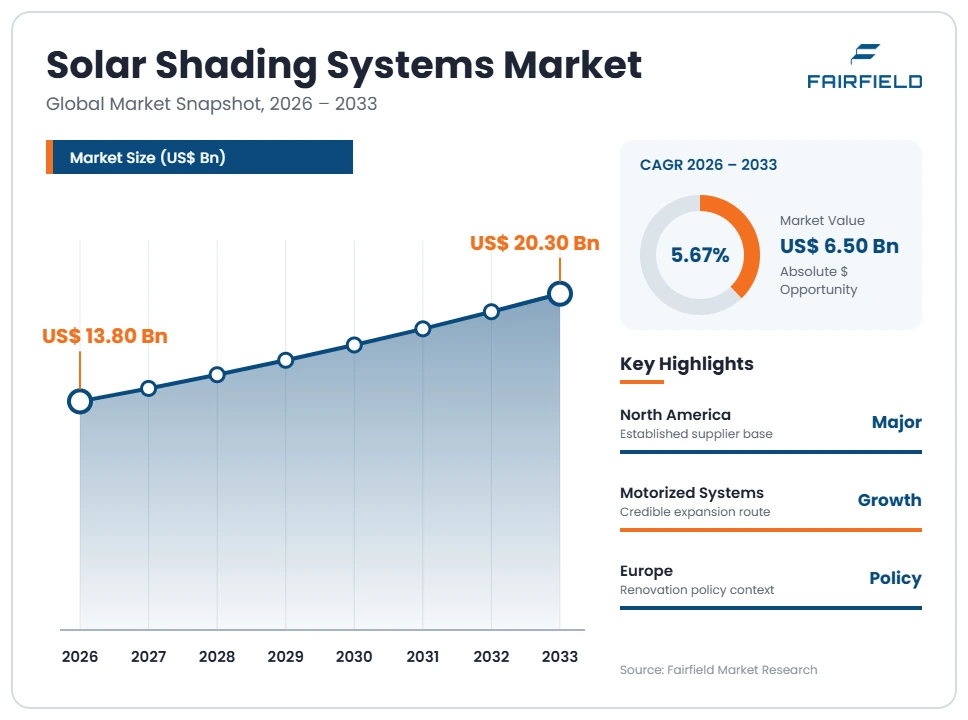
The global Solar Shading Systems market size is expected to be valued at US$13.80 billion in 2026 and projected to reach US$20.30 billion by 2033, growing at a CAGR of 5.67% between 2026 and 2033. Commercial demand connects solar heat control with visual comfort, building operation, and architectural requirements. The opportunity spans simple fixed devices, manually operated products, and coordinated motorized installations.
During 2020–2025, suppliers expanded connected controls and retrofit-oriented solutions alongside established shading products. A comparable historical CAGR is unavailable; back-calculation from the selected forecast implies a 2025 value of approximately US$13.06 billion. Heat management, refurbishment, and improved operating convenience support adoption. However, fabric choice, orientation, commissioning, and user behavior influence results. Growth therefore depends on practical installed performance rather than assuming that every automated product delivers identical energy savings or replaces mechanical cooling completely.
Key Report Takeaways
- By Product Type: Blinds, Fabric Shades and Screens, and Architectural Louvers and Awnings serve different light-control needs. Comparable product shares are unavailable. Design teams should select a system for its exposure, daylight function, and installation constraints.
- By Operating Mechanism: Motorized Systems offer a credible expansion route through scheduling and coordinated control. Hunter Douglas and Lutron Electronics demonstrate established automation offerings. Fixed Systems and Manual Systems remain relevant where simplicity, limited intervention, or lower initial cost meets the purchasing requirement.
- By Project Type: Retrofit Projects create opportunities to improve existing spaces without rebuilding an entire facade. WAREMA’s installation-focused development illustrates supplier attention to this requirement. New Construction Projects can accommodate integrated mounting and wiring earlier, although procurement remains sensitive to construction schedules.
- By Geography: Europe has a clear renovation-policy context, while North America has established shading and control suppliers. Asia Pacific offers varied climate and construction opportunities. These observations do not establish comparable regional size or growth rankings.
- By Customer Value: Heat control and glare reduction should be evaluated alongside daylight, visibility, and usability. Australian Government guidance emphasizes climate and orientation. A carefully specified shading system can address a building problem, while a generic energy-saving percentage provides limited procurement guidance.
Global Solar Shading Systems Market Trends and Insights
Drivers Impact Analysis
These ratings express analyst judgement about purchasing relevance rather than measured contributions to forecast growth.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Solar heat and glare management | High | All five standard regions | Short term (≤2 years) |
| Connected control and everyday usability | Medium | North America; Europe; Asia Pacific | Medium term (2–4 years) |
Solar Shading Systems Reduce Unwanted Solar Heat
Solar heat management creates demand when direct sunlight contributes to uncomfortable indoor conditions or unnecessary cooling loads. A suitable shading design can reduce unwanted exposure while preserving useful daylight. External solar shading can intercept sunlight outside the glazing, whereas interior products offer other practical advantages, including easier access and privacy control. Neither location is universally preferable: orientation, facade geometry, climate, building use, and the existing window assembly shape the appropriate design and operating strategy.
The Australian Government advises matching shading to climate and orientation, including seasonal differences in temperate conditions. This supports a site-specific purchasing case rather than a universal savings claim. Passive cooling can form part of the solution, alongside ventilation, insulation, glazing, and mechanical systems. Suppliers gain a stronger specification position when they explain those interactions. Buyers should request performance assumptions and maintenance requirements, especially before applying a result from one building to a different location.
Solar Shading Systems Gain Usability Through Coordinated Controls
Coordinated controls can make solar shading more useful when occupants cannot repeatedly adjust coverings during the day. Scheduling, grouped operation, and appropriate sensor inputs help a system respond to changing needs. Automated blinds can also improve access where controls are difficult to reach. The commercial value comes from dependable operation and a suitable control strategy, rather than adding connectivity to a product that lacks a clear role in the customer’s daily routine.
Hunter Douglas PowerView supports scheduled shade movement and smart-home compatibility, while Lutron Electronics offers integrated shading controls. Somfy supplies motors and related control technologies. These offerings demonstrate automation, without establishing interoperability across every product combination. Integration with building management systems can support coordinated operation in larger properties. Installers must still configure limits, grouping, and overrides correctly. Suppliers that simplify commissioning and explain compatibility can improve adoption without relying on unsupported promises of automatic energy savings.
Restraints Impact Analysis
Installed complexity and uncertain project outcomes can constrain adoption even where a product’s intended function is attractive.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Installation and control-integration costs | High | Retrofit and custom-facade projects | Short term (≤2 years) |
| Performance variability and maintenance exposure | Medium | Exterior and highly automated installations | Long term (≥4 years) |
Solar Shading Systems Installation Costs Challenge Retrofit Budgets
Installation costs can delay shading projects when an attractive equipment price excludes important site work. Mounting brackets, access equipment, electrical supply, control hardware, and commissioning all affect the final quotation. Existing buildings may have limited wiring routes or facade restrictions. Comparing manual interior coverings with motorized exterior installations means comparing different systems, not different prices for the same function. This complicates budget approval and comparisons between competing proposals.
Specific cost sources include custom dimensions, fabrication, motor sizing, cabling, building-control interfaces, and installer labor. WAREMA’s prefabricated transom-and-mullion shading development explicitly addresses planning and assembly, illustrating the commercial significance of installation effort. Wireless operation can avoid some wiring work, but does not eliminate power requirements, maintenance, or compatibility checks. Suppliers should separate essential equipment from optional functions and state commissioning responsibilities clearly. Transparent scope helps owners assess whether a proposed installation addresses the original comfort or operational problem.
Solar Shading Systems Performance Depends on Exposure and Operation
Performance variability can weaken buyer confidence when marketing claims are disconnected from site conditions. Fabric openness, color, glazing properties, mounting location, and sun angle influence heat and glare control. Exterior products must also respond appropriately to wind and weather. A device that retracts for protection may provide less shading during that period. Buyers therefore need to understand both the intended benefit and the circumstances under which the system changes position or cannot remain deployed.
Draper’s exterior shade documentation discusses fabric retention and outdoor stabilization, demonstrating why physical design matters. Certification approaches described by the U.S. Department of Energy also distinguish product energy performance under different conditions. These considerations create costs for testing, maintenance access, replacement components, and periodic control review. Suppliers can reduce uncertainty through clear operating envelopes and documented service arrangements. They should not extend product-specific results to buildings without considering lighting, heating, cooling, occupancy, and seasonal effects.
Market Opportunities
Solar Shading Systems Retrofit Packages Address Existing Buildings
Existing buildings create opportunities to package surveying, specification, installation, and service into repeatable retrofit offers. Schools, offices, hospitality properties, and housing operators can face recurring glare or heat problems in selected spaces. A focused intervention may be easier to schedule than a comprehensive facade replacement. The revenue opportunity extends beyond selling a blind: providers can help owners identify priority rooms, compare options, coordinate installation, and maintain consistent settings after handover.
The European Commission lists shading and digital controls among energy-renovation measures, creating a clear institutional context for such offers. This does not guarantee funding or mandate one shading product. Suppliers, facilities contractors, and installers can capture demand by demonstrating suitability and minimizing disruption. A staged program could begin with a representative site before wider deployment. Customers should assess comfort outcomes and operational performance against stated objectives, rather than treating the presence of automation as evidence that a retrofit has succeeded.
Solar Shading Systems Integration Creates Service Revenue
Integration services create an emerging revenue pool when shading becomes part of a coordinated building-control strategy. Owners may need help aligning glare control with lighting, occupancy, and changing room use. After installation, settings can become unsuitable as tenants or operating schedules change. Providers can address that problem through commissioning, periodic adjustment, troubleshooting, and training. The opportunity requires ongoing customer needs and explicit service scope; connected motors do not automatically generate subscriptions.
Lutron Electronics’ integrated controls and Somfy’s motorization ecosystem illustrate the technical foundation for this work. Installers and systems integrators can serve customers that lack specialist staff, particularly in multiroom or multisite properties. Revenue could arise from service agreements or defined support visits, provided access rights and responsibilities are clear. Suppliers should also plan for component compatibility and replacement. A maintainable system with understandable controls supports renewal more effectively than equipment requiring specialist intervention for routine adjustments.
Segment Analysis
- By Product Type: Solar Shading Systems Must Balance Daylight and Exposure
Blinds use adjustable or movable elements to manage light, while Fabric Shades and Screens provide other combinations of filtering, privacy, and visibility. Hunter Douglas and Draper demonstrate available shade products and operating choices. Solar control fabrics should be selected for the intended viewing and heat-control requirements, not only for appearance. Similar-looking fabrics can produce different practical results when combined with different glazing, colors, or installation positions. Evaluation needs a defined room and exposure.
Architectural Louvers and Awnings address facade or window shading through other physical configurations. WAREMA offers both external venetian blinds and window awnings for relevant facade applications. Those examples establish product availability rather than a global sales ranking. Comparable product shares and fastest-growth rates are unavailable. Suppliers should position each category around a clear design problem and provide sufficient specification information. Classifying products by their primary physical form also reduces overlap when reporting sales across multifunctional installations.
- By Operating Mechanism: Solar Shading Systems Automation Requires a Defined Control Purpose
Fixed Systems can provide shading without motors or repeated user action, but their geometry must suit the design conditions. Manual Systems allow adjustment with relatively simple controls, although actual use affects results. These categories remain commercially relevant because some purchasers prefer lower complexity or have limited power and service access. A simple system can be appropriate when its operating limitations are understood and it addresses the intended solar exposure effectively.
Motorized Systems offer scheduling, grouped operation, or sensor-led adjustment, with Hunter Douglas, Lutron Electronics, and Somfy providing relevant technologies. A solar-powered motor uses a small photovoltaic supply to operate the mechanism; this does not make the whole installation an electricity-generating building system. Motorized Systems have a plausible expansion opportunity through improved convenience, but a verified fastest-segment CAGR is unavailable. Buyers should specify power, communications, protective behavior, and manual overrides before choosing equipment. These details influence usability more directly than a broad smart-building label.
- By Project Type: Solar Shading Systems Retrofit and New-Build Purchases Differ
New Construction Projects allow shading to be considered alongside facade geometry, glazing, electrical design, and building controls. Early coordination can clarify mounting arrangements and avoid incompatible specifications. Architects, facade contractors, and systems integrators influence these decisions, making technical submissions and design support commercially important. However, construction schedules and changing project budgets can delay orders. Specification does not guarantee shipment or installation.
Retrofit Projects begin with an existing physical and operational constraint. They may require limited disruption, discreet mounting, or a practical power solution. WAREMA’s assembly-focused facade development and Lutron Electronics’ simplified shade offering illustrate supplier attention to these considerations. Evidence does not establish which project category leads globally or grows fastest. The commercial implication is to maintain separate proposals: new-build sales should emphasize coordination, while retrofit proposals should make surveying, access, installation, and handover responsibilities especially clear.
Geography Analysis
- Which Region Is Leading the Solar Shading Systems Market?
A comparable largest-region ranking is not established, although North America has a substantial shading and automation supplier base. The United States is home to companies including Lutron Electronics and Draper, while Canada is relevant to regional specification and installation channels. Hunter Douglas also serves residential customers with automated window treatments. These examples demonstrate commercial activity rather than measured regional market share.
Opportunities include residential upgrades, commercial glare management, and integration with existing control systems. Buyers should assess local installation capacity and product support alongside design preferences. Product-performance documentation can improve comparisons where thermal benefits influence procurement. Proposals should connect a defined room or building problem with an appropriate installation, rather than infer demand from smart-home adoption.
- Solar Shading Systems in Europe Gain a Clear Renovation Policy Context
Europe offers a documented policy context for building renovation and energy performance. The European Commission includes shading and digital controls among relevant renovation measures. Germany provides a directly verifiable supplier and installation example through WAREMA, while France is important to the motorization ecosystem represented by Somfy. The United Kingdom is another relevant market for design and integration services.
Commercial opportunities lie in specifying shading alongside wider building improvements, rather than promising a universal reduction in cooling demand. Requirements differ by climate, facade orientation, occupancy, and national implementation. Policy support should not be described as a blanket obligation to install one product or brand. Suppliers can improve adoption through clear performance assumptions, installer training, and practical support for existing buildings with mounting or wiring constraints.
- Which Region Is Growing Fastest in Solar Shading Systems?
A comparable fastest-growing region is not established from the selected evidence; Asia Pacific nevertheless offers varied commercial opportunities. China and India are prospective markets for construction-linked specification, while Australia provides official guidance emphasizing climate-appropriate shading. Regional customers face different combinations of cooling needs, seasonal heating benefits, building forms, and purchasing budgets. A single regional message would overlook important differences.
Somfy markets connected shading in Australia and project motorization solutions in India, illustrating accessible supply channels. Suppliers should prioritize identifiable projects and trained installation partners rather than infer orders from urbanization alone. Solar exposure and local service capability can shape product suitability. Demonstrating an appropriate solution for a defined building is more useful than assigning unsupported national growth rankings or treating all climates within the region as equivalent.
- Solar Shading Systems in Latin America Need Accessible Installation Models
Latin America offers potential in residential upgrades, commercial spaces, and hospitality properties where glare or heat affects usability. Brazil and Mexico are reasonable initial markets for customer discovery, rather than verified regional sales leaders. Interior products may offer a simpler starting point where facade changes are difficult, while exterior products require suitable mounting and exposure assessment.
Budget sensitivity, import costs, installer skills, and after-sales access can constrain adoption. Local partners can help suppliers adapt quotation, installation, and maintenance to customer expectations. Proposals should explain included equipment and repair or adjustment arrangements. Demonstration projects could establish customer value without requiring a complete property renovation. Regional shares and growth rates remain unquantified because the available evidence does not support a comparable numerical allocation.
- Solar Shading Systems in Middle East & Africa Need Robust Exposure Design
Middle East & Africa presents selective opportunities where solar exposure creates a clear comfort or building-operation problem. Saudi Arabia and the United Arab Emirates are prospective markets for specified commercial solutions, while South Africa is relevant for residential and institutional applications. These examples identify potential customer settings, not verified country rankings. Product selection must reflect the actual site rather than broad assumptions about regional climate.
Dust, wind, access, and prolonged exposure can influence maintenance and protective operating behavior. Customers should assess cleaning arrangements, material durability, and component availability before approving a motorized exterior installation. Suppliers could combine shading with design support for building owners and facilities teams. Local service capability may be especially important when equipment is difficult to reach. A reliable operating plan strengthens the purchasing case.
Competitive Landscape
Competition spans finished shading products, facade integration, motors, controls, and installation services. A medium concentration assessment describes this mixed structure qualitatively; no concentration ratio is claimed. Hunter Douglas, Lutron Electronics, WAREMA, Draper, and Somfy participate at different points in the value chain. A motor supplier’s revenue should not be added again to a finished-system sale when estimating the market. Their inclusion identifies capabilities rather than equivalent business models or market rankings.
Suppliers compete on physical performance, appearance, operating noise, installation effort, controls, and support. Residential purchasing often involves design preferences and dealer relationships. Commercial projects can require detailed submissions, coordination with other contractors, and predictable commissioning. These differences create room for specialists with a clear application focus. A technically capable product can still struggle commercially if quotations omit essential hardware, installation guidance is incomplete, or ordinary adjustments depend on unavailable specialist support.
Recent developments show attention to both installation and user experience. WAREMA revised its transom-and-mullion shading for easier planning and assembly. Lutron Electronics introduced a simplified roller-shade offering and subsequently announced sun-responsive smart wood blinds. Somfy presented new shade-motor technology through an industry exhibition announcement. These developments address different purchasing barriers without establishing identical capabilities, universal availability, or suitability for every facade.
Strategic differentiation should connect the installed system with a defined customer outcome. Providers can improve their position through compatibility documentation, appropriate performance evidence, and reliable commissioning. Fabric and mechanism choices should remain consistent with the proposed operating strategy. Partnerships between product manufacturers and qualified installers can improve delivery, while service agreements may support ongoing usability. Buyers should compare complete scope and maintenance responsibilities rather than rank suppliers from isolated features or assume automation ensures better performance.
Recent Industry Developments
- October 2024: Lutron Electronics introduced the Triathlon Select roller shade, emphasizing simplified specification and quoting for professional installers.
- January 2025: WAREMA announced revised transom-and-mullion shading, targeting easier assembly and integration into building facades.
- April 2025: Somfy announced new shade-motor technologies for the International Window Coverings Expo, expanding light-control options.
- January 2026: Lutron Electronics announced Caséta Smart Wood Blinds with sun-responsive tilting, extending its automated daylight-control offering.
Companies Covered in the Report
Hunter Douglas; Lutron Electronics; WAREMA; Draper; Somfy. Coverage includes finished-system manufacturers and component/control suppliers, with value-chain overlap excluded from market totals.
Solar Shading Systems Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$13.80 Billion |
| Market Size 2033 | US$20.30 Billion |
| CAGR 2026–2033 | 5.67% |
| Absolute Dollar Opportunity | US$6.50 Billion |
| Largest Market | Not independently established across comparable definitions |
| Fastest-Growing Market | Not independently established; regional opportunities assessed qualitatively |
| Market Concentration | Medium, qualitative assessment |
| Major Players | Hunter Douglas, Lutron Electronics, WAREMA, Draper, Somfy |
Solar Shading Systems Market Segmentation
Product Type
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
Operating Mechanism
- Fixed Systems
- Manual Systems
- Motorized Systems
Project Type
- New Construction Projects
- Retrofit Projects
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Solar Shading Systems Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Solar Shading Systems Reduce Unwanted Solar Heat
- Solar Shading Systems Gain Usability Through Coordinated Controls
- Restraints
- Solar Shading Systems Installation Costs Challenge Retrofit Budgets
- Solar Shading Systems Performance Depends on Exposure and Operation
- Market Opportunities
- Solar Shading Systems Retrofit Packages Address Existing Buildings
- Solar Shading Systems Integration Creates Service Revenue
- Drivers
- Global Solar Shading Systems Market Outlook, 2020–2033
- Global Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- Global Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- Global Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- Global Solar Shading Systems Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Solar Shading Systems Market Outlook, 2020–2033
- North America Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- North America Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- North America Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- North America Solar Shading Systems Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- United States Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- United States Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Canada Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Canada Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Canada Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- North America Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Solar Shading Systems Market Outlook, 2020–2033
- Europe Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- Europe Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- Europe Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- Europe Solar Shading Systems Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Germany Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Germany Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- France Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- France Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- France Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- United Kingdom Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- United Kingdom Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- United Kingdom Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Europe Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Solar Shading Systems Market Outlook, 2020–2033
- Asia Pacific Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- Asia Pacific Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- Asia Pacific Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- Asia Pacific Solar Shading Systems Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- China Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- China Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- India Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- India Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- India Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Australia Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Australia Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Australia Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Asia Pacific Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Solar Shading Systems Market Outlook, 2020–2033
- Latin America Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- Latin America Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- Latin America Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- Latin America Solar Shading Systems Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Brazil Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Brazil Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Mexico Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Mexico Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Mexico Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Latin America Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Solar Shading Systems Market Outlook, 2020–2033
- Middle East & Africa Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
- Middle East & Africa Solar Shading Systems Market Outlook, by Operating Mechanism, Value (US$ Billion), 2020–2033
- Fixed Systems
- Manual Systems
- Motorized Systems
- Middle East & Africa Solar Shading Systems Market Outlook, by Project Type, Value (US$ Billion), 2020–2033
- New Construction Projects
- Retrofit Projects
- Middle East & Africa Solar Shading Systems Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- Saudi Arabia Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- United Arab Emirates Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- United Arab Emirates Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- South Africa Solar Shading Systems Market Outlook, by Product Type, 2020–2033
- South Africa Solar Shading Systems Market Outlook, by Operating Mechanism, 2020–2033
- South Africa Solar Shading Systems Market Outlook, by Project Type, 2020–2033
- Middle East & Africa Solar Shading Systems Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Hunter Douglas
- Lutron Electronics
- WAREMA
- Draper
- Somfy
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Blinds
- Fabric Shades and Screens
- Architectural Louvers and Awnings
Operating Mechanism
- Fixed Systems
- Manual Systems
- Motorized Systems
Project Type
- New Construction Projects
- Retrofit Projects
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Solar Shading Systems Market is estimated at US$13.80 billion in 2026, covering dedicated shading products and their integral operating mechanisms and controls.
The Solar Shading Systems Market is projected to reach US$20.30 billion by 2033, implying a 5.67% CAGR and US$6.50 billion additional opportunity.
A comparable product-type leader is not established; Blinds, Fabric Shades and Screens, and Architectural Louvers and Awnings serve distinct specification and purchasing requirements.
Motorized Systems have a credible expansion opportunity through coordinated control and convenience, although the evidence does not establish a fastest-segment growth ranking.
A comparable largest-region ranking remains unverified; North America has established suppliers, while Europe provides a clear building-renovation context supporting shading-related customer opportunities.
Related Reports
Photovoltaic Glass Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global photovoltaic glass market is valued at US$21.6 billion in 2026, reaching US$42.4 billion by 2033, growing at a 10.1% CAGR
Oil and Gas Asset Integrity Management Services Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global oil and gas asset integrity management services market is valued at US$26.0 billion in 2026, reaching US$41.0 billion by 2033, growing at a 6.7% CAGR
LNG Carrier Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global LNG carrier market is valued at US$22.0 billion in 2026, reaching US$31.0 billion by 2033, growing at a 5.0% CAGR
Intelligent Pumps Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global intelligent pumps market is valued at US$10.8 billion in 2026, reaching US$19.6 billion by 2033, growing at an 8.9% CAGR
Automated Mooring Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automated mooring systems market is valued at US$0.5 billion in 2026, reaching US$1.1 billion by 2033, growing at an 11.9% CAGR
Toroidal Transformers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global toroidal transformers market is valued at US$1.2 billion in 2026, reaching US$1.8 billion by 2033, growing at a 6.0% CAGR