


Solid-state Battery Market
Solid-state Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Solid-state Battery Market Size and Trend Analysis
How Big Will the Solid-state Battery Market Get?
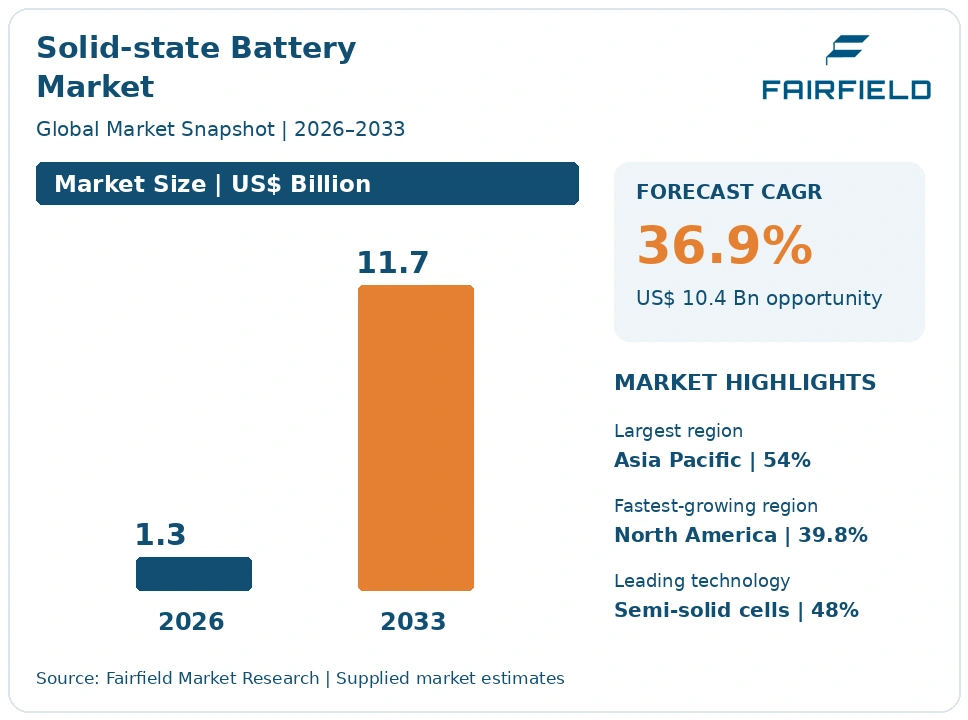
The global Solid-state Battery market size is expected to be valued at US$ 1.3 billion in 2026 and projected to reach US$ 11.7 billion by 2033, growing at a CAGR of 36.9% between 2026 and 2033.
The market expanded at roughly a 31.5% CAGR between 2020 and 2025, reaching about US$ 950 million, almost entirely on semi-solid and quasi-solid cells rather than all-solid-state products. The precise 2026 figure is US$ 1,295 million, rising to US$ 11,680 million by 2033. Three factors carry the forecast. Buyers of premium consumer devices accept a cell price premium for thinner, higher-energy packs. Carmakers in Japan, China and South Korea are funding qualification lines. Transport and vehicle safety rules, including UN 38.3 and ISO 6469, reward chemistries without flammable liquid electrolyte. The direction is an early ramp rather than a step change, and announced automotive launch dates across the industry have repeatedly moved.
Key Report Takeaways
- By Technology: Semi-solid cells held 48% share in 2026, while all-solid-state cells are projected to expand at a 47.2% CAGR through 2033, driven by vehicle qualification programmes that require complete removal of the flammable liquid electrolyte.
- By Electrolyte Type: Polymer-hybrid systems held 38% share in 2026, while sulphide electrolytes are projected to grow at a 44.6% CAGR through 2033, because their high ionic conductivity suits the large-format cells carmakers want.
- By Form Factor: Pouch cells held 46% share in 2026, while prismatic formats are projected to advance at a 41.8% CAGR through 2033, reflecting the stack pressure and module packaging requirements of vehicle battery systems.
- By Application: Consumer electronics held 41% share in 2026, while automotive is projected to rise at a 46.5% CAGR through 2033, as electric vehicle makers move solid-state cells from test fleets toward limited series production.
- By Geography: Asia Pacific held 54% share in 2026, while North America is projected to grow at a 39.8% CAGR through 2033, supported by federal production credits and a dense cluster of venture-funded cell developers.
Global Solid-state Battery Market Trends and Insights
Drivers Impact Analysis
Two demand pulls account for most of the forecast growth in solid electrolyte cells.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Energy density ceiling in premium consumer devices | High | Asia Pacific, North America | Short term ≤2 years |
| Thermal runaway containment cost in electric vehicles | High | Asia Pacific, Europe, North America | Long term ≥4 years |
Premium Consumer Devices Pull Semi-solid Cells into Volume Solid-state Battery Production
Consumer electronics is the first volume outlet for solid electrolyte cells, and it is pulling semi-solid designs into commercial production now. Smartwatches, wireless earbuds, smartphones and implantable medical devices need more energy in the same enclosure, and buyers in these categories tolerate a cell price far above the automotive threshold. Shipments today are small-format pouch and thin-film cells measured in milliamp-hours, not kilowatt-hours.
The mechanism is physical rather than commercial. Replacing most of the liquid electrolyte with a gel or ceramic-filled layer lets designers thin the stack and lift volumetric energy density without altering the device housing. Qualification is also quicker, because small cells clear UN 38.3 transport testing and UL 1973 safety requirements with far less effort than a traction pack. That shortens the path from pilot line to shipping product.
Thermal Runaway Containment Costs in Electric Vehicles Favour Non-flammable Solid Electrolytes
Vehicle safety engineering is the second demand pull for solid-state cells, because pack-level containment is expensive. A conventional traction pack carries cooling plates, fire barriers, venting paths and crash structures sized for a thermal runaway event. A cell that removes the flammable carbonate electrolyte allows engineers to trim that overhead, recovering mass and volume at pack level even when the cell itself costs more to build.
The regulatory frame makes this concrete. IEC 62660 defines performance and reliability testing for lithium-ion cells in electric road vehicles, ISO 6469 sets vehicle-level electrical safety requirements, and UL 2580 covers batteries used in electric vehicles. Each pushes designers toward cells that fail benignly. Carmakers in Japan, South Korea and China are funding solid electrolyte qualification work, supported by public schemes such as the Green Innovation Fund battery programme.
Restraints Impact Analysis
Two technical constraints explain why all-solid-state cells remain outside volume automotive production.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Interfacial resistance and stack pressure requirements | High | Global | Long term ≥4 years |
| Dry-room manufacture and low first-pass yield | Medium | Asia Pacific, Europe | Medium term 2–4 years |
Interfacial Resistance and Stack Pressure Requirements Keep All-solid-state Packs Expensive
Interfacial resistance at the electrolyte-electrode boundary is the main reason all-solid-state cells are not yet in volume automotive production. Two rigid solids do not stay in intimate contact as the anode expands and contracts on every cycle. Contact loss raises impedance, cuts available power and shortens life, so cells underperform their laboratory data once they are cycled against a realistic duty profile.
The practical remedy is mechanical, and it costs money. Many designs need sustained stack pressure applied by springs, plates or pressurised housings, which adds mass, volume and parts at module level. That overhead erodes the energy density advantage that justified the switch. Lithium dendrites can also propagate along grain boundaries and voids inside a solid electrolyte, so charge rates stay conservative until that penetration failure mode is reliably controlled.
Dry-room Manufacture of Sulphide Electrolytes Caps Yield and Raises Cell Cost
Manufacturing yield, not chemistry, is the binding constraint on sulphide cell cost today. Sulphide electrolytes react with moisture and can release hydrogen sulphide, so every handling step runs inside a dry room held at a far lower dew point than conventional cell assembly requires. Building and operating that environment adds capital cost and continuous energy cost to each square metre of production floor.
The cost sources are specific. Dehumidification plant, airlocks, inert transfer and operator protocols raise fixed cost, while thin and brittle electrolyte layers crack or pinhole during calendering and stacking, which lowers first-pass yield. Low yield spreads fixed cost across fewer saleable cells. Moving from coin and pilot pouch formats to large automotive cells worsens the problem, because defect probability rises with electrode area and stacked layer count.
Market Opportunities
Medical, Aerospace and Defence Cells Open a High-margin Pool Before Automotive Scale
Low-volume, high-value applications form an addressable revenue pool that does not wait for automotive qualification. Implantable medical devices, hearing aids, satellites, high-altitude platforms and dismounted soldier power all pay several times the consumer cell price for safety, long calendar life and tolerance of extreme temperature. These buyers value non-flammability directly, so they will fund cells at pilot-line volumes rather than gigafactory volumes.
Cell makers with small-format oxide or thin-film capability can capture this pool first, because the qualification burden is device-specific rather than fleet-wide. Demand comes from medical device manufacturers, satellite integrators and defence primes, all of which already run long component approval cycles. Procurement rules that reward non-flammable chemistry in enclosed or crewed spaces support the shift, and the resulting revenue funds the learning needed for larger cells.
Dry-electrode and Stacking Equipment Supply Becomes a Pool as Pilot Lines Convert
Production equipment is an emerging revenue pool inside the solid-state battery value chain. Solid electrolyte cells need isostatic or roll pressing, dry electrode coating, precise layer stacking and dry-room integration, and most of that tooling does not exist in conventional lithium-ion plants. Every pilot line converted or newly built generates equipment spending long before a single qualified cell is sold.
Machinery builders, dry-room contractors, inspection vendors and metrology suppliers are positioned to capture this pool. Demand comes from cell makers, materials firms and carmakers running qualification lines in Japan, South Korea, China, Germany and the United States. Public schemes that co-fund pilot capacity, including European battery research programmes and the Green Innovation Fund, support the spending. Equipment revenue therefore leads qualified cell revenue by several years across this market, which makes tooling suppliers an unusually early indicator of where production will land.
Segment Analysis
By Technology: Semi-solid Cells Lead While All-solid-state Scales Fastest
Semi-solid cells held 48% of revenue in 2026 because they are the form actually shipping. They retain a small quantity of liquid or gel electrolyte, so they can be built on modified conventional equipment and qualified without solving contact loss at every interface. Quasi-solid designs followed at 31%, thin-film solid-state at 8%. All-solid-state cells held only 13% but are projected to expand at a 47.2% CAGR to 2033, the fastest rate in the market, as carmakers complete multi-year qualification cycles and the first limited-series vehicle programmes begin. The split matters commercially. Revenue in the near term comes from intermediates that work today, while valuation and engineering effort sit with the all-solid-state endpoint. Suppliers that treat semi-solid production as a funding bridge, rather than a destination, are the ones able to sustain the research spending that the final transition requires.
By Electrolyte Type: Polymer-hybrid Chemistry Holds Share as Sulphide Systems Accelerate
Polymer-hybrid electrolytes held 38% share in 2026, the largest of any chemistry, because ceramic-filled polymer layers tolerate imperfect contact and process on existing coating lines. Oxide electrolytes followed at 29%, serving thin-film and microbattery formats where rigidity is acceptable. Halide systems remained small at 9%. Sulphide electrolytes held 24% and are projected to grow at a 44.6% CAGR through 2033, the fastest of the four, because their ionic conductivity approaches that of liquid electrolyte and suits the thick, large-area electrodes a traction cell needs. The trade-off is handling: sulphides demand dry-room manufacture, which is why their share lags their technical promise. Chemistry choice therefore determines factory design as much as cell performance, and suppliers are increasingly committing to one electrolyte family rather than hedging across several incompatible process routes.
By Form Factor: Pouch Cells Dominate While Prismatic Formats Gain on Vehicle Qualification
Pouch cells held 46% of 2026 revenue, reflecting the consumer electronics and medical applications where most solid electrolyte cells currently ship. Pouches are simple to stack, tolerate modest swelling and suit small capacities. Cylindrical cells held 17% and thin-film formats 8%. Prismatic cells held 29% and are projected to advance at a 41.8% CAGR to 2033, the fastest format, because a rigid metal can is the practical way to apply and hold the stack pressure that solid electrolyte cells require. Prismatic housings also pack efficiently into vehicle modules and simplify cooling plate contact. The implication is that format follows the pressure problem. As automotive volumes approach, demand shifts from flexible packaging toward stiff enclosures, changing the equipment and component supply base that serves the sector.
By Application: Consumer Electronics Leads Today While Automotive Grows Quickest to 2033
Consumer electronics held 41% share in 2026, the leading application, because small cells reach market without fleet-scale qualification and buyers absorb the price premium. Energy storage systems held 14%, medical devices 10% and aerospace and defence 8%. Automotive held 27% and is projected to rise at a 46.5% CAGR through 2033, the fastest application, as electric vehicle makers move from test fleets to limited series production. That growth is a ramp, not a switch: vehicle volumes build slowly from a small base, and several announced launch dates have already slipped. The business implication is sequencing. Suppliers need consumer and medical revenue to survive the automotive qualification period, which routinely runs five years or longer from first sample to production part approval, and underestimating that gap has stranded several developers.
Geography Analysis
Which Region Is Growing Fastest in the Solid-state Battery Market?
North America is growing fastest, at a projected 39.8% CAGR between 2026 and 2033, from a 21% share of global revenue in 2026. The United States accounts for most of it, with a dense cluster of venture-funded cell developers concentrated in California, Colorado and Massachusetts, supported by university and national laboratory research. The Inflation Reduction Act production credits and critical mineral sourcing rules give domestic cell manufacture a durable cost advantage, which has drawn carmaker investment into joint development programmes. Canada contributes materials processing capacity. The main barrier is the gap between prototype and production: several developers have strong cell data but no qualified volume line. The change to watch is the conversion of pilot capacity into automotive-grade output, which will decide whether the region converts research leadership into cell revenue.
Europe Turns Battery Regulation Compliance Into a Solid-state Qualification Requirement
Europe held 19% of 2026 revenue and is projected to grow at a 38.0% CAGR to 2033, placing it second for growth. Germany, France and the Netherlands lead, driven by premium carmakers that treat solid electrolyte cells as a differentiation route rather than a cost play. Regulation is unusually influential here. The EU Batteries Regulation imposes carbon footprint declarations, recycled content thresholds and a battery passport, so any new chemistry must arrive with traceable material data from the first production cell. That raises entry cost but rewards suppliers who design for compliance early. Research funding through European battery programmes supports pilot lines and materials work. The barrier is manufacturing scale: cell assembly capacity remains limited relative to vehicle demand, leaving the region dependent on imported cells and equipment during the ramp.
Which Region Is Leading the Solid-state Battery Market?
Asia Pacific leads the solid-state battery market with 54% of revenue in 2026 and a projected 36.4% CAGR to 2033. Japan holds the deepest patent position and the longest-running national battery programme, with the Green Innovation Fund supporting sulphide electrolyte development across carmakers and materials suppliers. China contributes the largest volume of semi-solid cell production, the most pilot capacity and almost all of the precursor and separator supply chain. South Korea adds cell engineering depth and equipment capability. The regional advantage is integration: electrolyte materials, electrode coating, dry-room construction and cell assembly all exist within a few hours of each other, which compresses development cycles. The change to watch is whether domestic electric vehicle makers commit volume platforms to solid electrolyte cells, which would convert pilot lines into sustained demand.
Latin America Builds Lithium Supply While Solid-state Cell Demand Stays Small
Latin America held 3.5% of 2026 revenue and is projected to grow at a 31.0% CAGR to 2033, the slowest major geography. Chile, Argentina and Brazil matter far more as lithium resource holders than as cell consumers, and lithium carbonate and hydroxide from the region feeds electrolyte and cathode production elsewhere. Cell demand is concentrated in imported consumer devices and a small number of electric vehicle fleet trials. The barriers are structural: no domestic dry-room cell manufacturing, limited high-purity chemical processing and a vehicle market that still favours internal combustion and flex-fuel powertrains. The opportunity is upstream integration. Moving from brine extraction into battery-grade lithium metal and electrolyte precursors would capture value from the solid electrolyte transition without requiring the region to build cell assembly capacity first.
Middle East & Africa Links Solid-state Interest to Grid Storage and Sovereign Investment
Middle East & Africa held 2.5% of 2026 revenue, the smallest share, with a projected 29.5% CAGR to 2033. Activity concentrates in the United Arab Emirates and Saudi Arabia, where sovereign investment vehicles have taken positions in battery technology developers and where national industrial strategies target energy storage manufacturing. Morocco and South Africa contribute cathode materials and mineral processing. Demand for solid electrolyte cells themselves is minimal, limited to specialist electronics and early grid storage evaluation. The barriers are severe: extreme ambient temperatures complicate thermal management, skilled cell manufacturing labour is scarce, and no qualification infrastructure exists. The opportunity lies in capital rather than consumption, since regional funds can finance pilot capacity elsewhere and negotiate technology transfer terms that seed local assembly later in the forecast period.
Competitive Landscape
The solid-state battery market is moderately concentrated, and concentration is rising as qualification costs filter out underfunded entrants. Three groups compete. Established cell manufacturers bring process engineering, existing automotive relationships and the balance sheet to absorb a long qualification cycle. Carmakers run internal cell programmes and joint ventures to control the technology rather than buy it. Specialist developers hold distinctive electrolyte chemistry and intellectual property but depend on external capital and partner manufacturing. Consolidation so far has taken the form of carmakers taking equity positions in developers rather than outright acquisition, which preserves the developer’s research culture while securing supply options.
Competition turns on a narrow set of factors. Demonstrated cycle life under realistic pressure and temperature conditions matters more than peak energy density, because customers have learned to discount laboratory cell data. Manufacturability is the second axis: whether a chemistry can run on modified existing equipment or demands an entirely new line. Patent position around electrolyte composition and interface engineering is the third, and it is unusually dense in this market. New entrants increasingly compete on the process rather than the material, offering coating, pressing or stacking methods that raise yield on chemistries others already own.
Strategic activity concentrates on pilot capacity, joint development agreements with vehicle manufacturers and upstream securing of lithium metal foil and specialty precursors. Materials and equipment suppliers are positioning alongside cell makers, because a solid electrolyte line reshapes the supplier list for coating, pressing and dry-room systems.
The prevailing strategic direction is staged commercialisation. Vendors monetise semi-solid and quasi-solid cells in consumer and specialist applications while funding all-solid-state work, and they are communicating automotive timelines more cautiously after repeated schedule changes across the industry.
Solid-state Battery Industry Leaders
- Toyota Motor Corporation
- Samsung SDI
- QuantumScape Corporation
- ProLogium Technology
- Contemporary Amperex Technology Co. Limited
Recent Industry Developments
August 2022: The United States enacted the Inflation Reduction Act, creating advanced manufacturing production credits for battery cells and modules and critical mineral sourcing conditions for the clean vehicle credit – this made domestic cell manufacturing economics materially more attractive for new chemistries.
December 2023: The United States Department of the Treasury and the Internal Revenue Service issued proposed guidance on the foreign entity of concern restrictions applying to the clean vehicle credit – this forced developers to map electrolyte and precursor supply chains far earlier than planned.
July 2023: The European Union published Regulation (EU) 2023/1542 on batteries and waste batteries in the Official Journal – this set the carbon footprint, recycled content and battery passport framework that any new cell chemistry must satisfy in Europe.
February 2024: Regulation (EU) 2023/1542 became generally applicable and replaced the earlier batteries directive – this started the compliance clock for traceability and material declaration obligations across the battery value chain.
Solid-state Battery Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 1.3 Billion |
| Market Size 2033 | US$ 11.7 Billion |
| CAGR 2026–2033 | 36.9% |
| Absolute Dollar Opportunity | US$ 10.4 Billion |
| Largest Market | Asia Pacific (54% share in 2026) |
| Fastest-Growing Market | North America (39.8% CAGR) |
| Market Concentration | Medium |
| Major Players | Toyota Motor Corporation, Samsung SDI, QuantumScape Corporation, ProLogium Technology |
This report covers solid-state battery cells and the packs built from them, spanning sulphide, oxide, halide and polymer-hybrid solid electrolytes together with the semi-solid and quasi-solid intermediates that precede all-solid-state designs. Conventional liquid electrolyte lithium-ion cells, separators sold alone and upstream lithium mining are excluded. The base year is 2025, the forecast period runs from 2026 to 2033, and all values are stated in US$ Billion.
Solid-state Battery Market Segmentation
Technology
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
Electrolyte Type
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
Form Factor
- Pouch
- Prismatic
- Cylindrical
- Thin-film
Application
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Solid-state Battery Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Premium Consumer Devices Pull Semi-solid Cells into Volume Solid-state Battery Production
- Thermal Runaway Containment Costs in Electric Vehicles Favour Non-flammable Solid Electrolytes
- Restraints
- Interfacial Resistance and Stack Pressure Requirements Keep All-solid-state Packs Expensive
- Dry-room Manufacture of Sulphide Electrolytes Caps Yield and Raises Cell Cost
- Market Opportunities
- Medical, Aerospace and Defence Cells Open a High-margin Pool Before Automotive Scale
- Dry-electrode and Stacking Equipment Supply Becomes a Pool as Pilot Lines Convert
- Drivers
- Global Solid-state Battery Market Outlook, 2020–2033
- Global Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- Global Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- Global Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- Global Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- Global Solid-state Battery Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- North America Solid-state Battery Market Outlook, 2020–2033
- North America Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- North America Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- North America Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- North America Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- North America Solid-state Battery Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Solid-state Battery Market Outlook, by Technology, 2020–2033
- United States Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- United States Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- United States Solid-state Battery Market Outlook, by Application, 2020–2033
- Canada Solid-state Battery Market Outlook, by Technology, 2020–2033
- Canada Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Canada Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Canada Solid-state Battery Market Outlook, by Application, 2020–2033
- North America Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Europe Solid-state Battery Market Outlook, 2020–2033
- Europe Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- Europe Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- Europe Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- Europe Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- Europe Solid-state Battery Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Solid-state Battery Market Outlook, by Technology, 2020–2033
- Germany Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Germany Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Germany Solid-state Battery Market Outlook, by Application, 2020–2033
- France Solid-state Battery Market Outlook, by Technology, 2020–2033
- France Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- France Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- France Solid-state Battery Market Outlook, by Application, 2020–2033
- Netherlands Solid-state Battery Market Outlook, by Technology, 2020–2033
- Netherlands Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Netherlands Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Netherlands Solid-state Battery Market Outlook, by Application, 2020–2033
- Europe Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Asia Pacific Solid-state Battery Market Outlook, 2020–2033
- Asia Pacific Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- Asia Pacific Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- Asia Pacific Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- Asia Pacific Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- Asia Pacific Solid-state Battery Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Japan Solid-state Battery Market Outlook, by Technology, 2020–2033
- Japan Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Japan Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Japan Solid-state Battery Market Outlook, by Application, 2020–2033
- China Solid-state Battery Market Outlook, by Technology, 2020–2033
- China Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- China Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- China Solid-state Battery Market Outlook, by Application, 2020–2033
- South Korea Solid-state Battery Market Outlook, by Technology, 2020–2033
- South Korea Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- South Korea Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- South Korea Solid-state Battery Market Outlook, by Application, 2020–2033
- Asia Pacific Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Latin America Solid-state Battery Market Outlook, 2020–2033
- Latin America Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- Latin America Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- Latin America Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- Latin America Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- Latin America Solid-state Battery Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Chile Solid-state Battery Market Outlook, by Technology, 2020–2033
- Chile Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Chile Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Chile Solid-state Battery Market Outlook, by Application, 2020–2033
- Argentina Solid-state Battery Market Outlook, by Technology, 2020–2033
- Argentina Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Argentina Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Argentina Solid-state Battery Market Outlook, by Application, 2020–2033
- Brazil Solid-state Battery Market Outlook, by Technology, 2020–2033
- Brazil Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Brazil Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Brazil Solid-state Battery Market Outlook, by Application, 2020–2033
- Latin America Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Middle East & Africa Solid-state Battery Market Outlook, 2020–2033
- Middle East & Africa Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
- Middle East & Africa Solid-state Battery Market Outlook, by Electrolyte Type, Value (US$ Billion), 2020–2033
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
- Middle East & Africa Solid-state Battery Market Outlook, by Form Factor, Value (US$ Billion), 2020–2033
- Pouch
- Prismatic
- Cylindrical
- Thin-film
- Middle East & Africa Solid-state Battery Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
- Middle East & Africa Solid-state Battery Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Solid-state Battery Market Outlook, by Technology, 2020–2033
- United Arab Emirates Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- United Arab Emirates Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- United Arab Emirates Solid-state Battery Market Outlook, by Application, 2020–2033
- Saudi Arabia Solid-state Battery Market Outlook, by Technology, 2020–2033
- Saudi Arabia Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Saudi Arabia Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Saudi Arabia Solid-state Battery Market Outlook, by Application, 2020–2033
- Morocco Solid-state Battery Market Outlook, by Technology, 2020–2033
- Morocco Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- Morocco Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- Morocco Solid-state Battery Market Outlook, by Application, 2020–2033
- South Africa Solid-state Battery Market Outlook, by Technology, 2020–2033
- South Africa Solid-state Battery Market Outlook, by Electrolyte Type, 2020–2033
- South Africa Solid-state Battery Market Outlook, by Form Factor, 2020–2033
- South Africa Solid-state Battery Market Outlook, by Application, 2020–2033
- Middle East & Africa Solid-state Battery Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Toyota Motor Corporation
- Nissan Motor Co., Ltd.
- Samsung SDI
- LG Energy Solution
- Panasonic Energy Co., Ltd.
- Murata Manufacturing Co., Ltd.
- TDK Corporation
- QuantumScape Corporation
- Solid Power, Inc.
- Factorial Energy
- ProLogium Technology
- Ilika plc
- Contemporary Amperex Technology Co. Limited
- WeLion New Energy Technology
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Technology
- Semi-solid
- Quasi-solid
- All-solid-state
- Thin-film solid-state
Electrolyte Type
- Sulphide
- Oxide
- Halide
- Polymer-hybrid
Form Factor
- Pouch
- Prismatic
- Cylindrical
- Thin-film
Application
- Consumer Electronics
- Automotive
- Energy Storage Systems
- Medical Devices
- Aerospace & Defence
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The solid-state battery market is valued at US$ 1.3 billion in 2026, with revenue concentrated in semi-solid and quasi-solid cells rather than all-solid-state products.
The market is projected to reach US$ 11.7 billion by 2033, growing at a 36.9% CAGR and adding US$ 10.4 billion of absolute dollar opportunity.
Semi-solid cells lead with 48% share in 2026, because they ship on modified conventional equipment without solving every solid-to-solid contact problem first.
Automotive is growing fastest at a 46.5% CAGR to 2033, as electric vehicle makers move solid electrolyte cells from test fleets toward limited series production.
Asia Pacific holds the largest share at 54% in 2026, supported by integrated electrolyte materials, equipment and cell assembly capacity across Japan, China and South Korea.
Related Reports
Shale Gas Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the shale gas market outlook for 2026–2033, covering technologies, applications, gas types, regional trends, and leading companies.
Bus HVAC Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the bus HVAC systems market outlook for 2026–2033, covering bus types, propulsion, cooling capacity, regional trends, and leading companies.
Frameless Solar Panels Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the frameless solar panels market outlook for 2026–2033, with cell technologies, mounting trends, regional demand, and competitive insights.
Building Energy Management Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the building energy management systems market outlook for 2026–2033, with component trends, deployment insights, regions, and key suppliers.
Fuel Management System Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global fuel management system market is valued at US$21.4 billion in 2026, reaching US$38.6 billion by 2033, growing at an 8.8% CAGR
Oil Immersed Current Transformer Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The oil immersed current transformer market is projected to grow from US$2.4 billion in 2026 to US$3.6 billion by 2033 at a 6.0% CAGR.