



Titanium Alloy Market
Titanium Alloy Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Titanium Alloy Market Size and Trend Analysis
What drives demand for qualified titanium alloys?
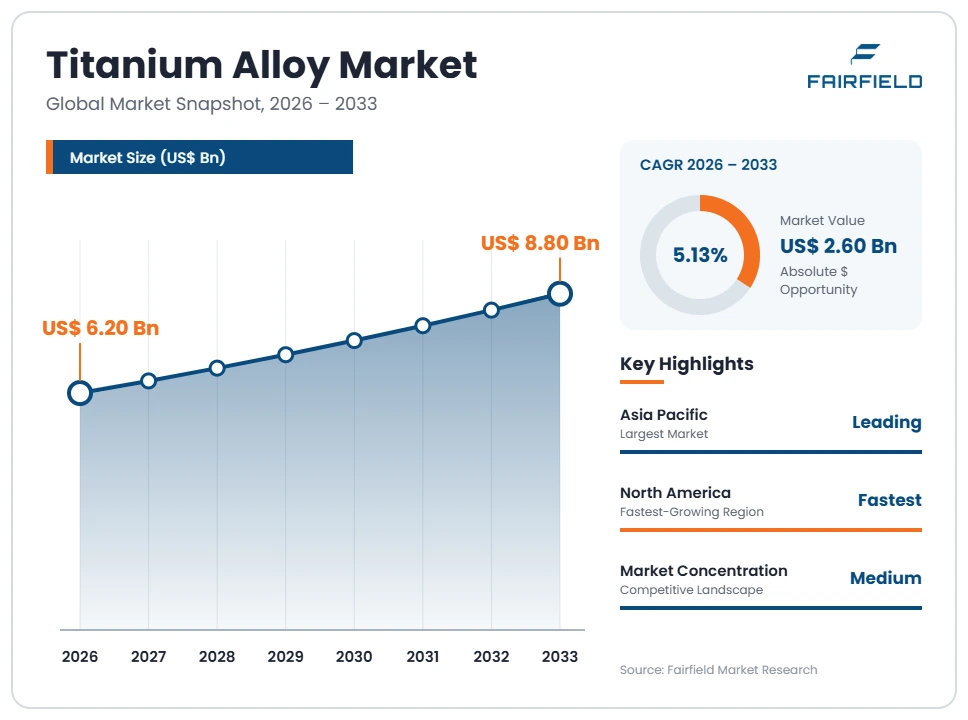
The global Titanium Alloy market size is expected to be valued at US$6.20 billion in 2026 and projected to reach US$8.80 billion by 2033, growing at a CAGR of 5.13% between 2026 and 2033. Demand concerns alloy materials supplied to manufacturers requiring specified properties and product forms. Buyers assess material suitability, traceability, processing condition, and delivery rather than treat all titanium production as interchangeable supply.
During 2020–2025, qualification and production schedules shaped purchasing across aviation, healthcare, and industrial customers. The selected benchmark reports historical growth near 4.5%; its forecast trajectory implies a 2025 value near US$5.90 billion. Aircraft production requirements, medical-device manufacturing, and specialized industrial uses support demand. Processing cost and approved-source constraints can limit substitution. The outlook therefore depends on qualified deliveries and customer schedules, with titanium dioxide, unalloyed metal, and complete aircraft or medical-device values excluded from the alloy-material boundary.
Key Report Takeaways
- By Product Form: Long Products, Flat Products, and Other Alloy Forms serve different manufacturing routes. ATI documents both long and flat offerings, while specialist suppliers provide additional forms. Comparable segment shares and fastest-growth rates are unavailable for this independently defined allocation.
- By Contract Model: Scheduled Supply supports customer programs with agreed delivery arrangements, while Transactional Supply covers other individual purchases. Long-term agreements improve demand visibility without guaranteeing actual shipment volumes. Comparable category leadership and growth rates are not established within the selected public evidence.
- By Customer Use: Flight Hardware, Medical Devices, and Other Industrial Uses require different specifications and supply relationships. Qualification does not automatically transfer between applications. Comparable shares are unavailable for these categories, and the value of finished customer products is excluded from alloy revenue.
- By Geography: Asia Pacific leads the selected benchmark, while North America has its fastest-growth direction. Regional production and final consumption are different measures. National share rankings are not inferred from titanium sponge capacity or a supplier’s planned melting expansion.
- By Competition: ATI, TIMET, Carpenter Technology, Perryman, and Aubert & Duval document relevant titanium capabilities. Competition concerns approved material, processing, delivery, and technical support. Total specialty-metal or component revenues cannot establish directly comparable titanium alloy shares.
Global Titanium Alloy Market Trends and Insights
Drivers Impact Analysis
Impact ratings reflect analyst judgement about material purchasing, rather than unsupported numerical additions to the forecast.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Aircraft program and qualified-material requirements | High | North America; Europe; Asia Pacific | Medium term (2–4 years) |
| Medical and specialized industrial applications | Medium | All five standard regions | Medium term (2–4 years) |
Titanium Alloy Aviation Programs Support Qualified Supply Agreements
Aircraft programs create alloy demand when manufacturers need specified materials for structural or engine-related components. Purchasing follows approved designs, production schedules, and available manufacturing capacity. An aircraft backlog alone does not establish the timing of alloy deliveries, because customers may hold inventory or revise production plans. Suppliers therefore need to connect material commitments with realistic customer requirements. The commercial value lies in dependable qualified supply, with traceability and suitable forms, beyond melting capacity.
ATI announced titanium supply agreements with Airbus and Boeing in 2025, establishing direct commercial relationships. The disclosed portfolios include several material forms, not only one alloy product. These agreements support demand visibility without publishing a universal shipment rate. Buyers should distinguish contractual coverage from actual material releases. Suppliers can strengthen planning through approved processes, consistent quality, and delivery coordination, keeping forecast alloy demand separate from the full financial value of customer aircraft programs.
Titanium Alloy Medical Applications Require Controlled Material Supply
Medical-device manufacturing supports demand where an alloy’s specified characteristics suit the intended component and manufacturing route. Customers need material identity, appropriate processing condition, and documentation that supports their own controlled production. General properties do not establish device suitability. Purchasing decisions therefore involve the exact grade, form, and customer requirements. Demand should be assessed through manufacturing programs and supplied material, rather than equated directly with patient populations or finished implant prices.
Carpenter Technology documents titanium products for medical applications through its specialist capabilities. Aubert & Duval lists titanium grades associated with medical and other uses. These disclosures establish direct participation without making every grade interchangeable or guaranteeing clinical outcomes. Suppliers can differentiate through consistent processing, traceability, and technical support. Buyers should confirm material specifications and manufacturing compatibility. Commercial assessment should separate alloy supply from subsequent machining, device validation, and distribution, preventing the same customer product from inflating several market totals.
Restraints Impact Analysis
Processing economics and customer approval requirements can limit supply responsiveness and restrict entry into demanding applications.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Specialized melting, conversion, and material losses | High | Alloy producers and component manufacturers | Short term (≤2 years) |
| Qualification and delivery-chain constraints | High | Controlled-specification applications | Long term (≥4 years) |
Titanium Alloy Processing Costs Limit Commodity-Like Substitution
Processing costs can restrict alloy adoption when customers compare the complete manufacturing economics against alternative materials. The purchased material may require controlled melting, conversion, heat treatment, finishing, and inspection. Component production can also generate material losses that affect component cost. A comparison based only on alloy price per unit of weight can therefore miss important manufacturing costs. Customers should assess the required properties and process route before assuming that lower weight guarantees lower cost.
TIMET and ATI document integrated titanium processing capabilities, while Perryman describes melting, conversion, and finishing functions. These operations explain why added capacity requires more than an available metal resource. Specific costs include energy, specialist equipment, tooling, inspection, rework, and inventory during processing. Suppliers should distinguish nominal capacity from qualified output. Buyers can improve economics through appropriate product form and manufacturing planning, but savings require application-specific evidence.
Titanium Alloy Qualification Can Delay Additional Supply
Qualification requirements can slow supply expansion when a customer needs material from an approved source and process route. New equipment or a nominally equivalent grade does not automatically satisfy the purchasing specification. Buyers may need evidence relating to composition, processing, inspection, and traceability. These requirements can make supplier changes slower than a simple commodity purchase. The constraint concerns qualified deliverability, rather than general upstream availability.
ATI’s sheet-development disclosure explicitly discusses customer qualifications, while supplier product documentation distinguishes grades and processing conditions. Costs arise from process development, trial material, testing, customer approval, and maintaining records. Producers also need stable downstream conversion and delivery arrangements. Customers should establish which sources and forms are actually approved before treating capacity as interchangeable. Providers can reduce uncertainty through transparent qualification milestones and realistic commitments, avoiding the assumption that every new facility immediately expands usable output for all applications.
Market Opportunities
Titanium Alloy Near-Net Supply Can Address Expensive Conversion Routes
Near-net material supply creates an opportunity where customers can reduce unnecessary conversion work through a more suitable starting form. The commercial offer may involve tailored dimensions, wire, powder-related feedstock, or a defined preform suited to the manufacturing route. Providers need to distinguish material supply from the final component and verify that the proposed form meets customer requirements. The revenue pool concerns qualified input material and associated processing, beyond downstream equipment investment.
Perryman documents wire and bar products supporting additive manufacturing routes. Carpenter Technology also describes titanium-related specialist capabilities. These disclosures support identifiable supplier participation, not a universal reduction in material waste or cost. Producers can pursue customers with established designs and a viable qualification pathway. Buyers should compare yield, finishing, inspection, and production rate alongside the purchased form. Application-specific trials can establish the commercial case, keeping alloy value separate from equipment, printing services, and finished products.
Titanium Alloy Product-Form Expansion Can Strengthen Program Relationships
Product-form expansion creates opportunities for suppliers that can meet more of an existing customer’s qualified material requirements. A buyer may prefer coordinated deliveries across sheet, plate, billet, or bar when specifications and approvals are satisfied. Suppliers can earn additional alloy revenue through conversion capabilities rather than only increasing primary melting. The case depends on customer demand and qualification; a wider catalog alone does not establish profitable orders.
ATI brought its Pageland titanium alloy sheet facility online in June 2025, providing a documented example of form-specific expansion. The development supports additional customer options without establishing full utilization. Producers and processors can pursue programs needing dependable material forms and delivery coordination. Customers should evaluate approved scope, technical support, and release schedules. Suppliers should distinguish potential capacity, contracted coverage, and actual shipments, preventing an investment announcement from being presented as realized market demand before qualified deliveries occur.
Segment Analysis
- By Product Form: Titanium Alloy Manufacturing Routes Determine Useful Supply
Long Products includes alloy bar, wire, and comparable elongated forms. Flat Products includes alloy plate, sheet, and strip or coil. Other Alloy Forms covers remaining supplied forms, such as powder or specified preforms, without counting the final customer component. Assignment follows the material sold at the defined boundary. This avoids treating the same material as separate market revenue whenever it moves between melting, rolling, distribution, and component manufacturing.
Comparable shares and fastest-growth rates are unavailable for these categories. ATI documents a portfolio spanning long and flat materials, while Perryman and Carpenter Technology demonstrate specialist supply capabilities. Buyers should select a starting form that matches manufacturing and approval requirements. Suppliers need appropriate conversion, inspection, and delivery capacity rather than a broad product label alone. The commercial implication is to evaluate actual supplied forms and customer release schedules, keeping metal value distinct from downstream machining or the complete component selling price.
- By Contract Model: Titanium Alloy Agreements Improve Visibility Without Fixing Shipments
Scheduled Supply includes purchases under defined program or delivery arrangements. Transactional Supply covers other individual orders outside those arrangements. Classification follows the commercial agreement, not whether the customer operates in aviation or another industry. A program contract can include several forms and changing release schedules, so its existence should not be interpreted as a fixed annual volume unless that commitment is explicitly disclosed.
Consistent shares and growth rankings are unavailable. ATI’s Airbus and Boeing agreements establish actual program relationships, but their public announcements do not quantify every future release. Suppliers should distinguish contracted access, committed capacity, and recognized revenue. Buyers may value visibility and continuity while retaining responsibilities for forecasts and inventory. Commercial analysis should examine pricing mechanisms, delivery obligations, and qualification scope, rather than assume long-term contracts eliminate exposure to production delays or make all supplied material immediately interchangeable with other sources.
- By Customer Use: Titanium Alloy Qualification Follows the Intended Application
Flight Hardware covers alloy supplied for aircraft and related flight-component manufacturing. Medical Devices covers material purchased for controlled medical manufacturing programs. Other Industrial Uses covers remaining customer applications within the alloy boundary. Assignment follows the documented end use of the material transaction, preventing a supplier’s complete titanium portfolio from being allocated to whichever sector currently has the strongest growth narrative.
Comparable category shares are unavailable for this independent grouping. Aubert & Duval lists titanium grades serving different applications, while Carpenter Technology and TIMET document specialist material capabilities. Buyers should confirm the exact grade, condition, form, and approved source. A grade used in several sectors does not imply identical qualification or processing requirements. Suppliers can improve their proposition through technical support and consistent documentation. Demand estimates should connect actual customer programs with supplied alloy value, excluding the much larger prices of finished aircraft, engines, implants, and other equipment.
Geography Analysis
- Which Region Is Growing Fastest in the Titanium Alloy Market?
North America has the fastest-growth direction in the selected benchmark. The United States provides documented examples through ATI’s customer agreements and alloy sheet expansion. Canada is another relevant industrial customer setting, but no comparable national ranking is adopted. Production, inventory, and final consumption must be distinguished when evaluating regional material flows and supplier opportunity.
Opportunities include qualified product forms, program supply, and suitable manufacturing inputs. Processing cost, customer approvals, and downstream conversion can limit responsiveness. Suppliers should distinguish announced capacity from usable output and actual shipments. Buyers need clarity about qualified sources, inspection, and delivery obligations. Regional strategy is therefore best grounded in documented customer programs rather than inferred directly from aircraft backlog, resource availability, or the nominal capacity of a melting installation.
- Titanium Alloy European Customers Require Approved Material Routes
Europe has a documented supplier and customer base in aviation, medical manufacturing, and specialist industrial uses. France provides a supplier context through Aubert & Duval, while the United Kingdom and Germany are relevant manufacturing settings. ATI’s Airbus agreement establishes an additional commercial relationship. These examples support participation without supplying consistent national market shares or proving that all grades have equivalent local availability.
Opportunities include product-form supply and coordination across approved processing routes. Qualification, conversion capacity, and delivery schedules can constrain procurement. Buyers should confirm specifications and source approvals before comparing price or lead time. Suppliers need transparent records and realistic capacity commitments. The region’s commercial opportunity follows qualified material transactions, not the complete revenue of aircraft programs, medical devices, or broader specialty-metal suppliers operating within Europe.
- Which Region Is Leading the Titanium Alloy Market?
Asia Pacific leads the selected benchmark outlook. China, Japan, and India provide relevant production and customer settings, while other regional markets participate in manufacturing and distribution. No current country shares are adopted. Upstream sponge production, alloy conversion, and final component demand are distinct measures, so regional resource or metal-production figures should not be treated as direct alloy-consumption estimates.
Opportunities include qualified material forms, customer support, and appropriate conversion capabilities. Approval requirements, processing cost, and delivery-chain coordination can restrict market access. Suppliers should establish which products and sources meet the intended customer specification. Buyers benefit from documented material identity and realistic delivery arrangements. Regional growth should be evaluated through actual alloy purchases rather than a fixed multiplier applied to industrial investment or announced downstream production capacity.
- Titanium Alloy Latin American Demand Requires Application-Specific Sourcing
Latin America offers selective demand across manufacturing, healthcare-related production, and industrial applications. Brazil and Mexico provide relevant customer-development settings without implying a verified national ranking. Buyers may require particular grades and forms, but broad manufacturing activity does not establish the quantity of qualified alloy purchased. Suppliers should identify the actual component route and material requirement before treating a customer sector as addressable demand.
Barriers include imported material costs, order scale, processing access, and technical support. Distributors and processors can create opportunities through traceable supply and appropriate stockholding. Buyers should assess documentation and approved sources alongside delivery time. A commercially credible offer connects the supplied alloy with an executable manufacturing process, keeping downstream component value and unrelated titanium products outside the market estimate.
- Titanium Alloy Middle East & Africa Needs Defined Specifications
Middle East & Africa presents selective opportunities in industrial equipment, aviation-related manufacturing, and other specialized uses. The United Arab Emirates, Saudi Arabia, and South Africa are relevant customer settings, rather than verified share leaders. Material demand should be linked to actual manufacturing activity and specifications. The full value of a new industrial facility or aviation investment does not establish an equivalent alloy market opportunity.
Constraints include qualified processing access, procurement scale, logistics, and technical support. Suppliers can pursue traceable material and product-form services where customers have a defined manufacturing route. Buyers should distinguish unalloyed titanium from alloy grades and confirm processing condition. Opportunities become measurable when actual orders, approved sources, and delivery obligations are established, preventing resource projects or general infrastructure announcements from being counted as immediate alloy revenue.
Competitive Landscape
Competition spans integrated titanium producers, specialist converters, and qualified material suppliers. Medium concentration is an analyst judgement about the overall supply base, with more limited options in particular approved applications. ATI, TIMET, Carpenter Technology, Perryman, and Aubert & Duval have documented relevant capabilities. Their broader revenues cannot establish titanium alloy shares because portfolios can include other metals, unalloyed titanium, finished components, and processing services outside the defined material transaction.
Customers compare grade availability, product form, processing capability, traceability, and delivery. New entrants may develop resource or melting access, but still need conversion and qualification before serving demanding customer programs. Established suppliers must also demonstrate that new capacity meets the required scope. A nominally matching alloy composition is insufficient if the purchasing specification includes processing, inspection, or source requirements that have not been satisfied.
Documented moves show the importance of both product forms and customer relationships. ATI signed an Airbus agreement in May 2025, brought alloy sheet production online at Pageland in June 2025, and expanded its Boeing relationship in July 2025. These are distinct commercial developments rather than equivalent additions to shipment volume. The agreements and capacity expansion should be assessed alongside qualification, release schedules, and actual deliveries before their market effect is quantified.
Strategic differentiation should connect approved material with dependable execution. Suppliers can strengthen relationships through technical support, consistent records, and suitable conversion capabilities. Buyers should compare the complete qualified supply route rather than raw metal availability alone. Competitive assessment should distinguish potential capacity, contractual coverage, and realized alloy revenue. This avoids unsupported rankings or predictions about winners, and prevents the full financial value of customer aircraft or medical programs from being misrepresented as titanium material demand.
Recent Industry Developments
- May 2025: ATI announced a multi-year Airbus agreement for titanium plate, sheet, and billet, establishing broader program supply coverage.
- June 2025: ATI brought its Pageland titanium alloy sheet facility online, extending its form-specific manufacturing capabilities for aerospace customers.
- July 2025: ATI extended and expanded its titanium products agreement with Boeing, covering a portfolio of long and flat materials.
Companies Covered in the Report
ATI; TIMET; Carpenter Technology; Perryman; Aubert & Duval; Airbus; Boeing. The aircraft manufacturers are discussed as customers, without treating their complete program values as alloy supplier revenue.
Titanium Alloy Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$6.20 Billion |
| Market Size 2033 | US$8.80 Billion |
| CAGR 2026–2033 | 5.13% |
| Absolute Dollar Opportunity | US$2.60 Billion |
| Largest Market | Asia Pacific, selected benchmark |
| Fastest-Growing Market | North America, selected benchmark |
| Market Concentration | Medium; qualified supply more concentrated, analyst judgement |
| Major Players | ATI, TIMET, Carpenter Technology, Perryman, Aubert & Duval |
Titanium Alloy Market Segmentation
Product Form
- Long Products
- Flat Products
- Other Alloy Forms
Contract Model
- Scheduled Supply
- Transactional Supply
Customer Use
- Flight Hardware
- Medical Devices
- Other Industrial Uses
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Titanium Alloy Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Titanium Alloy Aviation Programs Support Qualified Supply Agreements
- Titanium Alloy Medical Applications Require Controlled Material Supply
- Restraints
- Titanium Alloy Processing Costs Limit Commodity-Like Substitution
- Titanium Alloy Qualification Can Delay Additional Supply
- Market Opportunities
- Titanium Alloy Near-Net Supply Can Address Expensive Conversion Routes
- Titanium Alloy Product-Form Expansion Can Strengthen Program Relationships
- Drivers
- Global Titanium Alloy Market Outlook, 2020–2033
- Global Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- Global Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- Global Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- Global Titanium Alloy Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- North America Titanium Alloy Market Outlook, 2020–2033
- North America Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- North America Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- North America Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- North America Titanium Alloy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Titanium Alloy Market Outlook, by Product Form, 2020–2033
- United States Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- United States Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Canada Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Canada Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Canada Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- North America Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Europe Titanium Alloy Market Outlook, 2020–2033
- Europe Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- Europe Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- Europe Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- Europe Titanium Alloy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- France Titanium Alloy Market Outlook, by Product Form, 2020–2033
- France Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- France Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- United Kingdom Titanium Alloy Market Outlook, by Product Form, 2020–2033
- United Kingdom Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- United Kingdom Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Germany Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Germany Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Germany Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Europe Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Asia Pacific Titanium Alloy Market Outlook, 2020–2033
- Asia Pacific Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- Asia Pacific Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- Asia Pacific Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- Asia Pacific Titanium Alloy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Titanium Alloy Market Outlook, by Product Form, 2020–2033
- China Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- China Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Japan Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Japan Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Japan Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- India Titanium Alloy Market Outlook, by Product Form, 2020–2033
- India Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- India Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Asia Pacific Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Latin America Titanium Alloy Market Outlook, 2020–2033
- Latin America Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- Latin America Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- Latin America Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- Latin America Titanium Alloy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Brazil Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Brazil Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Mexico Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Mexico Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Mexico Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Latin America Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Middle East & Africa Titanium Alloy Market Outlook, 2020–2033
- Middle East & Africa Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Long Products
- Flat Products
- Other Alloy Forms
- Middle East & Africa Titanium Alloy Market Outlook, by Contract Model, Value (US$ Billion), 2020–2033
- Scheduled Supply
- Transactional Supply
- Middle East & Africa Titanium Alloy Market Outlook, by Customer Use, Value (US$ Billion), 2020–2033
- Flight Hardware
- Medical Devices
- Other Industrial Uses
- Middle East & Africa Titanium Alloy Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Titanium Alloy Market Outlook, by Product Form, 2020–2033
- United Arab Emirates Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- United Arab Emirates Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Saudi Arabia Titanium Alloy Market Outlook, by Product Form, 2020–2033
- Saudi Arabia Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- Saudi Arabia Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- South Africa Titanium Alloy Market Outlook, by Product Form, 2020–2033
- South Africa Titanium Alloy Market Outlook, by Contract Model, 2020–2033
- South Africa Titanium Alloy Market Outlook, by Customer Use, 2020–2033
- Middle East & Africa Titanium Alloy Market Outlook, by Product Form, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- ATI
- TIMET
- Carpenter Technology
- Perryman
- Aubert & Duval
- Airbus
- Boeing
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Form
- Long Products
- Flat Products
- Other Alloy Forms
Contract Model
- Scheduled Supply
- Transactional Supply
Customer Use
- Flight Hardware
- Medical Devices
- Other Industrial Uses
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Titanium Alloy Market is estimated at US$6.20 billion in 2026, covering defined alloy materials supplied to manufacturing customers across qualified and industrial applications.
The market is projected to reach US$8.80 billion by 2033, implying 5.13% annual growth and US$2.60 billion additional opportunity within the alloy-material boundary.
A comparable product-form leader is unavailable; Long Products, Flat Products, and Other Alloy Forms serve different manufacturing routes, specifications, and qualified customer requirements.
North America has the fastest-growth direction in the selected benchmark, with documented customer agreements and product-form expansion; comparable national growth rankings remain unavailable.
Asia Pacific leads the selected benchmark outlook, although upstream production, alloy conversion, and final consumption remain distinct measures without comparable country shares adopted here.
Related Reports
Rigid Bulk Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global rigid bulk packaging market is valued at US$68.5 billion in 2026, reaching US$96.4 billion by 2033, growing at a 5.0% CAGR
Probiotics Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the probiotics packaging market, valued at US$ 1.4 billion in 2026 and projected to reach US$ 2.4 billion by 2033, growing at an 8.0% CAGR.
Epoxy Composites Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the epoxy composites market, projected to reach US$ 22.3 billion by 2033 at a 6.7% CAGR, with resin, reinforcement and regional insights.
Advanced Materials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the advanced materials market, projected to reach US$ 121.08 billion by 2033 at a 6.6% CAGR, with product, application and regional insights.
Biopolymer Coatings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the biopolymer coatings market, projected to reach US$ 2.5 billion by 2033 at a 7.6% CAGR, with product, technology and regional insights.
Dry Construction Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the dry construction market, projected to reach US$ 134.87 billion by 2033 at a 4.7% CAGR, with material, system and regional insights.