


3D Bioprinting Market
3D Bioprinting Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
How Fast Is the 3D Bioprinting Market Growing?
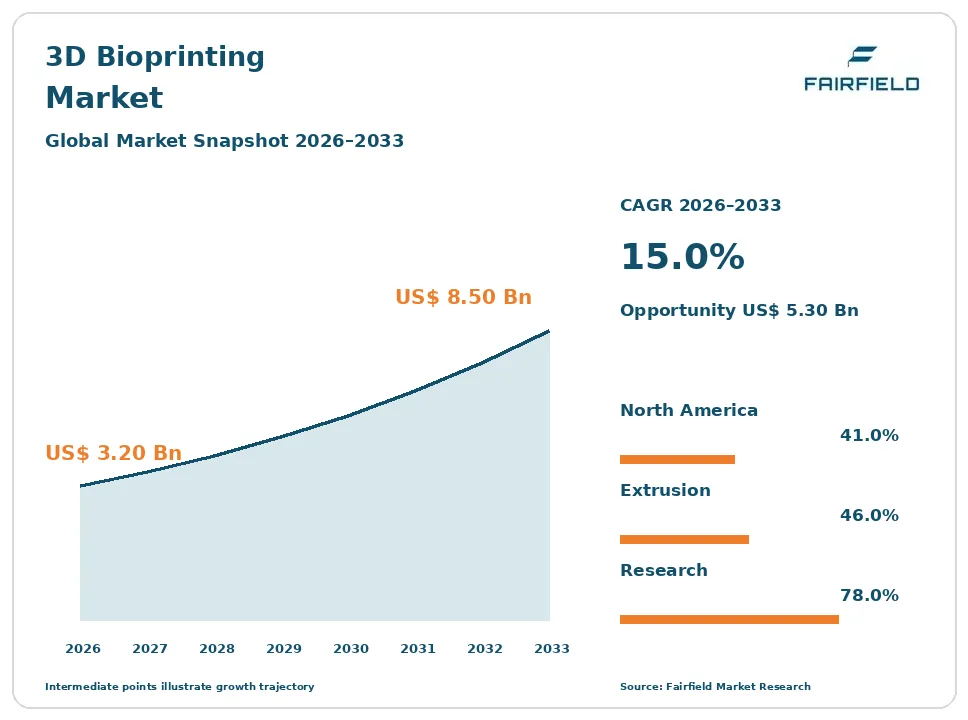
The global 3D bioprinting market size is expected to be valued at US$ 3.20 billion in 2026 and projected to reach US$ 8.50 billion by 2033, growing at a CAGR of 15.0% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 14.2%, as universities and drug companies bought bioprinters to build tissue models, venture funding flowed into tissue engineering startups, and regulators began encouraging alternatives to animal testing. 3D bioprinting uses printers to deposit living cells and bioinks layer by layer to create tissue-like structures. Three factors now drive growth: the use of bioprinted tissue models for drug screening and toxicity testing, the shortage of donor organs, and advances in tissue engineering, stem cells, and biomaterials. The market is shifting toward extrusion-based bioprinting systems with multiple print heads, light-based and volumetric printing for finer detail, vascularized bioprinted tissue, and partnerships with drugmakers. In February 2026, PrintBio joined a consortium led by the Wake Forest Institute for Regenerative Medicine under ARPA-H’s PRINT program, which provides up to US$ 24.8 million over five years to develop bioprinted kidney tissue.
Key Report Takeaways
- By Component: 3D Bioprinters held 44.0% share in 2026, while Bioinks are projected to expand at a 16.8% CAGR through 2033, driven by recurring purchases, new cell-friendly materials, and tissue-specific formulations.
- By Technology: Extrusion-Based Bioprinting held 46.0% share in 2026, while Light-Based Bioprinting is projected to expand at an 18.1% CAGR through 2033, driven by higher resolution, faster printing, and volumetric methods.
- By Application: Research held 78.0% share in 2026, while Clinical is projected to expand at a 17.6% CAGR through 2033, driven by early trials of bioprinted implants, skin, cartilage, and organ tissue.
- By Region: North America held 41.0% share in 2026, while Asia Pacific is projected to expand at a 17.4% CAGR through 2033, driven by research funding and biotech growth in China, Japan, South Korea, and India.
Global 3D Bioprinting Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Drug discovery and alternatives to animal testing | High | North America, Europe, Asia Pacific | Medium term (2-4 years) |
| Organ shortage and regenerative medicine research | High | Global | Long term (≥4 years) |
Two drivers carry the strongest influence on 3D bioprinting demand during the forecast period.
Drug Testing Needs Are Driving the 3D Bioprinting Market
Drug discovery needs and the push for alternatives to animal testing are the strongest driver of the 3D bioprinting market. Drugmakers want human-relevant models that predict results better.
The mechanism is the high cost of failed drugs. Most drug candidates fail in clinical trials, often because animal studies and flat cell cultures do not reflect human biology well. Bioprinted liver, kidney, skin, and tumor models let researchers test toxicity and effectiveness in three-dimensional human tissue. The FDA Modernization Act 2.0, passed in 2022, removed the US requirement for animal testing before human trials, and the U.S. Food and Drug Administration announced plans in 2025 to phase out some animal testing requirements in favor of human-based methods. Cosmetics makers, which face animal testing bans in many markets, use bioprinted skin models. These changes increase demand for bioprinters, bioinks, and contract tissue models.
Organ Shortage Is Expanding the 3D Bioprinting Market
The organ shortage and regenerative medicine research are expanding the 3D bioprinting market. Bioprinting may one day create replacement tissues and organs.
The cause is the large gap between organ supply and need. More than 100,000 people are on the US organ transplant waiting list, and many die before receiving an organ. Researchers are using bioprinting to build skin grafts, cartilage, bone, blood vessels, and kidney and liver tissue. Governments fund ambitious projects, such as ARPA-H’s PRINT program for kidney tissue. Aspect Biosystems raised US$ 115 million in Series B funding in January 2025 to advance bioprinted tissue therapeutics, including a partnership with Novo Nordisk on diabetes. Advances in stem cells allow printing with a patient’s own cells, reducing rejection risk. These efforts drive steady demand for advanced printers and materials.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Technical limits in vascularization and tissue function | High | Global | Long term (≥4 years) |
| High costs, regulatory uncertainty, and funding pressure | Medium | Global | Medium term (2-4 years) |
Two restraints limit how quickly the 3D bioprinting market grows.
Technical Limits Slow the 3D Bioprinting Market
Technical limits in vascularization and tissue function slow the 3D bioprinting market. Printing a working organ remains extremely difficult.
The specific causes are biological complexity. Thick tissues need networks of blood vessels to deliver oxygen and nutrients, and without them, cells in the center die. Printed tissues often lack the full structure and function of natural organs. Cells can be damaged by pressure, heat, or light during printing. Bioinks must be printable yet support cell growth, which is hard to balance. Tissues must mature for weeks after printing. Results can vary between labs, and standard protocols are lacking. These limits mean most bioprinting today is used in research rather than patient care. Clinical use of whole printed organs is still many years away, though simpler tissues are closer to patients.
High Costs and Funding Pressure Restrict the 3D Bioprinting Market
High costs, regulatory uncertainty, and funding pressure restrict the 3D bioprinting market. Many buyers and companies face tight budgets.
The underlying causes are expensive equipment and an uncertain path to revenue. Advanced bioprinters can cost hundreds of thousands of dollars, and cells, bioinks, and lab facilities add ongoing costs. Academic budgets and grant cycles limit purchases of high-end systems. Regulators have not yet created clear pathways for many bioprinted products, which makes clinical development risky. Venture funding for biotech tightened after 2021, and some companies have restructured. BICO, the parent of CELLINK, sold its MatTek and Visikol units to Sartorius for US$ 80 million in April 2025 to strengthen its balance sheet. Skilled staff are scarce. These factors slow adoption, and consolidation pressures remain across the sector.
Market Opportunities
Drug Screening Models and Services Open a Fast-Growth Revenue Pool
Bioprinted models for drug screening and related services open a fast-growth revenue pool in the 3D bioprinting market. Drugmakers prefer to buy ready-made tissues.
Companies that offer validated tissue models can capture this opportunity. Pharmaceutical companies want standardized liver, kidney, heart, lung, and tumor models that fit into automated testing workflows. Contract research services let drugmakers test compounds without buying printers. Regulatory moves to reduce animal testing increase demand for human-based data. Organ-on-chip devices combined with bioprinted tissue add more realistic conditions. Cosmetics and chemical companies need skin and eye models for safety testing. Vendors that prove their models predict human responses can win long-term contracts and charge premium prices. Automation of tissue production in well plates allows high-throughput testing at lower cost.
Clinical Tissue Products Create a Long-Term Revenue Pool
Clinical tissue products create a long-term revenue pool in the 3D bioprinting market. Simple tissues may reach patients first.
Bioprinting and regenerative medicine companies can capture this opportunity. Skin grafts for burns and chronic wounds, cartilage for ears and joints, bone grafts, and blood vessel patches are simpler than whole organs and are moving through early trials. CollPlant Biotechnologies uses plant-made human collagen in bioinks and breast implant research. Cyfuse Biomedical in Japan develops scaffold-free tissue printing for nerve and vascular repair. Aspect Biosystems is developing implantable bioprinted tissues for diabetes. Hospital-based printing of patient-specific tissues could follow. Companies that gain early approvals will shape the field. Regulators in the United States, Europe, and Japan are developing guidance for advanced manufactured tissues, which will help define the path to market.
Segment Analysis
By Component: 3D Bioprinters Lead While Bioinks Grow Fastest
3D Bioprinters held 44.0% share in 2026. Printers are the largest single upfront purchase for most labs, ranging from desktop systems for teaching to advanced multi-head platforms for research. CELLINK, 3D Systems, REGENHU, Advanced Solutions Life Sciences, and Nanoscribe are leading printer makers with large installed bases in universities.
Bioinks are the fastest-growing component, expanding at a 16.8% CAGR through 2033. Labs buy bioinks repeatedly, and demand is rising for hydrogels, extracellular matrix materials, collagen, gelatin, alginate, and synthetic polymers tailored to specific tissues. Software for design, simulation, and print control is a smaller but steadily growing component. For the market, bioink growth adds recurring revenue that balances one-time printer sales.
By Technology: Extrusion-Based Bioprinting Leads While Light-Based Bioprinting Grows Fastest
Extrusion-Based Bioprinting held 46.0% share in 2026. Extrusion-based bioprinting pushes bioinks through nozzles and is versatile, affordable, and compatible with many materials and cell densities, which makes it the most common method in labs worldwide.
Light-Based Bioprinting is the fastest-growing technology, expanding at an 18.1% CAGR through 2033. Stereolithography, digital light processing, and volumetric printing use light to cure bioinks with high resolution and speed, and companies such as Readily3D and Volumetric focus on these methods. Inkjet and laser-assisted printing serve fine-detail applications. For the market, light-based growth supports more complex tissues. Many labs now use hybrid systems that combine extrusion and light-based curing in a single printer to build tissues with several cell types.
By Application: Research Leads While Clinical Grows Fastest
Research held 78.0% share in 2026. Universities, research institutes, and drug companies use bioprinting for tissue engineering studies, disease models, and drug screening. Research use generates most printer and bioink sales.
Clinical is the fastest-growing application, expanding at a 17.6% CAGR through 2033. Early clinical studies of bioprinted skin, cartilage, and implants are underway, supported by government programs. By end user, academic and research institutes lead, followed by biopharmaceutical companies and hospitals. For the market, clinical growth signals the shift from research tools to therapies. Biopharmaceutical companies are the fastest-growing buyers as they adopt bioprinted models for drug screening and partner with tissue developers. Hospitals use bioprinting mainly in research programs linked to surgical departments.
Geography Analysis
Which Region Is Leading the 3D Bioprinting Market?
North America is leading the 3D bioprinting market with a 41.0% share in 2026. The United States has strong research funding from the National Institutes of Health and ARPA-H, many universities, and a large pharmaceutical industry. 3D Systems, Organovo, Advanced Solutions Life Sciences, and PrintBio are based in the country, and Aspect Biosystems is in Canada. Pharmaceutical companies in Boston and San Francisco are major buyers of tissue models. Key barriers include high costs and unclear clinical regulation. One change shaping the region is reduced animal testing, which increases demand for human tissue models.
Europe Builds the 3D Bioprinting Market Through Research Networks
Europe is a significant 3D bioprinting market. Germany, Switzerland, the United Kingdom, Sweden, and France have strong research and companies. CELLINK in Sweden, REGENHU in Switzerland, Nanoscribe in Germany, and Poietis in France are key players. The European Union funds tissue engineering research. The European ban on animal testing for cosmetics drives demand for bioprinted skin models, and research programs support alternative testing methods. Universities in the Netherlands, Spain, and Italy run active bioprinting labs. Key barriers include limited funding for commercialization. One opportunity is skin and eye models for cosmetic and chemical safety testing.
Which Region Is Growing Fastest in the 3D Bioprinting Market?
Asia Pacific is growing fastest in the 3D bioprinting market at a 17.4% CAGR through 2033. China invests heavily in bioprinting research and has local printer makers such as Revotek. Japan hosts Cyfuse Biomedical and supports regenerative medicine, while South Korea and India are growing quickly through university and startup activity. Australia and Singapore have strong university research and startups. Government programs in China fund regenerative medicine and tissue engineering at many hospitals. Key barriers include regulation and reliance on imported high-end printers. One change shaping the region is local suppliers offering lower-cost printers and bioinks to universities.
Latin America Grows the 3D Bioprinting Market Through University Research
Latin America is a growing 3D bioprinting market. Brazil, Mexico, Argentina, and Chile have universities and research institutes using bioprinters for tissue engineering research. Universities in Brazil have printed skin and cartilage models for research, and some hospitals are exploring bioprinted grafts for burn patients. Cosmetics companies in Brazil use alternative skin models because of local limits on animal testing. Research funding is limited and often depends on international collaboration with universities in Europe and North America. Key barriers include budgets, import costs, and few skilled staff. One opportunity is low-cost printers and open-source designs for teaching labs.
Middle East & Africa Expands the 3D Bioprinting Market Through Research Investment
Middle East & Africa is an emerging 3D bioprinting market. Israel hosts CollPlant Biotechnologies and Matricelf, and Saudi Arabia and the United Arab Emirates fund research in regenerative medicine and biotechnology. Universities in Israel are leaders in printing tissues from patient cells. Research hospitals in Saudi Arabia and the United Arab Emirates are building regenerative medicine programs as part of national health plans. Qatar and South Africa also have active university research groups in this field. Key barriers include limited expertise and small research budgets outside a few countries. One opportunity is research centers supported by government funding and international partnerships.
Competitive Landscape
The 3D bioprinting market is moderately concentrated. CELLINK, part of BICO, and 3D Systems lead in printers and materials, while Aspect Biosystems, Organovo, CollPlant Biotechnologies, and Cyfuse Biomedical focus on tissue therapeutics and models. REGENHU, Advanced Solutions Life Sciences, Nanoscribe, Poietis, UPM Biomedicals, and Brinter serve specific technologies and materials.
Companies compete on print resolution, speed, cell viability, material range, ease of use, price, and scientific support. Partnerships with drugmakers add credibility and revenue. Printer makers compete on technology range and service, while tissue developers compete on biology and clinical progress. Material suppliers such as UPM Biomedicals and CollPlant Biotechnologies offer specialized bioinks. Low-cost printer makers in China put pressure on prices in teaching and entry-level research markets.
Strategic moves show how competition is changing. In January 2025, Aspect Biosystems raised US$ 115 million. In April 2025, BICO agreed to sell MatTek and Visikol to Sartorius. In February 2026, PrintBio joined ARPA-H’s kidney bioprinting program. These moves show competition shifting toward therapeutics, government-funded organ programs, and tighter focus on profitable product lines, as investors look for clearer paths to revenue.
Three themes shape vendor strategy. First, companies are partnering with drugmakers on tissue models and therapies. Second, they are selling bioinks. Third, they are restructuring to focus on core businesses and conserve cash. Vendors that combine reliable printers, validated tissue models, and strong partnerships are best placed to win share.
3D Bioprinting Market Industry Leaders
- CELLINK
- 3D Systems
- Aspect Biosystems
- Organovo
- CollPlant Biotechnologies
Recent Industry Developments
- February 2026: PrintBio joined the Wake Forest Institute for Regenerative Medicine-led consortium under ARPA-H’s PRINT program, funded with up to US$ 24.8 million over five years - advances vascularized bioprinted tissue for kidneys.
- April 2025: BICO agreed to sell MatTek and Visikol to Sartorius for US$ 80 million, moving CELLINK into its Life Science Solutions unit - reshapes a leading bioprinting group.
- January 2025: Aspect Biosystems raised US$ 115 million in Series B financing - funds bioprinted tissue therapeutics.
Companies Covered in the Report
- CELLINK
- 3D Systems
- Aspect Biosystems
- Organovo
- CollPlant Biotechnologies
- Cyfuse Biomedical
- Advanced Solutions Life Sciences
- REGENHU
- Poietis
- Nanoscribe
- UPM Biomedicals
- Brinter
3D Bioprinting Market Report Scope
This report covers 3D bioprinting components, including 3D bioprinters, bioinks, and software, using inkjet, laser-assisted, extrusion-based, light-based, and other technologies, for research and clinical applications, by hospitals, academic and research institutes, biopharmaceutical companies, and others. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
3D Bioprinting Market Segmentation
| Component | 3D Bioprinters, Bioinks, Software |
| Technology | Inkjet Bioprinting, Laser-Assisted Bioprinting, Extrusion-Based Bioprinting, Light-Based Bioprinting, Others |
| Application | Research, Clinical |
| End User | Hospitals, Academic and Research Institutes, Biopharmaceutical Companies, Others |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
1. Executive Summary
1.1. Global 3D Bioprinting Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Drug Testing Needs Are Driving the 3D Bioprinting Market
2.3.1.2. Organ Shortage Is Expanding the 3D Bioprinting Market
2.3.2. Restraints
2.3.2.1. Technical Limits Slow the 3D Bioprinting Market
2.3.2.2. High Costs and Funding Pressure Restrict the 3D Bioprinting Market
2.3.3. Market Opportunities
2.3.3.1. Drug Screening Models and Services Open a Fast-Growth Revenue Pool
2.3.3.2. Clinical Tissue Products Create a Long-Term Revenue Pool
3. Global 3D Bioprinting Market Outlook, 2020-2033
3.1. Global 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
3.1.1. 3D Bioprinters
3.1.2. Bioinks
3.1.3. Software
3.2. Global 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
3.2.1. Inkjet Bioprinting
3.2.2. Laser-Assisted Bioprinting
3.2.3. Extrusion-Based Bioprinting
3.2.4. Light-Based Bioprinting
3.2.5. Others
3.3. Global 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
3.3.1. Research
3.3.2. Clinical
3.4. Global 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
3.4.1. Hospitals
3.4.2. Academic and Research Institutes
3.4.3. Biopharmaceutical Companies
3.4.4. Others
3.5. Global 3D Bioprinting Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.5.1. North America
3.5.2. Europe
3.5.3. Asia Pacific
3.5.4. Latin America
3.5.5. Middle East & Africa
4. North America 3D Bioprinting Market Outlook, 2020-2033
4.1. North America 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
4.1.1. 3D Bioprinters
4.1.2. Bioinks
4.1.3. Software
4.2. North America 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
4.2.1. Inkjet Bioprinting
4.2.2. Laser-Assisted Bioprinting
4.2.3. Extrusion-Based Bioprinting
4.2.4. Light-Based Bioprinting
4.2.5. Others
4.3. North America 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
4.3.1. Research
4.3.2. Clinical
4.4. North America 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
4.4.1. Hospitals
4.4.2. Academic and Research Institutes
4.4.3. Biopharmaceutical Companies
4.4.4. Others
4.5. North America 3D Bioprinting Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.5.1. United States 3D Bioprinting Market Outlook, by Component, 2020-2033
4.5.2. United States 3D Bioprinting Market Outlook, by Technology, 2020-2033
4.5.3. United States 3D Bioprinting Market Outlook, by Application, 2020-2033
4.5.4. United States 3D Bioprinting Market Outlook, by End User, 2020-2033
4.5.5. Canada 3D Bioprinting Market Outlook, by Component, 2020-2033
4.5.6. Canada 3D Bioprinting Market Outlook, by Technology, 2020-2033
4.5.7. Canada 3D Bioprinting Market Outlook, by Application, 2020-2033
4.5.8. Canada 3D Bioprinting Market Outlook, by End User, 2020-2033
5. Europe 3D Bioprinting Market Outlook, 2020-2033
5.1. Europe 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
5.1.1. 3D Bioprinters
5.1.2. Bioinks
5.1.3. Software
5.2. Europe 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
5.2.1. Inkjet Bioprinting
5.2.2. Laser-Assisted Bioprinting
5.2.3. Extrusion-Based Bioprinting
5.2.4. Light-Based Bioprinting
5.2.5. Others
5.3. Europe 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
5.3.1. Research
5.3.2. Clinical
5.4. Europe 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
5.4.1. Hospitals
5.4.2. Academic and Research Institutes
5.4.3. Biopharmaceutical Companies
5.4.4. Others
5.5. Europe 3D Bioprinting Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.5.1. Germany 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.2. Germany 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.3. Germany 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.4. Germany 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.5. Switzerland 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.6. Switzerland 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.7. Switzerland 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.8. Switzerland 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.9. United Kingdom 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.10. United Kingdom 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.11. United Kingdom 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.12. United Kingdom 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.13. Sweden 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.14. Sweden 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.15. Sweden 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.16. Sweden 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.17. France 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.18. France 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.19. France 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.20. France 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.21. Netherlands 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.22. Netherlands 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.23. Netherlands 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.24. Netherlands 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.25. Spain 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.26. Spain 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.27. Spain 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.28. Spain 3D Bioprinting Market Outlook, by End User, 2020-2033
5.5.29. Italy 3D Bioprinting Market Outlook, by Component, 2020-2033
5.5.30. Italy 3D Bioprinting Market Outlook, by Technology, 2020-2033
5.5.31. Italy 3D Bioprinting Market Outlook, by Application, 2020-2033
5.5.32. Italy 3D Bioprinting Market Outlook, by End User, 2020-2033
6. Asia Pacific 3D Bioprinting Market Outlook, 2020-2033
6.1. Asia Pacific 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
6.1.1. 3D Bioprinters
6.1.2. Bioinks
6.1.3. Software
6.2. Asia Pacific 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
6.2.1. Inkjet Bioprinting
6.2.2. Laser-Assisted Bioprinting
6.2.3. Extrusion-Based Bioprinting
6.2.4. Light-Based Bioprinting
6.2.5. Others
6.3. Asia Pacific 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
6.3.1. Research
6.3.2. Clinical
6.4. Asia Pacific 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
6.4.1. Hospitals
6.4.2. Academic and Research Institutes
6.4.3. Biopharmaceutical Companies
6.4.4. Others
6.5. Asia Pacific 3D Bioprinting Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.5.1. China 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.2. China 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.3. China 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.4. China 3D Bioprinting Market Outlook, by End User, 2020-2033
6.5.5. Japan 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.6. Japan 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.7. Japan 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.8. Japan 3D Bioprinting Market Outlook, by End User, 2020-2033
6.5.9. South Korea 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.10. South Korea 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.11. South Korea 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.12. South Korea 3D Bioprinting Market Outlook, by End User, 2020-2033
6.5.13. India 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.14. India 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.15. India 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.16. India 3D Bioprinting Market Outlook, by End User, 2020-2033
6.5.17. Australia 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.18. Australia 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.19. Australia 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.20. Australia 3D Bioprinting Market Outlook, by End User, 2020-2033
6.5.21. Singapore 3D Bioprinting Market Outlook, by Component, 2020-2033
6.5.22. Singapore 3D Bioprinting Market Outlook, by Technology, 2020-2033
6.5.23. Singapore 3D Bioprinting Market Outlook, by Application, 2020-2033
6.5.24. Singapore 3D Bioprinting Market Outlook, by End User, 2020-2033
7. Latin America 3D Bioprinting Market Outlook, 2020-2033
7.1. Latin America 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
7.1.1. 3D Bioprinters
7.1.2. Bioinks
7.1.3. Software
7.2. Latin America 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
7.2.1. Inkjet Bioprinting
7.2.2. Laser-Assisted Bioprinting
7.2.3. Extrusion-Based Bioprinting
7.2.4. Light-Based Bioprinting
7.2.5. Others
7.3. Latin America 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
7.3.1. Research
7.3.2. Clinical
7.4. Latin America 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
7.4.1. Hospitals
7.4.2. Academic and Research Institutes
7.4.3. Biopharmaceutical Companies
7.4.4. Others
7.5. Latin America 3D Bioprinting Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.5.1. Brazil 3D Bioprinting Market Outlook, by Component, 2020-2033
7.5.2. Brazil 3D Bioprinting Market Outlook, by Technology, 2020-2033
7.5.3. Brazil 3D Bioprinting Market Outlook, by Application, 2020-2033
7.5.4. Brazil 3D Bioprinting Market Outlook, by End User, 2020-2033
7.5.5. Mexico 3D Bioprinting Market Outlook, by Component, 2020-2033
7.5.6. Mexico 3D Bioprinting Market Outlook, by Technology, 2020-2033
7.5.7. Mexico 3D Bioprinting Market Outlook, by Application, 2020-2033
7.5.8. Mexico 3D Bioprinting Market Outlook, by End User, 2020-2033
7.5.9. Argentina 3D Bioprinting Market Outlook, by Component, 2020-2033
7.5.10. Argentina 3D Bioprinting Market Outlook, by Technology, 2020-2033
7.5.11. Argentina 3D Bioprinting Market Outlook, by Application, 2020-2033
7.5.12. Argentina 3D Bioprinting Market Outlook, by End User, 2020-2033
7.5.13. Chile 3D Bioprinting Market Outlook, by Component, 2020-2033
7.5.14. Chile 3D Bioprinting Market Outlook, by Technology, 2020-2033
7.5.15. Chile 3D Bioprinting Market Outlook, by Application, 2020-2033
7.5.16. Chile 3D Bioprinting Market Outlook, by End User, 2020-2033
8. Middle East & Africa 3D Bioprinting Market Outlook, 2020-2033
8.1. Middle East & Africa 3D Bioprinting Market Outlook, by Component, Value (US$ Billion), 2020-2033
8.1.1. 3D Bioprinters
8.1.2. Bioinks
8.1.3. Software
8.2. Middle East & Africa 3D Bioprinting Market Outlook, by Technology, Value (US$ Billion), 2020-2033
8.2.1. Inkjet Bioprinting
8.2.2. Laser-Assisted Bioprinting
8.2.3. Extrusion-Based Bioprinting
8.2.4. Light-Based Bioprinting
8.2.5. Others
8.3. Middle East & Africa 3D Bioprinting Market Outlook, by Application, Value (US$ Billion), 2020-2033
8.3.1. Research
8.3.2. Clinical
8.4. Middle East & Africa 3D Bioprinting Market Outlook, by End User, Value (US$ Billion), 2020-2033
8.4.1. Hospitals
8.4.2. Academic and Research Institutes
8.4.3. Biopharmaceutical Companies
8.4.4. Others
8.5. Middle East & Africa 3D Bioprinting Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.5.1. Israel 3D Bioprinting Market Outlook, by Component, 2020-2033
8.5.2. Israel 3D Bioprinting Market Outlook, by Technology, 2020-2033
8.5.3. Israel 3D Bioprinting Market Outlook, by Application, 2020-2033
8.5.4. Israel 3D Bioprinting Market Outlook, by End User, 2020-2033
8.5.5. Saudi Arabia 3D Bioprinting Market Outlook, by Component, 2020-2033
8.5.6. Saudi Arabia 3D Bioprinting Market Outlook, by Technology, 2020-2033
8.5.7. Saudi Arabia 3D Bioprinting Market Outlook, by Application, 2020-2033
8.5.8. Saudi Arabia 3D Bioprinting Market Outlook, by End User, 2020-2033
8.5.9. United Arab Emirates 3D Bioprinting Market Outlook, by Component, 2020-2033
8.5.10. United Arab Emirates 3D Bioprinting Market Outlook, by Technology, 2020-2033
8.5.11. United Arab Emirates 3D Bioprinting Market Outlook, by Application, 2020-2033
8.5.12. United Arab Emirates 3D Bioprinting Market Outlook, by End User, 2020-2033
8.5.13. Qatar 3D Bioprinting Market Outlook, by Component, 2020-2033
8.5.14. Qatar 3D Bioprinting Market Outlook, by Technology, 2020-2033
8.5.15. Qatar 3D Bioprinting Market Outlook, by Application, 2020-2033
8.5.16. Qatar 3D Bioprinting Market Outlook, by End User, 2020-2033
8.5.17. South Africa 3D Bioprinting Market Outlook, by Component, 2020-2033
8.5.18. South Africa 3D Bioprinting Market Outlook, by Technology, 2020-2033
8.5.19. South Africa 3D Bioprinting Market Outlook, by Application, 2020-2033
8.5.20. South Africa 3D Bioprinting Market Outlook, by End User, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. CELLINK
9.5.2. 3D Systems
9.5.3. Aspect Biosystems
9.5.4. Organovo
9.5.5. CollPlant Biotechnologies
9.5.6. Cyfuse Biomedical
9.5.7. Advanced Solutions Life Sciences
9.5.8. REGENHU
9.5.9. Poietis
9.5.10. Nanoscribe
9.5.11. UPM Biomedicals
9.5.12. Brinter
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Component | 3D Bioprinters, Bioinks, Software |
| Technology | Inkjet Bioprinting, Laser-Assisted Bioprinting, Extrusion-Based Bioprinting, Light-Based Bioprinting, Others |
| Application | Research, Clinical |
| End User | Hospitals, Academic and Research Institutes, Biopharmaceutical Companies, Others |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The 3D bioprinting market is valued at US$ 3.20 billion in 2026, led by bioprinters and North America, its largest market.
The market is projected to reach US$ 8.50 billion by 2033, growing at a 15.0% CAGR and adding US$ 5.30 billion.
Light-based bioprinting is growing fastest at an 18.1% CAGR through 2033, driven by higher resolution and volumetric methods.
Asia Pacific is growing fastest at a 17.4% CAGR through 2033, driven by research funding and biotech growth in China and Japan.
North America holds the largest share at 41.0% in 2026, supported by strong research funding and a large pharmaceutical industry.
Related Reports
Absorbable Tissue Spacer Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the absorbable tissue spacer market outlook for 2026–2033, with product trends, regional insights, growth drivers, and competitive analysis.
Glucose Tolerance Test Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global glucose tolerance test market is valued at US$1.97 billion in 2026, reaching US$2.98 billion by 2033, growing at a 6.1% CAGR
Medical Fiber Optics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The medical fiber optics market is projected to grow from US$1.4 billion in 2026 to US$1.9 billion by 2033 at a 4.5% CAGR.
Laser Hair Removal Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The laser hair removal market is projected to reach US$4.5 billion by 2033. Explore diode and multi-wavelength devices, clinic demand, and regional growth.
Joint Reconstruction Devices Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The joint reconstruction devices market is projected to reach US$35.2 billion by 2033. Explore knee and hip implants, revision procedures, and surgical robotics.
Interventional Cardiology Devices Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global interventional cardiology devices market is valued at US$18.0 billion in 2026, reaching US$26.4 billion by 2033, growing at a 5.62% CAGR