


Antimicrobial Susceptibility Testing Market
Antimicrobial Susceptibility Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Antimicrobial Susceptibility Testing Market Size and Trend Analysis
How Fast Is the Antimicrobial Susceptibility Testing Market Growing?
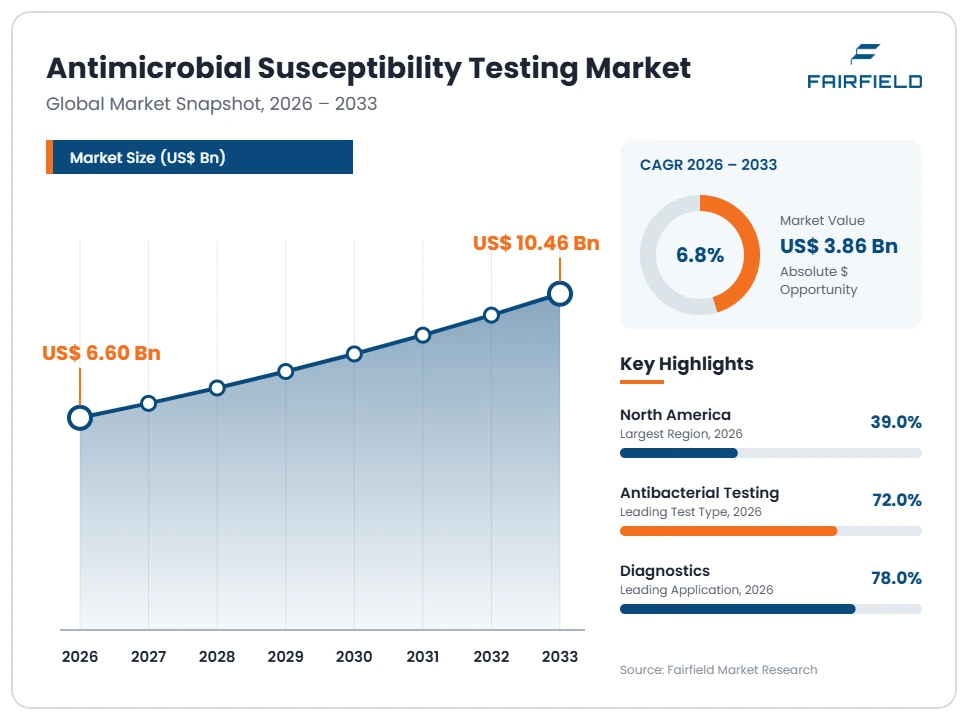
The global antimicrobial susceptibility testing market size is expected to be valued at US$ 6.60 billion in 2026 and projected to reach US$ 10.46 billion by 2033, growing at a CAGR of 6.8% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 6.2%, as hospitals faced more drug-resistant infections and labs invested in faster, automated testing. Antimicrobial susceptibility testing (AST) shows which antibiotics or antifungals will work against a patient’s infection, often by measuring the minimum inhibitory concentration of each drug. Three factors now drive growth: the global rise of antimicrobial resistance, the need for faster results in life-threatening conditions such as sepsis, and government programs that promote antibiotic stewardship. The market is shifting toward rapid AST systems that deliver results within hours, automated microbiology platforms that combine identification and susceptibility testing, and software that applies the latest testing standards automatically. New clearances in 2024 and 2025, including bioMérieux’s VITEK REVEAL and BD’s Phoenix M50 software, show strong competition on speed.
Key Report Takeaways
- By Test Type: Antibacterial Testing held 72.0% share in 2026, while Antifungal Testing is projected to expand at an 8.1% CAGR through 2033, driven by rising Candida auris and other resistant fungal infections in hospitals.
- By Application: Diagnostics held 78.0% share in 2026, while Drug Discovery and Development is projected to expand at an 8.0% CAGR through 2033, driven by new antibiotic and antifungal research programs.
- By End User: Hospitals and Clinics held 41.0% share in 2026, while Clinical Laboratories are projected to expand at a 7.6% CAGR through 2033, driven by centralized testing and lab consolidation.
- By Region: North America held 39.0% share in 2026, while Asia Pacific is projected to expand at an 8.6% CAGR through 2033, driven by high resistance rates and lab upgrades in India and China.
Global Antimicrobial Susceptibility Testing Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on antimicrobial susceptibility testing demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising antimicrobial resistance | High | Global | Long term (≥4 years) |
| Need for rapid results in sepsis and critical care | High | North America, Europe, Asia Pacific | Medium term (2–4 years) |
Antimicrobial Resistance Is Driving the Antimicrobial Susceptibility Testing Market
The global rise of antimicrobial resistance is the strongest driver of the antimicrobial susceptibility testing market. Bacteria and fungi are becoming harder to treat with common drugs.
The mechanism is the need to match each infection with an effective drug. Overuse of antibiotics in people and animals has created resistant germs such as MRSA, carbapenem-resistant Enterobacterales, and drug-resistant tuberculosis. Resistant infections are linked to more than one million deaths each year worldwide. Doctors can no longer safely guess which antibiotic will work, so labs must test each sample. Guidelines from the Infectious Diseases Society of America and national health agencies call for testing to support antibiotic stewardship. The World Health Organization and governments fund surveillance programs that track resistance using AST data. These factors steadily raise test volumes in hospitals and labs.
Rapid Testing Needs Are Expanding the Antimicrobial Susceptibility Testing Market
The need for faster results in sepsis and critical care is expanding the antimicrobial susceptibility testing market. Every hour of delay in effective treatment raises the risk of death.
The cause is the slow speed of traditional methods. Culture-based tests can take two to three days, during which patients receive broad-spectrum antibiotics that may not work and that drive more resistance. Rapid AST systems can deliver results in hours directly from positive blood cultures. bioMérieux’s VITEK REVEAL Gram-negative assay, cleared by the U.S. Food and Drug Administration in 2024, gives results in about 6 hours. Automated microbiology platforms also cut hands-on work as labs face staff shortages. Faster results shorten hospital stays, improve survival, and lower costs. These trends push hospitals to upgrade equipment.
Restraints Impact Analysis
Two restraints limit how quickly the antimicrobial susceptibility testing market grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| High cost of automated and rapid systems | High | Global | Short term (≤2 years) |
| Regulatory hurdles and changing breakpoints | Medium | North America, Europe | Medium term (2–4 years) |
High Costs Slow the Antimicrobial Susceptibility Testing Market
The high cost of automated and rapid systems slows the antimicrobial susceptibility testing market. Advanced instruments are expensive to buy and run.
The specific causes are equipment prices, test costs, and staffing. Automated AST systems and rapid platforms can cost hundreds of thousands of dollars, and each rapid test costs more than manual methods. Small hospitals and labs in developing countries often rely on cheaper disk diffusion and manual methods that take longer. Reimbursement for rapid tests may not cover their full cost. Labs also need trained microbiologists, who are in short supply. Some rapid systems test only certain bacteria or drugs, limiting their use in routine work. Accelerate Diagnostics, a rapid AST pioneer, faced financial difficulties. These factors slow adoption of advanced technology.
Regulatory Hurdles Restrict the Antimicrobial Susceptibility Testing Market
Regulatory hurdles and changing breakpoints restrict the antimicrobial susceptibility testing market. Tests must be updated as standards change.
The underlying causes are complex rules and evolving science. Breakpoints, the cut-off values that decide whether a germ is susceptible or resistant, are updated regularly by the Clinical and Laboratory Standards Institute and EUCAST. Manufacturers must update and get clearance for their tests, which takes time and money. Different regions use different standards, complicating global product development. New antibiotics often lack available commercial tests at launch, delaying their use. The U.S. Food and Drug Administration’s rules on lab-developed tests have added uncertainty. Labs must also validate each update before using it, adding work for already busy staff. These factors slow product launches and adoption of new tests.
Market Opportunities
Direct-from-Sample Rapid AST Opens a High-Value Revenue Pool
Direct-from-sample rapid AST opens a high-value revenue pool in the antimicrobial susceptibility testing market. Hospitals want answers without waiting for cultures to grow.
Companies developing new technologies can capture this opportunity. Methods using microfluidics, imaging, molecular signatures, and AI can detect resistance directly from blood or urine. These tests could guide treatment on the first day of infection. Hospitals with sepsis programs and intensive care units are the main buyers. Governments and groups such as BARDA and CARB-X fund development. High prices and recurring test sales support strong revenue. Partnerships with large diagnostics firms speed market access. Hospitals that can show shorter stays and lower antibiotic use make strong reference customers. Reimbursement codes for rapid tests would further support adoption.
Emerging Market Lab Expansion Creates a Volume Revenue Pool
Lab expansion in emerging markets creates a volume revenue pool in the antimicrobial susceptibility testing market. Many countries are building microbiology capacity.
Suppliers of affordable manual and automated systems can capture this opportunity. India, China, Indonesia, Brazil, Nigeria, and Egypt have high rates of resistant infections but limited testing. National action plans on antimicrobial resistance fund lab equipment and surveillance. The World Health Organization’s GLASS program supports data sharing. Low-cost disk diffusion and gradient strips serve smaller labs, while large hospitals buy automated systems. Training programs build long-term demand. Global health funders, such as the Fleming Fund, support lab equipment in low-income countries. Local manufacturing of disks and media in India and China lowers costs for regional buyers.
Segment Analysis
- By Test Type: Antibacterial Testing Leads While Antifungal Testing Grows Fastest
Antibacterial Testing held 72.0% share in 2026. Bacterial infections such as pneumonia, urinary tract infections, bloodstream infections, and wound infections are the most common reasons for AST. Most automated systems, panels, and disks focus on bacteria, and new antibiotics require updated panels. bioMérieux, BD, Thermo Fisher Scientific, and Beckman Coulter offer broad antibacterial panels.
Antifungal Testing is clearly the fastest-growing test type, expanding at an 8.1% CAGR through 2033. Resistant fungi such as Candida auris and Aspergillus are spreading in hospitals worldwide, and patients with weak immune systems are at high risk. New antifungal drugs need matching tests. Liofilchem and Thermo Fisher Scientific offer antifungal products. For the market, antifungal growth widens test menus.
- By Application: Diagnostics Leads While Drug Discovery and Development Grows Fastest
Diagnostics held 78.0% share in 2026. Hospitals and labs use AST to guide treatment for individual patients and to track resistance trends. Clinical testing drives most instrument and consumable sales. Surveillance programs also use AST data to track how resistance spreads between hospitals and countries. Veterinary and food safety labs add smaller volumes. Most testing uses the minimum inhibitory concentration or zone size to classify results.
Drug Discovery and Development is the fastest-growing application, expanding at an 8.0% CAGR through 2033. Pharmaceutical and biotech companies use AST to test new antibiotics and antifungals and to support regulatory submissions. Government incentives for new antibiotics, such as pull incentives in the United Kingdom, support research and new testing needs. Contract research organizations provide AST services for drug developers. Regulators require susceptibility data for new antibiotic approvals. For the market, drug discovery growth adds specialized demand.
- By End User: Hospitals and Clinics Lead While Clinical Laboratories Grow Fastest
Hospitals and Clinics held 41.0% share in 2026. Hospital labs run AST for inpatients, emergency patients, and intensive care units, where fast results matter most. Large hospitals invest in automated systems, while smaller clinics often send samples to outside labs. Hospital stewardship teams use results to reduce unnecessary antibiotic use.
Clinical Laboratories are the fastest-growing end user, expanding at a 7.6% CAGR through 2033. Independent and reference labs, such as Quest Diagnostics and Labcorp, handle growing volumes as hospitals outsource testing. Pharmaceutical and biotech companies are other key users. Consolidated labs process thousands of samples daily, which favors high-throughput automated platforms. For the market, lab growth supports high-throughput systems.
Geography Analysis
- Which Region Is Leading the Antimicrobial Susceptibility Testing Market?
North America is leading the antimicrobial susceptibility testing market with a 39.0% share in 2026. The United States has advanced hospital labs, high awareness of antimicrobial resistance, and strong funding from the Centers for Disease Control and Prevention and BARDA. BD, Thermo Fisher Scientific, Beckman Coulter, and Accelerate Diagnostics are based here. Canada has national stewardship programs and surveillance networks. Hospital stewardship requirements from the Centers for Medicare & Medicaid Services support routine testing. Lab staff shortages push hospitals toward automation. Key barriers include costs. One change shaping the region is rapid AST adoption.
- Europe Builds the Antimicrobial Susceptibility Testing Market Through Stewardship Programs
Europe is a major antimicrobial susceptibility testing market. France hosts bioMérieux, Germany hosts Bruker, and Italy hosts Liofilchem. EUCAST sets breakpoints used across the region and in many other countries. The United Kingdom, Spain, the Netherlands, and Sweden have strong surveillance programs and low antibiotic use. The EU One Health Action Plan against resistance supports testing in people and animals. Germany and France have large hospital lab networks with high automation and strong infection control teams. Key barriers include budget limits in public health systems. One opportunity is rapid testing in intensive care units.
- Which Region Is Growing Fastest in the Antimicrobial Susceptibility Testing Market?
Asia Pacific is growing fastest in the antimicrobial susceptibility testing market at an 8.6% CAGR through 2033. India and China have some of the highest resistance rates in the world, and both are expanding hospital labs under national action plans. Japan, South Korea, and Australia have advanced labs with high automation. Indonesia, Thailand, and Vietnam are upgrading testing in public hospitals. Private hospital chains in India are investing in rapid testing, and China is expanding lab capacity in smaller cities. Key barriers include cost and limited trained staff. One change shaping the region is automation.
- Latin America Grows the Antimicrobial Susceptibility Testing Market Through Lab Upgrades
Latin America is a growing antimicrobial susceptibility testing market. Brazil and Mexico have high rates of resistant infections in hospitals and are investing in lab automation and staff training. Argentina, Colombia, Peru, and Chile run hospital surveillance networks that share resistance data across the region. Public hospitals in Brazil use national surveillance data to guide antibiotic policies, and private labs in Mexico and Colombia are buying automated systems. Training programs supported by the Pan American Health Organization improve testing quality. Key barriers include limited public budgets and currency swings. One opportunity is affordable automated systems for mid-sized hospitals.
- Middle East & Africa Expands the Antimicrobial Susceptibility Testing Market Through Surveillance
Middle East & Africa is an emerging antimicrobial susceptibility testing market. Saudi Arabia and the United Arab Emirates are building advanced hospital labs as part of health reforms. South Africa, Nigeria, Kenya, and Egypt face high resistance rates with limited testing capacity. Many labs in Middle East & Africa still rely on manual disk diffusion. Hospitals in Qatar and Kuwait run stewardship programs with modern, automated labs. International donors fund microbiology training in Kenya, Ghana, and Nigeria. Key barriers include limited funding and staff shortages. One opportunity is WHO-supported surveillance and lab-strengthening programs.
Competitive Landscape
The antimicrobial susceptibility testing market is moderately concentrated. bioMérieux, Becton, Dickinson and Company, Thermo Fisher Scientific, Danaher through Beckman Coulter, and Bruker lead in automated systems and consumables. Roche, Siemens Healthineers, Liofilchem, Hardy Diagnostics, Mast Group, ELITechGroup, and Accelerate Diagnostics serve specialized needs.
Companies compete on speed, accuracy, test menu breadth, automation, software, service quality, and cost per test. Large, established firms benefit from installed instruments that drive recurring consumable sales, since labs rarely switch platforms once staff are trained. Smaller firms compete with low-cost disks, gradient strips, and culture media, or with new rapid technologies. Startups developing direct-from-sample tests often partner with established companies to reach hospitals and secure distribution. Software that applies expert rules and updated breakpoints automatically has become a key selling point for busy labs, and connectivity with lab information systems is now standard.
Strategic moves show how competition is changing in this market. In September 2024, bioMérieux received FDA clearance for its VITEK REVEAL Gram-negative AST assay. In March 2025, it received clearance for VITEK COMPACT PRO. In April 2025, BD received clearance for its Phoenix M50 system with BDXpert software. These moves show competition shifting toward speed, automation, and smaller labs.
Three themes shape vendor strategy. First, companies are launching rapid tests that cut time to result. Second, they are adding expert software that applies new breakpoints. Third, they are serving smaller labs with compact automated systems.
Recent Industry Developments
- April 2025: BD received FDA 510(k) clearance for its Phoenix M50 automated microbiology system with BDXpert software for ID and AST interpretation – supports automated microbiology and resistance detection.
- March 2025: bioMérieux received FDA 510(k) clearance for VITEK COMPACT PRO, an ID and AST system for small and medium labs – widens access to automated testing.
- September 2024: bioMérieux received FDA clearance for the VITEK REVEAL GN AST assay, delivering results in about 6 hours from positive blood cultures – advances rapid AST for sepsis.
Companies Covered in the Report
- bioMérieux
- Becton, Dickinson and Company
- Thermo Fisher Scientific
- Danaher
- Bruker
- Roche
- Siemens Healthineers
- Liofilchem
- Hardy Diagnostics
- Accelerate Diagnostics
- Mast Group
- ELITechGroup
Antimicrobial Susceptibility Testing Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 6.60 Billion |
| Market Size 2033 | US$ 10.46 Billion |
| CAGR 2026–2033 | 6.8% |
| Absolute Dollar Opportunity | US$ 3.86 Billion |
| Largest Market | North America |
| Fastest-Growing Market | Asia Pacific |
| Market Concentration | Moderate |
| Major Players | bioMérieux, Becton, Dickinson and Company, Thermo Fisher Scientific, Danaher, Bruker |
Antimicrobial Susceptibility Testing Market Segmentation
Test Type
- Antibacterial Testing
- Antifungal Testing
- Others
Method
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
Application
- Diagnostics
- Drug Discovery and Development
- Others
End User
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Antimicrobial Susceptibility Testing Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Antimicrobial Resistance Is Driving the Antimicrobial Susceptibility Testing Market
- Rapid Testing Needs Are Expanding the Antimicrobial Susceptibility Testing Market
- Restraints
- High Costs Slow the Antimicrobial Susceptibility Testing Market
- Regulatory Hurdles Restrict the Antimicrobial Susceptibility Testing Market
- Market Opportunities
- Direct-from-Sample Rapid AST Opens a High-Value Revenue Pool
- Emerging Market Lab Expansion Creates a Volume Revenue Pool
- Drivers
- Global Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- Global Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- Global Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- Global Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- Global Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- Global Antimicrobial Susceptibility Testing Market Outlook, by Region, Value (US$ Billion), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- North America Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- North America Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- North America Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- North America Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- North America Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- North America Antimicrobial Susceptibility Testing Market Outlook, by Country, Value (US$ Billion), 2020-2033
- United States Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- United States Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- United States Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- United States Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Canada Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Canada Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Canada Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Canada Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- North America Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Europe Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- Europe Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- Europe Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- Europe Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- Europe Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- Europe Antimicrobial Susceptibility Testing Market Outlook, by Country, Value (US$ Billion), 2020-2033
- France Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- France Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- France Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- France Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Germany Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Germany Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Germany Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Germany Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Italy Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Italy Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Italy Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Italy Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- United Kingdom Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- United Kingdom Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- United Kingdom Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- United Kingdom Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Spain Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Spain Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Spain Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Spain Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Netherlands Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Netherlands Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Netherlands Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Netherlands Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Sweden Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Sweden Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Sweden Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Sweden Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Europe Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by Country, Value (US$ Billion), 2020-2033
- India Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- India Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- India Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- India Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- China Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- China Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- China Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- China Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Japan Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Japan Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Japan Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Japan Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- South Korea Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- South Korea Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- South Korea Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- South Korea Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Australia Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Australia Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Australia Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Australia Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Indonesia Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Indonesia Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Indonesia Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Indonesia Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Thailand Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Thailand Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Thailand Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Thailand Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Vietnam Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Vietnam Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Vietnam Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Vietnam Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Asia Pacific Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Latin America Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Brazil Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Brazil Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Brazil Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Brazil Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Mexico Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Mexico Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Mexico Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Mexico Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Argentina Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Argentina Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Argentina Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Argentina Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Colombia Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Colombia Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Colombia Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Colombia Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Peru Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Peru Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Peru Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Peru Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Chile Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Chile Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Chile Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Chile Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Latin America Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, 2020-2033
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Antibacterial Testing
- Antifungal Testing
- Others
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by Method, Value (US$ Billion), 2020-2033
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by Application, Value (US$ Billion), 2020-2033
- Diagnostics
- Drug Discovery and Development
- Others
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by End User, Value (US$ Billion), 2020-2033
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Saudi Arabia Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Saudi Arabia Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Saudi Arabia Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Saudi Arabia Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- United Arab Emirates Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- United Arab Emirates Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- United Arab Emirates Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- United Arab Emirates Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- South Africa Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- South Africa Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- South Africa Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- South Africa Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Nigeria Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Nigeria Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Nigeria Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Nigeria Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Kenya Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Kenya Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Kenya Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Kenya Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Egypt Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Egypt Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Egypt Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Egypt Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Qatar Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Qatar Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Qatar Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Qatar Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Kuwait Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Kuwait Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Kuwait Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Kuwait Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Ghana Antimicrobial Susceptibility Testing Market Outlook, by Test Type, 2020-2033
- Ghana Antimicrobial Susceptibility Testing Market Outlook, by Method, 2020-2033
- Ghana Antimicrobial Susceptibility Testing Market Outlook, by Application, 2020-2033
- Ghana Antimicrobial Susceptibility Testing Market Outlook, by End User, 2020-2033
- Middle East & Africa Antimicrobial Susceptibility Testing Market Outlook, by Test Type, Value (US$ Billion), 2020-2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- bioMérieux
- Becton, Dickinson and Company
- Thermo Fisher Scientific
- Danaher
- Bruker
- Roche
- Siemens Healthineers
- Liofilchem
- Hardy Diagnostics
- Accelerate Diagnostics
- Mast Group
- ELITechGroup
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Test Type
- Antibacterial Testing
- Antifungal Testing
- Others
Method
- E-Test
- Disk Diffusion
- Rapid Automation Method
- Others
Application
- Diagnostics
- Drug Discovery and Development
- Others
End User
- Hospitals and Clinics
- Clinical Laboratories
- Pharmaceutical and Biotechnology Companies
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The antimicrobial susceptibility testing market is valued at US$ 6.60 billion in 2026, led by antibacterial testing and North America.
The market is projected to reach US$ 10.46 billion by 2033, growing at a 6.8% CAGR and adding US$ 3.86 billion.
Antifungal testing is growing fastest at an 8.1% CAGR through 2033, driven by resistant fungal infections such as Candida auris.
Asia Pacific is growing fastest at an 8.6% CAGR through 2033, driven by high resistance rates and lab upgrades in India and China.
North America holds the largest share at 39.0% in 2026, supported by advanced hospital labs and strong federal resistance programs.
Related Reports
Hemoglobin A1c Testing Devices Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global hemoglobin A1c testing devices market is valued at US$1.6 billion in 2026, reaching US$2.3 billion by 2033, growing at a 5.32% CAGR
Wireless Neurostimulators Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Wireless neurostimulators market to grow from US$ 6.2 billion in 2026 to US$ 11.5 billion by 2033 at a 9.2% CAGR. Explore products, applications and regions.
Ultrasound Needle Guides Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the ultrasound needle guides market, projected to reach US$0.7 billion by 2033 at 8.3% CAGR, with product, application and regional insights.
Oncology Molecular Diagnostic Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The oncology molecular diagnostic market is projected to grow from US$12.4 billion in 2026 to US$24.6 billion by 2033, at a 10.3% CAGR. Explore trends.
Mechanical Ventilators Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global mechanical ventilators market is valued at US$4.80 billion in 2026, reaching US$6.58 billion by 2033, growing at a 4.6% CAGR
Drugs of Abuse Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global drugs of abuse testing market is valued at US$6.80 billion in 2026, reaching US$14.60 billion by 2033, growing at an 11.5% CAGR