


Axial Flux Motor Market
Axial Flux Motor Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Axial Flux Motor Market Size and Trend Analysis
How Fast Is the Axial Flux Motor Market Scaling?
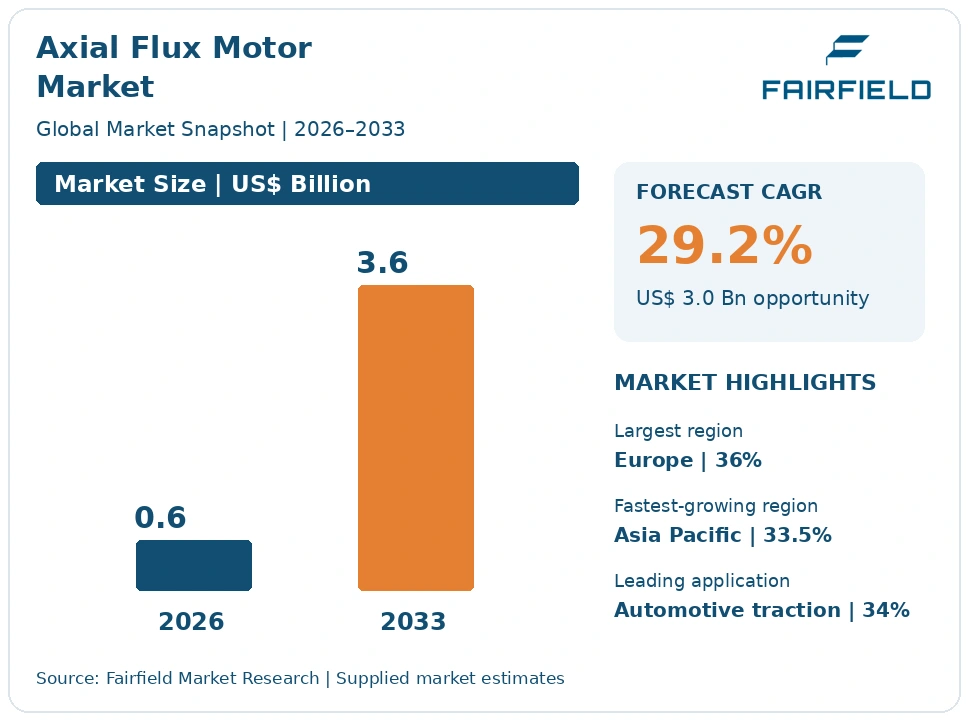
The global Axial Flux Motor market size is expected to be valued at US$ 0.6 billion in 2026 and projected to reach US$ 3.6 billion by 2033, growing at a CAGR of 29.2% between 2026 and 2033.
The market grew at roughly a 34% CAGR between 2020 and 2025, but from a base measured in tens of millions of dollars, so percentage growth overstates commercial maturity. Three factors shape the outlook. The pancake topology delivers higher torque per kilogram and a far shorter axial length than an equivalent radial machine, which wins designs where packaging is the binding constraint. Specialist producers are moving from prototype cells to genuine series lines. Electric aviation, marine and off-highway programmes are reaching hardware selection. The honest position is that axial flux will remain a small fraction of the electric machine market throughout the forecast, constrained by manufacturing readiness rather than by physics.
Key Report Takeaways
- By Topology: Single Stator–Single Rotor held 37% share in 2026, while Yokeless and Segmented Armature designs are projected to expand at a 33.4% CAGR through 2033, driven by their superior torque density and shorter end-winding losses.
- By Cooling Technology: Air Cooling held 48% share in 2026, while Direct Oil Cooling is projected to expand at a 34.2% CAGR through 2033, driven by continuous-rating requirements in traction and aviation duty cycles.
- By Power Rating: Up to 50 kW held 43% share in 2026, while the 50 kW to 200 kW band is projected to expand at a 31.8% CAGR through 2033, driven by axle-integrated and marine propulsion programmes.
- By Application: Automotive Traction held 34% share in 2026, while Aerospace and Electric Aviation is projected to expand at a 36.5% CAGR through 2033, driven by certification work on electric and hybrid-electric propulsion units.
- By Geography: Europe held 36% share in 2026, while Asia Pacific is projected to expand at a 33.5% CAGR through 2033, driven by magnet supply proximity and rapid industrial drive adoption.
Global Axial Flux Motor Market Trends and Insights
Drivers Impact Analysis
Two forces explain why designers accept a less mature machine topology.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Torque density and short axial length winning packaging-constrained designs | High | Europe, North America | Medium term 2–4 years |
| Efficiency regulation rewarding lower-loss machine architectures in industrial drives | Medium | Europe, Asia Pacific | Long term ≥4 years |
Short Axial Length Wins Designs Where Installation Depth Is the Binding Constraint
Packaging, not efficiency alone, is what sells an axial flux machine today. The disc geometry places the magnetic gap perpendicular to the shaft, which produces high torque from a machine only a fraction of the length of an equivalent radial motor. That matters when the envelope is a wheel hub, a thin axle housing or a nacelle. Designers accept a higher unit price when the alternative is a vehicle or aircraft that does not package at all.
The causal mechanism is the flux path. A shorter path through the stator teeth and a larger effective air-gap radius raise torque per unit of active mass. Yokeless and segmented armature construction removes the stator back-iron entirely, cutting mass and iron loss further. UNECE Regulation No. 85, which governs how net and thirty-minute power of electric drive trains is measured, gives buyers a common basis for comparing those density claims across suppliers.
Industrial Efficiency Classes Push Buyers Toward Lower-Loss Machine Architectures
Industrial drive demand is a quieter but steadier pull than traction, and it is driven by electricity cost and efficiency regulation. Pumps, fans, compressors, conveyors and robotic joints run for thousands of hours a year, so a point of efficiency is worth real money over an asset life. Axial flux machines, particularly air-cored designs with no cogging torque and negligible iron loss, compete strongly in this duty profile and often remove the need for a gearbox.
The regulatory mechanism is explicit. IEC 60034-30-1 defines efficiency classes from IE1 to IE5 for line-operated machines, and European Union ecodesign requirements have progressively raised the minimum class permitted for motors placed on the market. Facility operators specifying to the higher classes find that compact, direct-drive axial machines reduce both losses and installed footprint, which is valuable in retrofit projects where plant space is fixed.
Restraints Impact Analysis
Two constraints keep this topology a niche rather than a mainstream machine.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Manufacturing tolerance, winding and assembly difficulty limiting volume output | High | Global | Long term ≥4 years |
| Narrow supply base for high-grade magnets and thin laminations | Medium | Global | Short term ≤2 years |
Assembly Tolerances and Winding Complexity Cap Achievable Production Volume
Manufacturing readiness, not performance, is the binding limit on this market. An axial flux machine must hold a very small axial air gap across a large disc diameter, while the rotor exerts a strong axial magnetic attraction that tries to close that gap. Holding flatness, concentricity and bearing preload at volume is far harder than holding a radial machine’s cylindrical tolerances. Yield losses, rework and slow cycle times keep unit cost above radial equivalents even at comparable output.
The underlying cause is the absence of an installed production equipment base. Radial motor manufacturing runs on decades of amortised stator winding, lamination stacking and impregnation machinery. Axial flux needs segmented armature assembly, specialised coil forming, and automated magnet placement against large attractive forces, much of which is still being developed. Each new line is effectively bespoke capital, which raises the fixed cost that must be recovered over modest volumes.
Magnet and Lamination Supply Concentration Restricts Scale-Up Confidence
A narrow upstream supply chain makes volume commitments risky for both suppliers and their customers. High-energy neodymium-iron-boron magnets with the grain-boundary diffusion needed for high-temperature operation come from a small number of qualified producers. Thin, low-loss silicon steel and soft magnetic composite material for axial geometries has a similarly short qualified list. A single allocation decision upstream can stall a programme that has already passed design validation.
The specific exposure is policy as much as geology. Export licensing introduced on medium and heavy rare earth elements and the magnets containing them has lengthened lead times and injected price uncertainty. The European Union has responded with the Critical Raw Materials Act, which sets extraction, processing and recycling benchmarks, but new capacity takes years. Reduced-dysprosium, ferrite-assisted and wound-rotor alternatives are under development precisely to remove this dependency.
Market Opportunities
Two revenue pools sit outside mainstream passenger car traction.
Axle-Integrated and In-Wheel Units Open a Chassis-Level Revenue Pool
Integrating the machine into the axle or the wheel converts a component sale into a chassis module sale, at several times the value. An axial flux motor short enough to sit inside a wheel rim or within an axle beam frees the entire centre of the vehicle for battery, payload or cabin space. Commercial vehicle, bus and off-highway manufacturers value that volume directly, because it translates into range, load capacity or a lower floor.
The buyers are commercial vehicle and specialist platform makers rather than high-volume car manufacturers. Low-floor city buses, last-mile delivery vehicles, agricultural implements and airport ground equipment all face packaging constraints that a radial machine with its gearbox cannot resolve. Unsprung mass and shock loading remain genuine engineering obstacles for in-wheel designs, which is why axle-integrated configurations are reaching production first and will carry most near-term revenue.
Electric Aviation Propulsion Creates a Certification-Protected Revenue Pool
Electric and hybrid-electric aircraft propulsion is the application where axial flux economics work best, because power-to-weight dominates unit cost in the buying decision. Every kilogram removed from a propulsion unit returns directly as payload, range or battery allowance. Suppliers able to demonstrate continuous power density well above radial alternatives, with the thermal management to sustain it, can price accordingly in a market that does not shop on dollars per kilowatt.
Airframers developing vertical take-off and landing aircraft, commuter aircraft, retrofit propulsion for general aviation and unmanned platforms are the customer group. Certification is the moat: the European Union Aviation Safety Agency and the Federal Aviation Administration require exhaustive qualification of propulsion hardware, and the resulting evidence base is slow and costly to replicate. A supplier that completes that work with one airframer holds a durable position on subsequent programmes.
Segment Analysis
By Topology: Simple Single-Rotor Designs Lead While Yokeless Architectures Advance Fastest
Single Stator–Single Rotor machines held 37% of revenue in 2026, the largest topology position, because the configuration is the easiest to manufacture and to balance axially, and it suits lower-power industrial and light mobility duty. Dual Stator–Single Rotor designs follow, cancelling axial attraction forces and easing bearing design. Air-Cored Coreless machines occupy a specialist niche where zero cogging and negligible iron loss matter more than peak torque. Yokeless and Segmented Armature designs are the fastest-growing topology at a 33.4% CAGR to 2033. Removing the stator back-iron cuts mass and loss simultaneously, which produces the highest torque density available in production hardware, and segmented assembly is also the configuration most amenable to automation. The business implication is that the topology best suited to high-volume manufacture is also the one with the strongest performance case, which should compress cost over the forecast period.
By Cooling Technology: Air Cooling Leads Installed Units While Direct Oil Cooling Scales Quickest
Air Cooling held 48% of revenue in 2026, reflecting the large number of lower-power industrial, robotics and light mobility units where passive or fan-assisted cooling is sufficient and cheapest. Liquid Jacket Cooling takes the middle ground, circulating coolant through a housing channel and serving most automotive traction and marine applications today. Direct Oil Cooling is the fastest-growing approach at a 34.2% CAGR through 2033, because axial flux machines concentrate losses in end windings and rotor surfaces that a jacket cannot reach efficiently. Spraying or flooding oil directly onto the winding raises continuous rating substantially, which is the difference between a strong peak-torque figure and a machine that holds power through a climb or a long grade. For suppliers, thermal capability is becoming the main technical differentiator, since torque density claims mean little without the cooling to sustain them.
By Power Rating: Sub-50 Kilowatt Units Lead Volume as Mid-Range Machines Grow Fastest
Machines rated Up to 50 kW accounted for 43% of value in 2026, the largest power band, supported by robotics, industrial drives, light electric vehicles, marine auxiliaries and unmanned aerial platforms. These applications buy in reasonable quantity and tolerate the topology’s current cost premium. The 50 kW to 200 kW band is the fastest-growing rating at a 31.8% CAGR to 2033, driven by axle-integrated commercial vehicle drives, marine propulsion for workboats and ferries, and distributed aviation propulsion units. This band is where packaging advantage and power density both matter and where programme volumes are large enough to justify dedicated tooling. Machines Above 200 kW serve high-performance vehicles and larger marine installations, with lower unit counts but the highest prices. The implication is that mid-range production capacity is where suppliers should concentrate industrialisation spending.
By Application: Automotive Traction Leads Revenue While Electric Aviation Expands Most Rapidly
Automotive Traction held 34% of revenue in 2026, the largest application, though that position rests on high-performance and low-volume premium vehicles rather than on mass-market cars, where radial machines on amortised lines remain decisively cheaper. Commercial and Off-Highway Vehicles form the second block, valuing short axial length in axle and wheel installations. Industrial Drives and Robotics contribute steady volume at lower unit values. Marine Propulsion is growing on inland ferry and workboat electrification. Aerospace and Electric Aviation is the fastest-growing application at a 36.5% CAGR through 2033, expanding from a very small base as vertical take-off and landing, commuter and unmanned programmes move from demonstrators into qualification. For suppliers, the practical conclusion is to pursue applications that pay for power density rather than chasing mass-market traction volume.
Geography Analysis
North America Pairs Aerospace Programmes With Performance Vehicle Demand
North America held 27% of global revenue in 2026, with the United States supplying almost all of it and Canada adding aerospace research capacity. The regional profile is unusually weighted toward aviation and defence propulsion, where power-to-weight justifies the cost premium and where development funding is available well before commercial volume exists. Advanced air mobility developers, unmanned systems programmes and electric propulsion research consortia all specify high-density machines. A second pillar is performance and motorsport vehicles, where low production volumes suit a supplier base still working at modest scale. Industrial adoption is slower than in Europe, because efficiency regulation on motors is less prescriptive. The regional opportunity is onshore magnet and machine production, which policy support for critical mineral processing and domestic manufacturing is beginning to make viable.
Which Region Is Leading the Axial Flux Motor Market?
Europe leads with 36% of global revenue in 2026, a position built on engineering origin rather than on manufacturing scale. The United Kingdom, Germany, Italy, Belgium, Slovenia and France host most of the specialist developers that commercialised the topology, and several remain the reference suppliers for high-performance traction and aviation propulsion. Three causes sustain the lead. Premium and motorsport vehicle programmes provide early customers willing to pay for density. Electric aviation and marine demonstration projects attract public research funding. Industrial efficiency rules under European Union ecodesign requirements create a parallel pull in drives and robotics. The constraint is production capacity: most regional suppliers operate pilot or low-volume lines, so demand beyond a few thousand units per programme must be served from elsewhere. Scaling industrialisation, not winning designs, is the region’s open question.
Which Region Is Growing Fastest in the Axial Flux Motor Market?
Asia Pacific is growing fastest, at a 33.5% CAGR between 2026 and 2033, from 28% share in 2026. China, Japan, South Korea and India drive that expansion. The mechanism is proximity to inputs and to manufacturing capability. Magnet production, silicon steel rolling and precision machining capacity are concentrated in the region, which shortens lead times and lowers landed cost for anyone building machines locally. Electric two-wheeler and light vehicle production provides a large pool of applications where compactness matters and price tolerance is improving. Industrial automation and robotics demand adds a second stream, supported by national efficiency standards for motors. Japan and South Korea contribute materials science depth in magnets and soft magnetic composites. The region’s challenge is intellectual property position, since much of the core topology know-how originated elsewhere and licensing terms shape who can build at scale.
Latin America Builds Early Demand Through Mining and Marine Electrification
Latin America held 5% of revenue in 2026, a small position concentrated in Brazil, Chile and Mexico. Demand is application-led rather than broad. Mining operators in Chile and Peru are electrifying underground haulage and auxiliary equipment, where machine compactness and ventilation savings carry real value. Brazil contributes inland marine and agricultural equipment interest, alongside an established industrial motor manufacturing base that could eventually host local assembly. Barriers are substantial. There is no regional magnet or high-grade lamination supply, so every machine is imported with currency and tariff exposure. Technical service and repair capability for an unfamiliar topology is thin, which makes conservative buyers hesitate. The change worth watching is mining electrification procurement, where total cost of ownership analysis increasingly favours compact direct-drive machines over geared radial alternatives.
Middle East & Africa Begins With Marine, Defence and Industrial Niches
Middle East & Africa accounted for 4% of revenue in 2026, the smallest regional position, led by the United Arab Emirates, Saudi Arabia, Israel and South Africa. Demand is concentrated in unmanned aerial systems, defence propulsion, marine applications and a small number of industrial automation projects. Sovereign investment programmes aimed at advanced manufacturing and at diversifying away from hydrocarbon revenue are funding early technology partnerships. Barriers are the familiar ones for a nascent market. Volumes are too small to justify local production, high ambient temperatures complicate thermal design for machines already sensitive to winding temperature, and qualified service capability barely exists. South Africa offers mining equipment demand comparable to the Andean markets. The opportunity is desalination, oil and gas and industrial pumping, where direct-drive machines could cut both energy use and plant footprint.
Competitive Landscape
The market is fragmented and populated mainly by specialists rather than by diversified motor manufacturers. No supplier holds a dominant global position, and the leading names are small or mid-sized firms whose entire business rests on this topology. That structure reflects where the know-how sits: axial flux performance depends on proprietary rotor construction, winding methods and thermal design that large radial motor producers have little incentive to replicate while their existing lines are fully amortised. Vertical integration is appearing from a different direction, with vehicle and aerospace manufacturers acquiring or funding developers to secure supply rather than buying on the open market.
Competition rests on a short list of measurable factors. Continuous rather than peak torque density is the first, because buyers have learned to discount headline figures unsupported by thermal evidence. Demonstrated manufacturability at the customer’s required volume is the second, and it decides more programmes than performance does. Functional safety evidence under ISO 26262 matters wherever the machine drives a road vehicle, and aviation qualification evidence matters even more where it does not. Price per kilowatt is a secondary consideration in the applications where this topology currently wins, which is itself a signal of market immaturity.
Strategic positioning varies widely. YASA Limited and Evolito Limited trace to the same yokeless engineering lineage but address road and air applications respectively. EMRAX d.o.o. and MAGicALL, Inc. serve aviation, marine and specialist mobility customers from compact product ranges. Infinitum Electric, Inc. and Printed Motor Works Limited concentrate on industrial and commercial duty with printed or air-cored stators. WHYLOT SAS and Lucchi R. Elettromeccanica Srl pursue automotive and industrial programmes from European bases.
Strategic direction across the field points to three themes: industrialising assembly so that tolerance control no longer caps output, reducing or eliminating heavy rare earth content to defuse supply risk, and integrating power electronics and gearing into a sellable module rather than shipping a bare machine.
Axial Flux Motor Industry Leaders
- YASA Limited
- EMRAX d.o.o.
- Evolito Limited
- Infinitum Electric, Inc.
- WHYLOT SAS
Recent Industry Developments
July 2019: The European Union Aviation Safety Agency published its special condition for small-category vertical take-off and landing aircraft – it established the certification basis that electric propulsion suppliers must design against, opening a qualification pathway for high-density traction machines.
July 2023: European Union ecodesign requirements for electric motors moved to their second stage, raising the minimum efficiency class required for a large band of industrial machines – the step strengthened the commercial case for low-loss direct-drive architectures in pumps, fans and compressors.
May 2024: The European Union Critical Raw Materials Act entered into force, setting extraction, processing and recycling benchmarks for strategic materials including rare earth elements – it signalled long-term policy support for magnet supply security that axial flux producers depend on.
April 2025: China introduced export licensing on seven medium and heavy rare earth elements and on magnets containing them – the measure lengthened lead times and raised price uncertainty for high-temperature magnet grades used in axial flux rotors.
Axial Flux Motor Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 0.6 Billion |
| Market Size 2033 | US$ 3.6 Billion |
| CAGR 2026–2033 | 29.2% |
| Absolute Dollar Opportunity | US$ 3.0 Billion |
| Largest Market | Europe, 36% share in 2026 |
| Fastest-Growing Market | Asia Pacific, 33.5% CAGR |
| Market Concentration | Low |
| Major Players | YASA Limited, EMRAX d.o.o., Evolito Limited, Infinitum Electric, Inc. |
This study covers axial flux permanent magnet and related pancake-topology electric machines, including yokeless and segmented armature, single and dual rotor, air-cored and iron-cored designs, with their stator, rotor, magnet and cooling technology. Integrated power electronics are included where supplied as one unit. Radial flux machines, switched reluctance motors and standalone inverters are excluded. The base year is 2025 and the forecast period runs from 2026 to 2033, reported in US$ Billion.
Axial Flux Motor Market Segmentation
Topology
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
Cooling Technology
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
Power Rating
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
Application
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Axial Flux Motor Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Short Axial Length Wins Designs Where Installation Depth Is the Binding Constraint
- Industrial Efficiency Classes Push Buyers Toward Lower-Loss Machine Architectures
- Restraints
- Assembly Tolerances and Winding Complexity Cap Achievable Production Volume
- Magnet and Lamination Supply Concentration Restricts Scale-Up Confidence
- Market Opportunities
- Axle-Integrated and In-Wheel Units Open a Chassis-Level Revenue Pool
- Electric Aviation Propulsion Creates a Certification-Protected Revenue Pool
- Drivers
- Global Axial Flux Motor Market Outlook, 2020–2033
- Global Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- Global Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- Global Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- Global Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- Global Axial Flux Motor Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- North America Axial Flux Motor Market Outlook, 2020–2033
- North America Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- North America Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- North America Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- North America Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- North America Axial Flux Motor Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Axial Flux Motor Market Outlook, by Topology, 2020–2033
- United States Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- United States Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- United States Axial Flux Motor Market Outlook, by Application, 2020–2033
- Canada Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Canada Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Canada Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Canada Axial Flux Motor Market Outlook, by Application, 2020–2033
- North America Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Europe Axial Flux Motor Market Outlook, 2020–2033
- Europe Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- Europe Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- Europe Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- Europe Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- Europe Axial Flux Motor Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Kingdom Axial Flux Motor Market Outlook, by Topology, 2020–2033
- United Kingdom Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- United Kingdom Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- United Kingdom Axial Flux Motor Market Outlook, by Application, 2020–2033
- Germany Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Germany Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Germany Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Germany Axial Flux Motor Market Outlook, by Application, 2020–2033
- Italy Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Italy Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Italy Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Italy Axial Flux Motor Market Outlook, by Application, 2020–2033
- Belgium Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Belgium Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Belgium Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Belgium Axial Flux Motor Market Outlook, by Application, 2020–2033
- Slovenia Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Slovenia Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Slovenia Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Slovenia Axial Flux Motor Market Outlook, by Application, 2020–2033
- France Axial Flux Motor Market Outlook, by Topology, 2020–2033
- France Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- France Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- France Axial Flux Motor Market Outlook, by Application, 2020–2033
- Europe Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Asia Pacific Axial Flux Motor Market Outlook, 2020–2033
- Asia Pacific Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- Asia Pacific Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- Asia Pacific Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- Asia Pacific Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- Asia Pacific Axial Flux Motor Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Axial Flux Motor Market Outlook, by Topology, 2020–2033
- China Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- China Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- China Axial Flux Motor Market Outlook, by Application, 2020–2033
- Japan Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Japan Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Japan Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Japan Axial Flux Motor Market Outlook, by Application, 2020–2033
- South Korea Axial Flux Motor Market Outlook, by Topology, 2020–2033
- South Korea Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- South Korea Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- South Korea Axial Flux Motor Market Outlook, by Application, 2020–2033
- India Axial Flux Motor Market Outlook, by Topology, 2020–2033
- India Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- India Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- India Axial Flux Motor Market Outlook, by Application, 2020–2033
- Asia Pacific Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Latin America Axial Flux Motor Market Outlook, 2020–2033
- Latin America Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- Latin America Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- Latin America Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- Latin America Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- Latin America Axial Flux Motor Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Brazil Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Brazil Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Brazil Axial Flux Motor Market Outlook, by Application, 2020–2033
- Chile Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Chile Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Chile Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Chile Axial Flux Motor Market Outlook, by Application, 2020–2033
- Mexico Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Mexico Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Mexico Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Mexico Axial Flux Motor Market Outlook, by Application, 2020–2033
- Peru Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Peru Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Peru Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Peru Axial Flux Motor Market Outlook, by Application, 2020–2033
- Latin America Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Middle East & Africa Axial Flux Motor Market Outlook, 2020–2033
- Middle East & Africa Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
- Middle East & Africa Axial Flux Motor Market Outlook, by Cooling Technology, Value (US$ Billion), 2020–2033
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
- Middle East & Africa Axial Flux Motor Market Outlook, by Power Rating, Value (US$ Billion), 2020–2033
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
- Middle East & Africa Axial Flux Motor Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
- Middle East & Africa Axial Flux Motor Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Axial Flux Motor Market Outlook, by Topology, 2020–2033
- United Arab Emirates Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- United Arab Emirates Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- United Arab Emirates Axial Flux Motor Market Outlook, by Application, 2020–2033
- Saudi Arabia Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Saudi Arabia Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Saudi Arabia Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Saudi Arabia Axial Flux Motor Market Outlook, by Application, 2020–2033
- Israel Axial Flux Motor Market Outlook, by Topology, 2020–2033
- Israel Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- Israel Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- Israel Axial Flux Motor Market Outlook, by Application, 2020–2033
- South Africa Axial Flux Motor Market Outlook, by Topology, 2020–2033
- South Africa Axial Flux Motor Market Outlook, by Cooling Technology, 2020–2033
- South Africa Axial Flux Motor Market Outlook, by Power Rating, 2020–2033
- South Africa Axial Flux Motor Market Outlook, by Application, 2020–2033
- Middle East & Africa Axial Flux Motor Market Outlook, by Topology, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- YASA Limited
- EMRAX d.o.o.
- Evolito Limited
- Infinitum Electric, Inc.
- WHYLOT SAS
- Lucchi R. Elettromeccanica Srl
- Printed Motor Works Limited
- H3X Technologies, Inc.
- MAGicALL, Inc.
- Nidec Corporation
- Mercedes-Benz Group AG
- Ricardo plc
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Topology
- Single Stator–Single Rotor
- Dual Stator–Single Rotor
- Yokeless and Segmented Armature
- Air-Cored Coreless
Cooling Technology
- Air Cooling
- Liquid Jacket Cooling
- Direct Oil Cooling
Power Rating
- Up to 50 kW
- 50 kW to 200 kW
- Above 200 kW
Application
- Automotive Traction
- Commercial and Off-Highway Vehicles
- Marine Propulsion
- Aerospace and Electric Aviation
- Industrial Drives and Robotics
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 0.6 billion in 2026, a small fraction of total electric machine demand across traction, marine, aerospace and industrial applications.
Revenue is projected to reach US$ 3.6 billion by 2033, a 29.2% CAGR and an absolute dollar opportunity of US$ 3.0 billion over the period.
Automotive Traction leads with 34% share in 2026, concentrated in high-performance and premium vehicles rather than mass-market passenger car programmes.
Aerospace and Electric Aviation grows fastest at a 36.5% CAGR, as vertical take-off, commuter and unmanned propulsion programmes move from demonstrators into certification.
Concentration is low and the field is fragmented, dominated by topology specialists rather than by established radial motor manufacturers with amortised production lines.
Related Reports
Autonomous Cars, Robotaxis & Sensors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The autonomous cars, robotaxis and sensors market is projected to grow from US$38.0 Bn in 2026 to US$118.3 Bn by 2033, at a CAGR of 17.6%.
Electric Two Wheeler Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The electric two wheeler market is projected to grow from US$52.0 billion in 2026 to US$98.4 billion by 2033, at a CAGR of 9.5%, led by Asia Pacific demand.
Pass by Noise Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pass-by noise testing market to grow from US$1.72 Bn in 2026 to US$2.43 Bn by 2033 at 5.0% CAGR. Explore components, test types, propulsion and regions.
Electric Vehicle Sound Generator Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Electric vehicle sound generator market to grow from US$1.2 Bn in 2026 to US$3.2 Bn by 2033 at 15.0% CAGR. Explore systems, components and regions.
On-Demand Warehousing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-demand warehousing market to grow from US$17.20 Bn in 2026 to US$47.51 Bn by 2033 at 15.6% CAGR. Explore services, storage duration and regional trends.
On-Demand Trucking Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On-demand trucking market to grow from US$11.00 Bn in 2026 to US$30.52 Bn by 2033 at 15.7% CAGR. Explore truck types, services, industries and regions.