


Ayurveda Medicine Market
Ayurveda Medicine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Ayurveda Medicine Market Size and Trend Analysis
How Fast Is the Ayurveda Medicine Market Growing?
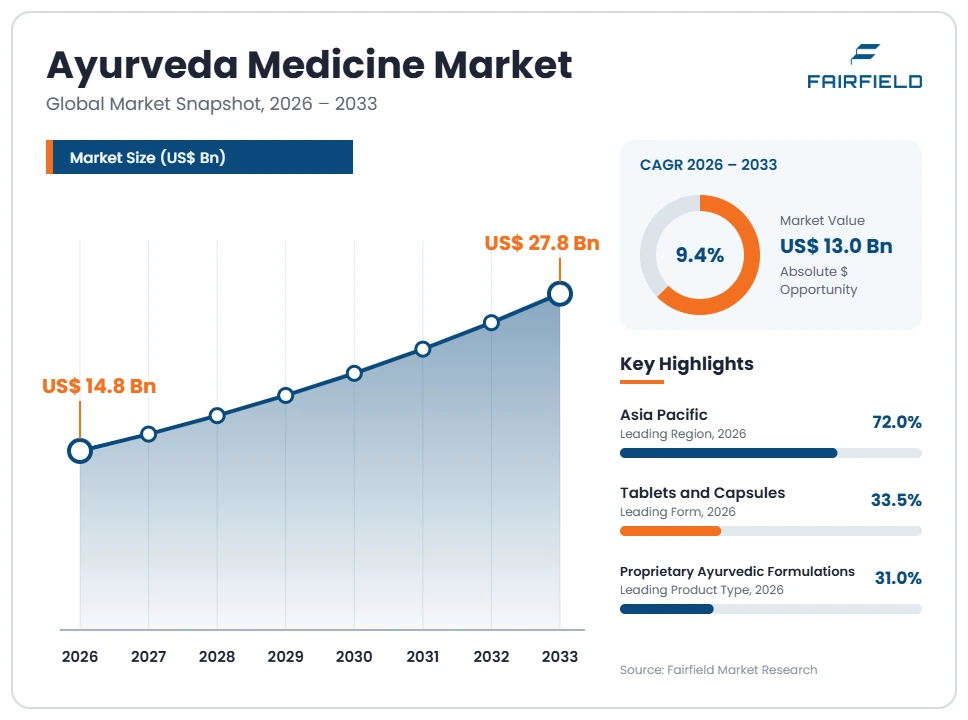
The global Ayurveda Medicine market size is expected to be valued at US$ 14.8 billion in 2026 and projected to reach US$ 27.8 billion by 2033, growing at a CAGR of 9.4% between 2026 and 2033.
The sector expanded at an estimated 8.6% CAGR between 2020 and 2025, lifted by pandemic-era interest in immunity-positioned products and by sustained policy support from India’s Ministry of Ayush. Three factors carry the forecast. First, household spending on traditional medicine keeps rising in India, where Ayurveda is a mainstream retail category rather than a niche one. Second, organised manufacturers are converting unbranded classical preparations into packaged, barcoded goods sold through modern trade. Third, export demand is widening, with Ayurvedic goods entering Western markets as dietary supplements or as registered traditional herbal products. Direction is steadily upward, though growth is uneven: advertising enforcement, product-quality scrutiny and limited clinical evidence temper the pace outside Asia Pacific.
Key Report Takeaways
- By Product Type: Proprietary Ayurvedic Formulations held 31.0% share in 2026, while Ayurvedic Nutraceuticals and Dietary Supplements are projected to expand at an 11.8% CAGR through 2033, driven by capsule-format wellness products sold outside the prescription channel.
- By Form: Tablets and Capsules held 33.5% share in 2026, while Oils and Topical Preparations are projected to expand at a 10.9% CAGR through 2033, supported by panchakarma-linked therapy demand and spa-channel procurement across the Gulf states.
- By Distribution Channel: Retail Pharmacies and Drug Stores held 28.0% share in 2026, while Online Retail is projected to expand at a 13.6% CAGR through 2033, reflecting the shift of repeat wellness purchases to subscription-based digital platforms.
- By Application Area: Skin and Hair Care held 27.0% share in 2026, while General Wellness and Immunity Support is projected to expand at an 11.2% CAGR through 2033, as daily-use positioning replaces episodic, condition-led purchasing.
- By Geography: Asia Pacific held 72.0% share in 2026, while Middle East & Africa is projected to expand at an 11.6% CAGR through 2033, helped by Gulf wellness-tourism investment and large resident Indian expatriate populations.
Global Ayurveda Medicine Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the incremental revenue expected across the Ayurvedic medicine industry to 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Ayush policy infrastructure and export certification in India | High | Asia Pacific, Middle East & Africa | Medium term 2–4 years |
| Migration of classical preparations into branded packaged retail | High | Global | Long term ≥4 years |
Ayush Policy Infrastructure in India Widens the Addressable Base for Ayurvedic Medicines
India’s state apparatus for traditional medicine is the single largest demand lever in this market. The Ministry of Ayush funds dispensaries, co-locates Ayurveda services in public health facilities, and supports teaching hospitals that generate steady institutional procurement. Public insurance and state wellness programmes have progressively recognised Ayurvedic treatment settings, which converts discretionary spending into budgeted spending and stabilises manufacturer order books.
The causal mechanism is certification plus distribution. Manufacturing of Ayurveda, Siddha and Unani drugs is licensed under the Drugs and Cosmetics Act, 1940 and its rules, with Schedule T setting good manufacturing practice for these drugs. Voluntary quality schemes such as the Ayush Premium Mark and export-oriented certification give buyers a documented basis for procurement. Importers in the Gulf and in Southeast Asian markets increasingly ask for that documentation before listing a product.
Conversion of Unbranded Classical Preparations into Packaged Retail Goods Lifts Realised Value
Formalisation is raising revenue per unit without requiring new consumers. Preparations that were once dispensed loose by practitioners are now sold as sealed tablets, sachets and bottles with batch numbers, expiry dates and printed ingredient lists. Packaged goods command higher prices than loose equivalents, move through modern trade, and are easier to export. This shift transfers volume from the informal economy into measured market value.
The mechanism is industrial rather than cultural. Contract manufacturing capacity in Gujarat, Uttarakhand, Kerala and Madhya Pradesh has standardised extraction, granulation and blister packing for herbal medicine lines. Schedule T compliance, stability testing and barcode-level traceability let large fast-moving consumer goods distributors handle these products on the same terms as conventional over-the-counter goods, which multiplies the number of outlets a single formulation can reach.
Restraints Impact Analysis
Two restraints materially slow conversion of consumer interest into regulated, exportable revenue.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Limited and contested clinical evidence base for most formulations | High | North America, Europe | Long term ≥4 years |
| Documented heavy-metal contamination and resulting import scrutiny | Medium | Global | Medium term 2–4 years |
Thin Clinical Evidence Keeps Ayurvedic Formulations Outside Reimbursed Western Care
The evidence position caps the premium that Ayurvedic products can command in regulated healthcare channels. Mainstream medical literature holds that rigorous, adequately powered trials are absent or inconclusive for most classical formulations, and systematic reviews frequently report high risk of bias in available studies. Without accepted efficacy data, these goods cannot enter prescription formularies or reimbursement schedules in most high-income health systems.
The regulatory consequence follows directly. In the European Union, Directive 2004/24/EC lets traditional herbal medicinal products register on evidence of long-standing traditional use rather than on clinical efficacy, which permits sale but restricts permitted indications. In the United States, products marketed under the Dietary Supplement Health and Education Act may not claim to diagnose, treat, cure or prevent disease. Both routes confine Ayurveda to self-care positioning and limit achievable pricing.
Heavy-Metal Findings and Advertising Enforcement Constrain Export Growth and Brand Claims
Product-quality findings and advertising rules together restrain the category’s fastest-moving claims. Peer-reviewed analyses published in the Journal of the American Medical Association found detectable lead, mercury or arsenic in roughly one in five Ayurvedic products purchased in retail and online channels in the United States. Those findings triggered health advisories and import alerts in several countries, which raises testing costs and slows customs clearance for exporters.
The underlying causes are raw-material and formulation specific. Some traditional rasa shastra preparations intentionally incorporate metallic ingredients, while agricultural inputs and soil can introduce contaminants into botanical raw material. Enforcement adds a second cost layer: India restricts advertising of drugs for listed conditions under the Drugs and Magic Remedies (Objectionable Advertisements) Act, 1954, and proceedings before the Supreme Court of India on misleading health claims have tightened scrutiny of Ayurvedic advertising.
Market Opportunities
Standardised Clinical Trial Programmes Open a Documented-Evidence Premium Segment
A small, defensible premium tier is emerging for formulations backed by published, well-designed research. Buyers in institutional and practitioner channels increasingly separate products with documented composition, marker-compound assays and registered trials from the broader category. That separation creates pricing headroom that generic churna and oil lines cannot access, and it supports listing in pharmacy chains that apply conventional vendor-qualification standards.
Capturing this pool favours manufacturers with in-house analytical laboratories and academic partnerships. The demand comes from integrative clinics, corporate wellness buyers and export distributors who must satisfy their own compliance committees. India’s research councils for traditional medicine and the World Health Organization work on traditional medicine documentation give these programmes an institutional framework. Standardised botanical fingerprinting and contaminant testing are the practical entry requirements for this revenue pool.
Ayurvedic Wellness Services and Medical Travel Create a Non-Product Revenue Pool
Treatment services are becoming a revenue line in their own right, separate from packaged goods. Residential panchakarma centres, hospital-attached Ayurveda departments and resort-based wellness programmes monetise practitioner time, accommodation and therapy courses at far higher ticket values than retail products. Kerala, Karnataka and Uttarakhand anchor this activity in India, and product sales attach to it as a secondary stream.
Hospitality groups, hospital operators and established manufacturers with clinic networks are best positioned to capture it. Demand comes from affluent domestic consumers, diaspora travellers and inbound visitors from the Gulf, Europe and Russia. India’s medical-value-travel promotion framework and visa facilitation for treatment travel support that flow, while state tourism boards grade and certify centres by service standard and facility type. Trained practitioner supply, rather than consumer demand, is the binding constraint on how quickly operators can add treatment rooms and residential capacity.
Segment Analysis
- By Product Type: Proprietary Formulations Lead While Ayurvedic Nutraceuticals Scale Fastest
Proprietary Ayurvedic Formulations held 31.0% of global revenue in 2026, the largest share of any product type. These branded, company-developed preparations carry higher margins than classical texts-based medicines because manufacturers control the recipe, the packaging and the price. They also advertise more freely than prescription-style classical products, so they dominate pharmacy shelves and general trade. Ayurvedic Nutraceuticals and Dietary Supplements are the fastest-growing type at an 11.8% CAGR to 2033, as ashwagandha, triphala and turmeric lines sell internationally in capsule and gummy formats under supplement rules rather than drug rules. Ayurvedic Personal Care Products contribute substantial volume through hair oils, toothpastes and skin preparations, and Ayurvedic Clinical and Wellness Services add service revenue. The practical implication is that growth capital is flowing toward formats that travel across borders with the least regulatory friction.
- By Form: Tablets and Capsules Dominate Shelves as Oils and Topicals Accelerate
Tablets and Capsules accounted for 33.5% of the Ayurvedic medicine market in 2026. Solid dose forms travel well, carry accurate labelling, resist spoilage and fit the blister-packing lines that contract manufacturers have installed, so organised brands default to them. Powders, or churna, remain important in traditional dispensing but lose share as consumers favour measured doses. Oils and Topical Preparations are the fastest-growing form at a 10.9% CAGR through 2033, pulled by therapy centres, massage-linked services and export buyers in the Gulf who purchase by volume for spa and salon use. Liquids such as asava and arishta hold a stable niche tied to practitioner prescribing. Form choice increasingly determines channel access: solid doses win modern retail listings, while oils anchor the services and hospitality business that manufacturers are building alongside products.
- By Distribution Channel: Retail Pharmacies Hold Scale While Online Retail Compounds Quickly
Retail Pharmacies and Drug Stores held 28.0% share in 2026, the leading channel, because Ayurvedic products sit beside conventional over-the-counter goods in the same Indian outlets that consumers already visit. Pharmacy staff act as informal advisers, and pack sizes are priced for repeat purchase. Online Retail is the fastest-growing channel at a 13.6% CAGR to 2033, supported by national e-commerce platforms, brand-owned stores and subscription refills that suit daily-use supplements. Ayurvedic Pharmacies and Dispensaries retain practitioner-linked demand, supermarkets carry personal care lines, and clinics and wellness centres sell therapy-attached products. Channel economics are shifting accordingly: digital commerce lowers the cost of reaching smaller cities and diaspora buyers, but it also exposes brands to platform-level claim moderation and to return rates that physical pharmacies never faced.
- By Application Area: Skin and Hair Care Leads as General Wellness Positioning Grows Fastest
Skin and Hair Care represented 27.0% of revenue in 2026, the largest application area, because Ayurvedic positioning is strongest in daily-use cosmetic categories where claims are mild and purchase frequency is high. Hair oils and herbal toothpastes in particular reach households that never visit an Ayurvedic practitioner. General Wellness and Immunity Support is the fastest-growing area at an 11.2% CAGR through 2033, as brands reposition single-herb and combination products as everyday nutrition rather than episodic remedies. Digestive and Gastrointestinal Care, Musculoskeletal and Joint Care, and Respiratory Care follow, each tied to traditional product families with long-standing consumer familiarity. Because permitted claims differ sharply between the Indian, European Union and United States regimes, application positioning is now a regulatory decision as much as a marketing one for every exporting manufacturer.
Geography Analysis
- North America Converts Ayurvedic Products into a Supplement Shelf Category
North America accounted for 12.0% of global revenue in 2026 and is forecast to grow at a 10.2% CAGR to 2033. The United States and Canada drive the entire figure. Products enter almost exclusively as dietary supplements, sold through natural-food retailers, pharmacy chains and large online marketplaces, with ashwagandha and turmeric lines leading. The Dietary Supplement Health and Education Act permits structure-function statements but bars disease claims, so marketing is deliberately general. The Food and Drug Administration has issued import alerts over heavy-metal content, and some state authorities have investigated lead exposure linked to imported herbal products. The region’s opportunity lies in third-party-tested, contaminant-certified lines that satisfy retailer vendor requirements and address the quality concerns that currently cap mainstream distribution.
- Europe Registers Traditional Herbal Products Under a Use-Based Pathway
Europe held 9.0% of the market in 2026, growing at an estimated 9.0% CAGR through 2033. Germany, the United Kingdom, Italy and the Netherlands are the principal destinations. Directive 2004/24/EC created a simplified registration for traditional herbal medicinal products, requiring documented use over a defined period instead of new clinical efficacy data, and the transition period for existing products closed in 2011. That framework gives compliant Ayurvedic preparations legal shelf space but narrows permitted indications to minor, self-limiting conditions. Many importers therefore position goods as food supplements under food law instead. Novel food rules and national maximum levels for contaminants add compliance cost. Growth comes from wellness retail, practitioner clinics and a sizeable diaspora consumer base concentrated in major cities.
- Which Region Is Leading the Ayurveda Medicine Market?
Asia Pacific leads the Ayurveda Medicine market with 72.0% revenue share in 2026, growing at a 9.1% CAGR to 2033. India alone contributes the overwhelming majority of that figure, as Ayurveda is a licensed system of medicine there with its own colleges, hospitals, pharmacopoeia and dedicated ministry. Household familiarity means Ayurvedic goods compete directly with conventional over-the-counter products rather than occupying a specialty niche. Nepal, Sri Lanka and Bangladesh add culturally contiguous demand, while Japan, Australia and Singapore import finished goods for wellness retail. Manufacturing is also concentrated in the region, with licensed units clustered in Gujarat, Uttarakhand, Kerala and Madhya Pradesh. The key change underway is formalisation: advertising enforcement and good manufacturing practice audits are steadily reallocating share toward documented, licensed producers.
- Latin America Builds Demand Through Wellness Retail and Practitioner Networks
Latin America represented 2.5% of global revenue in 2026 and is projected to advance at a 10.5% CAGR through 2033. Brazil and Mexico account for most activity, with Colombia and Argentina emerging. Brazil’s integrative and complementary health practices policy recognises Ayurveda within the public health system, which has normalised practitioner training and yoga-linked wellness services. Demand is concentrated in urban centres and flows through natural-products retailers and clinic networks rather than pharmacies. Barriers are substantial: registration pathways treat most imports as food supplements with restrictive labelling, import duties and freight costs inflate shelf prices, and Portuguese and Spanish labelling requirements deter smaller exporters. The clearest opportunity is local blending and packaging under regional distributor partnerships, which shortens lead times and reduces landed cost.
- Which Region Is Growing Fastest in the Ayurveda Medicine Market?
Middle East & Africa is growing fastest in the Ayurveda Medicine market, at an 11.6% CAGR between 2026 and 2033, from a 4.5% share in 2026. The United Arab Emirates, Saudi Arabia, Oman and Qatar lead, supported by large resident Indian expatriate populations and by state investment in wellness and medical tourism infrastructure. Dubai and Abu Dhabi license Ayurveda practitioners and clinics under their health authorities, which gives the category formal standing that most importing markets lack. South Africa, Kenya and Mauritius add smaller but steady demand. Barriers remain real: registration dossiers, Arabic labelling and halal verification raise entry cost, and contaminant testing at the border can delay shipments. Gulf wellness-resort development is the change most likely to sustain the region’s growth lead.
Competitive Landscape
The Ayurveda Medicine market is fragmented, with low overall concentration. Thousands of licensed manufacturing units operate in India alone, ranging from single-facility family firms producing classical preparations to diversified consumer goods companies with national distribution. A handful of large players such as Dabur India Limited, Patanjali Ayurved Limited, Himalaya Wellness Company and Emami Limited command meaningful branded share, yet the combined share of the top five remains modest against the long tail of regional and practitioner-linked producers. Consolidation has been limited, because brand value in this category is often tied to lineage and regional reputation that does not transfer easily to an acquirer.
Competition turns on four practical factors rather than on patents. The first is manufacturing credibility, evidenced by good manufacturing practice compliance, in-house testing and contaminant control. The second is distribution reach, since shelf presence in general trade and pharmacies determines volume. The third is claim management, as advertising rules restrict what can be said and penalties for overreach are reputational as well as legal. The fourth is price, because many classical formulations are effectively commoditised. New entrants are mostly digital-first supplement brands that outsource manufacturing and compete on formulation clarity, third-party testing and direct subscription selling.
Strategic activity concentrates on capacity, certification and channel. Established manufacturers have been expanding extraction and packaging capacity, pursuing export certification, building clinic and wellness-centre networks, and acquiring or licensing niche botanical brands to enter adjacent categories. Each of these moves addresses a specific competitive gap: capacity secures supply continuity, certification unlocks export listings, and services create recurring customer contact that packaged goods alone do not provide.
Strategic direction across the sector points toward documentation. Vendors are investing in standardised raw-material sourcing, contaminant testing, marker-based quality control and clearer labelling, because those capabilities determine which channels and which countries remain open to them.
Recent Industry Developments
- November 2014: The Government of India created the Ministry of Ayush as a standalone ministry for traditional systems of medicine – it centralised licensing support, research funding and export promotion for the sector.
- April 2011: The registration transition period under European Union Directive 2004/24/EC closed, requiring traditional herbal medicinal products to hold a registration or a marketing authorisation to remain on sale – it set the compliance baseline for Ayurvedic exports to Europe.
- April 2022: The World Health Organization and the Government of India laid the foundation for the WHO Global Centre for Traditional Medicine in Jamnagar, Gujarat – it signalled institutional backing for evidence and standards work in traditional medicine.
- 2024: The Supreme Court of India heard contempt proceedings concerning misleading advertisements for Ayurvedic and other medicinal products and sought self-declarations from advertisers – it raised the compliance cost of aggressive health claims across the category.
- 2024: The Ministry of Ayush moved to revise the advertising provisions applied to Ayurveda, Siddha and Unani products under the Drugs and Cosmetics Rules – it shifted enforcement emphasis toward the Drugs and Magic Remedies (Objectionable Advertisements) Act, 1954.
Companies Covered in the Report
- Dabur India Limited
- Himalaya Wellness Company
- Patanjali Ayurved Limited
- Emami Limited
- Shree Baidyanath Ayurved Bhawan Private Limited
- Arya Vaidya Sala, Kottakkal
- Shree Dhootapapeshwar Limited
- Charak Pharma Private Limited
- Kerala Ayurveda Limited
- Vicco Laboratories
- Amrutanjan Health Care Limited
- Maharishi Ayurveda Products Private Limited
- Sri Sri Tattva
- Organic India Private Limited
- Hindustan Unilever Limited
Ayurveda Medicine Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 14.8 Billion |
| Market Size 2033 | US$ 27.8 Billion |
| CAGR 2026–2033 | 9.4% |
| Absolute Dollar Opportunity | US$ 13.0 Billion |
| Largest Market | Asia Pacific (72.0% share, 2026) |
| Fastest-Growing Market | Middle East & Africa (11.6% CAGR) |
| Market Concentration | Low |
| Major Players | Dabur India Limited, Emami Limited, Himalaya Wellness Company, Patanjali Ayurved Limited, Shree Baidyanath Ayurved Bhawan Private Limited |
Ayurveda Medicine Market Segmentation
Product Type
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
Form
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
Distribution Channel
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
Application Area
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Ayurveda Medicine Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Ayush Policy Infrastructure in India Widens the Addressable Base for Ayurvedic Medicines
- Conversion of Unbranded Classical Preparations into Packaged Retail Goods Lifts Realised Value
- Restraints
- Thin Clinical Evidence Keeps Ayurvedic Formulations Outside Reimbursed Western Care
- Heavy-Metal Findings and Advertising Enforcement Constrain Export Growth and Brand Claims
- Market Opportunities
- Standardised Clinical Trial Programmes Open a Documented-Evidence Premium Segment
- Ayurvedic Wellness Services and Medical Travel Create a Non-Product Revenue Pool
- Drivers
- Global Ayurveda Medicine Market Outlook, 2020–2033
- Global Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- Global Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- Global Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- Global Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- Global Ayurveda Medicine Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Ayurveda Medicine Market Outlook, 2020–2033
- North America Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- North America Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- North America Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- North America Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- North America Ayurveda Medicine Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- United States Ayurveda Medicine Market Outlook, by Form, 2020–2033
- United States Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- United States Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Canada Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Canada Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Canada Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Canada Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- North America Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Ayurveda Medicine Market Outlook, 2020–2033
- Europe Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- Europe Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- Europe Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- Europe Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- Europe Ayurveda Medicine Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Germany Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Germany Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Germany Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- United Kingdom Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- United Kingdom Ayurveda Medicine Market Outlook, by Form, 2020–2033
- United Kingdom Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- United Kingdom Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Italy Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Italy Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Italy Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Italy Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Netherlands Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Netherlands Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Netherlands Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Netherlands Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Europe Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Ayurveda Medicine Market Outlook, 2020–2033
- Asia Pacific Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- Asia Pacific Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- Asia Pacific Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- Asia Pacific Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- Asia Pacific Ayurveda Medicine Market Outlook, by Country, Value (US$ Billion), 2020–2033
- India Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- India Ayurveda Medicine Market Outlook, by Form, 2020–2033
- India Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- India Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Nepal Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Nepal Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Nepal Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Nepal Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Sri Lanka Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Sri Lanka Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Sri Lanka Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Sri Lanka Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Bangladesh Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Bangladesh Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Bangladesh Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Bangladesh Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Japan Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Japan Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Japan Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Japan Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Australia Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Australia Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Australia Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Australia Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Singapore Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Singapore Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Singapore Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Singapore Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Asia Pacific Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Ayurveda Medicine Market Outlook, 2020–2033
- Latin America Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- Latin America Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- Latin America Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- Latin America Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- Latin America Ayurveda Medicine Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Brazil Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Brazil Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Brazil Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Mexico Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Mexico Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Mexico Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Mexico Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Colombia Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Colombia Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Colombia Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Colombia Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Argentina Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Argentina Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Argentina Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Argentina Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Latin America Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Ayurveda Medicine Market Outlook, 2020–2033
- Middle East & Africa Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
- Middle East & Africa Ayurveda Medicine Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
- Middle East & Africa Ayurveda Medicine Market Outlook, by Distribution Channel, Value (US$ Billion), 2020–2033
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
- Middle East & Africa Ayurveda Medicine Market Outlook, by Application Area, Value (US$ Billion), 2020–2033
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
- Middle East & Africa Ayurveda Medicine Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Ayurveda Medicine Market Outlook, by Form, 2020–2033
- United Arab Emirates Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- United Arab Emirates Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Saudi Arabia Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Saudi Arabia Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Saudi Arabia Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Oman Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Oman Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Oman Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Oman Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Qatar Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Qatar Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Qatar Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Qatar Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- South Africa Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- South Africa Ayurveda Medicine Market Outlook, by Form, 2020–2033
- South Africa Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- South Africa Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Kenya Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Kenya Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Kenya Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Kenya Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Mauritius Ayurveda Medicine Market Outlook, by Product Type, 2020–2033
- Mauritius Ayurveda Medicine Market Outlook, by Form, 2020–2033
- Mauritius Ayurveda Medicine Market Outlook, by Distribution Channel, 2020–2033
- Mauritius Ayurveda Medicine Market Outlook, by Application Area, 2020–2033
- Middle East & Africa Ayurveda Medicine Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Dabur India Limited
- Himalaya Wellness Company
- Patanjali Ayurved Limited
- Emami Limited
- Shree Baidyanath Ayurved Bhawan Private Limited
- Arya Vaidya Sala, Kottakkal
- Shree Dhootapapeshwar Limited
- Charak Pharma Private Limited
- Kerala Ayurveda Limited
- Vicco Laboratories
- Amrutanjan Health Care Limited
- Maharishi Ayurveda Products Private Limited
- Sri Sri Tattva
- Organic India Private Limited
- Hindustan Unilever Limited
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Classical Ayurvedic Medicines
- Proprietary Ayurvedic Formulations
- Ayurvedic Nutraceuticals and Dietary Supplements
- Ayurvedic Personal Care Products
- Ayurvedic Clinical and Wellness Services
Form
- Tablets and Capsules
- Powders (Churna)
- Liquids (Asava and Arishta)
- Oils and Topical Preparations
- Others
Distribution Channel
- Ayurvedic Pharmacies and Dispensaries
- Retail Pharmacies and Drug Stores
- Supermarkets and Hypermarkets
- Online Retail
- Ayurvedic Clinics and Wellness Centres
Application Area
- General Wellness and Immunity Support
- Digestive and Gastrointestinal Care
- Musculoskeletal and Joint Care
- Skin and Hair Care
- Respiratory Care
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Ayurveda Medicine market is valued at US$ 14.8 billion in 2026, covering Ayurvedic medicines, nutraceuticals, personal care products and clinical wellness services worldwide.
The market is projected to reach US$ 27.8 billion by 2033, expanding at a 9.4% CAGR and adding US$ 13.0 billion in absolute dollar opportunity.
Proprietary Ayurvedic Formulations lead with 31.0% share in 2026, helped by branded pricing power, wider advertising latitude and strong presence across pharmacy and general trade.
Middle East & Africa is growing fastest at an 11.6% CAGR to 2033, led by Gulf wellness investment, clinic licensing and large resident Indian expatriate communities.
Concentration is low and the market is fragmented, with a few large branded manufacturers competing against thousands of licensed regional and practitioner-linked producers.
Related Reports
Immune Checkpoint Inhibitors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global immune checkpoint inhibitors market is valued at US$52.0 billion in 2026, reaching US$68.0 billion by 2033, growing at a 3.91% CAGR
Geriatric Medicines Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global geriatric medicines market is valued at US$412.0 billion in 2026, reaching US$538.0 billion by 2033, growing at a 3.9% CAGR
Pharmaceutical Temperature Controlled Packaging Solutions Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pharmaceutical temperature controlled packaging solutions market to grow from US$ 6.86 billion in 2026 to US$ 13.98 billion by 2033 at a 10.7% CAGR.
Dermatology CRO Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the dermatology CRO market, projected to reach US$ 9.7 billion by 2033 at a 6.6% CAGR, with service, indication and regional insights.
Acetaminophen Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acetaminophen market is valued at US$11.70 billion in 2026, reaching US$15.93 billion by 2033, growing at a 4.5% CAGR
Allergy Diagnostics and Therapeutics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global allergy diagnostics and therapeutics market is valued at US$41.50 billion in 2026, reaching US$88.30 billion by 2033, growing at an 11.4% CAGR