


Cell Isolation Market
Cell Isolation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Cell Isolation Market Size and Trend Analysis
How Fast Is the Cell Isolation Market Growing?
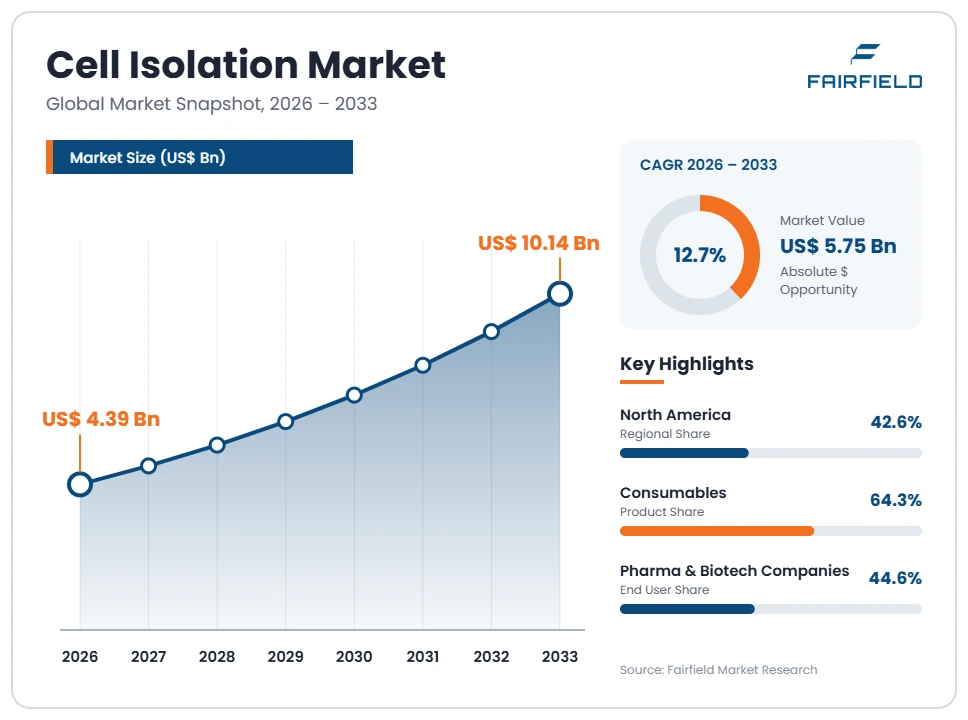
The global cell isolation market size is expected to be valued at US$ 4.39 billion in 2026 and projected to reach US$ 10.14 billion by 2033, growing at a CAGR of 12.7% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 11.2%, supported by pandemic-era immunology research and rapid growth of CAR-T and stem cell programs. Three factors now drive growth: scale-up of cell therapy manufacturing, rising cancer and immunology research, and wider use of single-cell analysis in drug discovery. The market is moving from manual, open bench methods toward automated, closed, and GMP-ready systems that combine magnetic-activated cell sorting, fluorescence-activated cell sorting, and microfluidics to isolate fragile cells with high purity and viability.
Key Report Takeaways
- By Product: Consumables held 64.3% share in 2026, while Instruments are projected to expand at a 13.6% CAGR through 2033, driven by investment in automated, closed systems for clinical-grade manufacturing.
- By Technique: Centrifugation-based held 33.8% share in 2026, while Microfluidics-based is projected to expand at a 15.2% CAGR through 2033, driven by gentle sorting that preserves viability of fragile cells.
- By Cell Type: Stem Cells held 34.2% share in 2026, while Immune Cells are projected to expand at a 14.6% CAGR through 2033, driven by T-cell and NK-cell isolation for CAR-T and other cell therapies.
- By End User: Pharmaceutical & Biotechnology Companies held 44.6% share in 2026, while Contract Development & Manufacturing Organizations are projected to expand at a 14.9% CAGR through 2033, driven by outsourced cell therapy production.
- By Region: North America held 42.6% share in 2026, while Asia Pacific is projected to expand at a 14.3% CAGR through 2033, driven by cell therapy pipelines in China and expanding research capacity in India, Japan, and South Korea.
Global Cell Isolation Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on cell isolation demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Scale-up of cell therapy manufacturing | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
| Growth in cancer, immunology, and single-cell research | High | Global | Medium term (2–4 years) |
Cell Therapy Manufacturing Is Driving Demand for Cell Isolation Systems
The scale-up of cell therapy manufacturing is the strongest driver of cell isolation demand. Every CAR-T, TCR, or stem cell therapy begins with isolating specific cells from a patient's or donor's blood or tissue. Purity and viability at this step directly affect product quality and patient outcomes.
The mechanism is the need for consistent, GMP-compliant cell selection. Manufacturers use magnetic-activated cell sorting to select T cells, CD34-positive stem cells, or NK cells, often in automated closed systems. New approvals of engineered cell therapies in the United States and Europe have expanded commercial production, while hundreds of programs remain in trials. Each patient dose requires single-use consumables such as beads, columns, and tubing sets. This creates recurring demand for cell therapy manufacturing products and encourages investment in automated isolation instruments.
Cancer and Single-Cell Research Expand Use of Cell Isolation Products
Growth in cancer, immunology, and single-cell research expands use of cell isolation products in laboratories. Researchers need pure populations of tumor cells, immune cells, and stem cells to study disease mechanisms, identify targets, and test new drugs.
The cause is rising research funding and new analytical technologies. The U.S. National Cancer Institute had a budget of about US$ 7.2 billion in fiscal 2024, and similar programs support cancer research in Europe and Asia Pacific. Single-cell analysis platforms for sequencing, proteomics, and spatial biology depend on high-quality isolated cells. Fluorescence-activated cell sorting allows researchers to separate rare cells by multiple markers. Organoid and 3D culture research also needs isolated primary cells. These trends keep academic institutes and drug discovery teams buying kits, reagents, and sorters.
Restraints Impact Analysis
Two restraints limit how quickly cell isolation technologies spread.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| High cost of instruments and GMP consumables | Medium | Global, strongest in emerging markets | Medium term (2–4 years) |
| Cell damage, variability, and technical complexity | Medium | Global | Long term (≥4 years) |
High Instrument and Consumable Costs Limit Cell Isolation Adoption
High costs for instruments and GMP-grade consumables limit cell isolation adoption, especially in smaller laboratories and emerging markets. Advanced cell sorters and automated cell processing systems require significant capital investment.
The specific cost sources are precision optics, lasers, microfluidic chips, and clinical-grade reagents. Fluorescence-activated cell sorters use multiple lasers and detectors, and they need trained operators and regular maintenance. GMP-grade antibodies, magnetic beads, and single-use tubing sets cost far more than research-grade versions because of quality control, documentation, and regulatory requirements. Annual service contracts add significant ongoing expense. Academic labs with limited grants often share instruments, which restricts throughput. In Latin America, Africa, and parts of Asia Pacific, budget limits slow adoption of advanced systems beyond major research centers and hospitals.
Cell Damage and Technical Complexity Slow Cell Isolation Performance
Cell damage, variability, and technical complexity slow cell isolation performance in research and manufacturing. Some methods expose cells to high pressure, electric charges, or long processing times, which can reduce viability and alter function.
The underlying causes are biological sensitivity and process differences. Droplet-based sorting can stress fragile cells such as stem cells and primary neurons. Starting material from patients varies widely in cell counts and health, especially in heavily treated cancer patients. Magnetic labeling can affect downstream cell behavior. Different laboratories use different protocols, which makes results hard to compare and scale. Skilled staff are needed to optimize and validate methods for each cell type. These challenges increase batch failure rates, raise costs, and push developers to seek gentler, standardized, and automated isolation technologies that reduce manual handling.
Market Opportunities
Gentle GMP-Ready Cell Sorting Opens a High-Value Revenue Pool in Cell Isolation
Gentle, closed, GMP-ready cell sorting creates a high-value revenue pool in cell isolation. Cell therapy developers want fluorescence-based sorting precision without the sterility and viability risks of traditional droplet sorters, which are hard to use in clinical production.
Instrument makers with closed microfluidic technologies are positioned to capture this opportunity. In June 2025, STEMCELL Technologies acquired Cellular Highways, a UK company whose Highway1 instrument uses vortex-actuated cell sorting in a closed, sterile system. The instrument entered the market in 2024 and is designed and manufactured under ISO 13485 certification. Cell and gene therapy developers, contract manufacturers, and academic GMP facilities are the main customers. Gentle sorting can enable more precise cell populations, such as specific T-cell subsets, which may improve therapy effectiveness and expand premium instrument and consumable sales.
Automated Hematopoietic Stem Cell and Organoid Workflows Create New Demand for Cell Isolation
Automated workflows for hematopoietic stem cell editing and organoid research create new demand for cell isolation. Gene-edited stem cell therapies and organoid models both depend on reliably isolated, high-quality starting cells, and manual methods limit scale.
Life science tool companies and research partners can capture this opportunity. In March 2026, Danaher and the San Raffaele Telethon Institute for Gene Therapy launched the Danaher Beacon collaboration on gene transfer and editing of hematopoietic stem cells, with a focus on automation. In January 2025, Merck KGaA acquired HUB Organoids to expand its organoid offerings. Gene therapy developers, pharmaceutical discovery teams, and academic centers are the main customers. Automated isolation integrated with editing and culture steps can reduce variability and support scale-up for stem cell research and therapy.
Segment Analysis
- By Product: Consumables Lead While Instruments Grow Fastest
Consumables held 64.3% share in 2026. Reagents, antibodies, magnetic beads, kits, columns, and single-use tubing sets are used in every isolation run. Recurring purchases by research labs and cell therapy manufacturers keep consumables the largest revenue source for suppliers.
Instruments are the fastest-growing product segment, expanding at a 13.6% CAGR through 2033. Cell therapy manufacturers and contract organizations are buying automated, closed systems that combine isolation, activation, and expansion. Advanced cell sorters with more lasers and parameters support complex research. New instrument types, such as microfluidic sorters, add premium options. For the market, instrument placements drive long-term consumable sales, because many systems use proprietary kits and tubing sets. This creates strong customer lock-in and recurring revenue for vendors.
- By Technique: Centrifugation-based Leads While Microfluidics-based Expands Fastest
Centrifugation-based held 33.8% share in 2026. Density gradient centrifugation is a simple, low-cost, and widely used method for separating blood cells and other populations. Most laboratories and blood processing centers already own centrifuges, which keeps this technique dominant in routine sample preparation.
Microfluidics-based is the fastest-growing technique, expanding at a 15.2% CAGR through 2033. Microfluidic devices separate cells by size, shape, or markers using tiny channels, often in closed systems. They handle small samples, reduce cell stress, and support rare cell isolation, such as circulating tumor cells. Systems like Highway1 show how microfluidics can bring precision sorting into GMP manufacturing. Surface marker-based and filtration methods remain important. For the market, microfluidic growth adds innovation and premium pricing.
- By Cell Type: Stem Cells Lead While Immune Cells Grow Fastest
Stem Cells held 34.2% share in 2026. Hematopoietic stem cells, mesenchymal stem cells, and induced pluripotent stem cells are central to regenerative medicine, transplantation, and stem cell research. Bone marrow transplant centers routinely isolate CD34-positive cells for therapy.
Immune Cells are the fastest-growing cell type, expanding at a 14.6% CAGR through 2033. CAR-T, TCR, and NK-cell therapies all start with isolating specific immune cells from blood. Immunology and immuno-oncology research also rely on isolated T cells, B cells, and macrophages. Approvals of engineered T-cell therapies in 2024 and growing programs for autoimmune diseases add demand. Tumor cells and other cell types remain significant. For the market, immune cell growth links cell isolation closely to the expanding cell therapy industry.
- By End User: Pharmaceutical & Biotechnology Companies Lead While CDMOs Grow Fastest
Pharmaceutical & Biotechnology Companies held 44.6% share in 2026. Drug developers use cell isolation in discovery, preclinical testing, and cell therapy manufacturing. Large companies run in-house manufacturing for approved therapies and buy high volumes of instruments and consumables under long-term supply agreements.
Contract Development & Manufacturing Organizations are the fastest-growing end user, expanding at a 14.9% CAGR through 2033. Many biotechs lack their own GMP facilities and outsource cell therapy production to specialized partners. These organizations invest in automated, closed isolation systems to serve multiple clients. Research and academic institutes, hospitals, and diagnostic laboratories also remain important. For the market, contract manufacturer growth concentrates purchasing among large, sophisticated buyers who demand validated, scalable, and regulatory-ready isolation platforms.
Geography Analysis
- Which Region Is Leading the Cell Isolation Market?
North America is leading the cell isolation market with a 42.6% share in 2026. The United States has the largest number of cell therapy developers, approved CAR-T therapies, and well-funded research institutions. The U.S. National Cancer Institute and National Institutes of Health support large research programs. Major suppliers such as Danaher, Thermo Fisher Scientific, and BD are based in the region and lead product innovation. Contract manufacturers are expanding cell therapy capacity across several states. Canada adds strength through STEMCELL Technologies in Vancouver. One change shaping the region is the shift to automated, closed manufacturing.
- Europe Combines Research Strength and Cell Therapy Innovation in Cell Isolation
Europe is a major market supported by strong academic research and cell therapy development. Germany is home to Miltenyi Biotec, a leader in magnetic-activated cell sorting and automated cell processing. Merck KGaA and Sartorius add strong tools businesses. The United Kingdom, France, Italy, and the Netherlands host many cell therapy developers and research centers. Italy's San Raffaele Telethon Institute for Gene Therapy is a leader in stem cell gene therapy. Strict regulations on advanced therapy medicinal products raise quality standards and demand for GMP-grade reagents. One opportunity is hospital-based cell therapy production, which requires compact isolation systems.
- Which Region Is Growing Fastest in the Cell Isolation Market?
Asia Pacific is growing fastest in the cell isolation market at a 14.3% CAGR through 2033. China has one of the world's largest CAR-T pipelines and many local developers and manufacturers. Japan offers a fast pathway for regenerative medicine products, supporting stem cell research. South Korea invests in biotechnology and cell therapy. India is expanding research and affordable cell therapy development. Government funding and lower research costs attract global partners and licensing deals. Local suppliers in China offer lower-cost reagents. Import costs and varied national regulations remain barriers. One opportunity is local manufacturing of GMP-grade consumables.
- Latin America Develops Research and Transplant Capacity in Cell Isolation
Latin America is an emerging region where academic research and transplant programs drive cell isolation demand. Brazil leads the region, with research institutes and hospitals developing locally produced CAR-T therapies. Mexico and Argentina have growing biotechnology and stem cell research communities. Bone marrow transplant centers use cell isolation for stem cell processing and graft engineering. Key barriers include limited research budgets, high import costs for instruments, and currency volatility. Skilled staff shortages also limit use of advanced sorting methods outside major cities. One opportunity is regional distribution partnerships that make kits and reagents more affordable for academic and hospital laboratories.
- Middle East & Africa Builds Biotechnology Capacity in Cell Isolation
Middle East & Africa is an early-stage region with growing investment in biotechnology. Saudi Arabia, the United Arab Emirates, and Qatar are building research centers, stem cell programs, and genomics initiatives as part of economic diversification plans. Leading hospitals in the Gulf are developing transplant and cell therapy services. In Africa, South Africa leads research activity. Key barriers include limited specialized laboratories, scarce expertise, and dependence on imported equipment. Research funding is concentrated in a few large academic and hospital centers. One opportunity is partnerships with global suppliers to set up training and regional service hubs.
Competitive Landscape
The cell isolation market is moderately concentrated. Danaher, through Beckman Coulter and other businesses, Thermo Fisher Scientific, and Merck KGaA are leading players. BD and Sony are strong in flow cytometry and cell sorting, while Miltenyi Biotec leads magnetic-activated cell sorting and automated cell processing. STEMCELL Technologies, Bio-Rad, Sartorius, QIAGEN, and Lonza compete in kits and systems. Startups such as Akadeum Life Sciences and pluriSelect target niche methods such as buoyancy-based and sieve-based separation.
Companies compete on purity, viability, speed, automation, GMP compliance, and breadth of kits for different cell types. Closed systems, validated protocols, and regulatory support files are key for cell therapy customers. Research customers value flexibility, ease of use, and multi-parameter sorting for complex experiments.
Strategic moves show how competition is changing. STEMCELL Technologies acquired Cellular Highways in June 2025 to add gentle, closed GMP sorting. Merck KGaA acquired HUB Organoids in January 2025 to strengthen organoid workflows. Alfa Laval launched the Culturefuge 200 B separator for medium-scale cell harvesting in October 2025. Danaher launched the Danaher Beacon collaboration on stem cell gene editing in March 2026. Together, these moves show vendors building complete workflows from isolation to engineering and scale-up.
Three main themes now shape vendor strategy across the industry. First, companies are developing closed, automated systems for cell therapy manufacturing. Second, they are adding gentle microfluidic and label-free technologies. Third, they are linking isolation with downstream culture, editing, and single-cell analysis.
Recent Industry Developments
- March 2026: Danaher and SR-TIGET launched the Danaher Beacon collaboration on stem cell gene transfer and editing – focuses on automating stem cell workflows.
- October 2025: Alfa Laval launched the Culturefuge 200 B separator for medium-scale cell harvesting – expands centrifugation options for bioprocessing.
- June 2025: STEMCELL Technologies acquired Cellular Highways – adds closed, GMP-ready microfluidic cell sorting.
- January 2025: Merck KGaA acquired HUB Organoids – strengthens organoid and 3D culture offerings that rely on isolated cells.
Companies Covered in the Report
- Danaher
- Thermo Fisher Scientific
- Merck KGaA
- Becton, Dickinson and Company (BD)
- Miltenyi Biotec
- STEMCELL Technologies
- Bio-Rad Laboratories
- Sartorius
- QIAGEN
- Lonza
- Sony
- Akadeum Life Sciences
Cell Isolation Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 4.39 Billion |
| Market Size 2033 | US$ 10.14 Billion |
| CAGR 2026–2033 | 12.7% |
| Absolute Dollar Opportunity | US$ 5.75 Billion |
| Largest Market | North America |
| Fastest-Growing Market | Asia Pacific |
| Market Concentration | Medium |
| Major Players | Danaher, Thermo Fisher Scientific, Merck KGaA, Becton, Dickinson and Company (BD), Miltenyi Biotec |
Cell Isolation Market Segmentation
Product
- Consumables
- Instruments
Technique
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
Cell Type
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
End User
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Cell Isolation Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Cell Therapy Manufacturing Is Driving Demand for Cell Isolation Systems
- Cancer and Single-Cell Research Expand Use of Cell Isolation Products
- Restraints
- High Instrument and Consumable Costs Limit Cell Isolation Adoption
- Cell Damage and Technical Complexity Slow Cell Isolation Performance
- Market Opportunities
- Gentle GMP-Ready Cell Sorting Opens a High-Value Revenue Pool in Cell Isolation
- Automated Hematopoietic Stem Cell and Organoid Workflows Create New Demand for Cell Isolation
- Drivers
- Global Cell Isolation Market Outlook, 2020–2033
- Global Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- Global Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- Global Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- Global Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- Global Cell Isolation Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- North America Cell Isolation Market Outlook, 2020–2033
- North America Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- North America Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- North America Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- North America Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- North America Cell Isolation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Cell Isolation Market Outlook, by Product, 2020–2033
- United States Cell Isolation Market Outlook, by Technique, 2020–2033
- United States Cell Isolation Market Outlook, by Cell Type, 2020–2033
- United States Cell Isolation Market Outlook, by End User, 2020–2033
- Canada Cell Isolation Market Outlook, by Product, 2020–2033
- Canada Cell Isolation Market Outlook, by Technique, 2020–2033
- Canada Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Canada Cell Isolation Market Outlook, by End User, 2020–2033
- North America Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Europe Cell Isolation Market Outlook, 2020–2033
- Europe Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- Europe Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- Europe Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- Europe Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- Europe Cell Isolation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Cell Isolation Market Outlook, by Product, 2020–2033
- Germany Cell Isolation Market Outlook, by Technique, 2020–2033
- Germany Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Germany Cell Isolation Market Outlook, by End User, 2020–2033
- United Kingdom Cell Isolation Market Outlook, by Product, 2020–2033
- United Kingdom Cell Isolation Market Outlook, by Technique, 2020–2033
- United Kingdom Cell Isolation Market Outlook, by Cell Type, 2020–2033
- United Kingdom Cell Isolation Market Outlook, by End User, 2020–2033
- France Cell Isolation Market Outlook, by Product, 2020–2033
- France Cell Isolation Market Outlook, by Technique, 2020–2033
- France Cell Isolation Market Outlook, by Cell Type, 2020–2033
- France Cell Isolation Market Outlook, by End User, 2020–2033
- Italy Cell Isolation Market Outlook, by Product, 2020–2033
- Italy Cell Isolation Market Outlook, by Technique, 2020–2033
- Italy Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Italy Cell Isolation Market Outlook, by End User, 2020–2033
- Netherlands Cell Isolation Market Outlook, by Product, 2020–2033
- Netherlands Cell Isolation Market Outlook, by Technique, 2020–2033
- Netherlands Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Netherlands Cell Isolation Market Outlook, by End User, 2020–2033
- Europe Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Asia Pacific Cell Isolation Market Outlook, 2020–2033
- Asia Pacific Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- Asia Pacific Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- Asia Pacific Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- Asia Pacific Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- Asia Pacific Cell Isolation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Cell Isolation Market Outlook, by Product, 2020–2033
- China Cell Isolation Market Outlook, by Technique, 2020–2033
- China Cell Isolation Market Outlook, by Cell Type, 2020–2033
- China Cell Isolation Market Outlook, by End User, 2020–2033
- Japan Cell Isolation Market Outlook, by Product, 2020–2033
- Japan Cell Isolation Market Outlook, by Technique, 2020–2033
- Japan Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Japan Cell Isolation Market Outlook, by End User, 2020–2033
- South Korea Cell Isolation Market Outlook, by Product, 2020–2033
- South Korea Cell Isolation Market Outlook, by Technique, 2020–2033
- South Korea Cell Isolation Market Outlook, by Cell Type, 2020–2033
- South Korea Cell Isolation Market Outlook, by End User, 2020–2033
- India Cell Isolation Market Outlook, by Product, 2020–2033
- India Cell Isolation Market Outlook, by Technique, 2020–2033
- India Cell Isolation Market Outlook, by Cell Type, 2020–2033
- India Cell Isolation Market Outlook, by End User, 2020–2033
- Asia Pacific Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Latin America Cell Isolation Market Outlook, 2020–2033
- Latin America Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- Latin America Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- Latin America Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- Latin America Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- Latin America Cell Isolation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Cell Isolation Market Outlook, by Product, 2020–2033
- Brazil Cell Isolation Market Outlook, by Technique, 2020–2033
- Brazil Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Brazil Cell Isolation Market Outlook, by End User, 2020–2033
- Mexico Cell Isolation Market Outlook, by Product, 2020–2033
- Mexico Cell Isolation Market Outlook, by Technique, 2020–2033
- Mexico Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Mexico Cell Isolation Market Outlook, by End User, 2020–2033
- Argentina Cell Isolation Market Outlook, by Product, 2020–2033
- Argentina Cell Isolation Market Outlook, by Technique, 2020–2033
- Argentina Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Argentina Cell Isolation Market Outlook, by End User, 2020–2033
- Latin America Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Middle East & Africa Cell Isolation Market Outlook, 2020–2033
- Middle East & Africa Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Consumables
- Instruments
- Middle East & Africa Cell Isolation Market Outlook, by Technique, Value (US$ Billion), 2020–2033
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
- Middle East & Africa Cell Isolation Market Outlook, by Cell Type, Value (US$ Billion), 2020–2033
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
- Middle East & Africa Cell Isolation Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
- Middle East & Africa Cell Isolation Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Cell Isolation Market Outlook, by Product, 2020–2033
- Saudi Arabia Cell Isolation Market Outlook, by Technique, 2020–2033
- Saudi Arabia Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Saudi Arabia Cell Isolation Market Outlook, by End User, 2020–2033
- United Arab Emirates Cell Isolation Market Outlook, by Product, 2020–2033
- United Arab Emirates Cell Isolation Market Outlook, by Technique, 2020–2033
- United Arab Emirates Cell Isolation Market Outlook, by Cell Type, 2020–2033
- United Arab Emirates Cell Isolation Market Outlook, by End User, 2020–2033
- Qatar Cell Isolation Market Outlook, by Product, 2020–2033
- Qatar Cell Isolation Market Outlook, by Technique, 2020–2033
- Qatar Cell Isolation Market Outlook, by Cell Type, 2020–2033
- Qatar Cell Isolation Market Outlook, by End User, 2020–2033
- South Africa Cell Isolation Market Outlook, by Product, 2020–2033
- South Africa Cell Isolation Market Outlook, by Technique, 2020–2033
- South Africa Cell Isolation Market Outlook, by Cell Type, 2020–2033
- South Africa Cell Isolation Market Outlook, by End User, 2020–2033
- Middle East & Africa Cell Isolation Market Outlook, by Product, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Danaher
- Thermo Fisher Scientific
- Merck KGaA
- Becton, Dickinson and Company (BD)
- Miltenyi Biotec
- STEMCELL Technologies
- Bio-Rad Laboratories
- Sartorius
- QIAGEN
- Lonza
- Sony
- Akadeum Life Sciences
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product
- Consumables
- Instruments
Technique
- Centrifugation-based
- Surface Marker-based
- Filtration-based
- Microfluidics-based
Cell Type
- Stem Cells
- Immune Cells
- Tumor Cells
- Other Cells
End User
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
- Hospitals & Diagnostic Laboratories
- Contract Development & Manufacturing Organizations
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The cell isolation market is valued at US$ 4.39 billion in 2026, led by consumables used in research and manufacturing.
The market is projected to reach US$ 10.14 billion by 2033, growing at a 12.7% CAGR and adding US$ 5.75 billion.
Immune Cells are growing fastest at a 14.6% CAGR through 2033, driven by T-cell and NK-cell isolation for cell therapies.
Asia Pacific is growing fastest at a 14.3% CAGR through 2033, driven by cell therapy pipelines in China and growing research capacity.
North America holds the largest share at 42.6% in 2026, supported by cell therapy developers, research funding, and major suppliers.
Related Reports
Immune Checkpoint Inhibitors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global immune checkpoint inhibitors market is valued at US$52.0 billion in 2026, reaching US$68.0 billion by 2033, growing at a 3.91% CAGR
Geriatric Medicines Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global geriatric medicines market is valued at US$412.0 billion in 2026, reaching US$538.0 billion by 2033, growing at a 3.9% CAGR
Pharmaceutical Temperature Controlled Packaging Solutions Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pharmaceutical temperature controlled packaging solutions market to grow from US$ 6.86 billion in 2026 to US$ 13.98 billion by 2033 at a 10.7% CAGR.
Dermatology CRO Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the dermatology CRO market, projected to reach US$ 9.7 billion by 2033 at a 6.6% CAGR, with service, indication and regional insights.
Acetaminophen Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acetaminophen market is valued at US$11.70 billion in 2026, reaching US$15.93 billion by 2033, growing at a 4.5% CAGR
Allergy Diagnostics and Therapeutics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global allergy diagnostics and therapeutics market is valued at US$41.50 billion in 2026, reaching US$88.30 billion by 2033, growing at an 11.4% CAGR