


Cervical Cancer Treatment Market
Cervical Cancer Treatment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Report Overview
Cervical Cancer Treatment Market Size and Trend Analysis
How Fast Is the Cervical Cancer Treatment Market Growing?
The global cervical cancer treatment market size is expected to be valued at US$ 10.55 billion in 2026 and projected to reach US$ 15.94 billion by 2033, growing at a CAGR of 6.1% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 5.8%, rising from roughly US$ 7.5 billion to US$ 9.95 billion, as screening and treatment recovered after pandemic delays, immunotherapy moved into earlier lines of care, and the first antibody-drug conjugate for cervical cancer reached patients. The cervical cancer treatment market covers surgery-related drugs, chemotherapy, radiation therapy, targeted therapy, and immunotherapy used to treat cancer of the cervix, which is mostly caused by persistent infection with high-risk human papillomavirus (HPV). Common drugs include cisplatin, paclitaxel, bevacizumab, pembrolizumab, tisotumab vedotin, and cadonilimab. Cervical cancer remains one of the most common cancers in women, with most deaths in lower-income countries. In June 2025, Akeso received approval in China for first-line use of cadonilimab.
Key Report Takeaways
- By Treatment: Chemotherapy held about 34% share in 2025, while Immunotherapy is projected to expand at an 11.5% CAGR through 2033, driven by checkpoint inhibitors approved with chemoradiotherapy and in first-line advanced disease, plus new bispecific antibodies.
- By Cancer Type: Squamous Cell Carcinoma held about 80% share in 2025, while Adenocarcinoma is projected to expand at a 6.8% CAGR through 2033, driven by rising detection, harder screening, and growing use of targeted and immune therapies.
- By End User: Hospitals and Clinics held about 75% share in 2025, while Ambulatory Surgery and Infusion Centres are projected to expand at a 7.0% CAGR through 2033, driven by outpatient drug infusions and lower-cost care settings.
- By Region: North America held about 40% share in 2025, while Asia Pacific is projected to expand at a 7.4% CAGR through 2033, driven by high disease burden, new approvals in China, and expanding cancer care in India.
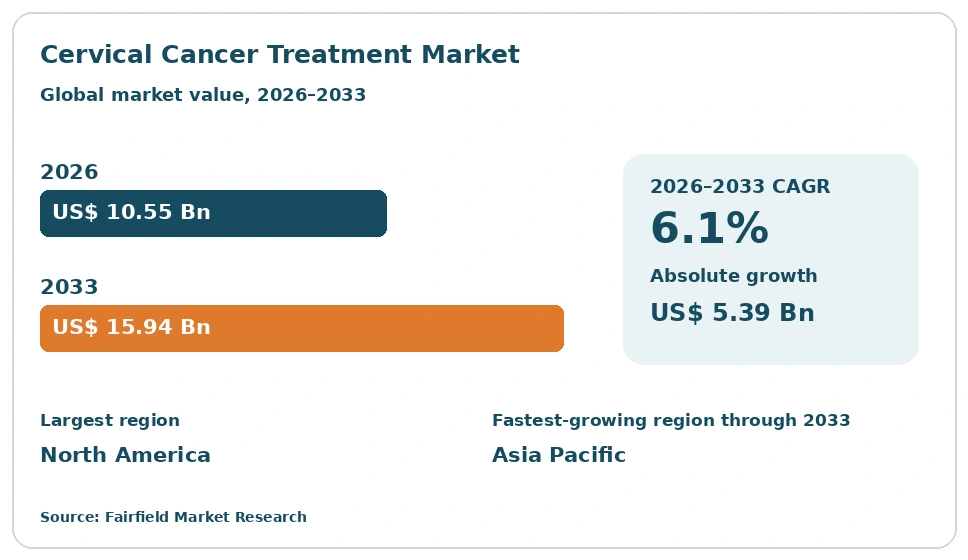
Global Cervical Cancer Treatment Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on cervical cancer treatment market demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Adoption of immunotherapy and antibody-drug conjugates | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
| High disease burden and better screening | Medium | Asia Pacific, Latin America, Middle East & Africa | Medium term (2-4 years) |
New Therapies Are Driving the Cervical Cancer Treatment Market
Adoption of immunotherapy and antibody-drug conjugates is the strongest driver of the cervical cancer treatment market. New drugs are changing how doctors treat advanced disease.
The mechanism is that newer medicines extend survival and are priced much higher than older chemotherapy. Merck & Co.’s Keytruda is approved with chemotherapy for first-line advanced cervical cancer and with chemoradiotherapy for high-risk locally advanced disease, bringing immunotherapy to earlier stages. Pfizer and Genmab’s Tivdak, a tissue factor-directed antibody-drug conjugate, received full approval for second-line use after improving survival. In China, Akeso’s bispecific cadonilimab and other domestic antibodies are approved. Each new approval adds treatment lines and longer therapy durations. Doctors now have more options after first-line treatment fails. These trends raise spending per patient.
Disease Burden and Screening Are Expanding the Cervical Cancer Treatment Market
High disease burden and better screening are expanding the cervical cancer treatment market. Many women still develop cervical cancer.
The cause is incomplete HPV vaccination and screening, especially in lower-income countries. Hundreds of thousands of women are diagnosed each year, with the largest numbers in India, China, Middle East & Africa, and Latin America. The World Health Organization strategy to eliminate cervical cancer is pushing countries to scale up screening and treatment, which identifies more patients who need care. Wider use of HPV testing finds more early cancers, which are treated with surgery, radiation, and chemotherapy, while improved access to cancer centres brings more advanced cases into treatment. Self-sampling tests also reach women who avoid clinic visits. These trends increase treated patient numbers across many regions.
Restraints Impact Analysis
Two restraints limit how quickly the cervical cancer treatment market grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| HPV vaccination reducing long-term incidence | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
| High drug costs and limited access | High | Asia Pacific, Latin America, Middle East & Africa | Medium term (2-4 years) |
HPV Vaccination Slows the Cervical Cancer Treatment Market
HPV vaccination reducing long-term incidence slows the cervical cancer treatment market. Prevention is working in many countries.
The problem for the market is that vaccines against HPV prevent most cervical cancers. Countries such as Australia, the United Kingdom, and Sweden that started vaccination programs early are already seeing large drops in cervical cancer among younger women, and Australia is on track to eliminate the disease as a public health problem. Single-dose vaccine schedules recommended by the World Health Organization make programs cheaper and easier to expand in more countries. Regular screening also removes pre-cancerous changes before they become cancer. Over time, these efforts will reduce the number of new patients in high-income markets. This trend limits volume growth in mature markets, although older women who were never vaccinated will still need care for many years.
High Costs Restrict the Cervical Cancer Treatment Market
High drug costs and limited access restrict the cervical cancer treatment market. Many patients cannot get modern treatment.
The constraint is that immunotherapies and antibody-drug conjugates cost tens of thousands of dollars per course in high-income countries, which most patients in lower-income countries cannot afford. Many hospitals in Middle East & Africa, Latin America, and parts of Asia Pacific lack radiation machines, trained gynecologic oncologists, and pathology services. Patients are often diagnosed late, when treatment is less effective. Public insurance programs may not cover newer drugs, and regulatory approvals can take years in some countries. Side effects, including eye toxicity with antibody-drug conjugates, also require careful monitoring. Travel distances to cancer centres also cause patients to miss treatment. These barriers limit market value where disease burden is highest.
Market Opportunities
Novel Biologics Open a Fast-Growth Revenue Pool
Novel biologics open a fast-growth revenue pool. Many new medicines are in development for cervical cancer.
The opportunity comes from bispecific antibodies, new checkpoint inhibitors, antibody-drug conjugates targeting proteins such as tissue factor and B7-H4, therapeutic HPV vaccines, and cell therapies such as tumor-infiltrating lymphocytes. Chinese companies such as Akeso, Gloria Biosciences, and Zai Lab are bringing new drugs to market quickly, while global companies are testing combinations in earlier disease. Biomarkers such as PD-L1 expression help match patients to the most suitable therapy. Several of these drugs are also being tested with radiation therapy. Companies that show clear survival benefits and win approvals in North America, Europe, and Asia Pacific can build strong positions in a growing treatment landscape.
Access Programs in Emerging Markets Create a Growth Revenue Pool
Access programs in emerging markets create a growth revenue pool. Most cervical cancer deaths occur in lower-income countries.
The opportunity reflects large unmet need in India, Indonesia, Nigeria, Kenya, South Africa, Brazil, and Mexico. Governments and global health groups are funding screening, radiation centres, and treatment programs to meet elimination goals. Lower-cost biosimilars of bevacizumab, generic chemotherapy, and tiered pricing for newer drugs can widen access. Pharmaceutical companies that partner with governments, local manufacturers, and nonprofit organizations can grow volumes while improving outcomes. Investments in radiotherapy equipment and training also expand treatment capacity. Mobile screening units and community health workers help bring patients into care earlier. These programs make emerging markets an important source of long-term growth for drug makers and equipment suppliers.
Segment Analysis
By Treatment: Chemotherapy Leads While Immunotherapy Grows Fastest
Chemotherapy held about 34% share in 2025. Cisplatin-based chemoradiotherapy is the standard treatment for locally advanced disease, and platinum and paclitaxel combinations remain the backbone of first-line treatment for advanced disease. Chemotherapy is widely available and affordable, which explains its large share in every region and treatment setting.
Immunotherapy is the fastest-growing treatment, expanding at an 11.5% CAGR through 2033. Checkpoint inhibitors such as pembrolizumab are now used with chemoradiotherapy and with first-line chemotherapy, and bispecific antibodies such as cadonilimab are approved in China. Radiation Therapy and Targeted Therapy, including bevacizumab and tisotumab vedotin, form other segments. For the market, immunotherapy growth raises value per patient and shifts spending toward branded biologics.
By Cancer Type: Squamous Cell Carcinoma Leads While Adenocarcinoma Grows Fastest
Squamous Cell Carcinoma held about 80% share in 2025. It starts in the thin flat cells lining the outer cervix and accounts for most cervical cancer cases, especially in countries with limited screening. Most treatment guidelines and clinical trials center on this type.
Adenocarcinoma is the fastest-growing cancer type, expanding at a 6.8% CAGR through 2033. It starts in glandular cells higher in the cervical canal and is harder to detect with standard cytology, so its share of cases has risen in screened populations. Improved HPV testing and targeted treatment support growth. Adenosquamous Carcinoma and other rare types form other segments. Survival rates can differ between types, which affects treatment choices. For the market, adenocarcinoma growth increases demand for tailored therapies.
By End User: Hospitals and Clinics Lead While Ambulatory Surgery and Infusion Centres Grow Fastest
Hospitals and Clinics held about 75% share in 2025. Cancer hospitals provide surgery, radiation therapy, chemotherapy, and immunotherapy in one place, along with diagnosis and supportive care, and most patients in every region are treated there, especially those needing combined surgery and radiation.
Ambulatory Surgery and Infusion Centres are the fastest-growing end user, expanding at a 7.0% CAGR through 2033. Outpatient centres give chemotherapy, immunotherapy, and antibody-drug conjugate infusions at lower cost and with more convenience, and payers in North America encourage this shift. Specialty Cancer Centres form another segment, offering advanced radiation and clinical trial access in major cities. For the market, outpatient growth supports wider use of infused biologics and more efficient care delivery.
Geography Analysis
Which Region Is Leading the Cervical Cancer Treatment Market?
North America is leading the cervical cancer treatment market with about 40% share in 2025. The United States has early access to new medicines, high drug prices, and broad insurance coverage, so patients receive immunotherapy and antibody-drug conjugates at high rates. Leading companies such as Merck & Co., Pfizer, and Bristol-Myers Squibb are based there, and many clinical trials run in the region. Canada adds demand through public cancer programs. Key barriers include declining incidence from vaccination and screening. Outpatient infusion centres are taking a larger share of treatment. One change shaping the region is the use of immunotherapy with chemoradiotherapy.
Europe Shapes the Cervical Cancer Treatment Market Through Prevention and Access
Europe is a major cervical cancer treatment market. Germany, France, Italy, Spain, and the United Kingdom have strong cancer care systems, and the European Medicines Agency has approved immunotherapy and antibody-drug conjugate treatments. Health technology assessment bodies control prices and access, which can delay uptake. Many countries have strong HPV vaccination and screening programs that are reducing new cases, while Poland, Romania, and other countries still have higher rates. Key barriers include price controls. Cancer networks share guidelines across borders. One opportunity is expanding access to new therapies in central and eastern member states.
Which Region Is Growing Fastest in the Cervical Cancer Treatment Market?
Asia Pacific is the fastest-growing cervical cancer treatment market, expanding at a 7.4% CAGR through 2033. China has a large number of new cases and has approved several domestic immunotherapies, including Akeso’s cadonilimab, while Zai Lab is launching Tivdak. India has one of the highest disease burdens in the world and is expanding cancer centres, screening, and its domestic HPV vaccine. Japan and South Korea have advanced cancer care, and Indonesia and Thailand are improving access. Key barriers include late diagnosis and affordability. One change shaping the region is fast approval of new drugs in China.
Latin America Grows the Cervical Cancer Treatment Market Through Expanding Cancer Care
Latin America is a growing cervical cancer treatment market. Brazil, Mexico, Colombia, Argentina, and Peru have high cervical cancer rates and are expanding public cancer programs, radiation capacity, and HPV vaccination. Private hospitals in large cities offer immunotherapy and newer drugs. Biosimilars help lower costs for public health systems. Key barriers include late diagnosis, limited radiation machines outside major cities, and budget constraints. Regional cancer institutes in Mexico and Brazil lead clinical research. Many women still face long waits for radiation therapy. One opportunity is tiered pricing and partnerships that make newer medicines available in public hospitals.
Middle East & Africa Builds the Cervical Cancer Treatment Market Through Elimination Programs
Middle East & Africa is an emerging cervical cancer treatment market with very high disease burden in many countries. South Africa, Nigeria, Kenya, Tanzania, and Ethiopia have some of the world’s highest cervical cancer death rates, and global health groups are funding screening, vaccination, and treatment. Saudi Arabia and the United Arab Emirates have modern cancer centres offering newer therapies. Key barriers include few radiotherapy machines, late diagnosis, and limited funding. Egypt and Morocco are also expanding cancer centres. Many countries rely on donated equipment and international training. One opportunity is affordable treatment programs linked to elimination goals.
Competitive Landscape
The cervical cancer treatment market is moderately consolidated. Merck & Co., Pfizer, Roche, Genmab, and Akeso are leading players, while Bristol-Myers Squibb, AstraZeneca, Zai Lab, GSK, Eli Lilly and Company, Johnson & Johnson, and Novartis compete strongly. A small number of branded medicines, especially Keytruda, Tivdak, and bevacizumab, account for a large share of spending in high-income markets. Generic chemotherapy and biosimilar makers supply much of the volume in Asia Pacific, Latin America, and Middle East & Africa.
Companies compete on survival benefit, safety, approved lines of therapy, biomarker strategy, price, and access programs. Clinical trial results drive guideline recommendations, which strongly influence prescribing. Chinese biotech companies are competing with fast development, lower prices, and new drug classes such as bispecific antibodies. Global companies rely on partnerships to reach patients in China and other emerging markets.
Strategic moves show how competition is changing. In April 2024, Pfizer and Genmab won full FDA approval for Tivdak. In June 2025, Akeso won approval for first-line cadonilimab in China. In June 2026, Zai Lab received approval to launch Tivdak in China. These moves show competition shifting toward immunotherapy and antibody-drug conjugates and rapid growth of the Chinese market.
Three themes shape vendor strategy. First, companies are moving immunotherapy into earlier stages of disease. Second, they are developing new antibody-drug conjugates, bispecific antibodies, and therapeutic vaccines. Third, they are expanding access in Asia Pacific, Latin America, and Middle East & Africa through partnerships, tiered pricing, and biosimilars.
Cervical Cancer Treatment Market Industry Leaders
- Merck & Co.
- Pfizer
- Roche
- Genmab
- Akeso
Recent Industry Developments
- June 2026: Zai Lab received approval from the National Medical Products Administration in China for Tivdak in recurrent or metastatic cervical cancer after chemotherapy - expands antibody-drug conjugate access in the cervical cancer treatment market.
- June 2025: Akeso received approval in China for cadonilimab with platinum chemotherapy as first-line treatment for persistent, recurrent, or metastatic cervical cancer - adds a bispecific immunotherapy option.
- April 2024: Pfizer and Genmab received full FDA approval for Tivdak in recurrent or metastatic cervical cancer after chemotherapy, based on improved survival - confirms antibody-drug conjugates in second-line care.
- January 2024: Merck & Co. received FDA approval for Keytruda with chemoradiotherapy in stage III to IVA cervical cancer - moves immunotherapy into earlier disease.
Companies Covered in the Report
- Merck & Co.
- Pfizer
- Roche
- Genmab
- Akeso
- Bristol-Myers Squibb
- AstraZeneca
- Zai Lab
- GSK
- Eli Lilly and Company
- Johnson & Johnson
- Novartis
Cervical Cancer Treatment Market Report Scope
This report covers the cervical cancer treatment market, including chemotherapy, radiation therapy, targeted therapy, and immunotherapy, for squamous cell carcinoma, adenocarcinoma, and adenosquamous carcinoma, used in hospitals and clinics, ambulatory surgery and infusion centres, and specialty cancer centres. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
| Treatment | Chemotherapy, Radiation Therapy, Targeted Therapy, Immunotherapy |
| Cancer Type | Squamous Cell Carcinoma, Adenocarcinoma, Adenosquamous Carcinoma, Others |
| End User | Hospitals and Clinics, Ambulatory Surgery and Infusion Centres, Specialty Cancer Centres |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
1. Executive Summary
1.1 Cervical Cancer Treatment Market Snapshot
1.2 Future Projections
1.3 Key Market Trends
1.4 Regional Snapshot
2. Market Overview
2.1 Market Definition and Report Scope
2.2 Historical Market Trends
2.3 Market Dynamics
2.3.1 Drivers
2.3.1.1 New Therapies Are Driving the Cervical Cancer Treatment Market
2.3.1.2 Disease Burden and Screening Are Expanding the Cervical Cancer Treatment Market
2.3.2 Restraints
2.3.2.1 HPV Vaccination Slows the Cervical Cancer Treatment Market
2.3.2.2 High Costs Restrict the Cervical Cancer Treatment Market
2.3.3 Market Opportunities
2.3.3.1 Novel Biologics Open a Fast-Growth Revenue Pool
2.3.3.2 Access Programs in Emerging Markets Create a Growth Revenue Pool
3. Global Cervical Cancer Treatment Market Outlook, 2020–2033
3.1 Global Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
3.1.1 Chemotherapy
3.1.2 Radiation Therapy
3.1.3 Targeted Therapy
3.1.4 Immunotherapy
3.2 Global Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
3.2.1 Squamous Cell Carcinoma
3.2.2 Adenocarcinoma
3.2.3 Adenosquamous Carcinoma
3.2.4 Others
3.3 Global Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
3.3.1 Hospitals and Clinics
3.3.2 Ambulatory Surgery and Infusion Centres
3.3.3 Specialty Cancer Centres
3.4 Global Cervical Cancer Treatment Market Outlook, by Region, Value (US$ Billion), 2020–2033
3.4.1 North America
3.4.2 Europe
3.4.3 Asia Pacific
3.4.4 Latin America
3.4.5 Middle East & Africa
4. North America Cervical Cancer Treatment Market Outlook, 2020–2033
4.1 North America Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
4.1.1 Chemotherapy
4.1.2 Radiation Therapy
4.1.3 Targeted Therapy
4.1.4 Immunotherapy
4.2 North America Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
4.2.1 Squamous Cell Carcinoma
4.2.2 Adenocarcinoma
4.2.3 Adenosquamous Carcinoma
4.2.4 Others
4.3 North America Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
4.3.1 Hospitals and Clinics
4.3.2 Ambulatory Surgery and Infusion Centres
4.3.3 Specialty Cancer Centres
4.4 North America Cervical Cancer Treatment Market Outlook, by Country, Value (US$ Billion), 2020–2033
4.4.1 United States Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
4.4.2 United States Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
4.4.3 United States Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
4.4.4 Canada Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
4.4.5 Canada Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
4.4.6 Canada Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5. Europe Cervical Cancer Treatment Market Outlook, 2020–2033
5.1 Europe Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
5.1.1 Chemotherapy
5.1.2 Radiation Therapy
5.1.3 Targeted Therapy
5.1.4 Immunotherapy
5.2 Europe Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
5.2.1 Squamous Cell Carcinoma
5.2.2 Adenocarcinoma
5.2.3 Adenosquamous Carcinoma
5.2.4 Others
5.3 Europe Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
5.3.1 Hospitals and Clinics
5.3.2 Ambulatory Surgery and Infusion Centres
5.3.3 Specialty Cancer Centres
5.4 Europe Cervical Cancer Treatment Market Outlook, by Country, Value (US$ Billion), 2020–2033
5.4.1 Germany Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.2 Germany Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.3 Germany Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.4 France Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.5 France Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.6 France Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.7 Italy Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.8 Italy Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.9 Italy Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.10 Spain Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.11 Spain Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.12 Spain Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.13 United Kingdom Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.14 United Kingdom Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.15 United Kingdom Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.16 Poland Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.17 Poland Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.18 Poland Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
5.4.19 Romania Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
5.4.20 Romania Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
5.4.21 Romania Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6. Asia Pacific Cervical Cancer Treatment Market Outlook, 2020–2033
6.1 Asia Pacific Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
6.1.1 Chemotherapy
6.1.2 Radiation Therapy
6.1.3 Targeted Therapy
6.1.4 Immunotherapy
6.2 Asia Pacific Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
6.2.1 Squamous Cell Carcinoma
6.2.2 Adenocarcinoma
6.2.3 Adenosquamous Carcinoma
6.2.4 Others
6.3 Asia Pacific Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
6.3.1 Hospitals and Clinics
6.3.2 Ambulatory Surgery and Infusion Centres
6.3.3 Specialty Cancer Centres
6.4 Asia Pacific Cervical Cancer Treatment Market Outlook, by Country, Value (US$ Billion), 2020–2033
6.4.1 China Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.2 China Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.3 China Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6.4.4 India Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.5 India Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.6 India Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6.4.7 Japan Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.8 Japan Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.9 Japan Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6.4.10 South Korea Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.11 South Korea Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.12 South Korea Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6.4.13 Indonesia Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.14 Indonesia Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.15 Indonesia Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
6.4.16 Thailand Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
6.4.17 Thailand Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
6.4.18 Thailand Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
7. Latin America Cervical Cancer Treatment Market Outlook, 2020–2033
7.1 Latin America Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
7.1.1 Chemotherapy
7.1.2 Radiation Therapy
7.1.3 Targeted Therapy
7.1.4 Immunotherapy
7.2 Latin America Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
7.2.1 Squamous Cell Carcinoma
7.2.2 Adenocarcinoma
7.2.3 Adenosquamous Carcinoma
7.2.4 Others
7.3 Latin America Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
7.3.1 Hospitals and Clinics
7.3.2 Ambulatory Surgery and Infusion Centres
7.3.3 Specialty Cancer Centres
7.4 Latin America Cervical Cancer Treatment Market Outlook, by Country, Value (US$ Billion), 2020–2033
7.4.1 Brazil Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
7.4.2 Brazil Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
7.4.3 Brazil Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
7.4.4 Mexico Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
7.4.5 Mexico Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
7.4.6 Mexico Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
7.4.7 Colombia Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
7.4.8 Colombia Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
7.4.9 Colombia Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
7.4.10 Argentina Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
7.4.11 Argentina Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
7.4.12 Argentina Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
7.4.13 Peru Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
7.4.14 Peru Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
7.4.15 Peru Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8. Middle East & Africa Cervical Cancer Treatment Market Outlook, 2020–2033
8.1 Middle East & Africa Cervical Cancer Treatment Market Outlook, by Treatment, Value (US$ Billion), 2020–2033
8.1.1 Chemotherapy
8.1.2 Radiation Therapy
8.1.3 Targeted Therapy
8.1.4 Immunotherapy
8.2 Middle East & Africa Cervical Cancer Treatment Market Outlook, by Cancer Type, Value (US$ Billion), 2020–2033
8.2.1 Squamous Cell Carcinoma
8.2.2 Adenocarcinoma
8.2.3 Adenosquamous Carcinoma
8.2.4 Others
8.3 Middle East & Africa Cervical Cancer Treatment Market Outlook, by End User, Value (US$ Billion), 2020–2033
8.3.1 Hospitals and Clinics
8.3.2 Ambulatory Surgery and Infusion Centres
8.3.3 Specialty Cancer Centres
8.4 Middle East & Africa Cervical Cancer Treatment Market Outlook, by Country, Value (US$ Billion), 2020–2033
8.4.1 South Africa Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.2 South Africa Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.3 South Africa Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.4 Nigeria Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.5 Nigeria Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.6 Nigeria Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.7 Kenya Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.8 Kenya Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.9 Kenya Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.10 Ethiopia Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.11 Ethiopia Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.12 Ethiopia Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.13 Saudi Arabia Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.14 Saudi Arabia Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.15 Saudi Arabia Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.16 United Arab Emirates Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.17 United Arab Emirates Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.18 United Arab Emirates Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.19 Egypt Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.20 Egypt Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.21 Egypt Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
8.4.22 Morocco Cervical Cancer Treatment Market Outlook, by Treatment, 2020–2033
8.4.23 Morocco Cervical Cancer Treatment Market Outlook, by Cancer Type, 2020–2033
8.4.24 Morocco Cervical Cancer Treatment Market Outlook, by End User, 2020–2033
9. Competitive Landscape
9.1 Cervical Cancer Treatment Market Industry Leaders
9.2 Recent Industry Developments
9.3 Company Profiles
9.3.1 Merck & Co.
9.3.2 Pfizer
9.3.3 Roche
9.3.4 Genmab
9.3.5 Akeso
9.3.6 Bristol-Myers Squibb
9.3.7 AstraZeneca
9.3.8 Zai Lab
9.3.9 GSK
9.3.10 Eli Lilly and Company
9.3.11 Johnson & Johnson
9.3.12 Novartis
10. Appendix
10.1 Research Methodology
10.2 Report Assumptions
10.3 Acronyms and Abbreviations
| Treatment | Chemotherapy, Radiation Therapy, Targeted Therapy, Immunotherapy |
| Cancer Type | Squamous Cell Carcinoma, Adenocarcinoma, Adenosquamous Carcinoma, Others |
| End User | Hospitals and Clinics, Ambulatory Surgery and Infusion Centres, Specialty Cancer Centres |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The cervical cancer treatment market is valued at US$ 10.55 billion in 2026, led by chemotherapy, hospitals, and North America.
The market is projected to reach US$ 15.94 billion by 2033, growing at a 6.1% CAGR and adding US$ 5.39 billion.
Immunotherapy is growing fastest at an 11.5% CAGR through 2033, driven by checkpoint inhibitors in earlier disease and new bispecific antibodies.
Asia Pacific is growing fastest at a 7.4% CAGR through 2033, driven by high disease burden and new drug approvals in China.
North America holds the largest share at about 40% in 2025, supported by early drug access, high prices, and insurance coverage.
Related Reports
Asthma Treatment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the asthma treatment market outlook for 2026–2033, covering drug classes, devices, distribution channels, patient segments, and regions.
Aesthetic Medicine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the aesthetic medicine market outlook for 2026–2033, covering products, patient groups, end users, regional trends, and leading companies.
Kidney Dialysis Centres Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the kidney dialysis centres market outlook for 2026–2033, covering dialysis types, service settings, centre types, regions, and key companies.
Gout Therapeutic Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global gout therapeutic market is valued at US$2.9 billion in 2026, reaching US$4.7 billion by 2033, growing at a 7.1% CAGR
Small Molecule API Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the small molecule API market outlook for 2026–2033, including synthesis, manufacturing, therapeutic applications, regions, and competitors.
Medical Marijuana Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the medical marijuana market outlook for 2026–2033, including product forms, distribution channels, regional trends, and competitive insights.