


Clinical Nutrition Market
Clinical Nutrition Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Clinical Nutrition Market Size and Trend Analysis
What supports growth in clinical nutrition spending?
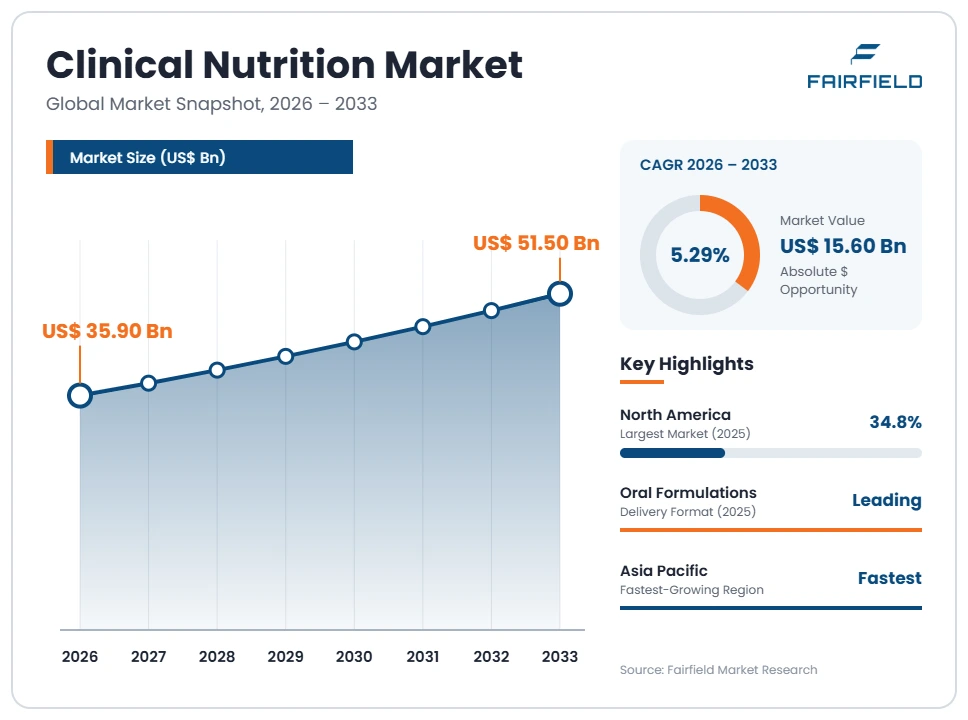
The global Clinical Nutrition market size is expected to be valued at US$35.90 billion in 2026 and projected to reach US$51.50 billion by 2033, growing at a CAGR of 5.29% between 2026 and 2033. The outlook concerns nutritional products used in clinical care, including oral supplements, tube-feeding formulations, and parenteral nutrition. Comparisons require consistent product boundaries and recognition of differences between hospital purchasing and continuing use outside institutions.
During 2020–2025, manufacturers developed specialized formulations and extended their medical nutrition portfolios. A comparable historical CAGR is unavailable; the selected benchmark places 2025 revenue at US$34.00 billion. Identified nutritional needs, product development, and continuity between care settings support the outlook. Access, purchasing arrangements, and manufacturing reliability affect realized sales. Product availability alone does not establish clinical suitability or reimbursement, and the forecast should not be interpreted as a prediction of patient outcomes or automatic access across countries.
Key Report Takeaways
- By Delivery Format: Oral Formulations, Tube-Feeding Formulations, and Parenteral Formulations distinguish the intended administration route. Oral nutrition led the benchmark in 2025, while parenteral nutrition has its fastest-growth direction. These historical and forecast findings should not be presented as current independent category shares.
- By Care Destination: Institutional Care and Community Care separate the destination of the purchased product. Comparable shares and growth rankings are unavailable for this allocation. Discharge arrangements, product availability, and recurring purchasing influence the commercial relationship beyond the first institutional order.
- By Purchase Arrangement: Contracted Supply and Noncontract Purchasing distinguish transactions governed by standing supply agreements from other purchases. Verified global segment rankings are unavailable. Suppliers should assess account retention, order predictability, and payment conditions separately from the patient’s location or formulation route.
- By Geography: North America represented 34.8% of the selected benchmark in 2025; Asia Pacific has its fastest-growth direction. Local access and product portfolios vary. Regional expansion should be assessed through country-specific distribution and purchasing arrangements rather than a uniform global commercialization assumption.
- By Competition: Abbott, Danone, Nestlé Health Science, Fresenius Kabi, and Baxter document relevant products or manufacturing capabilities. Medium concentration is an analyst assessment of established suppliers alongside specialized portfolios. Total company revenues cannot establish comparable clinical nutrition market shares.
Global Clinical Nutrition Market Trends and Insights
Drivers Impact Analysis
Ratings express analyst judgement about commercial mechanisms rather than a measured contribution to the forecast CAGR.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Documented nutritional needs within care pathways | High | Established and expanding care networks | Medium term (2–4 years) |
| Formulation and packaging development | Medium | Markets with accessible approved portfolios | Short term (≤2 years) |
Clinical Nutrition Demand Depends on Recognized Care Requirements
Clinical nutrition spending becomes commercially addressable when a care pathway identifies a nutritional requirement and connects it with accessible products. Population characteristics alone do not determine purchases. Product selection, availability, payment, and continuing supply intervene between a potential need and recognized revenue. Suppliers therefore benefit from understanding the institution or community service responsible for procurement. The business question is whether products reach intended settings reliably, with appropriate information and accountable distribution.
Verified portfolios from Abbott and Baxter establish participation across different nutritional product types. They do not imply that oral supplements and intravenous formulations are interchangeable. Manufacturers should segment accounts according to actual purchasing responsibilities and portfolio fit. A hospital tender, pharmacy order, and recurring community delivery can require different commercial capabilities. Forecast demand consequently needs to reflect practical access and product boundaries rather than count every person with a relevant condition as a confirmed customer.
Clinical Nutrition Formats Expand Beyond a Single Institutional Package
Formulation and packaging development can broaden commercially practical ways to supply nutrition within an established care plan. Customers may need different textures, volumes, or handling formats, while purchasers need products that fit storage and distribution arrangements. A new presentation creates an opportunity only where its intended use and local availability align. Manufacturers should evaluate commercial fit alongside production complexity, inventory requirements, and support for professional and community customers.
Nestlé Health Science introduced Compleat Paediatric Oral Blends in a pouch format, illustrating development for children with specialized medical nutrition needs. The announcement establishes a product introduction, without proving superiority or universal acceptance. For business planning, the relevant mechanism is a broader choice of presentation within a defined portfolio. Suppliers need evidence appropriate to their product and clear local communication. Additional variants should serve an identifiable requirement rather than multiply stock-keeping units without dependable demand.
Restraints Impact Analysis
Purchasing access and production requirements can restrict conversion of potential need into sustained product revenue.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Fragmented payment and purchasing access | High | Markets with divided payer responsibilities | Medium term (2–4 years) |
| Specialized manufacturing and portfolio complexity | Medium | Global production and distribution networks | Long term (≥4 years) |
Clinical Nutrition Access Gaps Limit Repeatable Commercial Demand
Payment and purchasing arrangements can constrain clinical nutrition sales even when a product has an identifiable role. An institutional contract may not cover continued use after discharge, while community access may involve another distributor or payer. Suppliers need to understand these boundaries before estimating account lifetime value. Initial orders do not establish recurring revenue, and population statistics cannot resolve affordability or availability. The commercial limitation is the gap between a stated requirement and a dependable purchasing route.
The underlying costs can include distributor margins, delivery to dispersed customers, administrative work, and inventory held across multiple channels. These expenses differ from manufacturing cost. Manufacturers should test their assumptions against actual customer purchasing conditions and avoid treating every channel as equally accessible. Clear ordering information and reliable supply may improve execution, but they do not themselves establish payment entitlement. Country-level analysis is preferable to a global access assumption.
Clinical Nutrition Manufacturing Complexity Restricts Easy Portfolio Expansion
Specialized production requirements can limit the pace at which manufacturers add clinical nutrition variants or enter another market. Ingredient control, packaging suitability, quality assurance, and documented processes create costs before commercial scale is established. More product choices can also split demand across smaller production runs. Suppliers should consider economics and reliability together. A broad catalogue is less useful when scheduling, availability, or information fails to support customer accounts.
The principal cost sources include process qualification, laboratory work, packaging changes, batch management, and product-specific inventory. Oral products, tube-feeding formulas, and parenteral nutrition should not be assumed to share identical manufacturing requirements. Danone’s documented investment in medical nutrition production illustrates the importance of industrial capacity, without establishing the economics of every competing plant. Companies can prioritize variants with a clear customer purpose and manageable operational demands. Expansion plans need enough volume and distribution support to justify this additional complexity.
Market Opportunities
Emerging revenue pools concern better-defined customer access and product formats rather than a general claim that all nutrition spending will grow.
Clinical Nutrition Community Supply Creates Continuity Opportunities
Community supply offers an opportunity where a product remains part of a care plan outside the purchasing institution. The potential revenue pool concerns accessible formulations, dependable replenishment, and appropriate commercial support for the responsible customer. It should not automatically include unrelated homecare services or every item used after discharge. Manufacturers and distributors can develop clearer propositions by identifying who orders, who pays, and which information must accompany transactions across care settings.
Suppliers with relevant oral or tube-feeding portfolios can assess these arrangements together with qualified local partners. The opportunity is strongest where recurring demand and the distribution route are established rather than assumed. Product information, delivery reliability, and manageable packaging can support service execution. Clinical decisions remain with the responsible professionals; commercial analysis should not prescribe treatment. Revenue forecasts should distinguish product sales from separate support fees and avoid counting the same product again at each distribution stage.
Clinical Nutrition Specialized Formats Offer Focused Portfolio Revenue
Specialized formats offer opportunities for manufacturers addressing a defined requirement within the wider nutrition category. Different presentation, ingredient, or handling preferences may justify a focused extension within an existing product family. The prospective revenue pool is the additional product business that these requirements support, after considering substitution within the portfolio. A launch can redistribute existing sales as well as attract new demand, making incremental contribution more informative than catalogue size alone.
Nestlé Health Science’s pediatric pouch introduction and Fresenius Kabi’s expanded enteral nutrition research facilities provide examples of product and development activity. Neither announcement guarantees commercial scale in every country. Suppliers can capture opportunities through a documented product purpose, feasible production, and an accessible route to customers. Institutional purchasers and community channels may value different formats, so local validation matters. Expansion plans connect product development with supply conditions and avoid unsupported clinical promises.
Segment Analysis
- By Delivery Format: Clinical Nutrition Routes Require Separate Product Economics
Oral Formulations led the selected benchmark in 2025, while Parenteral Formulations have its fastest-growth direction. A comparable 2026 share for this independent allocation is unavailable. Tube-Feeding Formulations complete the route-based category. Products intended for multiple routes should be allocated by the specified transaction or intended use, preventing duplicate revenue assignment. Route is a product characteristic, not a recommendation that one method should replace another.
The commercial mechanisms differ across oral nutritional supplements, enteral feeding, and parenteral nutrition. Packaging, purchasing responsibility, and manufacturing capabilities can affect account economics. Baxter documents parenteral products, while Nestlé Health Science documents oral and tube-feeding portfolios. These examples verify participation without assigning supplier rankings. For strategy teams, the useful comparison is revenue and margin within a clearly defined route, alongside customer access. Broad company nutrition sales should not automatically be allocated to every clinical route or counted as directly comparable product revenue.
- By Care Destination: Clinical Nutrition Supply Extends Across Care Settings
Institutional Care and Community Care distinguish where purchased products are intended to be used. Institutional Care includes hospitals and other organized care facilities; Community Care covers use outside those facilities. Comparable global shares and fastest-growth rankings are unavailable for this independent category. Classification follows the destination of the product, rather than whether an order happened online or through a distributor. This keeps the category separate from sales channel and purchasing contract.
A supplier serving hospital procurement may need another commercial arrangement for continuing community demand. Order sizes, replenishment, and delivery responsibilities can change, even when the underlying product family remains relevant. Medical nutrition suppliers should therefore map the handover between accounts and identify any access gap. The business implication is to assess availability and recurring purchasing separately. Community demand is a prospective commercial pool, but population counts or discharge volumes alone cannot establish product revenue without an accessible route to the customer.
- By Purchase Arrangement: Clinical Nutrition Contracts Shape Account Predictability
Contracted Supply and Noncontract Purchasing separate transactions under standing supply agreements from purchases without those agreements. Comparable segment shares, leadership, and forecast growth rankings are unavailable. Contracted Supply can support account planning where agreed terms define product access and ordering responsibilities. Noncontract Purchasing can cover varied customer requirements, but it should not automatically be characterized as smaller, less profitable, or faster growing. The relevant distinction is the transaction’s governing arrangement.
Manufacturers need to assess contract duration, product commitments, service expectations, and payment conditions before attributing predictable revenue to an account. A broad framework agreement may still leave actual volumes uncertain. Noncontract orders can be recurring without a standing commitment. For management, this category helps distinguish order visibility from product suitability and care destination. It also supports more realistic forecasts: an institutional customer can use either arrangement, and a community distribution partner may operate under a supply contract. Customer location therefore cannot substitute for evidence about purchasing terms.
Geography Analysis
- Which Region Is Leading the Clinical Nutrition Market?
North America led the selected benchmark, representing 34.8% of global revenue in 2025. This historical figure is not a verified 2026 share. The United States and Canada offer distinct customer and payment environments, requiring local account analysis. Established supplier portfolios provide commercial access points, but product availability and purchasing responsibility still need verification within each setting.
Regional strategy should connect institutional supply with accessible community purchasing rather than assume an order follows the patient automatically. A relevant opportunity lies in reliable replenishment and clearly defined product information across these settings. The main execution question is whether the manufacturer and its distribution partners can maintain supply under local purchasing conditions. Large aggregate spending does not remove account-specific access or profitability constraints.
- Europe: Clinical Nutrition Capacity Supports Portfolio Development
Europe offers documented manufacturing and product development activity, without a verified regional share in this report. France, Germany, the United Kingdom, and the Netherlands provide useful country markets for account assessment. Danone’s Steenvoorde production expansion establishes an investment in oral nutritional supplement capacity. It does not establish a uniform growth rate across European countries or imply that all additional capacity is already reflected in customer purchases.
Suppliers should assess institutional procurement, community availability, and language requirements at the country level. Portfolio breadth may help address varied customer needs, while additional product references create inventory complexity. An opportunity lies in coordinating manufacturing capabilities with realistic local demand. Buyers can evaluate supply continuity and the available presentation range alongside commercial terms, keeping product-specific evidence separate from broad brand recognition.
- Which Region Is Growing Fastest in the Clinical Nutrition Market?
Asia Pacific has the fastest-growth direction in the selected outlook. A comparable country ranking or regional CAGR is not used here. China, India, Japan, and Australia present different purchasing and distribution conditions. Fresenius Kabi’s expanded research center in Gurugram demonstrates investment in enteral nutrition development, rather than proof of identical product access throughout the region.
Commercial opportunities depend on local portfolio availability, customer affordability, and dependable supply arrangements. Manufacturers can assess whether institutional relationships support continuing demand outside hospitals and other facilities. Research capacity can support product development, but country entry still requires appropriate local execution. The business implication is to build country-level plans around accessible accounts and relevant product requirements. A regional growth forecast should not substitute for confirmed distribution, purchasing terms, or product-specific readiness.
- Latin America: Clinical Nutrition Access Depends on Distribution Economics
Latin America requires a practical assessment of distribution and purchasing conditions rather than a single regional assumption. Brazil, Mexico, and Argentina provide distinct markets for institutional and community account development. Comparable regional size, share, and growth figures are unavailable in the selected evidence. The opportunity concerns appropriately positioned nutritional products supported by dependable availability and a commercial route that customers can sustain.
Potential barriers include affordability, payment delays, imported-product costs, and delivery across dispersed accounts. Their importance should be established locally rather than assumed uniform. Suppliers can prioritize portfolios and partners that fit the intended customer setting. Account profitability needs to include inventory and distribution expenses, not simply the ex-factory price. A focused route to market may therefore be more useful than immediately introducing the entire global portfolio.
- Middle East & Africa: Clinical Nutrition Expansion Requires Selective Account Coverage
Middle East & Africa should be evaluated through specific national and customer markets. Saudi Arabia, the United Arab Emirates, and South Africa provide starting points for commercial assessment, without a verified ranking in this report. Institutional purchasing and community availability can create different requirements. An opportunity exists where a supplier can establish dependable access to relevant formulations through capable local distribution and clear account responsibilities.
The principal barriers can include affordability, import logistics, uneven customer coverage, and the cost of holding appropriate stock. These considerations require local evidence. Manufacturers should connect portfolio decisions with supply feasibility and the intended purchasing arrangement. Product availability in one country does not establish regional authorization or a uniform care pathway. Selective account development can support a more realistic expansion plan.
Competitive Landscape
Medium concentration is an analyst judgement reflecting established multinational suppliers alongside specialized product portfolios. It is not a calculated concentration ratio. Abbott, Danone, Nestlé Health Science, Fresenius Kabi, and Baxter verify direct participation through products, development capabilities, or manufacturing activity. Their portfolios differ, making company revenue an unsuitable basis for comparable clinical nutrition shares. Competitive assessment should define the product route, geography, and customer account before comparing commercial positions.
Competition concerns portfolio relevance, product evidence, manufacturing reliability, and customer access. A new entrant may identify a focused product requirement, but it also needs feasible production and an effective purchasing route. Established suppliers must manage the same practical issues when extending a portfolio. Additional formulations or packages can help address customer requirements while also increasing inventory and operating complexity. Buyers therefore need product-specific information rather than assume brand breadth establishes suitability across all uses.
Recent activity illustrates different investment priorities. Expanded research facilities concern development capability; a product introduction concerns a defined commercial presentation; production expansion concerns industrial capacity. None alone establishes a change in market share. Strategy teams should evaluate how these moves connect to accessible accounts, sustainable supply, and incremental product demand. An announced launch schedule or plant capability should not automatically be converted into realized revenue.
The strategic direction is toward clearly positioned portfolios supported by reliable supply across relevant care destinations. Companies can improve account planning by separating formulation route, product destination, and purchasing arrangement. This also makes commercial performance easier to interpret when distribution changes. Management should track repeat orders, portfolio contribution, and the cost to serve, while keeping clinical claims within the evidence for each product. No supplier ranking is assigned.
Recent Industry Developments
- June 2025: Fresenius Kabi opened its expanded enteral nutrition research center in Gurugram, India, strengthening product development capabilities within its research network.
- March 2026: Nestlé Health Science announced Compleat Paediatric Oral Blends, with initial European launches scheduled for March and April, adding a pediatric medical nutrition pouch presentation.
- September 2026: Danone inaugurated a medical nutrition production line in Steenvoorde, France, expanding capacity for its Fortimel range and associated product presentations.
Companies Covered in the Report
Abbott, Danone, Nestlé Health Science, Fresenius Kabi, Baxter.
Clinical Nutrition Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$35.90 Billion |
| Market Size 2033 | US$51.50 Billion |
| CAGR 2026–2033 | 5.29% |
| Absolute Dollar Opportunity | US$15.60 Billion |
| Largest Market | North America, 2025 benchmark leadership |
| Fastest-Growing Market | Asia Pacific, selected outlook |
| Market Concentration | Medium overall, analyst judgement |
| Major Players | Abbott, Danone, Nestlé Health Science, Fresenius Kabi, Baxter |
Clinical Nutrition Market Segmentation
Delivery Format
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
Care Destination
- Institutional Care
- Community Care
Purchase Arrangement
- Contracted Supply
- Noncontract Purchasing
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Clinical Nutrition Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Clinical Nutrition Demand Depends on Recognized Care Requirements
- Clinical Nutrition Formats Expand Beyond a Single Institutional Package
- Restraints
- Clinical Nutrition Access Gaps Limit Repeatable Commercial Demand
- Clinical Nutrition Manufacturing Complexity Restricts Easy Portfolio Expansion
- Market Opportunities
- Clinical Nutrition Community Supply Creates Continuity Opportunities
- Clinical Nutrition Specialized Formats Offer Focused Portfolio Revenue
- Drivers
- Global Clinical Nutrition Market Outlook, 2020–2033
- Global Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- Global Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- Global Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- Global Clinical Nutrition Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- North America Clinical Nutrition Market Outlook, 2020–2033
- North America Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- North America Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- North America Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- North America Clinical Nutrition Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- United States Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- United States Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Canada Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Canada Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Canada Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- North America Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Europe Clinical Nutrition Market Outlook, 2020–2033
- Europe Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- Europe Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- Europe Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- Europe Clinical Nutrition Market Outlook, by Country, Value (US$ Billion), 2020–2033
- France Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- France Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- France Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Germany Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Germany Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Germany Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- United Kingdom Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- United Kingdom Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- United Kingdom Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Netherlands Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Netherlands Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Netherlands Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Europe Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Asia Pacific Clinical Nutrition Market Outlook, 2020–2033
- Asia Pacific Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- Asia Pacific Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- Asia Pacific Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- Asia Pacific Clinical Nutrition Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- China Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- China Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- India Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- India Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- India Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Japan Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Japan Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Japan Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Australia Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Australia Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Australia Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Asia Pacific Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Latin America Clinical Nutrition Market Outlook, 2020–2033
- Latin America Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- Latin America Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- Latin America Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- Latin America Clinical Nutrition Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Brazil Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Brazil Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Mexico Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Mexico Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Mexico Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Argentina Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Argentina Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Argentina Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Latin America Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Middle East & Africa Clinical Nutrition Market Outlook, 2020–2033
- Middle East & Africa Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
- Middle East & Africa Clinical Nutrition Market Outlook, by Care Destination, Value (US$ Billion), 2020–2033
- Institutional Care
- Community Care
- Middle East & Africa Clinical Nutrition Market Outlook, by Purchase Arrangement, Value (US$ Billion), 2020–2033
- Contracted Supply
- Noncontract Purchasing
- Middle East & Africa Clinical Nutrition Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- Saudi Arabia Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- Saudi Arabia Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- United Arab Emirates Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- United Arab Emirates Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- United Arab Emirates Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- South Africa Clinical Nutrition Market Outlook, by Delivery Format, 2020–2033
- South Africa Clinical Nutrition Market Outlook, by Care Destination, 2020–2033
- South Africa Clinical Nutrition Market Outlook, by Purchase Arrangement, 2020–2033
- Middle East & Africa Clinical Nutrition Market Outlook, by Delivery Format, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Abbott
- Danone
- Nestlé Health Science
- Fresenius Kabi
- Baxter
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Delivery Format
- Oral Formulations
- Tube-Feeding Formulations
- Parenteral Formulations
Care Destination
- Institutional Care
- Community Care
Purchase Arrangement
- Contracted Supply
- Noncontract Purchasing
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Clinical Nutrition Market is valued at US$35.90 billion in 2026, covering nutritional formulations used within the report’s defined clinical care boundaries.
The market is projected to reach US$51.50 billion by 2033, with 5.29% CAGR calculated from the selected 2026 and 2033 endpoints.
Oral nutrition led the selected 2025 benchmark; comparable 2026 shares are unavailable for the report’s independently defined Delivery Format category allocation.
Asia Pacific has the fastest-growth direction in the selected outlook, while country-level rankings and a comparable regional CAGR are unavailable here.
Medium concentration is an analyst assessment reflecting established suppliers and specialized portfolios; no calculated concentration ratio or comparative supplier revenue ranking is assigned.
Related Reports
Omics-Based Clinical Trials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Omics-based clinical trials market to grow from US$38.32 Bn in 2026 to US$65.67 Bn by 2033 at 8.0% CAGR. Explore trial phases, indications and regions.
Ocular Hypertension Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Ocular hypertension market to reach US$ 8.05 billion by 2033 at an 8.2% CAGR. Explore drug classes, delivery modes, pharmacy channels and regional trends.
Obesity GLP-1 Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Obesity GLP-1 market to reach US$ 65.20 billion by 2033 at a 13.1% CAGR. Explore drugs, administration routes, pharmacy channels and regional trends.
Upstream Bioprocessing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Upstream bioprocessing market to reach US$ 92.23 billion by 2033 at a 14.3% CAGR. Explore products, use types, manufacturing modes and regional trends.
Personalized Cancer Vaccine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Personalized cancer vaccine market to reach US$ 16.57 billion by 2033 at an 18.7% CAGR. Explore vaccine types, cancer types and regional trends.
PEGylated Proteins Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
PEGylated proteins market to reach US$ 4.58 billion by 2033 at a 10.9% CAGR. Explore products, protein types, applications and regional trends.