


Corn Flour Market
Corn Flour Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Corn Flour Market Size and Trend Analysis
How Big Is the Corn Flour Market in 2026?
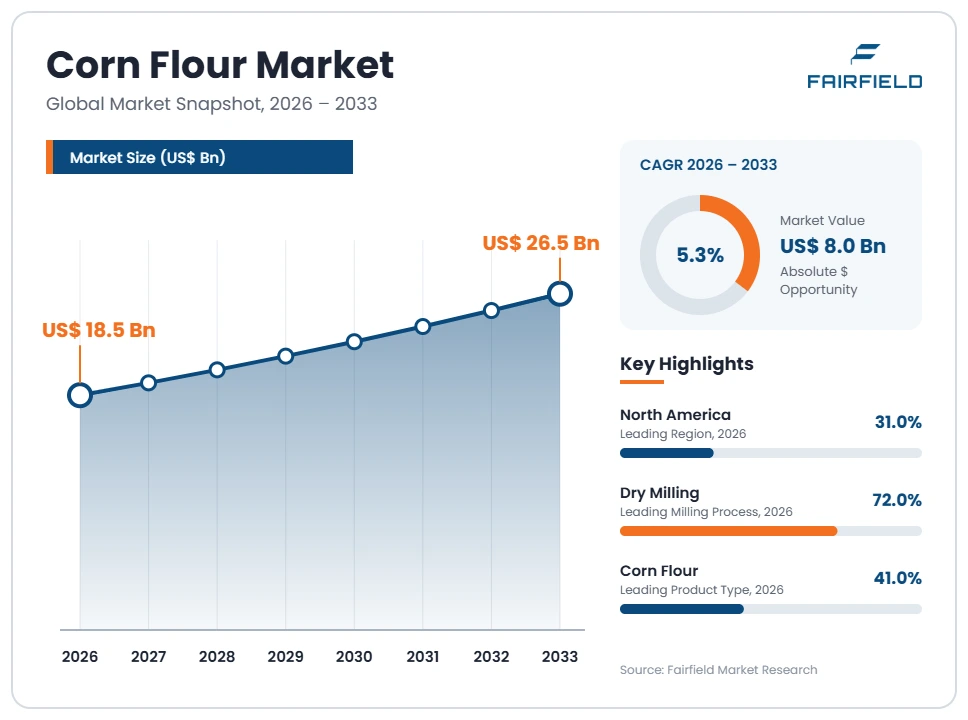
The global Corn Flour market size is expected to be valued at US$ 18.5 billion in 2026 and projected to reach US$ 26.5 billion by 2033, growing at a CAGR of 5.3% between 2026 and 2033.
Between 2020 and 2025 the market expanded at roughly a 4.1% CAGR, a pace set mainly by maize prices, milling energy costs and steady staple consumption rather than by volume breakthroughs. Three factors lift the forecast above that historical rate. Gluten-free baking has moved from a specialty niche into mainstream retail bakery and mix formulation, where corn flour is the lowest-cost functional base. Extruded snacks and ready-to-eat breakfast cereals continue to add milling capacity for corn grits and meal. Fortification programmes for milled maize products raise the per-tonne value of commodity meal. The overall direction is a high-volume, low-margin milling business whose revenue growth comes from value-added fractions, not from basic flour.
Key Report Takeaways
- By Product Type: Corn flour held 41% share in 2026, while corn grits are projected to expand at a 6.4% CAGR through 2033, driven by extrusion lines for puffed snacks and ready-to-eat breakfast cereals that specify tightly graded grit fractions.
- By Milling Process: Dry milling held 72% share in 2026, while wet milling is projected to expand at a 6.1% CAGR through 2033, as refined corn fractions feed coatings, batters and starch-adjacent ingredient blends that carry higher processing margins.
- By Nature: Conventional corn flour held 88% share in 2026, while organic volumes are projected to grow at an 8.2% CAGR through 2033, supported by organic certification capacity in dedicated identity-preserved maize supply chains.
- By Application: Bakery and confectionery held 29% share in 2026, while snacks and extruded products are projected to expand at a 7.1% CAGR through 2033, reflecting savoury snack launches that use corn meal as the primary carrier.
- By Geography: North America held 31% share in 2026, while Asia Pacific is projected to grow at a 6.9% CAGR through 2033, as packaged bakery and snack manufacturing scales across India, China, Indonesia and Vietnam.
Global Corn Flour Market Trends and Insights
Drivers Impact Analysis
Two demand forces account for most of the incremental revenue expected across the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Mainstreaming of gluten-free bakery and dry baking mixes | High | North America, Europe, Asia Pacific | Medium term 2–4 years |
| Expansion of extrusion capacity for snacks and breakfast cereals | High | Global, led by Asia Pacific and Latin America | Long term ≥4 years |
Gluten-Free Bakery Reformulation Makes Corn Flour a Default Base Ingredient
Gluten-free reformulation has become the single largest value driver in the corn flour trade. Retail bakery brands and private-label mix producers need a starch-rich, neutral-tasting cereal base that performs in breads, muffins, pancakes and cookies without wheat protein. Corn flour and finely milled corn meal meet that specification at a fraction of the cost of rice, sorghum or pulse flours, so they anchor most commercial gluten-free blends.
The regulatory mechanism is specific. The U.S. Food and Drug Administration gluten-free labelling rule sets a threshold of 20 milligrams per kilogram, and Regulation (EU) No 1169/2011 requires clear allergen declaration for cereals containing gluten. Those rules gave manufacturers an enforceable claim to market, which in turn justified dedicated gluten-free milling lines, segregated maize intake and certified cleaning protocols at dry mills serving bakery customers.
Snack and Breakfast Cereal Extrusion Pulls Dry-Milled Corn Grits Into Higher-Value Use
Extrusion has shifted a growing share of dry-milled corn output from basic meal into engineered snack feedstock. Puffed and direct-expanded savoury snacks, corn-based crisps and ready-to-eat breakfast cereals all require grits with controlled particle size, low fat content and consistent moisture. Mills that can deliver those specifications sell at a premium over commodity meal, which raises revenue per tonne even when total milling volume grows slowly.
The causal change is capacity-led. Twin-screw extrusion lines have become cheaper and more flexible, so regional snack manufacturers can run multiple shapes on one asset and launch products quickly. That flexibility rewards suppliers who hold several grit fractions in stock. Degerminated maize meal and flour, covered by the Codex Alimentarius standard for degermed maize meal and maize flour, provides the shelf-stable, low-oil feedstock that extruders need.
Restraints Impact Analysis
Two structural pressures limit margin capture and constrain usable supply in this milling business.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Maize price and milling energy cost volatility | High | Global | Short term ≤2 years |
| Mycotoxin maximum levels and rejection of non-compliant maize lots | Medium | Europe, Africa, Latin America | Medium term 2–4 years |
Maize and Energy Cost Swings Compress Dry-Milling Margins Across the Corn Flour Trade
Input volatility is the defining economic constraint on corn milling. Raw maize typically represents the majority of the delivered cost of a tonne of flour or meal, and most supply contracts with bakery and snack customers are repriced only quarterly or annually. When maize rises sharply, millers absorb the gap. That squeeze limits reinvestment in finer milling, sorting and packaging capacity, which is where differentiated products originate.
The cost sources are identifiable rather than general. Degermination, tempering and roller milling are electricity-intensive, drying is gas-intensive, and both energy streams reprice independently of grain. Freight is the third variable, because meal and flour are low-density, bulky and expensive to move relative to their value. Mills located far from maize-growing basins therefore carry a permanent landed-cost disadvantage that no operational improvement fully removes.
Fumonisin and Aflatoxin Limits Restrict the Pool of Food-Grade Maize Available to Millers
Contaminant limits tighten the supply of maize that can legally enter food-grade milling. Maize is the cereal most exposed to fumonisins, and aflatoxin contamination rises sharply in hot, drought-stressed growing seasons. Lots that fail testing are diverted to feed or industrial use at a steep discount, so millers face both reduced availability and the write-down risk on rejected intake.
Commission Regulation (EU) 2023/915 sets maximum levels for aflatoxins and fumonisins in maize and maize-milling products, with separate limits for products intended for direct human consumption. Compliance is not simply a testing cost. It requires representative sampling across heterogeneous bulk lots, optical sorting, cleaning and de-hulling steps, and segregated storage, plus contractual recourse against suppliers. Smaller regional mills often lack that analytical infrastructure, which pushes food-grade premiums higher during contaminated harvest years and strands otherwise usable capacity.
Market Opportunities
Fortified and Enriched Corn Meal Programmes Open Institutional Procurement Revenue
Public nutrition procurement is an underused revenue pool for corn millers. Governments and humanitarian buyers purchase fortified maize meal in large, predictable tenders, and fortified product carries a premium over plain meal because it requires dosing equipment, premix inventory and verification testing. Millers that qualify for these programmes gain volume that is insulated from retail promotional cycles.
Enrichment standards make the pool addressable. In the United States, 21 CFR part 137 sets the standards of identity for corn flour, corn meal and their enriched forms, defining the vitamin and mineral additions that qualify a product as enriched. That codified specification lets buyers write unambiguous tender language. The customer group is institutional: school feeding programmes, food aid agencies and national fortification schemes, most of them concentrated in Africa, Latin America and parts of Asia Pacific.
Functional and Heat-Treated Corn Flours Create a Premium Coatings and Batter Category
Heat-treated and functionally modified corn flours open a genuinely separate revenue pool from commodity meal. Pre-gelatinised, toasted and stabilised corn flours give batters better adhesion, crisper fried coatings and improved freeze-thaw performance in frozen prepared foods. Because these properties are achieved through thermal and mechanical processing rather than chemical modification, the resulting flours support clean-label declarations and sell at a clear premium.
Capture favours millers with processing assets beyond roller mills. The demand comes from frozen food manufacturers, quick-service restaurant supply chains and industrial batter and breading houses that need consistent pickup weight on automated lines. Regulation (EU) No 1169/2011 reinforces the pull, because a physically treated corn flour can be declared simply as corn flour. Gluten-free coating systems built on this base also serve the same bakery customers already buying corn-based blends.
Segment Analysis
- By Product Type: Fine Corn Flour Leads While Corn Grits Gain Momentum
Fine corn flour held 41% share in 2026, the largest of any product fraction. Its lead rests on breadth of use: it enters bakery mixes, gluten-free blends, batters, soups, sauces and confectionery coatings, so demand is spread across many customers rather than concentrated in one. Corn meal follows, supported by traditional baking and porridge consumption. Corn grits are the fastest-growing fraction at a 6.4% CAGR through 2033, because extrusion equipment demands tightly graded, low-fat particles that only degerminated grits deliver consistently. Corn bran remains small but is finding fibre-fortification use in bakery. The business implication is that mills with flexible roller and sifter configurations capture more value than single-grade operations, since the premium sits in particle-size control rather than in total throughput. Nixtamalised masa flour sits outside this product set entirely.
- By Milling Process: Dry Milling Holds Volume While Wet Milling Expands Faster
Dry milling accounted for 72% of 2026 revenue because it is the standard route to flour, meal, grits and bran, and it requires far less capital and water than the alternative. Most independent and regional mills operate dry. Wet milling is the faster-growing process at a 6.1% CAGR through 2033, since it separates maize into starch, protein, fibre and germ streams and yields highly refined corn fractions used in coatings, batters and texturising blends. Wet milling also carries better by-product economics because corn gluten meal and corn oil are saleable. The practical effect is a widening capability gap. Large integrated processors can arbitrage between food, feed and industrial outlets depending on margin, while dry millers depend almost entirely on food demand and therefore carry more exposure to a single market.
- By Nature: Conventional Volumes Dominate as Organic Corn Flour Scales Quickly
Conventional corn flour represented 88% of 2026 value, a share that reflects price sensitivity across bakery, snack and industrial buyers who purchase on specification and landed cost. Organic corn flour is the fastest-growing category at an 8.2% CAGR through 2033. Growth comes from identity-preserved maize contracting, where growers, storage operators and mills maintain documented segregation from field to finished pack. Retail demand is concentrated in natural-channel bakery mixes, infant and toddler foods, and gluten-free products where shoppers already read labels closely. The constraint is agronomic: organic maize yields are lower and supply is thin, so premiums stay wide and volatile. For millers, the implication is that organic lines work best as a dedicated campaign within a conventional plant, with cleaning and documentation costs recovered through contract pricing rather than spot sales.
- By Application: Bakery and Confectionery Leads While Snacks and Extruded Products Accelerate
Bakery and confectionery held 29% share in 2026, the largest single outlet, because corn flour appears in breads, cakes, cookies, tortilla-free flatbreads, dusting applications and gluten-free mixes sold through both retail and foodservice. Snacks and extruded products are expanding fastest at a 7.1% CAGR through 2033, driven by savoury snack launches where corn meal is the primary carrier and flavour delivery matrix. Breakfast cereals form a stable third outlet, while coatings and breadings grow with frozen prepared foods. Animal feed and industrial uses absorb off-specification fractions and stabilise mill economics. The implication for suppliers is that application mix now determines profitability more than scale. A mill selling into snack and coatings customers earns materially more per tonne than one shipping plain meal into commodity bakery channels.
Geography Analysis
- Which Region Is Leading the Corn Flour Market?
North America leads the corn flour market with 31% share in 2026, supported by the largest maize crop in the world and a dense base of dry and wet milling capacity. The United States accounts for most of that total, with Canada and Mexico adding converting and bakery demand. Three causes sustain the position. Milling assets sit close to the maize basin, which removes the freight penalty that burdens importing regions. The packaged snack and breakfast cereal industry is unusually large and buys graded grits in volume. Enrichment and labelling rules under 21 CFR part 137 and the U.S. Food and Drug Administration gluten-free framework give manufacturers clear, enforceable product claims. The main change ahead is reformulation toward whole-grain and higher-fibre corn meal in retail baking mixes, which shifts value toward mills able to run less-degerminated fractions.
- Europe Converts Strict Contaminant and Labelling Rules Into a High-Specification Corn Flour Trade
Europe holds 24% share in 2026, built on a specification-driven rather than volume-driven model. Italy, France, Spain, Romania and Germany are the principal producing and consuming countries, with Italian polenta-grade meal and French bakery flours the most visible products. The region imports a meaningful share of its food-grade maize, so sourcing discipline matters more here than anywhere else. Commission Regulation (EU) 2023/915 caps aflatoxins and fumonisins in maize products, and Regulation (EU) No 1169/2011 governs allergen and ingredient declaration, so mills invest heavily in sampling, optical sorting and traceability. Gluten-free bakery is a strong secondary pull, since coeliac diagnosis rates are high and reimbursement schemes exist in several member states. The opportunity is premium whole-grain and stone-ground corn meal sold on origin and texture rather than on price per tonne.
- Which Region Is Growing Fastest in the Corn Flour Market?
Asia Pacific is growing fastest at a 6.9% CAGR between 2026 and 2033, expanding from a 27% share base and outpacing every other geography. China, India, Indonesia, Vietnam and Thailand drive the expansion. The cause is industrialisation of food manufacturing rather than a change in staple diets. Packaged savoury snacks, instant noodles with corn-based coatings, bakery chains and ready-to-eat cereals are all scaling at once, and each of them buys milled maize fractions rather than whole grain. Domestic milling capacity is being added close to these converting plants, which shortens supply chains and lowers landed cost. Rising disposable income and organised retail penetration reinforce the shift. The constraint is maize availability, since several countries in the region are net importers and compete with feed demand. Mills that secure contracted grain supply will capture most of the incremental volume.
- Latin America Balances Strong Maize Supply Against Infrastructure and Price Barriers
Latin America holds 11% share in 2026 of the conventional corn flour trade, a figure that excludes nixtamalised masa production. Brazil and Argentina are the structural strengths, both large maize producers with growing domestic milling and snack manufacturing sectors. Colombia, Peru and Chile add steady bakery and breakfast cereal demand. Growth is held back by specific barriers: inland logistics costs that can rival the grain price itself, inconsistent grain storage that raises mycotoxin exposure in humid conditions, and currency volatility that makes capital equipment imports expensive. Working capital is also scarce for mid-sized mills. The change worth watching is export-oriented processing, where regional millers supply graded grits and meal to snack manufacturers abroad, converting an abundant raw material position into higher-value traded goods rather than shipping bulk grain.
- Middle East & Africa Depends on Imported Maize While Fortification Programmes Expand
Middle East & Africa accounts for 7% share in 2026 and remains the most supply-constrained geography in the study. Egypt, Nigeria, Kenya, South Africa and Saudi Arabia are the principal markets, with South Africa the only large domestic producer among them. Most other countries import maize, so flour prices track freight rates and foreign exchange availability as much as crop conditions. Barriers are severe: limited cold and dry storage, high post-harvest losses, aflatoxin prevalence in hot humid zones, and intermittent power supply that disrupts milling schedules. Smallholder and informal milling still handles a large share of consumption, which keeps commercial penetration low. The clear opportunity is mandatory fortification of milled maize products, now established in several national programmes, which raises the value of commercial mill output and favours operators with reliable dosing and testing capability.
Competitive Landscape
The corn flour market is moderately concentrated. A small group of integrated agricultural processors controls most wet-milling capacity and a meaningful share of large-scale dry milling, while hundreds of regional and specialty mills serve local bakery, snack and foodservice customers. Cargill, Archer-Daniels-Midland Company and Bunge Global SA hold advantages that come from grain origination rather than from milling technology, because owning storage, logistics and trading desks lets them secure food-grade maize in tight seasons. Ingredion Incorporated is positioned around refined corn fractions and texturising systems. Consolidation has been gradual, usually taking the form of regional mills being absorbed by larger ingredient groups seeking geographic coverage.
Competition rests on a narrow set of factors. Price per tonne delivered is decisive in commodity meal, but in value-added grades buyers evaluate particle-size consistency, fat content, microbiological performance, mycotoxin test results and audit readiness. Food-safety certification, gluten-free segregation and reliable documentation often decide contracts outright. New entrants tend to be specialists rather than generalists: organic and stone-ground millers, gluten-free blend formulators, and regional players building capacity next to new snack plants.
Strategic activity concentrates on moving up the value chain. Millers add heat treatment, pre-gelatinisation and fine grading to escape commodity pricing, invest in optical sorting to protect against contaminant rejections, and build dedicated gluten-free lines to serve bakery brands. Others pursue vertical integration into blending and co-packing so they sell finished mixes rather than bulk flour.
Strategic direction across the sector is consistent. Vendors are pursuing fewer, deeper customer relationships, improving traceability from field to pack, and reallocating capital toward fractions that carry processing margin instead of chasing throughput.
Recent Industry Developments
- August 2013: The U.S. Food and Drug Administration issued its final rule defining gluten-free labelling at a threshold of 20 milligrams per kilogram – establishing the enforceable claim that made corn flour the default base for commercial gluten-free bakery blends.
- May 2023: Commission Regulation (EU) 2023/915 on maximum levels for certain contaminants in food became applicable, replacing earlier legislation and consolidating aflatoxin and fumonisin limits for maize and maize-milling products – raising sourcing and testing requirements for every mill serving the European market.
- December 2024: The U.S. Food and Drug Administration published its final rule updating the nutrient content claim “healthy” – creating a labelling route that favours whole-grain corn meal and lower-sodium corn-based formulations.
- January 2025: The U.S. Food and Drug Administration proposed a front-of-package nutrition information box for most packaged foods – a change that will affect how retail corn flour, corn meal and dry baking mixes are presented at shelf.
Companies Covered in the Report
- Cargill
- Archer-Daniels-Midland Company
- Bunge Global SA
- Ingredion Incorporated
- Didion Milling, Inc.
- Agrana Beteiligungs-AG
- Associated British Foods plc
- Grain Millers, Inc.
- Semo Milling, LLC
- SunOpta Inc.
- Limagrain Ingredients
- C.H. Guenther & Son, LLC
- Great River Organic Milling
- Bob’s Red Mill Natural Foods
- Lifeline Foods, LLC
Corn Flour Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 18.5 Billion |
| Market Size 2033 | US$ 26.5 Billion |
| CAGR 2026–2033 | 5.3% |
| Absolute Dollar Opportunity | US$ 8.0 Billion |
| Largest Market | North America (31% share in 2026) |
| Fastest-Growing Market | Asia Pacific (6.9% CAGR) |
| Market Concentration | Medium |
| Major Players | Cargill, Archer-Daniels-Midland Company, Bunge Global SA, Ingredion Incorporated, Didion Milling |
Corn Flour Market Segmentation
Product Type
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
Milling Process
- Dry Milling
- Wet Milling
Nature
- Conventional
- Organic
Application
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Corn Flour Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Gluten-Free Bakery Reformulation Makes Corn Flour a Default Base Ingredient
- Snack and Breakfast Cereal Extrusion Pulls Dry-Milled Corn Grits Into Higher-Value Use
- Restraints
- Maize and Energy Cost Swings Compress Dry-Milling Margins Across the Corn Flour Trade
- Fumonisin and Aflatoxin Limits Restrict the Pool of Food-Grade Maize Available to Millers
- Market Opportunities
- Fortified and Enriched Corn Meal Programmes Open Institutional Procurement Revenue
- Functional and Heat-Treated Corn Flours Create a Premium Coatings and Batter Category
- Drivers
- Global Corn Flour Market Outlook, 2020–2033
- Global Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- Global Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- Global Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- Global Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- Global Corn Flour Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- North America Corn Flour Market Outlook, 2020–2033
- North America Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- North America Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- North America Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- North America Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- North America Corn Flour Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Corn Flour Market Outlook, by Product Type, 2020–2033
- United States Corn Flour Market Outlook, by Milling Process, 2020–2033
- United States Corn Flour Market Outlook, by Nature, 2020–2033
- United States Corn Flour Market Outlook, by Application, 2020–2033
- Canada Corn Flour Market Outlook, by Product Type, 2020–2033
- Canada Corn Flour Market Outlook, by Milling Process, 2020–2033
- Canada Corn Flour Market Outlook, by Nature, 2020–2033
- Canada Corn Flour Market Outlook, by Application, 2020–2033
- Mexico Corn Flour Market Outlook, by Product Type, 2020–2033
- Mexico Corn Flour Market Outlook, by Milling Process, 2020–2033
- Mexico Corn Flour Market Outlook, by Nature, 2020–2033
- Mexico Corn Flour Market Outlook, by Application, 2020–2033
- North America Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Europe Corn Flour Market Outlook, 2020–2033
- Europe Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- Europe Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- Europe Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- Europe Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- Europe Corn Flour Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Italy Corn Flour Market Outlook, by Product Type, 2020–2033
- Italy Corn Flour Market Outlook, by Milling Process, 2020–2033
- Italy Corn Flour Market Outlook, by Nature, 2020–2033
- Italy Corn Flour Market Outlook, by Application, 2020–2033
- France Corn Flour Market Outlook, by Product Type, 2020–2033
- France Corn Flour Market Outlook, by Milling Process, 2020–2033
- France Corn Flour Market Outlook, by Nature, 2020–2033
- France Corn Flour Market Outlook, by Application, 2020–2033
- Spain Corn Flour Market Outlook, by Product Type, 2020–2033
- Spain Corn Flour Market Outlook, by Milling Process, 2020–2033
- Spain Corn Flour Market Outlook, by Nature, 2020–2033
- Spain Corn Flour Market Outlook, by Application, 2020–2033
- Romania Corn Flour Market Outlook, by Product Type, 2020–2033
- Romania Corn Flour Market Outlook, by Milling Process, 2020–2033
- Romania Corn Flour Market Outlook, by Nature, 2020–2033
- Romania Corn Flour Market Outlook, by Application, 2020–2033
- Germany Corn Flour Market Outlook, by Product Type, 2020–2033
- Germany Corn Flour Market Outlook, by Milling Process, 2020–2033
- Germany Corn Flour Market Outlook, by Nature, 2020–2033
- Germany Corn Flour Market Outlook, by Application, 2020–2033
- Europe Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Asia Pacific Corn Flour Market Outlook, 2020–2033
- Asia Pacific Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- Asia Pacific Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- Asia Pacific Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- Asia Pacific Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- Asia Pacific Corn Flour Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Corn Flour Market Outlook, by Product Type, 2020–2033
- China Corn Flour Market Outlook, by Milling Process, 2020–2033
- China Corn Flour Market Outlook, by Nature, 2020–2033
- China Corn Flour Market Outlook, by Application, 2020–2033
- India Corn Flour Market Outlook, by Product Type, 2020–2033
- India Corn Flour Market Outlook, by Milling Process, 2020–2033
- India Corn Flour Market Outlook, by Nature, 2020–2033
- India Corn Flour Market Outlook, by Application, 2020–2033
- Indonesia Corn Flour Market Outlook, by Product Type, 2020–2033
- Indonesia Corn Flour Market Outlook, by Milling Process, 2020–2033
- Indonesia Corn Flour Market Outlook, by Nature, 2020–2033
- Indonesia Corn Flour Market Outlook, by Application, 2020–2033
- Vietnam Corn Flour Market Outlook, by Product Type, 2020–2033
- Vietnam Corn Flour Market Outlook, by Milling Process, 2020–2033
- Vietnam Corn Flour Market Outlook, by Nature, 2020–2033
- Vietnam Corn Flour Market Outlook, by Application, 2020–2033
- Thailand Corn Flour Market Outlook, by Product Type, 2020–2033
- Thailand Corn Flour Market Outlook, by Milling Process, 2020–2033
- Thailand Corn Flour Market Outlook, by Nature, 2020–2033
- Thailand Corn Flour Market Outlook, by Application, 2020–2033
- Asia Pacific Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Latin America Corn Flour Market Outlook, 2020–2033
- Latin America Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- Latin America Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- Latin America Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- Latin America Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- Latin America Corn Flour Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Corn Flour Market Outlook, by Product Type, 2020–2033
- Brazil Corn Flour Market Outlook, by Milling Process, 2020–2033
- Brazil Corn Flour Market Outlook, by Nature, 2020–2033
- Brazil Corn Flour Market Outlook, by Application, 2020–2033
- Argentina Corn Flour Market Outlook, by Product Type, 2020–2033
- Argentina Corn Flour Market Outlook, by Milling Process, 2020–2033
- Argentina Corn Flour Market Outlook, by Nature, 2020–2033
- Argentina Corn Flour Market Outlook, by Application, 2020–2033
- Colombia Corn Flour Market Outlook, by Product Type, 2020–2033
- Colombia Corn Flour Market Outlook, by Milling Process, 2020–2033
- Colombia Corn Flour Market Outlook, by Nature, 2020–2033
- Colombia Corn Flour Market Outlook, by Application, 2020–2033
- Peru Corn Flour Market Outlook, by Product Type, 2020–2033
- Peru Corn Flour Market Outlook, by Milling Process, 2020–2033
- Peru Corn Flour Market Outlook, by Nature, 2020–2033
- Peru Corn Flour Market Outlook, by Application, 2020–2033
- Chile Corn Flour Market Outlook, by Product Type, 2020–2033
- Chile Corn Flour Market Outlook, by Milling Process, 2020–2033
- Chile Corn Flour Market Outlook, by Nature, 2020–2033
- Chile Corn Flour Market Outlook, by Application, 2020–2033
- Latin America Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Corn Flour Market Outlook, 2020–2033
- Middle East & Africa Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
- Middle East & Africa Corn Flour Market Outlook, by Milling Process, Value (US$ Billion), 2020–2033
- Dry Milling
- Wet Milling
- Middle East & Africa Corn Flour Market Outlook, by Nature, Value (US$ Billion), 2020–2033
- Conventional
- Organic
- Middle East & Africa Corn Flour Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
- Middle East & Africa Corn Flour Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Egypt Corn Flour Market Outlook, by Product Type, 2020–2033
- Egypt Corn Flour Market Outlook, by Milling Process, 2020–2033
- Egypt Corn Flour Market Outlook, by Nature, 2020–2033
- Egypt Corn Flour Market Outlook, by Application, 2020–2033
- Nigeria Corn Flour Market Outlook, by Product Type, 2020–2033
- Nigeria Corn Flour Market Outlook, by Milling Process, 2020–2033
- Nigeria Corn Flour Market Outlook, by Nature, 2020–2033
- Nigeria Corn Flour Market Outlook, by Application, 2020–2033
- Kenya Corn Flour Market Outlook, by Product Type, 2020–2033
- Kenya Corn Flour Market Outlook, by Milling Process, 2020–2033
- Kenya Corn Flour Market Outlook, by Nature, 2020–2033
- Kenya Corn Flour Market Outlook, by Application, 2020–2033
- South Africa Corn Flour Market Outlook, by Product Type, 2020–2033
- South Africa Corn Flour Market Outlook, by Milling Process, 2020–2033
- South Africa Corn Flour Market Outlook, by Nature, 2020–2033
- South Africa Corn Flour Market Outlook, by Application, 2020–2033
- Saudi Arabia Corn Flour Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Corn Flour Market Outlook, by Milling Process, 2020–2033
- Saudi Arabia Corn Flour Market Outlook, by Nature, 2020–2033
- Saudi Arabia Corn Flour Market Outlook, by Application, 2020–2033
- Middle East & Africa Corn Flour Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Cargill
- Archer-Daniels-Midland Company
- Bunge Global SA
- Ingredion Incorporated
- Didion Milling, Inc.
- Agrana Beteiligungs-AG
- Associated British Foods plc
- Grain Millers, Inc.
- Semo Milling, LLC
- SunOpta Inc.
- Limagrain Ingredients
- C.H. Guenther & Son, LLC
- Great River Organic Milling
- Bob's Red Mill Natural Foods
- Lifeline Foods, LLC
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Product Type
- Corn Flour
- Corn Meal
- Corn Grits
- Corn Bran
Milling Process
- Dry Milling
- Wet Milling
Nature
- Conventional
- Organic
Application
- Bakery and Confectionery
- Snacks and Extruded Products
- Breakfast Cereals
- Coatings and Breadings
- Animal Feed and Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The corn flour market is valued at US$ 18.5 billion in 2026, covering conventional dry-milled and wet-milled corn flour, meal, grits and bran.
The market is projected to reach US$ 26.5 billion by 2033, expanding at a 5.3% CAGR and creating an absolute opportunity of US$ 8.0 billion.
Fine corn flour leads with 41% share in 2026, because it serves bakery mixes, gluten-free blends, batters, sauces and confectionery coatings simultaneously.
Corn grits grow fastest among products at a 6.4% CAGR, while Asia Pacific leads geographies at a 6.9% CAGR through 2033.
North America holds 31% share in 2026, supported by abundant domestic maize, co-located milling capacity and a large packaged snack industry.
Related Reports
Yeast Protein Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global yeast protein market is valued at US$0.9 billion in 2026, reaching US$2.0 billion by 2033, growing at a 12.1% CAGR
Starch Derivatives Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global starch derivatives market is valued at US$62.5 billion in 2026, reaching US$88.0 billion by 2033, growing at a 5.0% CAGR
Quick Service Restaurants Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global quick service restaurants market is valued at US$1,090.0 billion in 2026, reaching US$1,556.0 billion by 2033, growing at a 5.2% CAGR
Plant Extracts Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global plant extracts market is valued at US$42.0 billion in 2026, reaching US$68.5 billion by 2033, growing at a 7.2% CAGR
Kombucha Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The Kombucha Market is projected to grow from US$ 3.2 billion in 2026 to US$ 4.8 billion by 2033 at a 6.0% CAGR. Explore trends and leading segments.
Insect Protein Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Insect Protein Market is projected to grow from US$ 1.03 billion in 2026 to US$ 3.17 billion by 2033 at a 17.4% CAGR. Explore trends and key segments.