


Electric Brake Booster Market
Electric Brake Booster Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Electric Brake Booster Market Size and Trend Analysis
Why Is Demand for Electric Brake Boosters Accelerating?
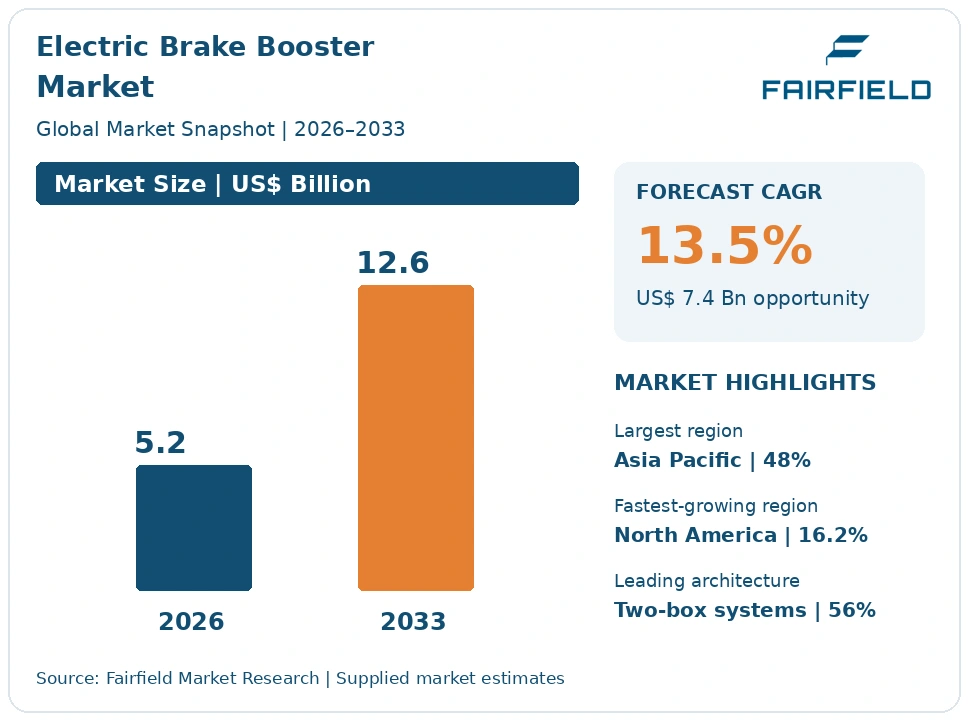
The global Electric Brake Booster market size is expected to be valued at US$ 5.2 billion in 2026 and projected to reach US$ 12.6 billion by 2033, growing at a CAGR of 13.5% between 2026 and 2033.
The market grew at roughly a 21.5% CAGR between 2020 and 2025, as the first large battery electric platforms moved into volume production. Three factors carry growth forward. An electrified powertrain produces no intake manifold vacuum, so the vacuum servo loses its energy source and must be replaced by an electrically actuated unit. Regenerative braking requires the brake system to blend friction and recuperation continuously, which only an electronically controlled actuator can do. Automatic emergency braking mandates require fast, precise, machine-commanded pressure build with a fallback path. Growth moderates from the earlier pace because penetration on new electrified platforms is already high.
Key Report Takeaways
- By Architecture: Two-Box Electro-Hydraulic systems held 56% share in 2026, while One-Box Integrated Brake Control is projected to expand at a 17.6% CAGR through 2033, driven by mass, cost and packaging savings from merging the booster with stability control.
- By Vehicle Type: Passenger Cars held 76% share in 2026, while Light Commercial Vehicles are projected to expand at a 16.8% CAGR through 2033, driven by electrification of urban delivery fleets and their heavier braking duty cycles.
- By Propulsion Type: Battery Electric platforms held 46% share in 2026, while Internal Combustion Engine vehicles are projected to expand at an 18.9% CAGR through 2033, driven by automated emergency braking requirements rather than by any powertrain change.
- By Sales Channel: Original Equipment held 94% share in 2026, while the Aftermarket is projected to expand at a 19.5% CAGR through 2033, driven by the first large cohorts of electrified vehicles passing out of warranty.
- By Geography: Asia Pacific held 48% share in 2026, while North America is projected to expand at a 16.2% CAGR through 2033, driven by federal automatic emergency braking rulemaking and rising light truck electrification.
Global Electric Brake Booster Market Trends and Insights
Drivers Impact Analysis
Two structural forces make the vacuum servo obsolete on modern platforms.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Electrified powertrains producing no engine vacuum for a conventional servo | High | Global | Long term ≥4 years |
| Regenerative braking requiring smooth blending of friction and recuperation | High | Asia Pacific, Europe, North America | Medium term 2–4 years |
Electrified Powertrains Leave the Vacuum Servo Without an Energy Source
The vacuum booster fails on an electrified vehicle for one reason: there is no vacuum. A conventional servo multiplies pedal force using the pressure difference between atmosphere and the intake manifold of a throttled petrol engine. A battery electric vehicle has no manifold, and a hybrid shuts its engine off for long periods, so vacuum is intermittent. Every such platform therefore needs an electrically generated source of boost.
The interim workaround proved unsatisfactory, which is why the market exists. Early hybrids and electric vehicles fitted an electric vacuum pump to feed a conventional servo, adding a noisy, power-consuming component with a finite duty cycle and its own failure mode. Replacing both pump and servo with a single electro-mechanical actuator removes the parasitic load, cuts package volume and noise, and delivers pressure far faster. UNECE Regulation No. 13-H governs the braking performance that any such replacement must demonstrate.
Regeneration Blending Turns the Brake Pedal Into an Energy Recovery Interface
Blending is where recuperation is actually realised, and a mechanical booster cannot perform it. When a driver presses the pedal in an electrified vehicle, the control unit must decide moment by moment how much deceleration the motor should supply as generator torque and how much the friction brakes must add. The split changes with battery state of charge, temperature, wheel slip and speed. Only a decoupled, electronically commanded actuator can vary hydraulic pressure independently of pedal travel.
The commercial consequence is that this component is an efficiency part as much as a safety part. Poor blending leaves recoverable energy as heat in the discs, directly reducing range and raising pad wear. Vehicle manufacturers chasing certified consumption figures treat blending quality as a range lever. A pedal feel simulator makes the arrangement acceptable to drivers by reproducing the force and travel characteristic that a hydraulically coupled system would have given.
Restraints Impact Analysis
Two constraints slow adoption on platforms that are not forced to change.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Cost premium against a mature, inexpensive vacuum booster | High | Asia Pacific, Latin America | Medium term 2–4 years |
| Functional safety, pedal feel and validation burden on a safety-critical actuator | Medium | Global | Long term ≥4 years |
Cost Premium Against a Cheap Vacuum Servo Slows Non-Electrified Adoption
Price is the reason combustion platforms without an automation requirement still fit a vacuum booster. A conventional servo is a stamped steel can with a diaphragm, a spring and a valve, produced in enormous volume on fully depreciated tooling, and it costs very little. An electric brake booster replaces that with a brushless motor, a ball screw or gear reduction, position sensing, a pressure sensor set, a pedal feel simulator and an electronic control unit with its own power supply and diagnostics.
The cost sources are specific rather than general. The actuator motor and its gearing must deliver full pressure in well under two hundred milliseconds, which sets torque and stiffness requirements that cheap components cannot meet. Redundant sensing and a secondary energy path add further content. Electronic control unit software must be developed, calibrated and maintained across the vehicle’s life, which converts a one-off part cost into an ongoing engineering commitment.
Functional Safety and Pedal Feel Validation Lengthen Development and Raise Liability
A brake actuator carries the heaviest safety obligations in the vehicle, and that weight slows programmes and deters entrants. Loss of braking is classified at the highest automotive safety integrity level, so the design must carry redundancy, continuous self-diagnosis and a defined degraded mode that still stops the vehicle. ISO 26262 sets the development process and the hardware metrics required to claim that integrity level, and the evidence package is extensive.
Two further burdens compound it. Pedal feel is subjective and must be tuned until drivers cannot detect the decoupling, particularly during transitions between regeneration and friction, which consumes calibration time on every variant. ISO 21448 adds obligations around hazards arising from intended function in situations the system handles poorly. Because the part is safety-critical, field failures carry recall and liability exposure that makes vehicle manufacturers slow to qualify unproven suppliers.
Market Opportunities
Two revenue pools emerge from automation and from the ageing electrified parc.
Redundant Actuation for Automated Driving Opens a Second Actuator Sale
Higher levels of automation create demand for a second, independent braking actuator on the same vehicle, which roughly doubles the addressable content. A system that drives without the driver supervising must still stop safely after any single failure, so it needs a fallback path capable of achieving meaningful deceleration on its own. That requirement turns braking from one component into a redundant architecture with two controllers, two energy paths and arbitration between them.
Vehicle manufacturers developing conditionally and highly automated systems, robotaxi operators and commercial platform builders are the buyers. The pull is regulatory as well as technical: UNECE Regulation No. 152 sets performance requirements for advanced emergency braking on light vehicles, and automation approval frameworks require demonstrated fault tolerance. Suppliers able to deliver a one-box primary unit plus a validated secondary actuator, with the arbitration software between them, capture content that previously did not exist.
Dry Electro-Mechanical Braking Creates a Corner Module Revenue Pool
Fully dry brake-by-wire, in which an electric motor clamps the caliper directly with no hydraulic circuit at all, opens a larger and later revenue pool. Removing fluid, lines, the master cylinder and the hydraulic control unit saves mass and assembly time, eliminates a fluid service item, and allows per-wheel torque control with a response time no hydraulic system can match. The value per vehicle rises because the supplier sells four actuated corners plus central control.
Vehicle manufacturers building on high-voltage, zonal electrical architectures are the natural first customers, since dry braking needs a reliable power supply and fast, deterministic networking to each corner. Premium battery electric platforms will adopt first, as they can absorb the cost and benefit most from packaging freedom. UNECE Regulations No. 155 and No. 156 on cybersecurity and software update management apply directly, since a dry system’s stopping performance is defined entirely in software.
Segment Analysis
By Architecture: Two-Box Systems Hold the Installed Base While One-Box Integration Advances
Two-Box Electro-Hydraulic systems held 56% of revenue in 2026, the largest architecture position, because they allow a vehicle manufacturer to replace the vacuum servo while keeping an existing and already approved stability control unit. That reduces integration risk and suits platforms derived from combustion predecessors. One-Box Integrated Brake Control is the fastest-growing architecture at a 17.6% CAGR to 2033. Merging boosting, pressure generation and stability control into a single unit removes a controller, a wiring harness branch and several kilograms, and it shortens pressure build time because one actuator serves both functions. Electro-Mechanical Brake-by-Wire remains a small, forward-looking segment confined to early premium applications. The business implication is that integration is where margin now sits: a one-box unit carries far more software and sensing content than the servo it replaces, and it locks the supplier into the chassis control architecture.
By Vehicle Type: Passenger Cars Dominate Fitment as Light Commercial Vehicles Grow Fastest
Passenger Cars represented 76% of demand in 2026, reflecting their share of electrified production and the fact that most one-box programmes launch on car platforms first. This segment also drives the pedal feel expectations that shape the whole product category. Light Commercial Vehicles are the fastest-growing vehicle type at a 16.8% CAGR through 2033. Urban delivery fleets are electrifying quickly because duty cycles suit battery range and because low-emission zones restrict combustion access, and these vehicles brake far more often per kilometre than private cars, which makes blending quality and actuator durability commercially significant. Buses and Medium Commercial Vehicles form a smaller segment where hydraulic braking persists. Heavy trucks using compressed air braking fall outside this market entirely. For suppliers, commercial duty cycles demand higher endurance validation than passenger car programmes, which is a defensible technical barrier.
By Propulsion Type: Battery Electric Platforms Lead While Combustion Vehicles Grow Quickest
Battery Electric platforms held 46% of value in 2026, the largest propulsion position, because they have no vacuum source and depend on blending to recover energy, making the electric booster effectively mandatory. Hybrid and Plug-in Hybrid Electric platforms form the second block, with intermittent engine operation producing the same problem in a milder form. Internal Combustion Engine vehicles are the fastest-growing propulsion type at an 18.9% CAGR to 2033, which is the most counterintuitive finding in this market. These vehicles have a working vacuum source, so the adoption reason is entirely different: automatic emergency braking performance requirements demand pressure build rates and precision that a vacuum servo with an external pump cannot reliably deliver. The strategic implication is that the addressable base is far larger than the electrified fleet alone, and that safety regulation will extend this component into vehicles that have no efficiency reason to adopt it.
By Sales Channel: Original Equipment Carries Almost All Volume While Aftermarket Demand Emerges
Original Equipment held 94% of value in 2026, an unusually high concentration even for a chassis component. Brake actuation is safety-critical, approved as part of the vehicle type, and supplied under long-term contracts that require functional safety evidence and software maintenance commitments. The Aftermarket is the faster-growing channel at a 19.5% CAGR to 2033, from a very small base. The electrified vehicle parc is still young, so few units have yet reached the age at which an actuator motor, position sensor or control unit fails. As the first large cohorts pass out of warranty, independent repair demand will appear, though it will be constrained by the need for coded replacement parts, calibration tools and secure diagnostic access. The consequence is that aftermarket participation will favour suppliers with original equipment relationships and authorised service tooling rather than independent brands.
Geography Analysis
Which Region Is Growing Fastest in the Electric Brake Booster Market?
North America is growing fastest, at a 16.2% CAGR between 2026 and 2033, from 20% share in 2026. The United States supplies most of that demand, with Mexico and Canada contributing assembly capacity. The mechanism is regulation acting on a vehicle mix that is not otherwise electrifying quickly. Federal rulemaking on automatic emergency braking sets performance requirements that effectively oblige electronically commanded brake actuation across the light vehicle fleet, including pickups and large sport utility vehicles that will keep combustion and hybrid powertrains for years. FMVSS 135 governs the underlying service brake performance those systems must still meet. A second pull comes from electric pickup and full-size van programmes, which are heavy and therefore demanding on both blending and actuator sizing. The constraint is schedule uncertainty, since compliance deadlines and their interpretation shape supplier capacity planning.
Europe Converts Safety Mandates Into Near-Universal Electronic Brake Actuation
Europe accounted for 23% of revenue in 2026, led by Germany, France, Italy, Spain and the United Kingdom. The region sets the most demanding combination of safety and automation requirements anywhere. The General Safety Regulation made advanced emergency braking a condition of registration for new vehicles, and type approval under UNECE Regulation No. 13-H governs the braking performance that must be achieved. Together these push electronic actuation onto platforms regardless of powertrain. The region also hosts the premium manufacturers developing conditionally automated driving, which is where redundant brake architectures appear first. Cybersecurity and software update management obligations apply to the component because its behaviour is defined in software. The regional opportunity is dry electro-mechanical braking, which premium platforms built on zonal electrical architectures are best placed to adopt.
Which Region Is Leading the Electric Brake Booster Market?
Asia Pacific leads with 48% of global revenue in 2026, a position built on electrified vehicle production volume concentrated in a single country. China builds and sells more battery electric and plug-in hybrid vehicles than the rest of the world combined, and every one of them needs an electrically boosted brake system, which makes fitment volume the primary cause of the regional lead. A second cause is a capable domestic supplier base that has moved from licensed designs to in-house one-box systems, compressing prices and accelerating local adoption. Japan and South Korea add established chassis suppliers and strong hybrid output, while India is beginning to electrify light commercial fleets. The complication is price pressure: intense domestic competition has pushed unit prices below levels available elsewhere, which compresses margins for all participants. Export of low-cost systems from the region is the change to watch.
Latin America Adopts Electronic Braking Through Imported Electrified Models
Latin America held 5% of revenue in 2026, concentrated in Brazil, Mexico and Chile. Adoption follows imported vehicles rather than local engineering. Mexico is significant chiefly as an export assembly base, building electrified models fitted with systems specified by manufacturers for other markets. Brazil and Chile show growing urban battery electric bus and delivery fleet procurement, which brings electronic brake actuation into service. Barriers are substantial. Price sensitivity in the dominant entry-level car segment favours vacuum boosters, local safety rules do not yet mandate advanced emergency braking as firmly as in Europe, and workshop capability for diagnosing an electronically actuated brake system is limited. Charging infrastructure constrains electrification generally. The change worth watching is public fleet procurement, which is specifying higher safety content than private buyers currently demand.
Middle East & Africa Builds Demand From Imported Electrified Fleets and Safety Upgrades
Middle East & Africa accounted for 4% of revenue in 2026, the smallest regional position, led by the United Arab Emirates, Saudi Arabia, Israel and South Africa. Gulf markets are the most active, where government fleet electrification targets and a premium-weighted vehicle mix bring electronically boosted systems in with imported models. South Africa and Morocco host vehicle assembly that increasingly builds to European safety specifications for export, which pulls the component in regardless of local demand. Barriers are clear. Vehicle fleets are dominated by older imported combustion models, there is no regional engineering or production base for chassis control systems, and extreme ambient temperatures raise thermal validation requirements for actuator motors and electronics. The opportunity sits in commercial fleet and public transport electrification programmes funded by sovereign investment vehicles.
Competitive Landscape
The market is highly concentrated, more so than most chassis component categories. A small number of global suppliers holds the large majority of production, because brake actuation demands functional safety evidence at the highest integrity level, software maintained over a vehicle’s service life, and a validated manufacturing process that vehicle manufacturers audit closely. Those requirements create a barrier that capital alone does not overcome. The notable structural change is the emergence of Chinese suppliers who have moved from second-source status to primary supply on domestic programmes, which has introduced genuine price competition into a field that previously had little.
Competition rests on factors that are mostly invisible to the end customer. Pressure build time under machine command is the first, since automatic emergency braking performance depends on it. Blending quality is the second, measured by how much recuperation energy is retained and how undetectable the friction transition feels. Functional safety architecture under ISO 26262, the credibility of the degraded mode, and the completeness of the cybersecurity case under UNECE Regulations No. 155 and No. 156 all shape sourcing decisions. Software update capability over the air is increasingly a condition of award rather than a differentiator.
Positioning varies across the field. Robert Bosch GmbH, Continental AG and ZF Friedrichshafen AG combine long braking histories with full chassis control portfolios and supply both two-box and one-box architectures. Hitachi Astemo, Ltd., ADVICS Co., Ltd., HL Mando Corporation and Hyundai Mobis Co., Ltd. anchor Japanese and Korean platforms. Bethel Automotive Safety Systems Co., Ltd., Zhejiang Asia Pacific Mechanical & Electronic Co., Ltd. and NASN Automotive Electronics (Shanghai) Co., Ltd. compete aggressively in China. Brembo S.p.A. approaches the category from the caliper side with decoupled braking concepts.
Strategic direction points to three themes: consolidating boosting and stability control into one-box units to protect content value, building redundant architectures for automated driving, and preparing dry electro-mechanical systems that will eventually displace hydraulics at the corner.
Electric Brake Booster Industry Leaders
- Robert Bosch GmbH
- Continental AG
- ZF Friedrichshafen AG
- Hitachi Astemo, Ltd.
- HL Mando Corporation
Recent Industry Developments
January 2020: UNECE Regulation No. 152 on advanced emergency braking systems for light vehicles entered into force – it set collision avoidance performance requirements that demand machine-commanded pressure build faster than a vacuum servo with an auxiliary pump can deliver.
January 2021: UNECE Regulations No. 155 and No. 156 on cybersecurity management systems and software update management systems entered into force – they brought software-defined brake actuation inside a formal type-approval obligation, raising the compliance burden on suppliers.
April 2024: The United States National Highway Traffic Safety Administration issued a final rule establishing FMVSS No. 127, requiring automatic emergency braking and pedestrian automatic emergency braking on light vehicles, with compliance required by September 2029 – it extends electronic brake actuation demand across combustion light trucks.
July 2024: The European Union General Safety Regulation extended its advanced emergency braking requirement to all new vehicles registered in the bloc – the step made electronically controlled braking a practical condition of sale across the entire European market.
Electric Brake Booster Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 5.2 Billion |
| Market Size 2033 | US$ 12.6 Billion |
| CAGR 2026–2033 | 13.5% |
| Absolute Dollar Opportunity | US$ 7.4 Billion |
| Largest Market | Asia Pacific, 48% share in 2026 |
| Fastest-Growing Market | North America, 16.2% CAGR |
| Market Concentration | High |
| Major Players | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Hitachi Astemo, Ltd., HL Mando Corporation |
This study covers electro-mechanical and electro-hydraulic brake boosters and integrated brake control units that replace the vacuum servo, including one-box and two-box architectures, stability control integration, pedal feel simulators and emerging dry electro-mechanical actuation. Conventional vacuum boosters, vacuum pumps, compressed air braking for heavy trucks, calipers and friction material are excluded. The base year is 2025 and the forecast period runs from 2026 to 2033, reported in US$ Billion.
Electric Brake Booster Market Segmentation
Architecture
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
Propulsion Type
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
Sales Channel
- Original Equipment
- Aftermarket
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Electric Brake Booster Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Electrified Powertrains Leave the Vacuum Servo Without an Energy Source
- Regeneration Blending Turns the Brake Pedal Into an Energy Recovery Interface
- Restraints
- Cost Premium Against a Cheap Vacuum Servo Slows Non-Electrified Adoption
- Functional Safety and Pedal Feel Validation Lengthen Development and Raise Liability
- Market Opportunities
- Redundant Actuation for Automated Driving Opens a Second Actuator Sale
- Dry Electro-Mechanical Braking Creates a Corner Module Revenue Pool
- Drivers
- Global Electric Brake Booster Market Outlook, 2020–2033
- Global Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- Global Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- Global Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- Global Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- Global Electric Brake Booster Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- North America Electric Brake Booster Market Outlook, 2020–2033
- North America Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- North America Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- North America Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- North America Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- North America Electric Brake Booster Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- United States Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- United States Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- United States Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Canada Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Canada Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Canada Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Canada Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- North America Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Europe Electric Brake Booster Market Outlook, 2020–2033
- Europe Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- Europe Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- Europe Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- Europe Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- Europe Electric Brake Booster Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Germany Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Germany Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Germany Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- France Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- France Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- France Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- France Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Italy Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Italy Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Italy Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Italy Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Spain Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Spain Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Spain Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Spain Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- United Kingdom Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- United Kingdom Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- United Kingdom Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- United Kingdom Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Europe Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Asia Pacific Electric Brake Booster Market Outlook, 2020–2033
- Asia Pacific Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- Asia Pacific Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- Asia Pacific Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- Asia Pacific Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- Asia Pacific Electric Brake Booster Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- China Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- China Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- China Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Japan Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Japan Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Japan Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Japan Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- South Korea Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- South Korea Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- South Korea Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- South Korea Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- India Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- India Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- India Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- India Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Asia Pacific Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Latin America Electric Brake Booster Market Outlook, 2020–2033
- Latin America Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- Latin America Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- Latin America Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- Latin America Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- Latin America Electric Brake Booster Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Brazil Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Brazil Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Brazil Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Mexico Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Chile Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Chile Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Chile Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Chile Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Latin America Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Middle East & Africa Electric Brake Booster Market Outlook, 2020–2033
- Middle East & Africa Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
- Middle East & Africa Electric Brake Booster Market Outlook, by Vehicle Type, Value (US$ Billion), 2020–2033
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
- Middle East & Africa Electric Brake Booster Market Outlook, by Propulsion Type, Value (US$ Billion), 2020–2033
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
- Middle East & Africa Electric Brake Booster Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Aftermarket
- Middle East & Africa Electric Brake Booster Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- United Arab Emirates Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- United Arab Emirates Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- United Arab Emirates Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Saudi Arabia Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Saudi Arabia Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Saudi Arabia Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Saudi Arabia Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Israel Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Israel Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Israel Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Israel Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- South Africa Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- South Africa Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- South Africa Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- South Africa Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Morocco Electric Brake Booster Market Outlook, by Architecture, 2020–2033
- Morocco Electric Brake Booster Market Outlook, by Vehicle Type, 2020–2033
- Morocco Electric Brake Booster Market Outlook, by Propulsion Type, 2020–2033
- Morocco Electric Brake Booster Market Outlook, by Sales Channel, 2020–2033
- Middle East & Africa Electric Brake Booster Market Outlook, by Architecture, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Robert Bosch GmbH
- Continental AG
- ZF Friedrichshafen AG
- Hitachi Astemo, Ltd.
- ADVICS Co., Ltd.
- HL Mando Corporation
- Hyundai Mobis Co., Ltd.
- Brembo S.p.A.
- Bethel Automotive Safety Systems Co., Ltd.
- Zhejiang Asia Pacific Mechanical & Electronic Co., Ltd.
- NASN Automotive Electronics (Shanghai) Co., Ltd.
- BWI Group
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Architecture
- Two-Box Electro-Hydraulic
- One-Box Integrated Brake Control
- Electro-Mechanical Brake-by-Wire
Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Buses and Medium Commercial Vehicles
Propulsion Type
- Battery Electric
- Hybrid and Plug-in Hybrid Electric
- Internal Combustion Engine
Sales Channel
- Original Equipment
- Aftermarket
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 5.2 billion in 2026, covering electro-mechanical and electro-hydraulic boosters and integrated brake control units across all light vehicle platforms.
Revenue is projected to reach US$ 12.6 billion by 2033, a 13.5% CAGR and an absolute dollar opportunity of US$ 7.4 billion over the period.
Two-Box Electro-Hydraulic systems lead with 56% share in 2026, because they replace the vacuum servo while retaining an already approved stability control unit.
Internal Combustion Engine vehicles grow fastest at an 18.9% CAGR, because automatic emergency braking requirements demand actuation precision that a vacuum servo cannot reliably provide.
Asia Pacific holds 48% share in 2026, built on electrified vehicle production volume in China and a capable domestic chassis supplier base.
Related Reports
Container Fleet Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the container fleet market, projected to reach US$ 26.8 billion by 2033 at a 5.4% CAGR, with container types, ownership and regional insights.
Micro-mobility Charging Infrastructure Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global micro-mobility charging infrastructure market is valued at US$9.06 billion in 2026, reaching US$34.02 billion by 2033, growing at a 20.8% CAGR
eCTOL Aircraft Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the eCTOL aircraft market, projected to reach US$ 11.14 billion by 2033 at a 10.6% CAGR, with propulsion, application and regional insights.
Smart EV Charging Networks Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global smart EV charging networks market is valued at US$9.43 billion in 2026, reaching US$37.07 billion by 2033, growing at a 21.6% CAGR
Ultra High Performance Tire Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global ultra high performance tire market is valued at US$18.65 billion in 2026, reaching US$38.97 billion by 2033, growing at an 11.1% CAGR
Small Parcels Delivery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the small parcels delivery market, forecast to reach US$957.5 billion by 2033 at 7.3% CAGR, with service, shipment weight and regional insights.