


Facility Management Market
Facility Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Facility Management Market Size and Trend Analysis
What supports growth in facility management spending?
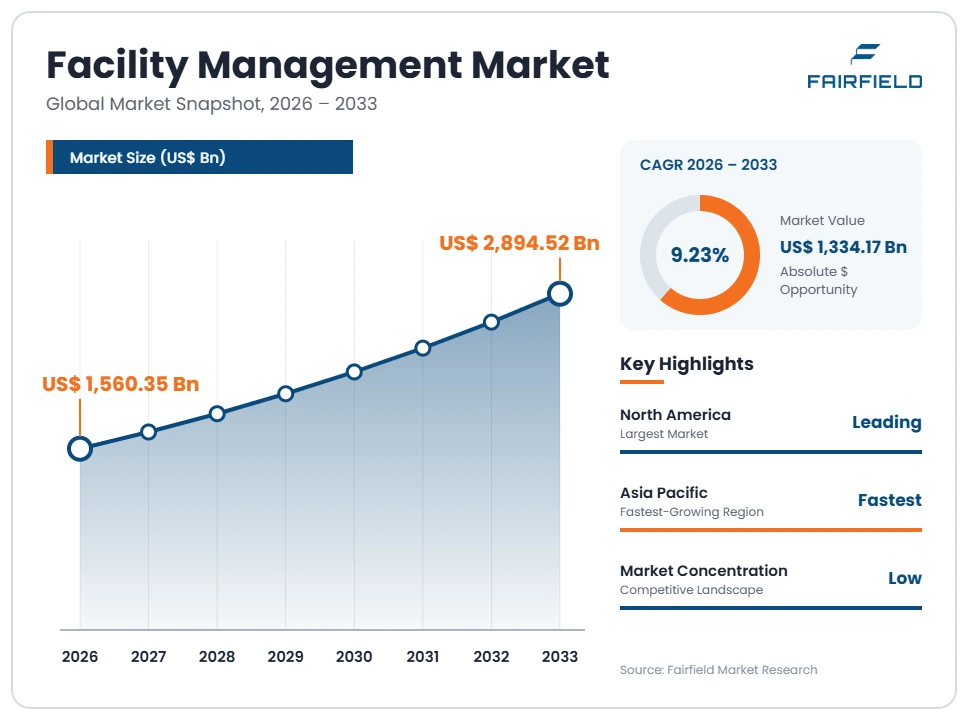
The global Facility Management market size is expected to be valued at US$1,560.35 billion in 2026 and projected to reach US$2,894.52 billion by 2033, growing at a CAGR of 9.23% between 2026 and 2033. This broad activity benchmark includes in-house and externally delivered building operations. It is not a software-only estimate or a measure of revenue earned solely by outsourced service companies.
During 2020–2025, organizations reassessed building use, maintenance planning, and workplace service requirements. A comparable historical CAGR is unavailable; the selected series values 2025 at US$1,428.52 billion. Asset upkeep, multi-site service coordination, and building-performance objectives support spending. Labor costs and contract scope also affect reported values. The outlook therefore combines changes in service volumes, delivery models, and prices. Outsourcing can shift expenditure between internal and external providers without creating an equivalent increase in the underlying amount of facility work.
Key Report Takeaways
- By Work Purpose: Asset Reliability covers maintaining building systems, Occupant Services covers the working environment, and Operational Governance covers coordination. Shares are unavailable for these independent categories. Integrated contracts can include all purposes, requiring allocation by actual deliverable rather than repeated counting.
- By Accountability Model: Internal Delivery retains service execution within the organization, while External Delivery assigns defined work to a provider. Mixed arrangements are allocated by work package. Outsourcing may change who records revenue without proportionately expanding the underlying building-service requirement.
- By Portfolio Structure: Single-Site Programs and Multi-Site Programs require different coordination and reporting arrangements. Comparable leadership and fastest-growth rates are unavailable. A larger property portfolio creates potential scale benefits, but local staffing, asset condition, and service scope determine achievable contract economics.
- By Geography: North America leads the selected broad activity benchmark, while Asia Pacific has its fastest-growth direction. Consistent country rankings are not adopted. Supplier coverage, building use, and customer procurement practices affect opportunity alongside the amount of built infrastructure.
- By Competition: CBRE, ISS, JLL, Sodexo, and Cushman & Wakefield document facility-related services. Competition varies between local work packages and global programs. Total property, catering, investment, or project-management revenue should not be treated as directly comparable facility management revenue.
Global Facility Management Market Trends and Insights
Drivers Impact Analysis
Ratings describe analyst judgement about operating expenditure and service purchasing, without assigning unsupported numerical contributions to growth.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Maintenance and operational continuity needs | High | All five standard regions | Short term (≤2 years) |
| Coordinated workplace and portfolio services | Medium | Corporate and institutional portfolios | Medium term (2–4 years) |
Facility Management Asset Upkeep Sustains Recurring Work
Buildings require continuing maintenance even when construction slows or occupancy changes. Heating, ventilation, electrical distribution, and other systems need inspection, servicing, and corrective work suited to condition. Deferred maintenance can increase the difficulty of planning later interventions, making asset information and work prioritization commercially useful. Customers therefore purchase technical facility services to support reliable operation, rather than isolated repairs. The associated spending depends on asset complexity, operating hours, and agreed service requirements.
JLL documents engineering and building-system maintenance, while ISS describes technical services within integrated facilities delivery. These offerings establish a recurring work requirement without proving a universal reduction in failures or operating costs. Providers can improve their proposition through accurate asset registers, appropriate maintenance plans, and documented completion. Buyers should distinguish planned activities from reactive work and capital replacement. That separation helps evaluate service performance and prevents equipment investment from being counted as routine management revenue.
Facility Management Portfolio Coordination Supports Integrated Contracts
Multi-site organizations create demand for coordinated facility services when local contracts produce inconsistent reporting or fragmented accountability. A common governance model can help customers compare work orders, staffing, and service standards across properties. The commercial requirement is a practical connection between central oversight and local delivery. Customers may combine selected services while retaining specialist responsibilities internally. Integrated facility management therefore concerns contract design and execution, not merely combining providers.
CBRE’s building-operations strategy and Cushman & Wakefield’s integrated facilities offering demonstrate relevant supplier capabilities. ISS also documents international customer relationships. These examples support the availability of coordinated delivery, without establishing identical benefits across portfolios. Providers need local staff, subcontractor oversight, and usable service data. Buyers should define escalation, reporting, and responsibility for specialist work before consolidation. This makes integration a manageable operating arrangement rather than an assumption that fewer supplier names automatically produce lower total expenditure.
Restraints Impact Analysis
Workforce costs and uncertain asset information can limit margins, service quality, and the pace of contract expansion.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Staffing, supervision, and specialist availability | High | Labor-intensive services | Short term (≤2 years) |
| Incomplete asset data and contract ambiguity | Medium | Older and changing portfolios | Medium term (2–4 years) |
Facility Management Labor Requirements Constrain Contract Economics
Labor requirements constrain facility management economics because many tasks depend on trained staff being available at the correct location and time. Cleaning, reception, maintenance, and supervision have different staffing needs, and technical work may require specific competencies. A contract price that assumes unrealistic productivity can weaken service delivery or supplier margins. Customers should therefore evaluate staffing plans against operating hours, building use, and response requirements rather than compare headline fees without examining execution.
ISS and Sodexo document people-intensive service portfolios, while technical providers describe specialist building support. Costs include recruitment, training, supervision, absence coverage, travel, and subcontractor coordination. These costs cannot be removed simply by adding a reporting platform. Technology can support scheduling and visibility, but physical tasks still require an executable delivery model. Providers should state assumptions and escalation arrangements. Buyers benefit from transparent service boundaries and realistic resourcing, across varied work packages.
Facility Management Data Gaps Complicate Performance-Based Agreements
Incomplete asset and service data can restrict adoption of more demanding performance agreements. A provider cannot reliably price maintenance risk without understanding equipment condition, operating requirements, and existing obligations. Occupancy changes can also alter cleaning, reception, and workplace demand. Customers and suppliers may disagree when the contract does not define how those changes affect staffing or fees. The restraint is uncertainty about work and responsibility, beyond software features.
Computerized maintenance management systems and building analytics can organize information, but their usefulness depends on accurate records and disciplined work-order handling. JLL documents technology-supported facility operations, illustrating an available delivery capability without guaranteeing complete data at contract start. Specific costs include surveys, asset verification, system configuration, and continuing data maintenance. Providers should establish baselines and change procedures before offering outcome commitments. Buyers should verify measurement methods and retained responsibilities, avoiding targets without auditable measures.
Market Opportunities
Facility Management Operational Energy Services Create Measurable Projects
Operational energy management creates a service opportunity where building operations do not match actual use. Providers can offer assessment, monitoring, control review, and continuing verification. The revenue pool concerns defined operational services, with capital equipment replacement treated separately. Customers need an agreed baseline and adjustment method before savings can be attributed to the service. Weather, occupancy, production schedules, and energy tariffs can otherwise obscure whether an observed change came from the provider’s work.
Technical facility providers and specialist partners can pursue customers with accessible system data and authority to implement agreed changes. JLL documents energy and building-system expertise, while ISS includes technical services within its offering. These capabilities support a practical supplier base, not a universal payback estimate. Contracts should define measurement, maintenance, and customer participation. Providers can capture continuing monitoring fees for regular performance review, distinguishing this emerging service package from ordinary maintenance already contracted.
Facility Management Mobilization Services Can Support Expanding Portfolios
Portfolio expansion creates opportunities for providers that can mobilize staff, suppliers, asset records, and reporting at new or newly outsourced sites. Customers may need transition planning beyond replacement staffing. Providers can earn implementation and continuing management revenue when they organize these activities within a clear contract. The opportunity depends on actual operational handover, because an announced property project does not independently establish the timing or scope of service spending.
ISS’s documented India partnership and Australian contract renewal illustrate different mobilization settings: geographic expansion and continued site delivery. CBRE’s workplace strategy provides another commercial context. Providers can differentiate through site assessment, staff readiness, and consistent reporting after launch. Customers should establish which assets and obligations transfer, while monitoring subcontractors. A staged handover can support continuity, but its costs and responsibilities must be explicit. This prevents transition fees, normal operations, and unrelated property expenditure from being counted repeatedly.
Segment Analysis
- By Work Purpose: Facility Management Reliability and Occupant Services Need Different Measures
Asset Reliability includes work primarily intended to maintain building systems and infrastructure. Occupant Services covers services supporting people using the facility, such as cleaning, reception, or workplace support. Operational Governance covers separately identified coordination, reporting, and supplier oversight. Work packages are assigned by their primary deliverable, rather than counting an integrated contract in full under every purpose. This preserves a commercial boundary even when the same provider manages several activities.
Comparable shares and fastest-growth rates are unavailable for these independent categories. JLL, ISS, and Cushman & Wakefield document offerings spanning different facility requirements. The relevant performance measures differ: technical work needs an asset and maintenance basis, while occupant services require appropriate service definitions and workload assumptions. Governance fees should be identified separately when contracted. Buyers can use this distinction to compare proposals without assuming a broad service bundle has the same cost structure or performance objectives as a single specialist work package.
- By Accountability Model: Facility Management Outsourcing Changes Revenue Attribution
Internal Delivery covers work executed within the facility owner’s or occupier’s organization. External Delivery covers work packages assigned to a separate service provider. Mixed programs are allocated at the activity level, avoiding a residual category that overlaps with both. The selected market benchmark includes internal activity, so the overall value cannot be compared directly with the aggregate revenue of outsourced companies. This boundary is essential when assessing supplier opportunity or estimating the effect of a new outsourcing contract.
Consistent category shares and growth rankings are not adopted for this independent allocation. Outsourcing can shift expenditure between categories without changing the building’s underlying requirements. Providers should evaluate the work available for transfer, staffing arrangements, and retained customer responsibilities. ISS, Sodexo, and CBRE establish relevant external capabilities. Buyers should compare the full operating model, including internal governance, rather than assume outsourcing eliminates all customer work or automatically produces a proportional increase in total facility management activity.
- By Portfolio Structure: Facility Management Multi-Site Programs Need Local Execution
Single-Site Programs cover contracts or internal programs organized around one operating location. Multi-Site Programs coordinate defined service responsibilities across several locations. Classification follows the commercial program rather than the number of buildings within a campus. This avoids counting a campus repeatedly or treating every location in a wider customer organization as part of the same contract when services are procured separately.
Comparable leadership and fastest-growth rates are unavailable. Multi-site programs can support common reporting and supplier coordination, but local asset condition and staffing still influence cost. Single-site work can require substantial technical depth when the operation is complex. CBRE, JLL, and Cushman & Wakefield document portfolio-oriented capabilities, while local providers may serve narrower assignments. Buyers should compare central management charges, local work packages, and transition costs separately. Suppliers need evidence that proposed standardization fits actual sites rather than assuming every location benefits from identical staffing or maintenance routines.
Geography Analysis
- Which Region Is Leading the Facility Management Market?
North America leads the selected broad activity benchmark. The United States and Canada contain established corporate, institutional, and industrial building portfolios with varied service requirements. CBRE and JLL document relevant operating capabilities. Their presence supports supplier access, but does not establish a consistent national ranking or imply that outsourced service revenue equals all regional facility activity.
Opportunities include technical maintenance, workplace services, and portfolio coordination. Customers need clear baselines and realistic staffing assumptions when changing service models. Providers should distinguish new outsourcing from genuinely additional work. Building use, asset condition, and contract pricing can affect expenditure independently of floor area. Regional strategy is therefore more useful when based on executable work packages and local support than on a single property-market growth indicator.
- Facility Management European Portfolios Require Country-Specific Delivery
Europe offers facility management demand across offices, industrial sites, public institutions, and other operating properties. Germany, France, and the United Kingdom provide relevant customer settings. ISS and Sodexo document broad service capabilities, while technical and property-service providers support specialist requirements. Comparable national shares are not adopted. Local service obligations and staffing arrangements require assessment for each proposed contract.
Opportunities include operational energy services, coordinated maintenance, and clearer portfolio reporting. Suppliers need to understand existing staff, subcontractors, asset records, and customer responsibilities before promising standardization. Transition costs and service boundaries can limit the attractiveness of a superficially large portfolio. Buyers should compare actual work and governance arrangements, keeping ordinary operations separate from capital projects, property transactions, and software-only spending within broader commercial relationships.
- Which Region Is Growing Fastest in the Facility Management Market?
Asia Pacific has the fastest-growth direction in the selected broad benchmark. China, India, Japan, and Australia provide varied building and service environments. ISS’s documented India contract and Australian renewal establish specific commercial examples. They do not independently measure regional growth or prove that all countries share the same outsourcing pattern. Local service scope and contract execution remain central to opportunity.
Providers can pursue technical operations, workplace services, and mobilization where customer requirements are defined. Staffing, local support, pricing, and asset information can constrain delivery. Buyers should distinguish an expanding property pipeline from sites ready for operational handover. Country rankings are not inferred here. Commercial demand becomes more concrete when a provider can identify the work package, delivery team, and continuing responsibilities attached to an actual customer facility.
- Facility Management Latin American Contracts Need Clear Cost Assumptions
Latin America offers selective opportunities across commercial, industrial, healthcare, and institutional facilities. Brazil, Mexico, and Chile provide customer-development settings without implying a verified national ranking. Buyers may seek dependable maintenance, coordinated workplace services, or better reporting. Each requirement needs a practical service definition rather than an assumption that all facility activities can be transferred under one uniform regional agreement.
Constraints include budgets, labor costs, subcontractor oversight, and uneven availability of specialist technical staff. Providers can differentiate through local delivery and transparent scope changes. Opportunities include staged outsourcing and improvements to existing operations. Customers should examine how fees respond to occupancy, asset additions, and required service hours. A sustainable contract connects price with measurable work and clear responsibilities, reducing disputes when operating conditions change during delivery.
- Facility Management Middle East & Africa Needs Mobilization Discipline
Middle East & Africa presents opportunities in operating commercial properties, industrial sites, hospitality, and public facilities. Saudi Arabia, the United Arab Emirates, and South Africa are relevant customer settings. These examples are not verified regional share leaders. New developments can generate service requirements, but timing depends on handover, occupancy, and the actual operating model adopted by the owner or occupier.
Barriers include mobilization costs, technical staffing, asset-data quality, and continuing support across dispersed locations. Providers can pursue defined handover and operations packages where responsibilities are clear. Buyers should distinguish construction completion from service readiness. A credible program establishes asset records, maintenance plans, staffing, and escalation before routine operations begin. This creates a more assessable commercial opportunity than allocating all announced infrastructure spending to facility management services.
Competitive Landscape
Competition is fragmented across local providers, specialist contractors, and large integrated groups. Low overall concentration is an analyst judgement reflecting that broad delivery base; competition for global programs can be more concentrated. CBRE, ISS, JLL, Sodexo, and Cushman & Wakefield have directly documented facility-related services. Their wider property, food, investment, or project activities are not interchangeable measures of facility management share. The broad market also includes internal activity that produces no external supplier revenue.
Customers compare staffing, technical competence, local coverage, reporting, and the ability to manage changes in service requirements. New entrants can address particular sites or specialist tasks, but need supervision and continuity arrangements. Larger providers must demonstrate local execution rather than rely only on portfolio scale. A low quoted fee is commercially weak if the contract leaves essential work undefined or assumes staffing that cannot meet operating requirements.
Documented developments show attention to workplace delivery and geographic relationships. CBRE announced its Industrious transaction and building-operations segment in January 2025. ISS continued an Australian site relationship under a renewal commencing in June 2025, and documented an India agreement expected to begin in July 2025. These are different forms of competitive activity, not equivalent additions to market size. Acquisition, renewal, and outsourcing should be distinguished when assessing growth.
Strategic direction should connect service promises with measurable work, capable local teams, and transparent governance. Providers can build relationships through reliable mobilization and auditable performance. Buyers should identify retained responsibilities, subcontracted activities, and the treatment of capital work. Competitive comparisons should follow defined facility services, avoiding predicted winners or rankings based on revenues that include unrelated commercial activities. This provides a sounder basis for procurement and supplier assessment across both local contracts and wider portfolios.
Recent Industry Developments
- January 2025: CBRE announced the acquisition of remaining Industrious interests and a Building Operations & Experience segment, linking workplace operations with its property-service strategy.
- June 2025: ISS’s renewed Homeground Gladstone agreement commenced, continuing accommodation-related services including housekeeping, catering, and maintenance activities.
- July 2025: ISS identified the expected start of an India integrated-services contract, expanding an existing international customer relationship into another operating market.
Companies Covered in the Report
CBRE; ISS; JLL; Sodexo; Cushman & Wakefield; Industrious. The latter is discussed in connection with CBRE’s workplace strategy, without treating its entire flexible-workplace business as comparable facility management revenue.
Facility Management Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$1,560.35 Billion |
| Market Size 2033 | US$2,894.52 Billion |
| CAGR 2026–2033 | 9.23% |
| Absolute Dollar Opportunity | US$1,334.17 Billion |
| Largest Market | North America, selected benchmark |
| Fastest-Growing Market | Asia Pacific, selected benchmark |
| Market Concentration | Low overall; higher in global contracts, analyst judgement |
| Major Players | CBRE, ISS, JLL, Sodexo, Cushman & Wakefield |
Facility Management Market Segmentation
Work Purpose
- Asset Reliability
- Occupant Services
- Operational Governance
Accountability Model
- Internal Delivery
- External Delivery
Portfolio Structure
- Single-Site Programs
- Multi-Site Programs
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Facility Management Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Facility Management Asset Upkeep Sustains Recurring Work
- Facility Management Portfolio Coordination Supports Integrated Contracts
- Restraints
- Facility Management Labor Requirements Constrain Contract Economics
- Facility Management Data Gaps Complicate Performance-Based Agreements
- Market Opportunities
- Facility Management Operational Energy Services Create Measurable Projects
- Facility Management Mobilization Services Can Support Expanding Portfolios
- Drivers
- Global Facility Management Market Outlook, 2020–2033
- Global Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- Global Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- Global Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- Global Facility Management Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- North America Facility Management Market Outlook, 2020–2033
- North America Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- North America Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- North America Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- North America Facility Management Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Facility Management Market Outlook, by Work Purpose, 2020–2033
- United States Facility Management Market Outlook, by Accountability Model, 2020–2033
- United States Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Canada Facility Management Market Outlook, by Work Purpose, 2020–2033
- Canada Facility Management Market Outlook, by Accountability Model, 2020–2033
- Canada Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- North America Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Europe Facility Management Market Outlook, 2020–2033
- Europe Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- Europe Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- Europe Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- Europe Facility Management Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Facility Management Market Outlook, by Work Purpose, 2020–2033
- Germany Facility Management Market Outlook, by Accountability Model, 2020–2033
- Germany Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- France Facility Management Market Outlook, by Work Purpose, 2020–2033
- France Facility Management Market Outlook, by Accountability Model, 2020–2033
- France Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- United Kingdom Facility Management Market Outlook, by Work Purpose, 2020–2033
- United Kingdom Facility Management Market Outlook, by Accountability Model, 2020–2033
- United Kingdom Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Europe Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asia Pacific Facility Management Market Outlook, 2020–2033
- Asia Pacific Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- Asia Pacific Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- Asia Pacific Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- Asia Pacific Facility Management Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Facility Management Market Outlook, by Work Purpose, 2020–2033
- China Facility Management Market Outlook, by Accountability Model, 2020–2033
- China Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- India Facility Management Market Outlook, by Work Purpose, 2020–2033
- India Facility Management Market Outlook, by Accountability Model, 2020–2033
- India Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Japan Facility Management Market Outlook, by Work Purpose, 2020–2033
- Japan Facility Management Market Outlook, by Accountability Model, 2020–2033
- Japan Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Australia Facility Management Market Outlook, by Work Purpose, 2020–2033
- Australia Facility Management Market Outlook, by Accountability Model, 2020–2033
- Australia Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Asia Pacific Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Latin America Facility Management Market Outlook, 2020–2033
- Latin America Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- Latin America Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- Latin America Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- Latin America Facility Management Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Facility Management Market Outlook, by Work Purpose, 2020–2033
- Brazil Facility Management Market Outlook, by Accountability Model, 2020–2033
- Brazil Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Mexico Facility Management Market Outlook, by Work Purpose, 2020–2033
- Mexico Facility Management Market Outlook, by Accountability Model, 2020–2033
- Mexico Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Chile Facility Management Market Outlook, by Work Purpose, 2020–2033
- Chile Facility Management Market Outlook, by Accountability Model, 2020–2033
- Chile Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Latin America Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Middle East & Africa Facility Management Market Outlook, 2020–2033
- Middle East & Africa Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Asset Reliability
- Occupant Services
- Operational Governance
- Middle East & Africa Facility Management Market Outlook, by Accountability Model, Value (US$ Billion), 2020–2033
- Internal Delivery
- External Delivery
- Middle East & Africa Facility Management Market Outlook, by Portfolio Structure, Value (US$ Billion), 2020–2033
- Single-Site Programs
- Multi-Site Programs
- Middle East & Africa Facility Management Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Facility Management Market Outlook, by Work Purpose, 2020–2033
- Saudi Arabia Facility Management Market Outlook, by Accountability Model, 2020–2033
- Saudi Arabia Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- United Arab Emirates Facility Management Market Outlook, by Work Purpose, 2020–2033
- United Arab Emirates Facility Management Market Outlook, by Accountability Model, 2020–2033
- United Arab Emirates Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- South Africa Facility Management Market Outlook, by Work Purpose, 2020–2033
- South Africa Facility Management Market Outlook, by Accountability Model, 2020–2033
- South Africa Facility Management Market Outlook, by Portfolio Structure, 2020–2033
- Middle East & Africa Facility Management Market Outlook, by Work Purpose, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- CBRE
- ISS
- JLL
- Sodexo
- Cushman & Wakefield
- Industrious
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Work Purpose
- Asset Reliability
- Occupant Services
- Operational Governance
Accountability Model
- Internal Delivery
- External Delivery
Portfolio Structure
- Single-Site Programs
- Multi-Site Programs
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Facility Management Market is estimated at US$1,560.35 billion in 2026, covering broad internal and externally delivered building operations rather than software alone.
The market is projected to reach US$2,894.52 billion by 2033, implying 9.23% annual growth and US$1,334.17 billion additional activity within the defined boundary.
A comparable work-purpose leader is unavailable; Asset Reliability, Occupant Services, and Operational Governance require different delivery models and performance measures within facility programs.
Asia Pacific has the fastest-growth direction in the selected broad benchmark, with opportunities depending on actual building operations, staffing, mobilization, and customer service requirements.
North America leads the selected benchmark, supported by established operating portfolios and service availability, although broad facility activity must remain distinct from outsourced revenue.
Related Reports
Underwater LiDAR Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the underwater LiDAR market, projected to reach US$0.9 billion by 2033 at 12.3% CAGR, with platform, application and regional insights.
Aerial Imaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global aerial imaging market is valued at US$3.83 billion in 2026, reaching US$8.13 billion by 2033, growing at an 11.4% CAGR
Satcom Terminal Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The satcom terminal market is projected to grow from US$8.6 billion in 2026 to US$20.6 billion by 2033, at a 13.3% CAGR. Explore segments and key trends.
Non-Dispersive Infrared Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The non-dispersive infrared market is projected to grow from US$1.6 billion in 2026 to US$2.7 billion by 2033, at a 7.8% CAGR. Explore segments and trends.
5G Edge Computing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global 5G edge computing market is valued at US$10.45 billion in 2026, reaching US$161.37 billion by 2033, growing at a 47.8% CAGR
Wearable Cameras Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global wearable cameras market is valued at US$8.80 billion in 2026, reaching US$20.80 billion by 2033, growing at a 13.1% CAGR