


Heavy Metal Testing Market
Heavy Metal Testing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Heavy Metal Testing Market Size and Trend Analysis
Why is heavy metal testing demand expanding?
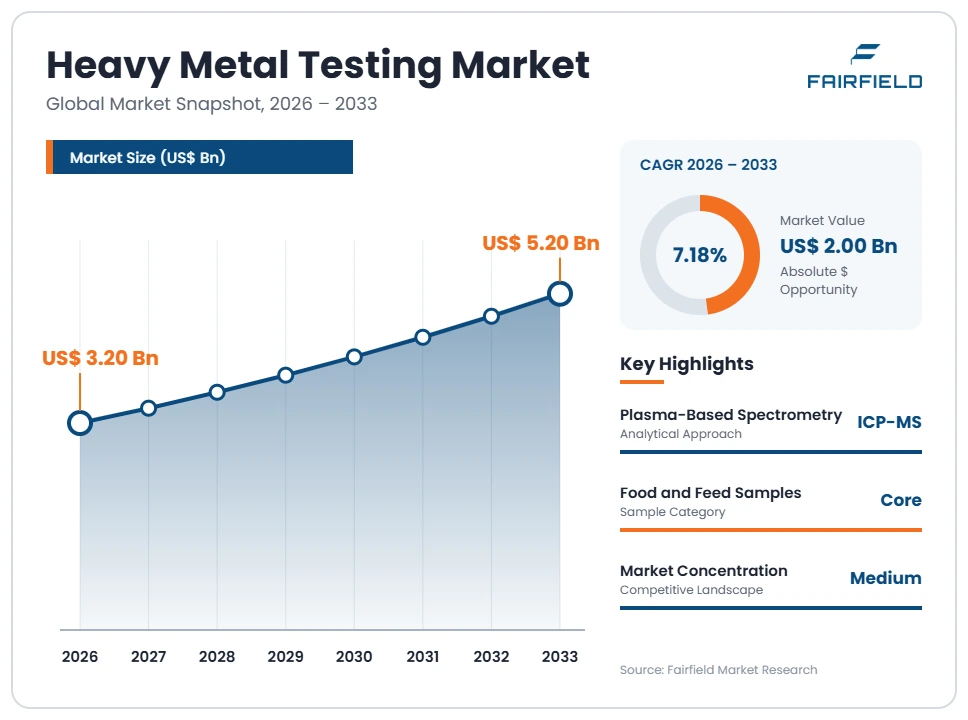
The global Heavy Metal Testing market size is expected to be valued at US$3.20 billion in 2026 and projected to reach US$5.20 billion by 2033, growing at a CAGR of 7.18% between 2026 and 2033. Demand connects contaminant monitoring with product release, supplier qualification, and environmental assessment. Buyers need reliable results for a defined sample and decision, rather than simply access to an instrument with a low advertised detection limit.
During 2020–2025, attention to food contaminants and trace-element analysis strengthened the commercial relevance of specialist laboratories. A comparable historical CAGR is unavailable; back-calculation implies a 2025 value near US$2.99 billion. Food-safety requirements, water monitoring, and supply-chain verification support demand. Growth depends on sampling quality, validated methods, and timely reporting. Analytical capacity alone cannot guarantee useful results when sample preparation, acceptance criteria, or the customer’s intended use remain unclear.
Key Report Takeaways
- By Analytical Approach: Plasma-Based Spectrometry supports multi-element analysis, while Atomic Absorption Methods and Other Techniques address different requirements. SGS documents both plasma and atomic-absorption capabilities. Public evidence does not establish a comparable technology leader or fastest-growing technique within the report’s independently defined categories.
- By Sample Category: Food and Feed Samples provide a documented purchasing base, while Water and Environmental Samples create separate sampling and reporting requirements. Other Product and Process Samples covers remaining nonclinical applications. Sample-specific validation matters more than assuming a method transfers unchanged across matrices.
- By Customer Model: Outsourced Laboratory Services provide specialist capacity without requiring every customer to operate an analytical laboratory. In-House Testing Workflows remain relevant for organizations needing direct control. The choice depends on volume, turnaround, expertise, and quality-system requirements rather than a universally superior model.
- By Geography: North America has a clear food-safety and environmental-method context, while Europe and Asia Pacific host verified laboratory activity. Comparable regional shares and fastest-growth rankings remain unavailable. Commercial priorities should therefore follow local demand, laboratory scope, and sample logistics.
- By Decision Quality: Heavy metal testing must distinguish total-element measurement from speciation where chemical form matters. Eurofins Scientific documents specialist elemental services, while FDA guidance illustrates a regulatory purchasing context. Detection alone does not establish compliance without appropriate units, matrix, and interpretation.
Global Heavy Metal Testing Market Trends and Insights
Drivers Impact Analysis
These qualitative ratings describe the importance of purchasing mechanisms rather than measured additions to forecast growth.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Food contaminant monitoring and supplier checks | High | All five standard regions | Short term (≤2 years) |
| Water and environmental analytical requirements | High | All five standard regions | Medium term (2–4 years) |
Heavy Metal Testing Benefits From Defined Food-Contaminant Decisions
Food contaminant monitoring supports testing when manufacturers need evidence about ingredients, production batches, or finished products. Customers may use results to qualify suppliers, investigate variation, or assess whether a product meets an applicable requirement. Food safety testing is therefore a workflow rather than a single measurement. A useful service connects representative sampling, suitable preparation, analytical performance, and reporting with the decision the customer needs to make about a particular product or supply chain.
In January 2025, the U.S. Food and Drug Administration issued final guidance on lead action levels for certain processed foods intended for babies and young children. The guidance is not a universal testing mandate for every food product. It nevertheless provides a concrete example of why customers need reliable, matrix-appropriate results. Laboratories can address that need through clear method scope and reporting. General contaminant concerns do not establish identical testing frequencies across products.
Heavy Metal Testing Water Programs Support Recurring Analytical Work
Water and environmental programs create demand for trace metals analysis across defined monitoring and investigation tasks. Customers may need information about source water, industrial discharges, contaminated sites, or material handling. These assignments differ in sampling location, preservation, preparation, and reporting requirements. Repeat testing can arise from an established monitoring program, but a laboratory must understand the relevant method and purpose before proposing a service. A generic metals panel does not automatically answer every environmental question.
The U.S. Environmental Protection Agency publishes Method 200.8 for trace elements in waters and wastes using plasma mass spectrometry. This is a method reference, not a claim that the same procedure applies to every matrix or jurisdiction. SGS also documents environmental metals services. Suppliers can strengthen recurring relationships by coordinating sample logistics and defensible reporting. Customers benefit when method scope, turnaround expectations, and quality-control arrangements are agreed before samples arrive, reducing avoidable reanalysis and delays.
Restraints Impact Analysis
Preparation complexity and limited specialist capacity can constrain testing even when customer demand is well defined.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Preparation and quality-control costs | High | All five standard regions | Short term (≤2 years) |
| Method-transfer and interpretation complexity | Medium | Regulated and difficult-matrix testing | Medium term (2–4 years) |
Heavy Metal Testing Preparation Costs Limit Simple Price Comparisons
Sample preparation can make heavy metal testing more expensive than an instrument-run quotation suggests. Foods, soils, water, and manufactured products can require different handling and digestion. Laboratories also need suitable reagents, reference materials, quality-control samples, and trained staff. These inputs influence both turnaround and the defensibility of the final result. Customers comparing prices should therefore check what the quotation includes, especially whether preparation, additional dilution, repeat analysis, or special reporting creates separate charges.
Specific cost sources include high-purity reagents, digestion equipment, contamination control, instrument maintenance, and analyst review. Intertek describes inorganic analysis across varied product matrices, illustrating the breadth of technical requirements. Multi-element capability can improve efficiency, but it does not remove the need for appropriate quality checks. Laboratories can reduce purchasing friction with clear scope and realistic turnaround commitments. A low headline price offers limited value when the delivered report cannot support the customer’s intended product-release or investigation decision.
Heavy Metal Testing Method Differences Can Complicate Customer Interpretation
Method differences can create uncertainty when customers compare results from laboratories using different preparation or reporting conventions. Total-element measurement is different from chemical speciation, and results must be expressed on the appropriate basis. Sampling variation can also affect comparisons before instrument performance becomes relevant. A laboratory may produce a technically sound result that still fails to answer the customer’s actual question because the requested analysis was not suitable for the sample or decision.
Eurofins Scientific describes specialist metals and elemental analysis, including speciation-related capabilities, while SGS documents chromatographic coupling for selected applications. These examples show why method selection requires more detail than naming a contaminant. Laboratories incur costs through validation, reference materials, staff competence, and technical review. Customers should confirm the required analytes, matrix, units, and reporting limits before commissioning work. Clear communication reduces avoidable disputes and prevents an instrument’s broad analytical capability from being mistaken for universal method suitability.
Market Opportunities
Heavy Metal Testing Supplier Programs Support Managed Services
Supplier verification creates an opportunity for laboratories to provide coordinated testing programs rather than isolated sample reports. Manufacturers sourcing ingredients or components from multiple suppliers may need consistent instructions, comparable methods, and organized reporting. A managed service can connect sample submission, agreed panels, turnaround targets, and exception handling. The commercial value comes from reducing administrative uncertainty and making results easier to use across purchasing and quality teams, without assuming that every supplier requires the same testing schedule.
Intertek, Eurofins Scientific, and Mérieux NutriSciences offer relevant food-contaminant capabilities, establishing a practical supplier base. Laboratory networks can capture demand by aligning testing with a customer’s actual supplier risks and product requirements. Additional value may come from reporting consistency and technical support rather than more tests alone. Customers retain sampling and acceptance responsibilities. Repeatable programs support relationships when scope is proportionate and analytical findings remain distinct from certification or regulatory approval.
Heavy Metal Testing Speciation Addresses Specialist Questions
Specialized speciation creates an opportunity where customers need information about chemical forms rather than only the total amount of an element. Such assignments can require more demanding separation, measurement, and interpretation. The revenue pool is distinct from routine multi-element screening because the service addresses a narrower analytical question. Laboratories can pursue premium work when they demonstrate suitable methods, reference materials, and staff expertise, instead of extending a general instrument capability into an unsupported claim of comprehensive speciation coverage.
Eurofins Scientific and SGS document relevant specialist offerings, providing a verifiable commercial foundation. Food producers, research teams, and other customers may require additional analysis when total-element results are insufficient for their purpose. Demand should be established case by case rather than inferred from all routine testing volumes. Providers can differentiate through method scope, transparent reporting, and technical consultation. Laboratories should explain precisely what was measured and how it answers the customer’s question.
Segment Analysis
- By Analytical Approach: Heavy Metal Testing Requires Method and Matrix Alignment
Plasma-Based Spectrometry includes ICP-MS testing and related optical-emission approaches. These technologies can support multi-element measurement, but required performance depends on the matrix and analyte. EPA Method 200.8 demonstrates a specific environmental mass-spectrometry application. A laboratory should not assume that purchasing a plasma instrument establishes validated capability for every food, water, or industrial sample. Preparation, interference management, and quality control remain part of the analytical workflow and influence its commercial usefulness.
Atomic Absorption Methods provide another established route, while Other Techniques covers remaining approaches and specialized combinations. SGS documents both atomic absorption and plasma-based services, illustrating technology choice within one supplier. Comparable technology shares and growth rankings are not assigned. Customers should select a method for the decision they need to support, including the required reporting limit and chemical form. Laboratories can compete through method-specific competence and consistent delivery rather than treating one instrument architecture as universally preferable.
- By Sample Category: Heavy Metal Testing Food and Water Workflows Differ
Food and Feed Samples require attention to heterogeneous materials, preparation, and the basis on which results are reported. Mérieux NutriSciences, Intertek, and Eurofins Scientific provide documented food-contaminant services. These offerings establish participation without proving which sample category leads globally. A customer should clarify the relevant product and analytes rather than assume that a generic package covers every ingredient or regulatory purpose. Food contaminant analysis must remain connected to representative sampling and an appropriate decision framework.
Water and Environmental Samples creates different logistics and method requirements, including project-specific collection and preservation. Other Product and Process Samples includes nonclinical materials outside the first categories. Assigning samples by their primary matrix avoids counting the same work repeatedly under several customer industries. Publicly comparable shares and fastest-growth rates are unavailable. Laboratories should align preparation capacity, staff expertise, and reporting with the sample mix they expect, because a broad service catalogue alone does not ensure economical or timely processing.
- By Customer Model: Heavy Metal Testing Outsourcing Trades Capital for Service Dependence
Outsourced Laboratory Services allows customers to access equipment and specialist expertise without operating every analytical function internally. Network providers can offer multiple locations and defined technical capabilities. SGS’ laboratory investments illustrate the importance of capacity and local support. Customers still need suitable sample collection and clear instructions, while laboratories need realistic acceptance and turnaround arrangements. Outsourcing transfers analytical work, but it does not eliminate the customer’s need to understand what the result will be used to decide.
In-House Testing Workflows may suit organizations with sufficient recurring volume, staff, and quality-system resources. Instrument vendors support this model, but equipment sales are not added again to outsourced service revenue. Hybrid purchasing arrangements can combine internal screening with external specialist analysis. Comparable model shares and growth rankings are unavailable. The commercial implication is to evaluate total workflow cost, reporting needs, and available expertise rather than choose outsourcing or internal capability solely from the price of a single test.
Geography Analysis
- Which Region Is Leading the Heavy Metal Testing Market?
A comparable largest-region ranking is not established, although North America has a strong regulatory and laboratory-services context. The United States provides directly documented examples through FDA food guidance, EPA analytical methods, and SGS laboratory activity. Canada is relevant to regional customer and sample-logistics networks, but supplier presence should not be treated as a measured demand share.
Opportunities include food verification, water monitoring, and built-environment investigations. Customers should assess a laboratory’s specific method scope and service arrangements rather than rely only on a global brand. Local collection, courier access, and technical support can affect turnaround. Laboratory investment can improve available capability, but actual project demand and operational execution determine utilization and commercial returns.
- Heavy Metal Testing in Europe Supports Specialist Analysis
Europe provides verifiable specialist laboratory activity through companies including Eurofins Scientific, SGS, and Intertek. Germany hosts documented elemental-analysis expertise, while the United Kingdom and France are relevant markets for food and environmental services. These examples identify commercial participation rather than a numerical ranking of countries or laboratory networks.
Customers may need methods aligned with product destination and applicable requirements. A report prepared for one purpose should not automatically be assumed sufficient for another market or product category. Laboratories can pursue opportunities through method-specific expertise, clear documentation, and consistent service across customer locations. The strongest proposition connects technical competence with practical sampling and reporting. Comparable regional growth rates are left unquantified rather than combining incompatible estimates from different market definitions.
- Which Region Is Growing Fastest in Heavy Metal Testing?
A comparable fastest-growing region is not established from the selected evidence; Asia Pacific nevertheless offers identifiable testing opportunities. India and China are relevant to food production and industrial supply chains, while Singapore provides a documented laboratory-services location through ALS and other providers. These markets differ in customer requirements, sample logistics, and institutional capacity.
Eurofins Scientific, Intertek, and SGS publish regional service offerings, demonstrating accessible commercial capability. Suppliers can pursue food exporters, manufacturers, and environmental customers with clearly defined analytical needs. Expansion should follow actual sample demand and appropriate method scope, rather than assume that manufacturing growth creates identical testing requirements everywhere. Country-specific revenue shares and growth rankings remain unavailable on a consistent public basis.
- Heavy Metal Testing in Latin America Requires Practical Sample Logistics
Latin America offers potential across food supply chains, water assessment, and industrial investigations. Brazil and Mexico are reasonable focus countries for customer and partner assessment, rather than verified regional demand leaders. Buyers may require results for domestic decisions or export-related documentation. Those uses can differ in analyte scope, accepted method, and the reporting required by the intended recipient.
Constraints include courier access, preparation capacity, specialist staff, and the cost of sending samples to distant facilities. Laboratories can improve the proposition through clear collection instructions and dependable local support. Partnerships may help customers access specialist analysis without building every capability in each location. Commercial planning should prioritize repeatable sample flows and suitable methods, while avoiding unsupported regional market shares or assumed testing obligations.
- Heavy Metal Testing in Middle East & Africa Needs Accessible Expertise
Middle East & Africa presents selective opportunities in food supply, water programs, and industrial activity. Saudi Arabia, the United Arab Emirates, and South Africa are prospective customer-development settings. ALS documents regional analytical capability, while international laboratory networks offer additional routes to specialist services. These examples do not establish a comparable country market ranking.
Budget constraints, sampling logistics, and access to qualified staff can shape adoption. Customers need to know where samples will be analyzed and whether the receiving laboratory can perform the required work. Providers can differentiate through accessible technical consultation and consistent reporting. A focused service for a clearly identified customer problem is more credible than a broad claim that every project requires the same heavy-metals panel or that laboratory accreditation covers all possible methods.
Competitive Landscape
Heavy metal testing competition includes international laboratory networks, regional specialists, and in-house analytical teams. A medium concentration assessment is qualitative rather than a calculated market-share ratio. SGS, Eurofins Scientific, Intertek, ALS, and Mérieux NutriSciences have verified relevant services. Instrument suppliers support the value chain but should not be counted as equivalent outsourced-testing providers.
Laboratories compete on validated capability, turnaround, sample access, reporting quality, and technical support. A customer investigating a difficult food matrix may value specialist advice, while a routine environmental program may prioritize reliable scheduling and consistent reports. Smaller laboratories can serve defined local needs, but must maintain appropriate methods and resources. Buyers should assess the relevant laboratory location and method scope rather than assume that a global network name guarantees every service at every facility.
Recent SGS developments illustrate different forms of capability expansion. Its Reno laboratory added metals-analysis instrumentation, while AMA Analytical Services brought lead/metals and built-environment expertise into the network. The addition of RTI Laboratories concerned broader environmental and materials capabilities. These developments are commercially relevant, but their full revenues cannot be attributed to heavy metal testing. The distinction matters because laboratory networks provide many analytical services beyond the market discussed here.
Strategic differentiation should focus on defensible results and clear customer decisions. Providers can improve relationships through consistent reporting, understandable scope, and practical sample logistics. Equipment investment supports capability, but analyst competence and quality control remain essential. Customers should compare complete workflow costs and responsibilities. A credible market assessment therefore distinguishes technical capacity, service coverage, and realized testing demand while avoiding claims that one supplier is universally superior or that a new instrument guarantees regulatory acceptance for every application.
Recent Industry Developments
- April 2024: SGS announced additional ICP-MS instrumentation at its Reno laboratory, supporting metals-analysis capacity and redundancy.
- November 2024: SGS welcomed AMA Analytical Services, expanding built-environment capabilities that include lead/metals analysis.
- February 2025: SGS announced the addition of RTI Laboratories, broadening environmental and materials-testing capabilities beyond metals alone.
Companies Covered in the Report
SGS; Eurofins Scientific; Intertek; ALS; Mérieux NutriSciences. AMA Analytical Services and RTI Laboratories are discussed within SGS, without duplicate competitor counts.
Heavy Metal Testing Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$3.20 Billion |
| Market Size 2033 | US$5.20 Billion |
| CAGR 2026–2033 | 7.18% |
| Absolute Dollar Opportunity | US$2.00 Billion |
| Largest Market | Not established across comparable public data |
| Fastest-Growing Market | Not established across comparable public data |
| Market Concentration | Medium, qualitative assessment |
| Major Players | SGS, Eurofins Scientific, Intertek, ALS, Mérieux NutriSciences |
Heavy Metal Testing Market Segmentation
Analytical Approach
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
Sample Category
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
Customer Model
- Outsourced Laboratory Services
- In-House Testing Workflows
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Heavy Metal Testing Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Heavy Metal Testing Benefits From Defined Food-Contaminant Decisions
- Heavy Metal Testing Water Programs Support Recurring Analytical Work
- Restraints
- Heavy Metal Testing Preparation Costs Limit Simple Price Comparisons
- Heavy Metal Testing Method Differences Can Complicate Customer Interpretation
- Market Opportunities
- Heavy Metal Testing Supplier Programs Support Managed Services
- Heavy Metal Testing Speciation Addresses Specialist Questions
- Drivers
- Global Heavy Metal Testing Market Outlook, 2020–2033
- Global Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- Global Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- Global Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- Global Heavy Metal Testing Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- North America Heavy Metal Testing Market Outlook, 2020–2033
- North America Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- North America Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- North America Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- North America Heavy Metal Testing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- United States Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- United States Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Canada Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Canada Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Canada Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- North America Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Europe Heavy Metal Testing Market Outlook, 2020–2033
- Europe Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- Europe Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- Europe Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- Europe Heavy Metal Testing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Germany Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Germany Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- United Kingdom Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- United Kingdom Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- United Kingdom Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- France Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- France Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- France Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Europe Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Asia Pacific Heavy Metal Testing Market Outlook, 2020–2033
- Asia Pacific Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- Asia Pacific Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- Asia Pacific Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- Asia Pacific Heavy Metal Testing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- India Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- India Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- India Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- China Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- China Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- China Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Singapore Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Singapore Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Singapore Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Asia Pacific Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Latin America Heavy Metal Testing Market Outlook, 2020–2033
- Latin America Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- Latin America Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- Latin America Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- Latin America Heavy Metal Testing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Brazil Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Brazil Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Mexico Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Mexico Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Mexico Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Latin America Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Middle East & Africa Heavy Metal Testing Market Outlook, 2020–2033
- Middle East & Africa Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
- Middle East & Africa Heavy Metal Testing Market Outlook, by Sample Category, Value (US$ Billion), 2020–2033
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
- Middle East & Africa Heavy Metal Testing Market Outlook, by Customer Model, Value (US$ Billion), 2020–2033
- Outsourced Laboratory Services
- In-House Testing Workflows
- Middle East & Africa Heavy Metal Testing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- Saudi Arabia Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- Saudi Arabia Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- United Arab Emirates Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- United Arab Emirates Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- United Arab Emirates Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- South Africa Heavy Metal Testing Market Outlook, by Analytical Approach, 2020–2033
- South Africa Heavy Metal Testing Market Outlook, by Sample Category, 2020–2033
- South Africa Heavy Metal Testing Market Outlook, by Customer Model, 2020–2033
- Middle East & Africa Heavy Metal Testing Market Outlook, by Analytical Approach, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- SGS
- Eurofins Scientific
- Intertek
- ALS
- Mérieux NutriSciences
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Analytical Approach
- Plasma-Based Spectrometry
- Atomic Absorption Methods
- Other Techniques
Sample Category
- Food and Feed Samples
- Water and Environmental Samples
- Other Product and Process Samples
Customer Model
- Outsourced Laboratory Services
- In-House Testing Workflows
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Heavy Metal Testing Market is estimated at US$3.20 billion in 2026, covering defined analytical workflows for food, environmental, water, and nonclinical product samples.
The Heavy Metal Testing Market is projected to reach US$5.20 billion by 2033, implying a 7.18% CAGR and US$2.00 billion additional opportunity.
A comparable technology leader is not established; Plasma-Based Spectrometry and Atomic Absorption Methods serve different matrix, analyte, reporting-limit, and customer decision requirements.
A comparable fastest-growing region remains unverified; Asia Pacific offers identifiable opportunities linked to food supply chains, industrial customers, and established laboratory-service networks.
Competition depends on validated method scope, dependable turnaround, sample logistics, and technical support, with international networks and regional specialists addressing different customer needs.
Related Reports
Polymer Emulsion Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Polymer emulsion market to grow from US$44.8 Bn in 2026 to US$66.5 Bn by 2033 at 5.8% CAGR. Explore products, applications, end-use industries and regions.
On The Go Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On the go packaging market to grow from US$2.19 Bn in 2026 to US$3.00 Bn by 2033 at 4.6% CAGR. Explore materials, products, applications and regions.
Nylon 6 Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Nylon 6 market to reach US$ 26.95 billion by 2033 at a 5.6% CAGR. Explore product forms, applications, feedstocks, leading companies and regional trends.
Vitamin A-Acetate Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Vitamin A-acetate market to reach US$ 2.68 billion by 2033 at a 5.9% CAGR. Explore forms, grades, applications, leading companies and regional trends.
Spinosad Active Ingredient Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Spinosad active ingredient market to reach US$ 1.257 billion by 2033 at an 8.6% CAGR. Explore forms, crops, applications, companies and regional trends.
D-Psicose (Allulose) Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
D-psicose (allulose) market to reach US$ 0.749 billion by 2033 at a 15.7% CAGR. Explore forms, applications, sales channels and regional trends.