


Heavy Duty Trucks Market
Heavy Duty Trucks Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Heavy Duty Trucks Market Size and Trend Analysis
What supports growth in heavy duty trucks?
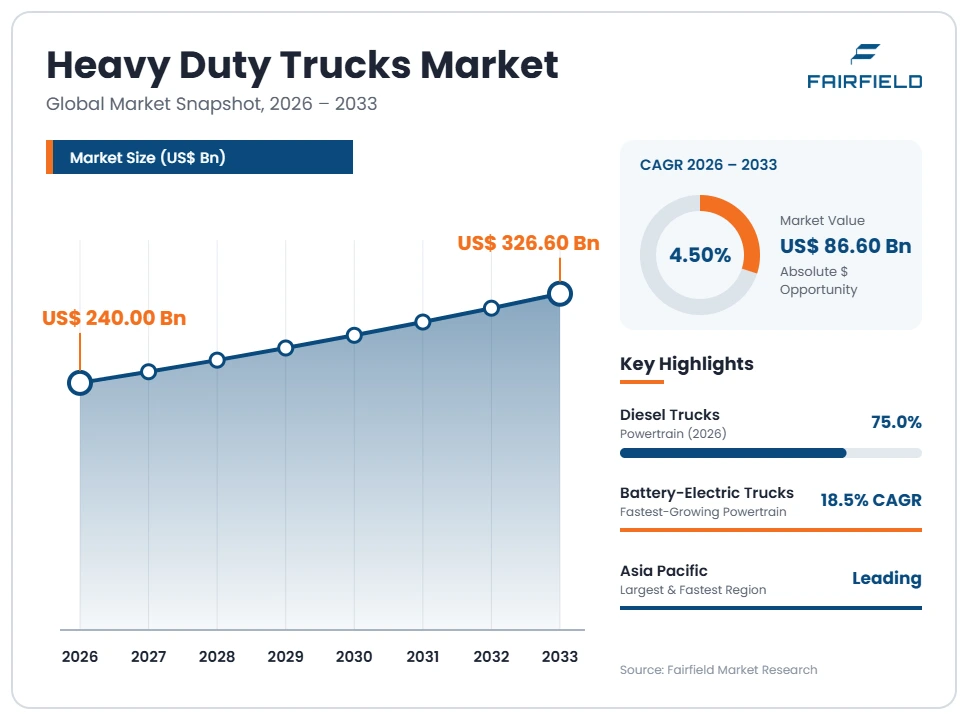
The global Heavy Duty Trucks market size is expected to be valued at US$240.00 billion in 2026 and projected to reach US$326.60 billion by 2033, growing at a CAGR of 4.50% between 2026 and 2033. Fleet purchasing combines replacement needs with demand for reliable freight and vocational capacity. Suppliers must address operating cost, vehicle availability, and service coverage rather than depend solely on new powertrain announcements.
During 2020–2025, production disruption and changing freight conditions complicated procurement, while manufacturers continued developing alternative powertrains. The selected benchmark reports historical growth of 4.3%; back-calculation implies a 2025 market near US$229.67 billion. Freight renewal, construction requirements, and improvements in vehicle productivity support the forecast. Diesel remains commercially important, while electrification advances where routes and charging arrangements fit. Financing constraints and uncertain residual values can delay purchases even when transport requirements remain substantial.
Key Report Takeaways
- By Powertrain: Diesel Trucks account for approximately 75% of the selected 2026 benchmark, while Battery-Electric Trucks have the strongest forecast growth at roughly 18.5% annually. Charging access, predictable routes, and payload requirements determine where electric alternatives become operationally credible.
- By Configuration: Tractor Units serve articulated freight operations, while Rigid Trucks support body-specific and vocational requirements. Their purchasing economics differ because trailers, body equipment, and utilization patterns vary. Comparable shares for this independently defined configuration framework are not assigned.
- By Application: Freight Transport provides an established demand base, while Construction and Industrial Operations requires vehicles configured for demanding site conditions. Municipal and Other Services adds distinct operating needs. Growth prospects should follow actual fleet requirements rather than assume every infrastructure announcement generates truck orders.
- By Geography: Asia Pacific combines the largest position and fastest-growth direction in the selected benchmark. North America and Europe retain substantial manufacturing and service capabilities. These regional roles imply different commercial priorities, from fleet scale to powertrain integration and aftermarket support.
- By Ownership Economics: Uptime, financing, and maintenance influence purchasing alongside vehicle price. PACCAR documents integrated truck, parts, leasing, and finance activities, illustrating a broader customer proposition. The opportunity is to improve fleet productivity without confusing recurring service revenue with new-vehicle market value.
Global Heavy Duty Trucks Market Trends and Insights
Drivers Impact Analysis
The impact ratings below are qualitative assessments of purchasing relevance, not measured percentage additions to the forecast.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Fleet replacement and freight reliability | High | All five standard regions | Short term (≤2 years) |
| Improved powertrain and vehicle productivity | Medium | Asia Pacific; Europe; North America | Medium term (2–4 years) |
Heavy Duty Trucks Replacement Demand Rewards Reliable Fleet Economics
Fleet replacement supports purchasing when maintaining older equipment becomes less attractive than acquiring a suitable new truck. Operators weigh repair frequency, fuel consumption, driver acceptance, and the cost of missed deliveries. A replacement decision can remain necessary during a weak freight cycle, although fleets may extend ownership periods or reduce order quantities. The commercial opportunity depends on transport economics; freight growth and truck sales do not always move together.
PACCAR’s business combines truck production with parts and financial services, demonstrating the importance of ownership support. Its published regional industry indicators also show why manufacturers monitor different markets separately. Heavy commercial vehicles require dependable service networks and appropriate configurations for their assigned work. Dealers can support purchasing through maintenance planning and realistic delivery commitments. Suppliers should state operating assumptions rather than rely on purchase price or unsupported productivity claims.
Heavy Duty Trucks Powertrain Development Broadens Operational Choices
Powertrain development supports demand by giving fleets more ways to match a vehicle with its duty cycle. Diesel improvements remain relevant for routes requiring established fueling and broad service access. Battery-electric trucks can suit operations with predictable distances and charging windows. Gas and hydrogen-related options address other use cases, but their suitability depends on fuel supply, equipment availability, and commercial conditions. Purchasing should compare operating plans rather than headline range figures.
Volvo Trucks announced a broader powertrain program in May 2026, while Daimler Truck has brought a battery-electric long-haul platform into series production. These developments establish supplier activity without proving identical adoption across all routes. Heavy-duty electric trucks create additional work in charging design and scheduling. Manufacturers can strengthen customer confidence through route assessment and appropriate service support. Alternative powertrains expand choice, but fleets still require evidence that the proposed configuration can complete its assigned tasks economically.
Restraints Impact Analysis
Capital exposure and infrastructure readiness can constrain procurement even where customer interest in a new platform is strong.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Financing and residual-value uncertainty | High | All five standard regions | Short term (≤2 years) |
| Alternative-energy infrastructure constraints | High | Electrification and hydrogen corridors | Medium term (2–4 years) |
Heavy Duty Trucks Financing Costs Can Delay Fleet Renewal
Financing constraints can postpone truck replacement when operators cannot recover higher ownership costs through freight rates or contract terms. A vehicle purchase may require a deposit, ongoing debt service, insurance, and additional working capital. For unfamiliar technologies, buyers also face uncertainty about resale value and long-term maintenance. Smaller operators are particularly exposed because one unavailable truck can disrupt a significant portion of their fleet. Demand for transport therefore does not automatically create immediate purchasing capacity.
Specific cost sources include interest, body integration, tires, maintenance reserves, and the infrastructure associated with a different powertrain. PACCAR’s finance and leasing activities illustrate the industry’s use of ownership alternatives, although any particular financing offer depends on credit and market conditions. Manufacturers can support conversion with clear warranty provisions and realistic operating assumptions. Buyers should compare total ownership exposure across equivalent tasks. Lower energy costs help only within a workable financing and utilization plan.
Heavy Duty Trucks Energy Infrastructure Limits Route Conversion
Energy infrastructure can restrict deployment when an alternative-powertrain truck is available before the required charging or fuel supply is dependable. A depot may need electrical upgrades, space for chargers, and sufficient connection capacity. Long-distance operations can depend on access beyond the home base. Charging queues, equipment failures, or incompatible schedules can reduce utilization. These constraints make route suitability central to procurement; nominal range cannot replace a deployment plan.
Infrastructure cost sources include grid connection, civil works, chargers, energy-management equipment, and maintenance arrangements. Hydrogen deployments require a different supply and refueling assessment. Tata Motors’ hydrogen-truck trials demonstrate active evaluation, but trials are not evidence that a universal commercial fuel network exists. Operators can reduce risk through staged deployment on defined routes. Suppliers should establish clear responsibilities for vehicles, energy equipment, and operational support. A coordinated project offers a stronger purchasing case than an isolated vehicle sale with unresolved energy access.
Market Opportunities
Heavy Duty Trucks Depot Electrification Creates Integration Revenue
Depot-based electrification creates a revenue opportunity around a complete transport assignment rather than a standalone electric truck. Fleets operating repeatable routes can assess vehicle selection, charging windows, energy supply, and maintenance together. A manufacturer or service partner can help configure that package and reduce the number of unresolved decisions facing the buyer. The opportunity is particularly relevant where vehicles return to a known site and the operator can measure how the new system affects daily dispatch.
MAN, within TRATON, began series production of battery-electric heavy-duty trucks in June 2025, providing an identifiable product foundation. Charging providers, utilities, installers, and finance partners can participate alongside vehicle manufacturers. Commercial value requires viable routes and clear responsibilities. Customers should evaluate availability, payload, and charging schedules before expansion. Integration support can generate revenue, but it should remain distinct from vehicle revenue when describing the size of the underlying truck market.
Heavy Duty Trucks Lifecycle Support Extends Customer Value
Lifecycle support creates an additional opportunity when operators need predictable maintenance and easier access to replacement parts. A truck’s economic contribution depends on availability over its ownership period, not only its initial specification. Connected fleet management can help organize inspections and identify service requirements, provided the data supports practical decisions. Manufacturers and dealers can pursue service contracts, remanufactured components, and maintenance planning where these offerings address customer capacity constraints and reduce the disruption associated with unplanned repairs.
PACCAR describes investment in aftermarket capabilities and engine remanufacturing, illustrating an established commercial route. Similar opportunities can arise for alternative-powertrain fleets that require specialist support. Dealers, component suppliers, and service providers can capture demand if contract scope, response expectations, and exclusions are understandable. Operators should distinguish genuinely useful support from subscriptions that duplicate internal processes. Customer needs continue after delivery, but service value depends on execution and must remain separate from new-truck sales.
Segment Analysis
- By Powertrain: Heavy Duty Trucks Diesel Leadership Coexists With Electric Expansion
Diesel Trucks retain leadership in the selected benchmark because fleets can rely on established fueling, maintenance familiarity, and broad product availability. That position does not prevent electric growth; it reflects the difference between the existing purchasing base and the rate of expansion from a smaller segment. Battery-Electric Trucks offer the stronger forecast direction where energy infrastructure and operating schedules fit. Daimler Truck and Volvo Group provide directly verifiable examples of manufacturers developing that commercial offering.
Natural-Gas Trucks and Other Powertrains serve additional customer requirements. Hybrid systems and hydrogen technologies fall within the latter category, with individual projects requiring separate assessment. Renewable diesel compatibility is treated as a fuel attribute within the relevant combustion category, avoiding duplicate vehicle counts. A fleet should compare payload, route completion, energy access, and support before choosing. The business implication is to maintain multiple powertrain propositions while building deployment evidence for each, rather than assume one technology suits all heavy transport.
- By Configuration: Heavy Duty Trucks Articulated and Rigid Platforms Differ
Tractor Units support articulated operations where a powered vehicle can work with different trailers. Their commercial value depends on matching the tractor with cargo, distance, and trailer availability. Rigid Trucks carry their working body on the vehicle itself and can suit construction, distribution, municipal, or other vocational uses. This configuration distinction avoids placing body types and vehicle architectures in the same overlapping category. It also clarifies why the complete purchasing specification extends beyond an engine and cab.
PACCAR’s truck brands and the portfolios of TRATON serve different configurations and customer tasks. Bodybuilders, dealers, and component suppliers influence compatibility and completion schedules. Configuration-specific shares and fastest-growth rates are not assigned because public figures use inconsistent classifications. Suppliers should help customers define axle, body, coupling, and equipment requirements early. Good configuration support can improve quotation quality and reduce rework. A broad heavy-duty label does not establish whether a vehicle is suitable for a specific combination or load.
- By Application: Heavy Duty Trucks Freight and Vocational Requirements Differ
Freight Transport provides a large and established purchasing context for heavy duty trucks, including intercity and regional work. Fleet buyers emphasize dependable delivery, operating cost, and driver acceptance. Construction and Industrial Operations places more weight on site access, equipment integration, and demanding load conditions. Municipal and Other Services includes remaining assignments with specific duty cycles. These independent application groups are defined by primary use so that a vehicle is not counted repeatedly across freight, logistics, and customer-industry labels.
Tata Motors’ commercial-vehicle offering and Volvo Trucks’ heavy-duty portfolio demonstrate the range of tasks manufacturers address. Demand can respond differently to construction projects, freight contracts, and public procurement cycles. No comparable share or fastest-growth rate is assigned to these independently defined groups. Suppliers should maintain application-specific configuration and support capabilities. A suitable product proposal explains how the vehicle completes its work, while a general market-growth narrative offers limited help in selecting equipment or planning production.
Geography Analysis
- Heavy Duty Trucks in North America Depend on Freight Cycles
North America combines an established heavy-truck market with extensive dealer and aftermarket requirements. The United States and Canada are central to the commercial activity described by PACCAR, whose brands include Kenworth and Peterbilt. Regional fleet decisions depend on freight conditions, financing, equipment age, and the ability to maintain service availability across operating routes.
Customers evaluating electric trucks also need suitable depot power and a realistic route plan. Manufacturers can support adoption through configuration advice, local maintenance capacity, and transparent warranties. Suppliers should therefore distinguish quoted interest, orders, and delivered vehicles when assessing demand. Regional market size is not inferred from the revenue of one manufacturer or a single national registration series.
- Heavy Duty Trucks in Europe Expand Electric Production
Europe offers directly documented electric-truck production alongside established combustion platforms. Germany is a major manufacturing location for Daimler Truck and MAN, while Sweden hosts substantial activity from Volvo Group and Scania. France and the United Kingdom are also relevant operating markets, with cross-border assignments requiring consistent vehicle support and energy planning.
Commercial opportunities depend on the customer’s transport task rather than a uniform regional conversion schedule. Long-haul freight, regional deliveries, and municipal work have different charging and service requirements. Manufacturers can strengthen proposals through route analysis and coordination with infrastructure providers. Fleet buyers should check the legal requirements applicable to their own vehicles and dates rather than rely on generalized emissions claims. The region’s production launches demonstrate progress, but not identical operating economics for every customer.
- Which Region Is Leading the Heavy Duty Trucks Market?
Asia Pacific leads the selected benchmark, supported by large freight, manufacturing, and construction requirements. China and India are important commercial focus areas, while Japan contributes established vehicle manufacturing capabilities. Regional demand spans multiple price points and duty cycles, making a single product specification inadequate for the whole market.
- Which Region Is Growing Fastest in Heavy Duty Trucks?
Asia Pacific also has the fastest-growth direction in the selected forecast. Tata Motors’ hydrogen trials in India illustrate technology evaluation alongside conventional truck demand. Manufacturers can pursue localized configuration, service partnerships, and financing support. Growth still depends on project execution, customer economics, and energy availability. Suppliers should assess national requirements separately and avoid treating regional infrastructure plans as guaranteed orders or assuming that a trial establishes large-scale commercial adoption.
- Heavy Duty Trucks in Latin America Require Durable Products and Financing Access
Latin America presents opportunities in freight, agriculture-linked transport, and construction-related operations. Brazil and Mexico are relevant markets for manufacturer and distributor assessment. TRATON’s operations include Volkswagen Truck & Bus and Scania, while PACCAR documents regional truck activity. These examples demonstrate participation without establishing a single comparable regional market share.
Financing conditions, maintenance access, and delivered vehicle cost can constrain purchasing. Operators need products suited to their routes and loads, with practical access to parts. Alternative-powertrain opportunities should follow specific infrastructure and fleet requirements rather than assume that an imported product will be operationally suitable. Manufacturers can improve the customer proposition through local support and clear ownership-cost comparisons. The strongest commercial case connects vehicle durability and service availability with a manageable procurement and financing plan.
- Heavy Duty Trucks in Middle East & Africa Need Route-Specific Support
Middle East & Africa offers selective demand across freight, construction, industrial activity, and public services. Saudi Arabia and the United Arab Emirates are prospective markets for project-related transport, while South Africa is relevant to established commercial-vehicle operations. These country examples identify possible sales priorities, not verified regional leadership or growth rankings.
Distance, heat, demanding work sites, financing, and service access can shape purchasing. Customers should assess cooling requirements, filtration, parts availability, and support capacity when selecting equipment. Alternative powertrains require an additional energy-supply evaluation. Manufacturers and dealers can develop opportunities by matching configurations to local tasks and maintaining dependable technical support. Large project announcements may justify customer outreach, but confirmed schedules, procurement responsibilities, and operating requirements are needed before treating them as a dependable vehicle-sales pipeline.
Competitive Landscape
Heavy duty truck competition is concentrated around manufacturers with engineering scale, manufacturing capability, and established service networks. A high concentration assessment is qualitative rather than a calculated concentration ratio. Daimler Truck, Volvo Group, TRATON, PACCAR, and Tata Motors represent directly verified participation. Their inclusion does not imply identical geographic coverage or technology readiness. Parent groups and their brands are treated together to avoid counting the same manufacturer as several independent competitors.
Suppliers compete on operating economics, reliability, configuration, driver acceptance, and support. Dealers and financial services can influence the purchasing decision as strongly as a particular vehicle feature. New entrants may find opportunities in defined electric or specialist applications, but they still need manufacturing discipline and dependable after-sales provision. Customers should evaluate route fit and support commitments rather than compare platforms solely through headline battery capacity, range, or announced development spending.
Recent developments show a mix of production launches and evaluation programs. Daimler Truck began series production of the Mercedes-Benz eActros 600 in November 2024. MAN followed with heavy-duty electric series production in June 2025, while Tata Motors announced hydrogen trials earlier that year. Volvo Trucks subsequently broadened its powertrain program. These milestones have different commercial meanings: trials create evidence, production enables supply, and customer deployment determines realized market adoption.
Strategic direction will remain tied to customer productivity and the ability to support multiple operating requirements. Manufacturers can combine conventional improvements with selective electrification. Partnerships may improve infrastructure and service, provided responsibilities are explicit. Vehicle revenue must remain distinct from finance, parts, and infrastructure spending. Assessment should consider customer requirements without predicting technology winners.
Recent Industry Developments
- November 2024: Daimler Truck started series production of the Mercedes-Benz eActros 600, extending its battery-electric long-haul offering.
- March 2025: Tata Motors announced hydrogen-powered heavy-truck trials in India, supporting evaluation under defined operating conditions.
- June 2025: MAN began battery-electric heavy-truck series production in Munich, adding production capability within TRATON.
- May 2026: Volvo Trucks announced a broader powertrain program, supporting multiple routes toward lower-emission transport.
Companies Covered in the Report
Daimler Truck; Volvo Group; TRATON; PACCAR; Tata Motors. Brand references include Mercedes-Benz Trucks, Volvo Trucks, MAN, Scania, Volkswagen Truck & Bus, Kenworth, and Peterbilt.
Heavy Duty Trucks Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$240.00 Billion |
| Market Size 2033 | US$326.60 Billion |
| CAGR 2026–2033 | 4.50% |
| Absolute Dollar Opportunity | US$86.60 Billion |
| Largest Market | Asia Pacific |
| Fastest-Growing Market | Asia Pacific |
| Market Concentration | High, qualitative assessment |
| Major Players | Daimler Truck, Volvo Group, TRATON, PACCAR, Tata Motors |
Heavy Duty Trucks Market Segmentation
Powertrain
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
Configuration
- Tractor Units
- Rigid Trucks
Application
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Heavy Duty Trucks Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Heavy Duty Trucks Replacement Demand Rewards Reliable Fleet Economics
- Heavy Duty Trucks Powertrain Development Broadens Operational Choices
- Restraints
- Heavy Duty Trucks Financing Costs Can Delay Fleet Renewal
- Heavy Duty Trucks Energy Infrastructure Limits Route Conversion
- Market Opportunities
- Heavy Duty Trucks Depot Electrification Creates Integration Revenue
- Heavy Duty Trucks Lifecycle Support Extends Customer Value
- Drivers
- Global Heavy Duty Trucks Market Outlook, 2020–2033
- Global Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- Global Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- Global Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- Global Heavy Duty Trucks Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- North America Heavy Duty Trucks Market Outlook, 2020–2033
- North America Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- North America Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- North America Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- North America Heavy Duty Trucks Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- United States Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- United States Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Canada Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Canada Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Canada Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- North America Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Europe Heavy Duty Trucks Market Outlook, 2020–2033
- Europe Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- Europe Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- Europe Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- Europe Heavy Duty Trucks Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Germany Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Germany Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Sweden Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Sweden Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Sweden Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- France Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- France Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- France Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- United Kingdom Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- United Kingdom Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- United Kingdom Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Europe Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Asia Pacific Heavy Duty Trucks Market Outlook, 2020–2033
- Asia Pacific Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- Asia Pacific Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- Asia Pacific Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- Asia Pacific Heavy Duty Trucks Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- China Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- China Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- India Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- India Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- India Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Japan Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Japan Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Japan Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Asia Pacific Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Latin America Heavy Duty Trucks Market Outlook, 2020–2033
- Latin America Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- Latin America Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- Latin America Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- Latin America Heavy Duty Trucks Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Brazil Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Brazil Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Mexico Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Mexico Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Mexico Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Latin America Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Middle East & Africa Heavy Duty Trucks Market Outlook, 2020–2033
- Middle East & Africa Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
- Middle East & Africa Heavy Duty Trucks Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Tractor Units
- Rigid Trucks
- Middle East & Africa Heavy Duty Trucks Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
- Middle East & Africa Heavy Duty Trucks Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- Saudi Arabia Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- Saudi Arabia Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- United Arab Emirates Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- United Arab Emirates Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- United Arab Emirates Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- South Africa Heavy Duty Trucks Market Outlook, by Powertrain, 2020–2033
- South Africa Heavy Duty Trucks Market Outlook, by Configuration, 2020–2033
- South Africa Heavy Duty Trucks Market Outlook, by Application, 2020–2033
- Middle East & Africa Heavy Duty Trucks Market Outlook, by Powertrain, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Daimler Truck
- Volvo Group
- TRATON
- PACCAR
- Tata Motors
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Powertrain
- Diesel Trucks
- Battery-Electric Trucks
- Natural-Gas Trucks
- Other Powertrains
Configuration
- Tractor Units
- Rigid Trucks
Application
- Freight Transport
- Construction and Industrial Operations
- Municipal and Other Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The Heavy Duty Trucks Market is estimated at US$240.00 billion in 2026, covering new heavy commercial vehicles across defined freight and vocational applications.
The Heavy Duty Trucks Market is projected to reach US$326.60 billion by 2033, implying 4.50% annual growth and US$86.60 billion additional opportunity.
Diesel Trucks lead the selected benchmark, supported by established fueling and service access, while fleet suitability continues to depend on configuration and operating requirements.
Battery-Electric Trucks have the fastest-growth outlook in the selected powertrain benchmark, with adoption depending on charging access, route suitability, and manageable ownership costs.
Asia Pacific leads the selected Heavy Duty Trucks Market benchmark and has its fastest regional growth direction, supported by varied freight and construction requirements.
Related Reports
Off-highway Electric Vehicle Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global off-highway electric vehicle market is valued at US$3.64 billion in 2026, reaching US$10.11 billion by 2033, growing at a 15.7% CAGR
Leisure Boat Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The leisure boat market is projected to grow from US$ 53.90 billion in 2026 to US$ 81.04 billion by 2033 at a 6.0% CAGR.
Hydrogen Aircraft Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The hydrogen aircraft market is forecast to grow from US$ 1.20 billion in 2026 to US$ 7.60 billion by 2033 at a 33.6% CAGR.
Exhaust Flexible Couplings Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The exhaust flexible couplings market is projected to grow from US$ 756.4 million in 2026 to US$ 1,057.3 million by 2033 at a 4.9% CAGR.
Automotive VVT System Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The automotive VVT system market is projected to grow from US$ 77.20 billion in 2026 to US$ 118.42 billion by 2033 at a 6.3% CAGR.
Used Vehicle Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global used vehicle market is valued at US$1.7 trillion in 2026, reaching US$2.6 trillion by 2033, growing at a 6.3% CAGR