


In-car Audio System Market
In-car Audio System Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
In-car Audio System Market Size and Trend Analysis
What Is Driving Growth in Vehicle Audio Demand?
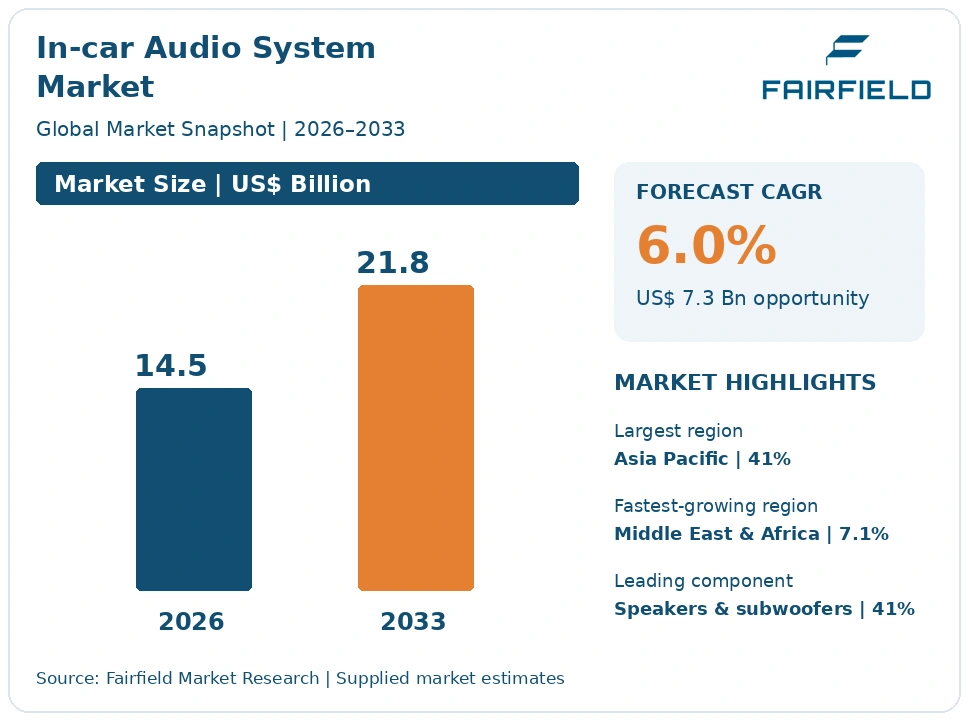
The global In-car Audio System market size is expected to be valued at US$ 14.5 billion in 2026 and projected to reach US$ 21.8 billion by 2033, growing at a CAGR of 6.0% between 2026 and 2033.
Between 2020 and 2025 the market grew at roughly 4.6% a year, held back by semiconductor shortages and weak vehicle output before production recovered. Growth now comes from content per vehicle rather than from vehicle volume. Premium branded systems have moved down from luxury cars into mainstream trims, speaker counts and amplifier channels have risen, and audio processing has become a software function running on shared compute. Working against this, the independent aftermarket keeps shrinking as factory systems improve and dashboards become harder to modify. The overall direction is a value-led automotive electronics market where original equipment fitment dominates and where differentiation shifts steadily from loudspeakers toward signal processing and licensed sound tuning.
Key Report Takeaways
- By Component, Speakers, Tweeters and Subwoofers held 41% share in 2026, while Audio Processing Software is projected to expand at a 9.4% CAGR through 2033, as tuning, noise control and spatial rendering move onto shared vehicle compute.
- By Sales Channel, Original Equipment held 74% share in 2026, while Dealer-Fitted and Accessory installations are projected to grow at a 6.9% CAGR through 2033, because branded upgrades sell best at the point of vehicle purchase.
- By Vehicle Class, Premium and Luxury Passenger Cars held 36% share in 2026, while Mid-Range Passenger Cars are projected to advance at a 7.0% CAGR through 2033, as branded audio migrates down the model range as a paid option.
- By System Tier, Mid-Tier Systems held 42% share in 2026, while Premium Branded Systems are projected to grow at a 7.8% CAGR through 2033, driven by option take rates that carry unusually high margin for carmakers.
- By geography, Asia Pacific held 41% share in 2026, while Middle East & Africa is projected to grow fastest at a 7.1% CAGR through 2033, from a small base lifted by vehicle parc expansion and high premium option take rates.
Global In-car Audio System Market Trends and Insights
Drivers Impact Analysis
The two drivers below explain why audio content per vehicle keeps rising even where unit volumes do not.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Migration of premium branded audio into mainstream vehicle trims | High | Asia Pacific, Europe, North America | Medium term (2–4 years) |
| Quiet electric vehicle cabins raising the perceived audio quality bar | High | Global, led by Asia Pacific and Europe | Long term (≥4 years) |
Branded Audio Has Become One of the Few Remaining Cabin Differentiators
Audio is now one of the few ways a carmaker can make a cabin feel distinct, and that has pulled premium systems down the model range. Powertrains are converging, interiors share switchgear and screens, and buyers struggle to tell competing models apart on a test drive. A named audio brand on the speaker grille gives a showroom story and a visible upgrade. Carmakers price these systems as options or trim bundles, which lifts revenue per vehicle without changing the vehicle itself.
The mechanism is margin, not acoustics. A branded system typically adds speakers, more amplifier channels and a licensed tuning package at modest incremental cost, yet the option price carries margin well above the vehicle average. Suppliers earn licence revenue and component content together. The result is more channels, more enclosure volume and more digital signal processing in cars that would previously have shipped with a four-speaker base system.
Quiet Electric Cabins Raise the Quality Bar Facing In-Vehicle Audio Systems
Electric vehicles change the audio brief because there is no engine noise to mask anything. Removing combustion sound exposes tyre roar, wind turbulence, suspension impacts and electric motor whine that drivers never previously noticed. The perceived quality bar for the sound system rises accordingly, since listeners judge clarity against a quieter background. Carmakers respond with more capable systems, added microphones and active noise control, pushing audio content per electric vehicle above comparable combustion models.
The engineering causes are specific. Without an alternator, the audio system draws from a high-voltage architecture through converters, which changes power budgeting and electromagnetic compatibility work under UNECE Regulation No. 10. Battery packs occupy floor space that once held wiring and enclosures, so speakers move into doors, pillars and headliners. Active noise cancellation needs cabin microphones, accelerometers and low-latency processing, all of which add components and software that did not exist in older cars.
Restraints Impact Analysis
The two restraints below limit specification levels, upsell rates and long-run aftermarket demand.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Copper and magnet mass in speaker systems working against efficiency targets | Medium | Global, strongest in Europe and Asia Pacific | Medium term (2–4 years) |
| Buyers cannot distinguish system tiers in a showroom | Medium | North America, Europe, Latin America | Long term (≥4 years) |
Speaker Copper and Magnet Mass Collide With Vehicle Weight and Cost Targets
Physical mass is a genuine constraint on how many speakers a vehicle programme can accept. A sixteen-channel system adds voice-coil copper, neodymium or ferrite magnets, steel baskets, amplifier heat sinks and a wiring harness, and every kilogram works against range and efficiency targets. Vehicle programmes run strict weight and cost budgets per subsystem, so audio engineers compete with seats, glazing and insulation for the same allowance. That competition caps specification in high-volume mainstream models.
The cost sources are specific materials and the harness, not vague expense. Copper pricing affects both voice coils and the multi-conductor cabling that connects a distributed amplifier to a dozen or more drivers. Rare earth content in neodymium magnets carries supply and price risk, which pushes some designers back to heavier ferrite alternatives. Amplifier thermal management adds metal and packaging volume, and each added enclosure removes cabin or luggage space that product planners defend closely.
Showroom Buyers Cannot Hear Tier Differences, So Upsell Rests on Brand Names
Most buyers cannot distinguish a mid-tier system from a premium one during a dealership visit, and that weakens the entire upsell case. Showrooms are noisy, test drives are short, and source material is rarely consistent. Measured performance therefore does little selling work. Option take rates depend on the badge, the speaker grille design and the trim bundle rather than on acoustic merit, which limits how much carmakers can charge for genuine engineering improvements.
The underlying cause is that audio quality is subjective and hard to demonstrate under sales conditions. Suppliers cannot publish comparable specifications the way display or battery suppliers can, so brand licensing substitutes for proof. This favours a handful of recognised names and makes it difficult for technically strong but unbranded suppliers to earn premium pricing. It also discourages investment in improvements that cannot be heard within a two-minute demonstration.
Market Opportunities
Two revenue pools sit beyond conventional speaker and head unit content and remain only partly served.
Software-Defined Audio and Over-the-Air Tuning Shift Value Toward Processing
Audio is becoming a software function, and that opens a licensing and update revenue pool that hardware suppliers never had. Tuning profiles, equalisation, spatial rendering, in-car communication and noise control increasingly run as applications on shared vehicle compute rather than on dedicated boxes. Because the code can be updated after delivery, carmakers can sell improved sound packages, new listening modes or additional channels during the ownership period rather than only at the point of sale.
Suppliers with signal processing expertise, audio brands with licensable tuning and tier-one integrators able to validate software on central compute are positioned to capture this pool. Demand comes from carmakers consolidating electronic control units and seeking post-sale revenue. UNECE Regulations No. 155 and No. 156 on cybersecurity and software update management give this a compliance framework, because audio code shipped to connected head units must now move through a managed update process.
Exterior Alerting Sound and Engine Sound Enhancement Form a Separate Audio Workload
Exterior and synthesised sound is a distinct revenue pool that sits beside the entertainment system. Quiet vehicles must emit an audible signal at low speed, which requires an external sound generator, an amplifier channel, a weatherproof transducer and tuned sound files. Inside the cabin, engine sound enhancement delivers an acceleration character that an electric powertrain does not produce naturally. Both workloads carry their own hardware, their own tuning effort and their own validation testing.
Suppliers already producing amplifiers, transducers and sound design content are best placed to serve this demand, which comes from every carmaker launching electrified models. UNECE Regulation No. 138 sets the audibility requirements for quiet road transport vehicles in markets applying United Nations rules, and FMVSS 141 sets the equivalent minimum sound requirement in the United States. Compliance is mandatory, so this content attaches to vehicles regardless of audio trim level.
Segment Analysis
By Component: Speakers Lead Revenue While Audio Software Expands Fastest
Speakers, Tweeters and Subwoofers held 41% share in 2026, because transducer count rises with every tier upgrade and because speakers remain the most visible, most frequently multiplied component in the system. A premium cabin may carry more than twenty drivers. Audio Processing Software is the fastest-growing component at a 9.4% CAGR through 2033, as tuning, active noise cancellation, in-car communication and spatial rendering move from fixed hardware into updatable code on shared compute. Amplifiers and digital signal processors continue to consolidate into fewer, more powerful units, while microphone counts rise to serve noise control and voice interaction. The commercial implication is a slow transfer of value from metal and magnets toward licensed algorithms, which changes who captures margin in a vehicle audio programme.
By Sales Channel: Factory Fitment Dominates While Dealer Upgrades Outgrow Retail
Original Equipment held 74% share in 2026, reflecting integrated systems that are designed into the vehicle architecture and cannot easily be replaced later. Dealer-Fitted and Accessory installations form the fastest-growing channel at a 6.9% CAGR through 2033, because branded upgrade packages sell most effectively while the customer is already choosing options and financing the purchase. The Independent Aftermarket continues its long-run decline, growing at barely 2% a year. Factory systems now meet most expectations, dashboards are bonded assemblies built around fixed displays, and removing a head unit can disable climate control, driver assistance warnings and connectivity. Retrofit demand survives mainly in older vehicles, commercial fleets and enthusiast installations. The implication is that suppliers must win design-in programmes years ahead of production or lose access entirely.
By Vehicle Class: Luxury Cars Lead Value as Mid-Range Models Grow Quickest
Premium and Luxury Passenger Cars held 36% share in 2026, because content per vehicle in this class runs several times that of an entry model, with more channels, more amplifier power and bespoke acoustic tuning. Mid-Range Passenger Cars are growing fastest at a 7.0% CAGR through 2033, as branded audio migrates down the range to become a paid option on volume models. This migration is the single clearest structural movement in vehicle audio. Entry and Economy Passenger Cars still ship modest systems constrained by cost, while light and heavy commercial vehicles buy for durability, hands-free communication and noise control rather than musical performance. The business implication is that mainstream programmes, not flagship cars, now decide a supplier’s total volume and licensing revenue.
By System Tier: Mid-Tier Systems Hold the Centre While Premium Branded Packages Surge
Mid-Tier Systems held 42% share in 2026, occupying the centre of the market with six to ten speakers, a modest external amplifier and factory tuning without a licensed brand. Premium Branded Systems are expanding fastest at a 7.8% CAGR through 2033, since option take rates carry margin that carmakers value highly and since the badge performs the selling work that measured specifications cannot. Base Audio Systems are losing share as even entry trims gain more channels and digital processing. Electrified models accelerate the shift, because a quiet cabin makes a weak system conspicuous. For suppliers, the practical consequence is that tier strategy, licence terms and the ability to scale one acoustic platform across several trims matter more than absolute acoustic performance.
Geography Analysis
North America Combines High Premium Take Rates With a Shrinking Retrofit Base
North America held 24% share of vehicle audio revenue in 2026 and is projected to grow at a 5.1% CAGR through 2033. The United States, Canada and Mexico form an integrated production base, and large body styles such as pickups and full-size sport utility vehicles carry generous cabin volume that supports many speakers and powerful subwoofers. Premium branded option take rates are among the highest anywhere, helped by high average transaction prices. FMVSS 141 requires a minimum audible sound from electric and hybrid vehicles at low speed, adding exterior sound content. The main regional change is the steady erosion of the once-dominant retrofit business, as bonded dashboards and integrated safety warnings make head unit replacement impractical for most owners.
Europe Sets the Compliance Agenda and Anchors Luxury Acoustic Engineering
Europe held 25% share in 2026 and is projected to grow at a 5.0% CAGR through 2033, the slowest pace of the five regions despite its technical leadership. Germany anchors luxury vehicle programmes where acoustic engineering reaches its highest content levels, and France, Italy, Spain and the United Kingdom add volume and specialist supply. Regulation originates here in practice: UNECE Regulations No. 155 and No. 156 on cybersecurity and software update management govern connected head units, UNECE Regulation No. 10 sets electromagnetic compatibility limits, and UNECE Regulation No. 138 mandates acoustic alerting on quiet vehicles. Interior noise measurement standards shape cabin targets. Slow vehicle output growth caps the region, so revenue gains depend almost entirely on rising content per car.
Which Region Is Leading the In-car Audio System Market?
Asia Pacific leads with 41% share in 2026 and is forecast to grow at a 6.8% CAGR through 2033, because the region builds more vehicles than anywhere else and because its electric models set the pace on audio content. China is the decisive market, where domestic brands use speaker count, immersive audio modes and karaoke features as explicit selling points on mainstream electric cars. Japan and South Korea contribute deep supplier capability in transducers, amplifiers and semiconductors, while India adds fast-rising volume at entry and mid price points. Cabin quietness in electric models has become a competitive claim in the region. The main change is that specification leadership now originates here rather than arriving from luxury programmes elsewhere.
Latin America Grows on Fleet Renewal Despite Tight Vehicle Affordability
Latin America accounted for 5% of the market in 2026 and is projected to grow at a 6.2% CAGR through 2033, with Brazil, Argentina, Colombia and Chile providing most demand. Vehicle production in Brazil supports local fitment of base and mid-tier systems, and fleet renewal in ride-hailing and corporate use lifts replacement volumes. Barriers are significant: affordability pressure keeps most buyers in entry trims, currency movement raises imported component costs, and premium branded options sell in small numbers outside major cities. Connectivity is nonetheless widely valued, so smartphone projection and hands-free calling often take priority over speaker count. The main change is that mid-tier systems with better microphones are becoming standard rather than optional on popular models.
Which Region Is Growing Fastest in the In-car Audio System Market?
Middle East & Africa is growing fastest, at a 7.1% CAGR through 2033 from a 5% share in 2026, the smallest base of the five regions. Gulf markets including Saudi Arabia and the United Arab Emirates show unusually strong appetite for premium branded systems on large sport utility vehicles, where long highway journeys make cabin quality a priority. South Africa and Morocco host vehicle assembly that supports local fitment. Barriers include heat and dust that stress transducers and amplifiers, uneven after-sales networks, and wide income dispersion that keeps most volume at base specification. The main change is fleet and government vehicle renewal programmes, which bring newer connected head units into service faster than private replacement alone would.
Competitive Landscape
The in-car audio system market is moderately concentrated, with a clear split between integration suppliers and licensed sound brands. Harman International holds a broad position spanning hardware, software and a portfolio of audio brands, while Panasonic Automotive Systems, Alps Alpine, Pioneer Corporation and Forvia supply head units, amplifiers and integrated cockpit electronics at scale. Bose Corporation competes across luxury and mainstream programmes. A second group of specialist acoustic names, including Bowers & Wilkins, Dynaudio, Burmester Audiosysteme, Bang & Olufsen and Focal, licenses tuning and branding into specific carmaker platforms.
Vendors compete on four things: acoustic tuning capability, system integration into the vehicle’s electronic architecture, brand value in the showroom, and cost per channel at volume. Winning a programme usually means proving that one acoustic platform can scale across several trims and several models without re-engineering. Sony Corporation, LG Electronics and Continental AG approach the market from infotainment and cockpit compute rather than from loudspeakers, which matters as audio becomes a software workload on shared processors. Semiconductor suppliers of audio amplifiers and processors increasingly shape what is possible.
Strategic activity concentrates on software capability, brand licensing portfolios and manufacturing footprint near vehicle assembly. Suppliers are building validation teams for over-the-air audio updates, expanding libraries of tuning content, and positioning for cockpit consolidation programmes where audio shares compute with displays and connectivity. Specialist acoustic brands pursue broader licensing across more carmakers to offset their limited hardware scale.
The common strategic direction is a move up the value chain from transducers toward processing, tuning and updatable content, alongside closer integration with cockpit electronics roadmaps and tighter management of copper, magnet and semiconductor supply.
In-car Audio System Industry Leaders
- Harman International
- Bose Corporation
- Alps Alpine
- Panasonic Automotive Systems
- Pioneer Corporation
Recent Industry Developments
July 2024: UNECE Regulations No. 155 and No. 156 on cybersecurity management and software update management became applicable to all newly registered vehicles in the European Union – connected head units and over-the-air audio tuning updates now sit inside a formal compliance regime that favours suppliers with certified processes.
July 2024: The second phase of the European Union General Safety Regulation applied to all newly registered vehicles, extending mandatory driver warning and alerting functions – audible warning output must now be designed alongside entertainment audio on a shared amplifier and speaker set.
September 2025: The European Union Data Act became applicable, setting access rules for data generated by connected products including vehicles – it affects how usage data from infotainment and audio systems may be shared with service providers and aftermarket businesses.
In-car Audio System Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 14.5 Billion |
| Market Size 2033 | US$ 21.8 Billion |
| CAGR 2026–2033 | 6.0% |
| Absolute Dollar Opportunity | US$ 7.3 Billion |
| Largest Market | Asia Pacific (41% share in 2026) |
| Fastest-Growing Market | Middle East & Africa (7.1% CAGR) |
| Market Concentration | Medium |
| Major Players | Harman International, Bose Corporation, Alps Alpine, Panasonic Automotive Systems |
This study covers factory-fitted and aftermarket vehicle audio across passenger cars and commercial vehicles, including speakers, tweeters, subwoofers, amplifiers, digital signal processors, head units, audio-capable infotainment, microphones and audio processing software. It excludes portable speakers, headphones, standalone telematics hardware and non-audio infotainment displays. The base year is 2025 and the forecast period runs from 2026 to 2033, with all values reported in US$ Billion.
In-car Audio System Market Segmentation
Component
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
Sales Channel
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
Vehicle Class
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
System Tier
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global In-car Audio System Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Branded Audio Has Become One of the Few Remaining Cabin Differentiators
- Quiet Electric Cabins Raise the Quality Bar Facing In-Vehicle Audio Systems
- Restraints
- Speaker Copper and Magnet Mass Collide With Vehicle Weight and Cost Targets
- Showroom Buyers Cannot Hear Tier Differences, So Upsell Rests on Brand Names
- Market Opportunities
- Software-Defined Audio and Over-the-Air Tuning Shift Value Toward Processing
- Exterior Alerting Sound and Engine Sound Enhancement Form a Separate Audio Workload
- Drivers
- Global In-car Audio System Market Outlook, 2020–2033
- Global In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- Global In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- Global In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Global In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- Global In-car Audio System Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- North America In-car Audio System Market Outlook, 2020–2033
- North America In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- North America In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- North America In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- North America In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- North America In-car Audio System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States In-car Audio System Market Outlook, by Component, 2020–2033
- United States In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- United States In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- United States In-car Audio System Market Outlook, by System Tier, 2020–2033
- Canada In-car Audio System Market Outlook, by Component, 2020–2033
- Canada In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Canada In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Canada In-car Audio System Market Outlook, by System Tier, 2020–2033
- Mexico In-car Audio System Market Outlook, by Component, 2020–2033
- Mexico In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Mexico In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Mexico In-car Audio System Market Outlook, by System Tier, 2020–2033
- North America In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Europe In-car Audio System Market Outlook, 2020–2033
- Europe In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- Europe In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- Europe In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Europe In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- Europe In-car Audio System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany In-car Audio System Market Outlook, by Component, 2020–2033
- Germany In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Germany In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Germany In-car Audio System Market Outlook, by System Tier, 2020–2033
- France In-car Audio System Market Outlook, by Component, 2020–2033
- France In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- France In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- France In-car Audio System Market Outlook, by System Tier, 2020–2033
- Italy In-car Audio System Market Outlook, by Component, 2020–2033
- Italy In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Italy In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Italy In-car Audio System Market Outlook, by System Tier, 2020–2033
- Spain In-car Audio System Market Outlook, by Component, 2020–2033
- Spain In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Spain In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Spain In-car Audio System Market Outlook, by System Tier, 2020–2033
- United Kingdom In-car Audio System Market Outlook, by Component, 2020–2033
- United Kingdom In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- United Kingdom In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- United Kingdom In-car Audio System Market Outlook, by System Tier, 2020–2033
- Europe In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Asia Pacific In-car Audio System Market Outlook, 2020–2033
- Asia Pacific In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- Asia Pacific In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- Asia Pacific In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Asia Pacific In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- Asia Pacific In-car Audio System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China In-car Audio System Market Outlook, by Component, 2020–2033
- China In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- China In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- China In-car Audio System Market Outlook, by System Tier, 2020–2033
- Japan In-car Audio System Market Outlook, by Component, 2020–2033
- Japan In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Japan In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Japan In-car Audio System Market Outlook, by System Tier, 2020–2033
- South Korea In-car Audio System Market Outlook, by Component, 2020–2033
- South Korea In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- South Korea In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- South Korea In-car Audio System Market Outlook, by System Tier, 2020–2033
- India In-car Audio System Market Outlook, by Component, 2020–2033
- India In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- India In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- India In-car Audio System Market Outlook, by System Tier, 2020–2033
- Asia Pacific In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Latin America In-car Audio System Market Outlook, 2020–2033
- Latin America In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- Latin America In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- Latin America In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Latin America In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- Latin America In-car Audio System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil In-car Audio System Market Outlook, by Component, 2020–2033
- Brazil In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Brazil In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Brazil In-car Audio System Market Outlook, by System Tier, 2020–2033
- Argentina In-car Audio System Market Outlook, by Component, 2020–2033
- Argentina In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Argentina In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Argentina In-car Audio System Market Outlook, by System Tier, 2020–2033
- Colombia In-car Audio System Market Outlook, by Component, 2020–2033
- Colombia In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Colombia In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Colombia In-car Audio System Market Outlook, by System Tier, 2020–2033
- Chile In-car Audio System Market Outlook, by Component, 2020–2033
- Chile In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Chile In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Chile In-car Audio System Market Outlook, by System Tier, 2020–2033
- Latin America In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Middle East & Africa In-car Audio System Market Outlook, 2020–2033
- Middle East & Africa In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
- Middle East & Africa In-car Audio System Market Outlook, by Sales Channel, Value (US$ Billion), 2020–2033
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
- Middle East & Africa In-car Audio System Market Outlook, by Vehicle Class, Value (US$ Billion), 2020–2033
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- Middle East & Africa In-car Audio System Market Outlook, by System Tier, Value (US$ Billion), 2020–2033
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
- Middle East & Africa In-car Audio System Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia In-car Audio System Market Outlook, by Component, 2020–2033
- Saudi Arabia In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Saudi Arabia In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Saudi Arabia In-car Audio System Market Outlook, by System Tier, 2020–2033
- United Arab Emirates In-car Audio System Market Outlook, by Component, 2020–2033
- United Arab Emirates In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- United Arab Emirates In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- United Arab Emirates In-car Audio System Market Outlook, by System Tier, 2020–2033
- South Africa In-car Audio System Market Outlook, by Component, 2020–2033
- South Africa In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- South Africa In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- South Africa In-car Audio System Market Outlook, by System Tier, 2020–2033
- Morocco In-car Audio System Market Outlook, by Component, 2020–2033
- Morocco In-car Audio System Market Outlook, by Sales Channel, 2020–2033
- Morocco In-car Audio System Market Outlook, by Vehicle Class, 2020–2033
- Morocco In-car Audio System Market Outlook, by System Tier, 2020–2033
- Middle East & Africa In-car Audio System Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Harman International
- Bose Corporation
- Alps Alpine
- Pioneer Corporation
- Panasonic Automotive Systems
- Sony Corporation
- Bowers & Wilkins
- Dynaudio
- Burmester Audiosysteme
- Bang & Olufsen
- Focal
- Forvia
- Continental AG
- LG Electronics
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Component
- Speakers, Tweeters and Subwoofers
- Amplifiers and Digital Signal Processors
- Head Units and Audio-Capable Infotainment
- Microphones
- Audio Processing Software
Sales Channel
- Original Equipment
- Dealer-Fitted and Accessory
- Independent Aftermarket
Vehicle Class
- Entry and Economy Passenger Cars
- Mid-Range Passenger Cars
- Premium and Luxury Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
System Tier
- Base Audio Systems
- Mid-Tier Systems
- Premium Branded Systems
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 14.5 billion in 2026, covering factory-fitted and aftermarket vehicle audio across passenger cars and commercial vehicles worldwide.
Revenue is projected to reach US$ 21.8 billion by 2033, a 6.0% CAGR and an absolute dollar opportunity of US$ 7.3 billion across the forecast period.
Speakers, Tweeters and Subwoofers lead with 41% share in 2026, because transducer counts multiply with every system tier upgrade inside the cabin.
Audio Processing Software grows fastest at a 9.4% CAGR through 2033, as tuning, noise control and spatial rendering move onto shared vehicle compute.
Asia Pacific leads with 41% share in 2026, and concentration is medium, split between large integration suppliers and licensed specialist acoustic brands.
Related Reports
Locomotive Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The locomotive market is projected to reach US$29.5 billion by 2033. Explore propulsion trends, freight and passenger demand, and regional growth.
Li-ion Battery Management Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The Li-ion battery management systems market is projected to reach US$30.2 billion by 2033. Explore trends by topology, pack voltage, and application.
In-Vehicle Payment Services Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The in-vehicle payment services market is forecast to reach US$30.86 billion by 2033 at a 17.3% CAGR as connected cars expand access to in-car payments.
Automotive TIC Services Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automotive TIC services market is valued at US$25.30 billion in 2026, reaching US$37.79 billion by 2033, growing at a 5.9% CAGR
Recreational Vehicle Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global recreational vehicle market is valued at US$78.3 billion in 2026, reaching US$168.3 billion by 2033, growing at an 11.6% CAGR
Off-highway Electric Vehicle Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global off-highway electric vehicle market is valued at US$3.64 billion in 2026, reaching US$10.11 billion by 2033, growing at a 15.7% CAGR