


Kidney Dialysis Centres Market
Kidney Dialysis Centres Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Report Overview
Kidney Dialysis Centres Market Size and Trend Analysis
How Fast Is the Kidney Dialysis Centres Market Growing?
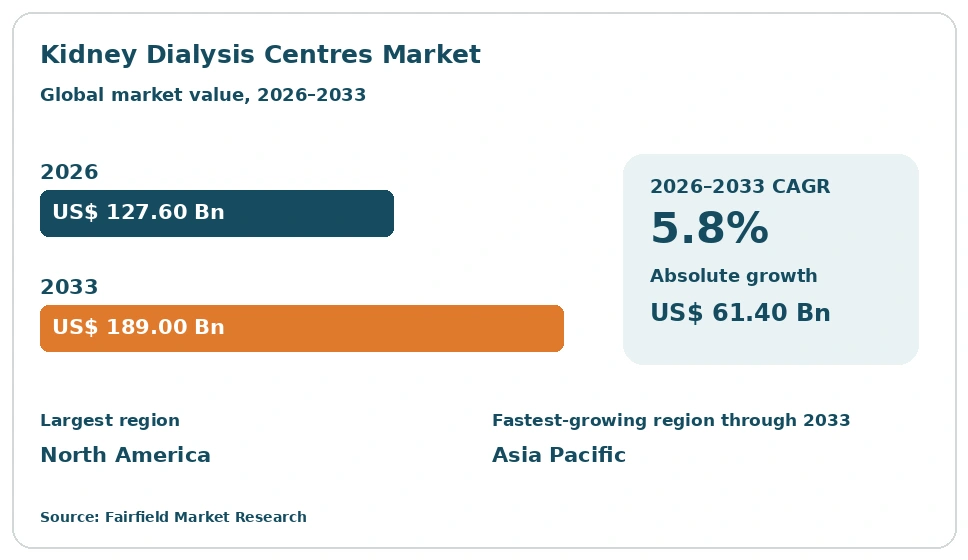
The global kidney dialysis centres market size is expected to be valued at US$ 127.60 billion in 2026 and projected to reach US$ 189.00 billion by 2033, growing at a CAGR of 5.8% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 4.7%, rising from roughly US$ 96 billion to about US$ 120.6 billion, as the number of people with end-stage kidney disease kept rising, while the pandemic caused high death rates among dialysis patients and staff shortages that slowed growth in 2020 and 2021. The kidney dialysis centres market covers hospital-based and standalone centres that provide hemodialysis, peritoneal dialysis support, home dialysis training, and related care for patients whose kidneys have failed. Most patients visit a centre three times a week for treatment sessions of about four hours. Diabetes, high blood pressure, obesity, and aging are the main causes of kidney failure. Revenue comes from government programs, private insurance, and out-of-pocket payments. In April 2026, Diaverum acquired four clinics in Brazil from the Lund Group.
Key Report Takeaways
- By Dialysis Type: Hemodialysis held about 88% share in 2025, while Peritoneal Dialysis is projected to expand at a 7.8% CAGR through 2033, driven by home-based care policies, lower costs, and patient preference for treatment flexibility and independence.
- By Service Setting: In-Center Dialysis held about 80% share in 2025, while Home Dialysis Support is projected to expand at an 8.7% CAGR through 2033, driven by payment incentives, remote monitoring, and easier home machines.
- By Centre Type: Standalone Centres held about 62% share in 2025, while Public-Private Partnership Centres are projected to expand at an 8.2% CAGR through 2033, driven by government dialysis programs in India, Indonesia, Saudi Arabia, and Egypt.
- By Region: North America held about 36% share in 2025, while Asia Pacific is projected to expand at a 7.0% CAGR through 2033, driven by rising diabetes, large untreated patient populations, and rapid centre expansion in China and India.
Global Kidney Dialysis Centres Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on kidney dialysis centres market demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising chronic kidney disease and kidney failure | High | Global | Long term (≥4 years) |
| Government funding and dialysis programs | High | Asia Pacific, Latin America, Middle East & Africa | Medium term (2-4 years) |
Rising Kidney Failure Is Driving the Kidney Dialysis Centres Market
Rising chronic kidney disease and kidney failure are the strongest driver of the kidney dialysis centres market. More people need dialysis every year.
The mechanism is the global spread of diabetes, high blood pressure, and obesity, which damage the kidneys over time. Aging populations in North America, Europe, Japan, and China add more patients, and people with kidney failure now live longer on dialysis because of better care. Kidney transplants cannot meet demand because donor organs are scarce, so most patients rely on dialysis for years. Each patient needs about 150 hemodialysis sessions a year, creating steady demand for centre capacity, nurses, machines, and consumables. Better screening is also finding more patients who need treatment. These trends support long-term growth in centre numbers and treatment volumes.
Government Programs Are Expanding the Kidney Dialysis Centres Market
Government funding and dialysis programs are expanding the kidney dialysis centres market. Many countries now pay for most dialysis treatment.
The cause is a policy shift toward covering kidney failure treatment, which was once unaffordable for most patients in developing countries. India runs the Pradhan Mantri National Dialysis Programme, offering free dialysis in district hospitals through public-private partnerships. China has expanded insurance coverage for dialysis, while Brazil, Mexico, Saudi Arabia, and Egypt fund treatment through public systems. In the United States, Medicare covers most patients with kidney failure regardless of age. These programs raise the number of patients who can access regular treatment, encouraging private operators to open new centres in partnership with governments and hospitals. Many programs now reach smaller towns and rural districts.
Restraints Impact Analysis
Two restraints limit how quickly the kidney dialysis centres market grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Staff shortages and rising operating costs | High | Global | Long term (≥4 years) |
| Reimbursement pressure and shift to home care | Medium | North America, Europe | Medium term (2-4 years) |
Staff Shortages Slow the Kidney Dialysis Centres Market
Staff shortages and rising operating costs slow the kidney dialysis centres market. Dialysis depends on skilled people.
The problem is that every centre needs nephrologists, dialysis nurses, technicians, and dietitians, and many countries face shortages of these workers. Nurse wages rose sharply after the pandemic, and staff turnover remains high because the work is demanding. Some operators have closed or merged centres because they cannot staff them. Costs for water treatment, utilities, consumables, and machines have also risen. In developing countries, few nephrologists practice outside large cities, limiting where centres can open. Training programs take years to produce new specialists. Supply disruptions for dialyzers and fluids have also affected some regions. Water quality rules add further costs. These pressures reduce margins and slow expansion, especially for smaller operators with limited resources.
Reimbursement Pressure Restricts the Kidney Dialysis Centres Market
Reimbursement pressure and the shift to home care restrict the kidney dialysis centres market. Payers increasingly want lower costs and better outcomes.
The constraint is that dialysis payment rates from Medicare in the United States and public systems in Europe often rise more slowly than costs, squeezing centre profits. Governments are also encouraging home dialysis and kidney transplants through payment models and targets, which may reduce demand for in-centre chairs over time. New drugs that slow kidney disease, such as SGLT2 inhibitors and GLP-1 medicines, could delay the need for dialysis for some patients. Private insurers also negotiate harder on prices. Some operators have closed underused centres in response. These factors limit revenue growth per patient in mature markets and push operators to cut costs and improve efficiency.
Market Opportunities
Home Dialysis Support Opens a Fast-Growth Revenue Pool
Home dialysis support opens a fast-growth revenue pool. Many patients want to dialyze at home.
The opportunity comes from peritoneal dialysis and home hemodialysis, which give patients more freedom, fewer trips, and often better quality of life. Payment models in the United States reward providers for raising home dialysis and transplant rates, and countries such as China, Thailand, and Mexico promote peritoneal dialysis to save costs. Dialysis centres play a central role by training patients, supplying equipment and fluids, monitoring treatments remotely, and providing backup care. Smaller, easier-to-use home machines and remote monitoring software make this model practical. Home programs also help centres serve patients living far from clinics. Operators that build strong home programs can grow revenue while reducing pressure on centre capacity and staff.
Emerging Markets Create a Growth Revenue Pool
Emerging markets create a growth revenue pool. Millions of patients worldwide still lack regular access to dialysis today.
The opportunity reflects large gaps in care in India, China, Indonesia, Vietnam, Brazil, Mexico, Egypt, and Nigeria, where many people with kidney failure never receive regular treatment. Rising incomes, expanding insurance, and public-private partnerships are making new centres viable. Chains such as NephroPlus, DaVita, Diaverum, and Fresenius Medical Care are expanding through new clinics and acquisitions. Lower-cost models, including smaller satellite centres, shared staff, and local equipment, can reach smaller cities. Medical tourism for dialysis is also growing in some countries. Operators that build efficient networks and partner with governments can capture strong long-term growth in these markets.
Segment Analysis
By Dialysis Type: Hemodialysis Leads While Peritoneal Dialysis Grows Fastest
Hemodialysis held about 88% share in 2025. Blood is pumped through a dialyzer that removes waste and extra fluid, usually three times a week in a centre. It is the most common treatment worldwide, supported by well-established centre networks, trained staff, and broad reimbursement.
Peritoneal Dialysis is the fastest-growing dialysis type, expanding at a 7.8% CAGR through 2033. It uses the lining of the abdomen as a filter and is done at home daily, often overnight with a machine. Governments promote it because it can cost less than in-centre care and suits patients in remote areas. Centres provide training, supplies, and follow-up. For the market, peritoneal growth expands home support services and creates demand for training nurses and supply logistics.
By Service Setting: In-Center Dialysis Leads While Home Dialysis Support Grows Fastest
In-Center Dialysis held about 80% share in 2025. Most patients receive hemodialysis in centres where nurses and technicians manage treatment and doctors monitor health. Many patients prefer the safety and social contact of centre care, and many lack space or support at home.
Home Dialysis Support is the fastest-growing setting, expanding at an 8.7% CAGR through 2033. Centres train patients and carers, supply equipment, monitor treatment remotely, and handle problems. Payment incentives in the United States, new home machines, and patient preference support growth. Nocturnal and Self-Care Dialysis within centres form other services. Telehealth visits allow doctors to review home patients without travel. For the market, home support growth changes how centres earn revenue.
By Centre Type: Standalone Centres Lead While Public-Private Partnership Centres Grow Fastest
Standalone Centres held about 62% share in 2025. Independent and chain-operated clinics run by companies such as Fresenius Medical Care, DaVita, and Diaverum treat most dialysis patients in North America and many in Europe and Latin America. They focus on efficient, high-volume outpatient care.
Public-Private Partnership Centres are the fastest-growing centre type, expanding at an 8.2% CAGR through 2033. Governments provide space or funding in public hospitals while private operators run treatment, which quickly adds capacity in India, Middle East & Africa, and other emerging markets. Hospital-Based Centres form another segment treating acute and complex patients. For the market, partnership growth widens access and brings private operators into public health systems at lower cost.
Geography Analysis
Which Region Is Leading the Kidney Dialysis Centres Market?
North America is leading the kidney dialysis centres market with about 36% share in 2025. The United States has more than half a million patients on dialysis and thousands of outpatient centres, with DaVita alone running 2,657 U.S. centres at the end of 2025 and Fresenius Medical Care operating a similar network. Medicare covers most patients with kidney failure. Canada provides dialysis through public hospitals and satellite units. Key barriers include staff shortages and tight payment rates. Many centres are in suburban and rural areas. One change shaping the region is the push toward home dialysis and value-based kidney care models.
Europe Shapes the Kidney Dialysis Centres Market Through Public Health Systems
Europe is a major kidney dialysis centres market. Germany, Italy, France, Spain, and the United Kingdom have large dialysis populations and aging societies, and public health systems pay for most treatment. Providers such as Fresenius Medical Care, Diaverum, and B. Braun run centre networks, while many patients are treated in public hospital units. Poland and other countries are expanding private centres. Key barriers include budget limits, staff shortages, and pressure on payment rates. Cross-border operators are also buying smaller local providers. Waiting lists for transplants keep many patients on long-term dialysis. One opportunity is home dialysis and integrated kidney care programs.
Which Region Is Growing Fastest in the Kidney Dialysis Centres Market?
Asia Pacific is the fastest-growing kidney dialysis centres market, expanding at a 7.0% CAGR through 2033. China has a very large and growing dialysis population supported by expanding insurance coverage and private centre chains. India is adding centres through its national dialysis program and private chains such as NephroPlus, which also operates in other countries. Japan and Taiwan have some of the highest dialysis rates in the world, while Indonesia, Vietnam, and the Philippines are expanding access. Key barriers include staff shortages and affordability. One change shaping the region is rapid growth of dialysis chains.
Latin America Grows the Kidney Dialysis Centres Market Through Acquisitions
Latin America is a growing kidney dialysis centres market. Brazil and Mexico have large dialysis populations driven by diabetes, and public systems fund much of the treatment through private providers. DaVita, Diaverum, and Fresenius Medical Care are expanding through acquisitions in Brazil, Colombia, Chile, and Argentina. Mexico uses peritoneal dialysis widely. Key barriers include low payment rates, currency swings, and unequal access outside big cities. Colombia and Chile have growing private dialysis networks serving insured patients. Many clinics are still owned by local doctors. One opportunity is consolidating fragmented local clinics into efficient networks.
Middle East & Africa Builds the Kidney Dialysis Centres Market Through Public Investment
Middle East & Africa is an emerging kidney dialysis centres market. Saudi Arabia, the United Arab Emirates, and Kuwait have high diabetes rates and fund dialysis through public systems, often working with private operators such as Diaverum and Fresenius Medical Care. Egypt has a large dialysis population, while South Africa, Nigeria, and Kenya face major access gaps. Key barriers include high costs, few nephrologists, and limited public funding in many countries. Many patients in the region start dialysis late because of limited screening. Training more local nurses is a priority. One opportunity is public-private partnerships to expand centre networks.
Competitive Landscape
The kidney dialysis centres market is moderately consolidated. Fresenius Medical Care, DaVita, B. Braun, Diaverum, and NephroPlus are leading players, while U.S. Renal Care, American Renal Associates, Dialysis Clinic Inc., Satellite Healthcare, Nipro, Vantive, and Asahi Kasei compete strongly. Fresenius Medical Care and DaVita together treat a large share of patients in the United States and run large international networks. In Europe, Asia Pacific, and Latin America, many patients are treated by public hospitals and local clinic groups.
Companies compete on clinical quality, patient outcomes, location and convenience, staff retention, cost per treatment, and relationships with nephrologists and payers. Vertical integration is important, as some operators also make dialysis machines, dialyzers, and fluids. Large chains use scale to buy supplies cheaply, standardize care, and invest in data systems that track patient health and centre performance.
Strategic moves show how competition is changing. In December 2025, NephroPlus opened its initial public offering in India to fund growth. In February 2026, DaVita reported 3,242 centres worldwide. In April 2026, Diaverum acquired four clinics in Brazil, following other purchases in the country. These moves show consolidation in fragmented markets and growing investment in emerging regions.
Three themes shape vendor strategy. First, operators are expanding home dialysis programs and value-based kidney care. Second, they are acquiring local clinic groups to build scale in Latin America, Asia Pacific, and Middle East & Africa. Third, they are investing in staff training, digital monitoring, and efficiency to manage cost and labor pressures.
Kidney Dialysis Centres Market Industry Leaders
- Fresenius Medical Care
- DaVita
- B. Braun
- Diaverum
- NephroPlus
Recent Industry Developments
- April 2026: Diaverum acquired four clinics in São Paulo state from the Lund Group, serving about 1,400 patients and more than 220,000 treatments a year - strengthens its network in Brazil and the kidney dialysis centres market.
- February 2026: DaVita reported serving about 295,000 patients at 3,242 outpatient dialysis centres at the end of 2025, including 585 centres outside the United States - shows the scale of leading dialysis centre chains.
- December 2025: NephroPlus opened its ?871 crore initial public offering in India - funds expansion of dialysis centres in Asia Pacific and other emerging markets.
Companies Covered in the Report
- Fresenius Medical Care
- DaVita
- B. Braun
- Diaverum
- NephroPlus
- U.S. Renal Care
- American Renal Associates
- Dialysis Clinic Inc.
- Satellite Healthcare
- Nipro
- Vantive
- Asahi Kasei
Kidney Dialysis Centres Market Report Scope
This report covers the kidney dialysis centres market, including hemodialysis and peritoneal dialysis services delivered through in-center and home dialysis support settings by standalone, hospital-based, and public-private partnership centres, along with related equipment and consumables used in centre operations. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
| Dialysis Type | Hemodialysis, Peritoneal Dialysis |
| Service Setting | In-Center Dialysis, Home Dialysis Support |
| Centre Type | Standalone Centres, Hospital-Based Centres, Public-Private Partnership Centres |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
1. Executive Summary
1.1 Kidney Dialysis Centres Market Snapshot
1.2 Future Projections
1.3 Key Market Trends
1.4 Regional Snapshot
2. Market Overview
2.1 Market Definition and Report Scope
2.2 Historical Market Trends
2.3 Market Dynamics
2.3.1 Drivers
2.3.1.1 Rising Kidney Failure Is Driving the Kidney Dialysis Centres Market
2.3.1.2 Government Programs Are Expanding the Kidney Dialysis Centres Market
2.3.2 Restraints
2.3.2.1 Staff Shortages Slow the Kidney Dialysis Centres Market
2.3.2.2 Reimbursement Pressure Restricts the Kidney Dialysis Centres Market
2.3.3 Market Opportunities
2.3.3.1 Home Dialysis Support Opens a Fast-Growth Revenue Pool
2.3.3.2 Emerging Markets Create a Growth Revenue Pool
3. Global Kidney Dialysis Centres Market Outlook, 2020–2033
3.1 Global Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
3.1.1 Hemodialysis
3.1.2 Peritoneal Dialysis
3.2 Global Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
3.2.1 In-Center Dialysis
3.2.2 Home Dialysis Support
3.3 Global Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
3.3.1 Standalone Centres
3.3.2 Hospital-Based Centres
3.3.3 Public-Private Partnership Centres
3.4 Global Kidney Dialysis Centres Market Outlook, by Region, Value (US$ Billion), 2020–2033
3.4.1 North America
3.4.2 Europe
3.4.3 Asia Pacific
3.4.4 Latin America
3.4.5 Middle East & Africa
4. North America Kidney Dialysis Centres Market Outlook, 2020–2033
4.1 North America Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
4.1.1 Hemodialysis
4.1.2 Peritoneal Dialysis
4.2 North America Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
4.2.1 In-Center Dialysis
4.2.2 Home Dialysis Support
4.3 North America Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
4.3.1 Standalone Centres
4.3.2 Hospital-Based Centres
4.3.3 Public-Private Partnership Centres
4.4 North America Kidney Dialysis Centres Market Outlook, by Country, Value (US$ Billion), 2020–2033
4.4.1 United States Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
4.4.2 United States Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
4.4.3 United States Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
4.4.4 Canada Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
4.4.5 Canada Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
4.4.6 Canada Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5. Europe Kidney Dialysis Centres Market Outlook, 2020–2033
5.1 Europe Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
5.1.1 Hemodialysis
5.1.2 Peritoneal Dialysis
5.2 Europe Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
5.2.1 In-Center Dialysis
5.2.2 Home Dialysis Support
5.3 Europe Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
5.3.1 Standalone Centres
5.3.2 Hospital-Based Centres
5.3.3 Public-Private Partnership Centres
5.4 Europe Kidney Dialysis Centres Market Outlook, by Country, Value (US$ Billion), 2020–2033
5.4.1 Germany Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.2 Germany Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.3 Germany Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5.4.4 Italy Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.5 Italy Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.6 Italy Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5.4.7 France Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.8 France Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.9 France Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5.4.10 Spain Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.11 Spain Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.12 Spain Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5.4.13 United Kingdom Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.14 United Kingdom Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.15 United Kingdom Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
5.4.16 Poland Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
5.4.17 Poland Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
5.4.18 Poland Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6. Asia Pacific Kidney Dialysis Centres Market Outlook, 2020–2033
6.1 Asia Pacific Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
6.1.1 Hemodialysis
6.1.2 Peritoneal Dialysis
6.2 Asia Pacific Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
6.2.1 In-Center Dialysis
6.2.2 Home Dialysis Support
6.3 Asia Pacific Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
6.3.1 Standalone Centres
6.3.2 Hospital-Based Centres
6.3.3 Public-Private Partnership Centres
6.4 Asia Pacific Kidney Dialysis Centres Market Outlook, by Country, Value (US$ Billion), 2020–2033
6.4.1 China Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.2 China Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.3 China Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.4 India Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.5 India Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.6 India Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.7 Japan Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.8 Japan Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.9 Japan Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.10 Taiwan Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.11 Taiwan Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.12 Taiwan Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.13 Indonesia Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.14 Indonesia Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.15 Indonesia Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.16 Vietnam Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.17 Vietnam Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.18 Vietnam Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
6.4.19 Philippines Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
6.4.20 Philippines Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
6.4.21 Philippines Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
7. Latin America Kidney Dialysis Centres Market Outlook, 2020–2033
7.1 Latin America Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
7.1.1 Hemodialysis
7.1.2 Peritoneal Dialysis
7.2 Latin America Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
7.2.1 In-Center Dialysis
7.2.2 Home Dialysis Support
7.3 Latin America Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
7.3.1 Standalone Centres
7.3.2 Hospital-Based Centres
7.3.3 Public-Private Partnership Centres
7.4 Latin America Kidney Dialysis Centres Market Outlook, by Country, Value (US$ Billion), 2020–2033
7.4.1 Brazil Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
7.4.2 Brazil Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
7.4.3 Brazil Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
7.4.4 Mexico Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
7.4.5 Mexico Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
7.4.6 Mexico Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
7.4.7 Colombia Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
7.4.8 Colombia Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
7.4.9 Colombia Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
7.4.10 Chile Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
7.4.11 Chile Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
7.4.12 Chile Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
7.4.13 Argentina Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
7.4.14 Argentina Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
7.4.15 Argentina Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8. Middle East & Africa Kidney Dialysis Centres Market Outlook, 2020–2033
8.1 Middle East & Africa Kidney Dialysis Centres Market Outlook, by Dialysis Type, Value (US$ Billion), 2020–2033
8.1.1 Hemodialysis
8.1.2 Peritoneal Dialysis
8.2 Middle East & Africa Kidney Dialysis Centres Market Outlook, by Service Setting, Value (US$ Billion), 2020–2033
8.2.1 In-Center Dialysis
8.2.2 Home Dialysis Support
8.3 Middle East & Africa Kidney Dialysis Centres Market Outlook, by Centre Type, Value (US$ Billion), 2020–2033
8.3.1 Standalone Centres
8.3.2 Hospital-Based Centres
8.3.3 Public-Private Partnership Centres
8.4 Middle East & Africa Kidney Dialysis Centres Market Outlook, by Country, Value (US$ Billion), 2020–2033
8.4.1 Saudi Arabia Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.2 Saudi Arabia Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.3 Saudi Arabia Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.4 United Arab Emirates Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.5 United Arab Emirates Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.6 United Arab Emirates Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.7 Kuwait Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.8 Kuwait Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.9 Kuwait Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.10 Egypt Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.11 Egypt Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.12 Egypt Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.13 South Africa Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.14 South Africa Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.15 South Africa Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.16 Nigeria Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.17 Nigeria Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.18 Nigeria Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
8.4.19 Kenya Kidney Dialysis Centres Market Outlook, by Dialysis Type, 2020–2033
8.4.20 Kenya Kidney Dialysis Centres Market Outlook, by Service Setting, 2020–2033
8.4.21 Kenya Kidney Dialysis Centres Market Outlook, by Centre Type, 2020–2033
9. Competitive Landscape
9.1 Kidney Dialysis Centres Market Industry Leaders
9.2 Recent Industry Developments
9.3 Company Profiles
9.3.1 Fresenius Medical Care
9.3.2 DaVita
9.3.3 B. Braun
9.3.4 Diaverum
9.3.5 NephroPlus
9.3.6 U.S. Renal Care
9.3.7 American Renal Associates
9.3.8 Dialysis Clinic Inc.
9.3.9 Satellite Healthcare
9.3.10 Nipro
9.3.11 Vantive
9.3.12 Asahi Kasei
10. Appendix
10.1 Research Methodology
10.2 Report Assumptions
10.3 Acronyms and Abbreviations
| Dialysis Type | Hemodialysis, Peritoneal Dialysis |
| Service Setting | In-Center Dialysis, Home Dialysis Support |
| Centre Type | Standalone Centres, Hospital-Based Centres, Public-Private Partnership Centres |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The kidney dialysis centres market is valued at US$ 127.60 billion in 2026, led by hemodialysis and North America.
The market is projected to reach US$ 189.00 billion by 2033, growing at a 5.8% CAGR and adding US$ 61.40 billion.
Home dialysis support is growing fastest at an 8.7% CAGR through 2033, driven by payment incentives, remote monitoring, and easier machines.
Asia Pacific is growing fastest at a 7.0% CAGR through 2033, driven by rising diabetes, untreated patients, and rapid centre expansion.
North America holds the largest share at about 36% in 2025, supported by large patient numbers, Medicare coverage, and major chains.
Related Reports
Cervical Cancer Treatment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the cervical cancer treatment market outlook for 2026–2033, covering therapies, cancer types, end users, regional trends, and key companies.
Gout Therapeutic Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global gout therapeutic market is valued at US$2.9 billion in 2026, reaching US$4.7 billion by 2033, growing at a 7.1% CAGR
Small Molecule API Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the small molecule API market outlook for 2026–2033, including synthesis, manufacturing, therapeutic applications, regions, and competitors.
Medical Marijuana Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the medical marijuana market outlook for 2026–2033, including product forms, distribution channels, regional trends, and competitive insights.
Pantoprazole Sodium Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global pantoprazole sodium market is valued at US$2.36 billion in 2026, reaching US$3.57 billion by 2033, growing at a 6.1% CAGR
Immunotherapy Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global immunotherapy market is valued at US$274.5 billion in 2026, reaching US$521.4 billion by 2033, growing at a 9.6% CAGR