


Nickel Alloys Market
Nickel Alloys Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Nickel Alloys Market Analysis, 2026–2033
Nickel Alloys Market Size and Trend Analysis
How Fast Is the Nickel Alloys Market Growing?
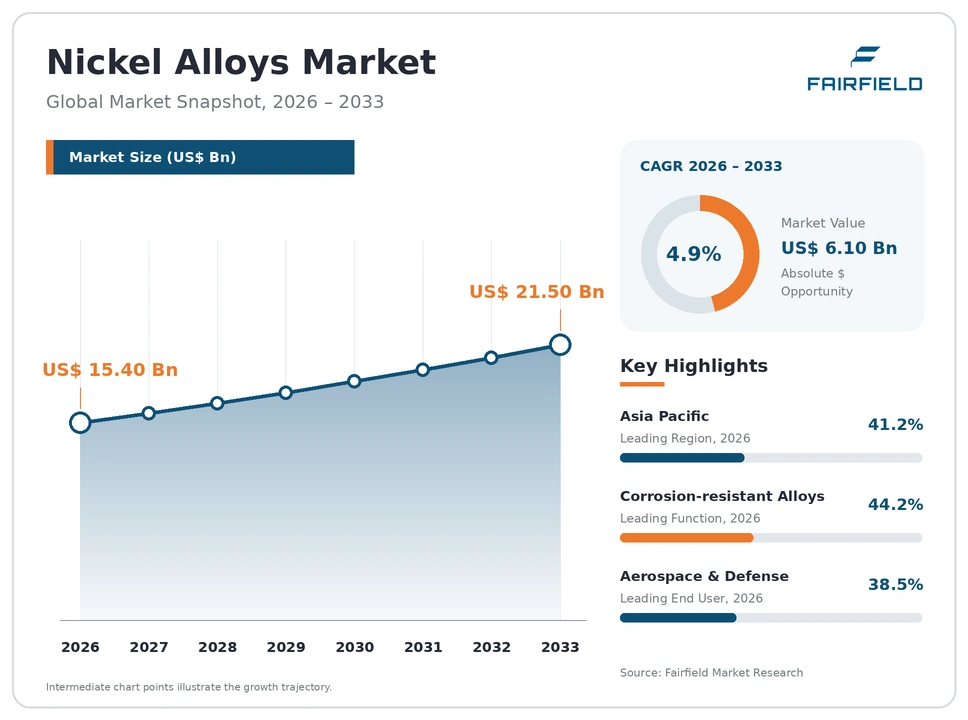
The global nickel alloys market size is expected to be valued at US$ 15.40 billion in 2026 and projected to reach US$ 21.50 billion by 2033, growing at a CAGR of 4.9% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 3.8%, recovering from pandemic disruptions in aerospace and oil and gas, while facing sharp nickel price swings, including the 2022 price spike on the London Metal Exchange. Three factors now drive growth: rising aerospace and defense production, investment in chemical processing, LNG, and energy infrastructure, and new uses in hydrogen, nuclear power, and additive manufacturing. The market is shifting toward higher-performance alloys that resist extreme heat and corrosion, along with powders for 3D printing. Lower nickel prices from Indonesian supply have eased raw material costs, but price volatility remains a concern.
Key Report Takeaways
- By Function: Corrosion-resistant Alloys held 44.2% share in 2026, while Heat-resistant Alloys are projected to expand at a 5.8% CAGR through 2033, driven by jet engine and gas turbine demand.
- By Product Form: Bars & Rods held 31.6% share in 2026, while Powder is projected to expand at a 9.8% CAGR through 2033, driven by additive manufacturing and thermal spray coatings.
- By End User: Aerospace & Defense held 38.5% share in 2026, while Energy & Power is projected to expand at a 6.3% CAGR through 2033, driven by hydrogen, nuclear, and gas-fired power projects.
- By Region: Asia Pacific held 41.2% share in 2026, while India is projected to expand at a 6.8% CAGR through 2033, driven by chemical, refining, and aerospace manufacturing growth.
Global Nickel Alloys Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on nickel alloys demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Aerospace and defense production growth | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
| Chemical processing, LNG, and energy infrastructure investment | High | Asia Pacific, Middle East & Africa, North America | Medium term (2-4 years) |
Aerospace and Defense Production Is Driving Nickel Alloys Demand
Aerospace and defense production is the strongest driver of nickel alloys demand. Aircraft engines, airframes, and military systems use nickel alloys because they combine strength, heat resistance, and corrosion resistance.
The mechanism is a long aircraft order backlog and rising defense budgets. Airbus and Boeing hold backlogs of more than 15,000 commercial aircraft, while engine makers such as GE Aerospace, Pratt & Whitney, Rolls-Royce, and Safran are increasing output and aftermarket support. Engines use alloys such as Inconel 718 and 625 in disks, casings, combustors, and exhaust systems. Airframes use nickel alloys in hydraulic tubing, fasteners, and heat shields. NATO members have committed to higher defense spending, supporting fighter jets, missiles, naval vessels, and armored vehicles. Space launch companies also use nickel alloys in rocket engines. These programs create steady, high-value demand for certified bars, sheets, forgings, and powders.
Energy and Chemical Infrastructure Is Expanding Nickel Alloys Use
Investment in chemical processing, LNG, and energy infrastructure is expanding nickel alloys use. These industries handle corrosive chemicals, high temperatures, and high pressures that quickly damage ordinary steels.
The cause is new capacity and stricter safety and reliability requirements. Chemical and petrochemical plants use Hastelloy and similar nickel-molybdenum-chromium alloys in reactors, heat exchangers, and piping that handle acids and chlorides. Refineries and sour gas facilities in the Middle East use nickel alloys to resist hydrogen sulfide corrosion. LNG export projects in the United States, Qatar, and Australia need cryogenic and corrosion-resistant materials. Flue gas desulfurization systems, pollution control equipment, and desalination plants use corrosion-resistant alloys such as Monel and Alloy C-276. Gas turbines for data center power add heat-resistant alloy demand, while nuclear plants use alloys such as Alloy 690 in steam generators.
Restraints Impact Analysis
Two restraints limit how quickly nickel alloys demand grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Nickel price volatility and supply concentration | Medium | Global | Short term (≤2 years) |
| High processing costs and competition from substitute materials | Medium | Global | Medium term (2-4 years) |
Nickel Price Volatility Creates Cost Uncertainty for Nickel Alloys
Nickel price volatility and supply concentration create cost uncertainty for nickel alloys producers and buyers. Raw materials make up a large share of alloy costs, so price swings directly affect margins and project budgets.
The specific causes are concentrated production and policy changes. Indonesia has become the dominant nickel producer through rapid expansion of mining and processing, which pushed prices down after 2023 and forced mine closures in Australia and elsewhere. In April 2025, Indonesia introduced progressive nickel ore royalties of 14% to 19%, replacing a flat 10% rate. Sanctions on Russia, home to Nornickel, have complicated supply of high-purity nickel. The 2022 short squeeze on the London Metal Exchange showed how quickly prices can spike. Other alloying elements, including molybdenum, cobalt, and niobium, also face supply risks, which complicate long-term pricing.
High Processing Costs and Substitutes Limit Nickel Alloys Adoption
High processing costs and competition from substitute materials limit nickel alloys adoption in some applications. Nickel alloys are much more expensive than carbon steel and stainless steel, so buyers use them only where necessary.
The underlying causes are complex production and alternative materials. Nickel alloys require vacuum melting, remelting, hot working, and careful heat treatment, which use expensive equipment and energy. They are harder to machine and weld than steel, increasing fabrication costs. Duplex and super duplex stainless steels, titanium alloys, coated steels, and composites compete in some corrosion and weight-sensitive applications. Plastics and fiber-reinforced materials replace metals in some chemical equipment. High energy costs in Europe raise production costs for local mills. Buyers in price-sensitive markets may choose cheaper materials, accepting shorter equipment life and higher maintenance costs.
Market Opportunities
Hydrogen and Nuclear Power Open a New Nickel Alloys Revenue Pool
Hydrogen and nuclear power open a new revenue pool in the nickel alloys market. Both technologies operate under demanding conditions that require materials with high strength, corrosion resistance, and long service life.
Producers with qualified alloys and energy industry experience can capture this demand. Electrolyzers use nickel components and nickel-based alloys in electrodes and stack parts. Hydrogen pipelines, storage, and fueling systems need materials resistant to hydrogen embrittlement. Small modular reactors and advanced nuclear designs being developed in the United States, Canada, the United Kingdom, and Asia Pacific need high-temperature alloys for heat exchangers and reactor internals. In October 2025, the ASME released a code case for VDM Metals’ Alloy 699 XA, supporting its use in high-temperature equipment. Utilities, electrolyzer makers, and reactor developers are key customers.
Additive Manufacturing and Recycling Create a Nickel Alloy Powder Revenue Pool
Additive manufacturing and recycling create a nickel alloy powder revenue pool. Industries increasingly print complex nickel alloy parts and want to reduce waste and raw material costs.
Powder producers, printer makers, and recyclers can capture this opportunity. Aerospace, energy, and space companies print fuel nozzles, heat exchangers, turbine components, and rocket engine parts from alloys such as Inconel 718 and 625. Printing greatly reduces material waste compared with machining from solid bars. Recycling spent powder and scrap lowers costs and emissions. In February 2026, 6K Additive signed a long-term agreement with Siemens Energy to recycle spent nickel alloy powder. Gas turbine makers, engine makers, and defense contractors are the main customers. Qualified powders sell at much higher prices per kilogram than conventional mill products, improving supplier margins.
Segment Analysis
By Function: Corrosion-resistant Alloys Lead While Heat-resistant Alloys Gain Momentum
Corrosion-resistant Alloys held 44.2% share in 2026. Alloys such as Hastelloy C-276, Inconel 625, and Monel 400 protect equipment in chemical processing, oil and gas, marine, pollution control, and desalination applications. Their long service life reduces downtime and replacement costs in harsh environments.
Heat-resistant Alloys are the fastest-growing function, expanding at a 5.8% CAGR through 2033. Jet engines, industrial gas turbines, furnaces, and heat treatment equipment need alloys that keep strength and resist oxidation at very high temperatures. Rising aircraft production and gas turbine orders for data center power increase demand. Advanced nuclear and concentrated solar power systems also need heat-resistant materials. Electronic and magnetic alloys serve electronics and precision instruments. For the market, heat-resistant growth increases demand for high-value, certified products.
By Product Form: Bars & Rods Lead While Powder Grows Fastest
Bars & Rods held 31.6% share in 2026. These forms are machined into fasteners, shafts, valve parts, forgings, and engine components, making them the most widely used products in aerospace, oil and gas, and industrial equipment. Sheets and plates, pipes and tubes, and wire are other major forms.
Powder is the fastest-growing product form, expanding at a 9.8% CAGR through 2033. Additive manufacturing uses nickel alloy powders to print complex parts with internal channels and fewer welds. Thermal spray and laser cladding use powders to protect surfaces against wear and corrosion. Powder metallurgy produces high-performance turbine disks. Gas atomization capacity is expanding to meet demand. For the market, powder growth adds high-value products and connects nickel alloys to digital and advanced manufacturing.
By End User: Aerospace & Defense Leads While Energy & Power Grows Fastest
Aerospace & Defense held 38.5% share in 2026. Jet engines, airframes, missiles, naval ships, and space vehicles use nickel alloys for heat and corrosion resistance. Long certification processes and strict quality standards make aerospace a high-value market.
Energy & Power is the fastest-growing end user, expanding at a 6.3% CAGR through 2033. Gas turbine orders are rising to meet electricity demand from data centers and electrification. Nuclear refurbishments, small modular reactors, hydrogen electrolyzers, and concentrated solar power need specialized alloys. Oil and gas, chemical and petrochemical, marine, and automotive remain important end users, with chemical plants consuming large volumes of corrosion-resistant grades. For the market, energy growth diversifies demand and links nickel alloys to the energy transition.
Geography Analysis
North America Drives Aerospace and Defense Demand for Nickel Alloys
North America is a major nickel alloys market driven by aerospace, defense, and energy. The United States hosts engine makers such as GE Aerospace and Pratt & Whitney and producers including Precision Castparts, ATI, Carpenter Technology, and Haynes International. Defense budgets support military aircraft, missiles, and naval shipbuilding. LNG export terminals and gas-fired power plants add demand. Canada adds aerospace and nuclear applications, including CANDU reactor refurbishments in Ontario, and oil sands processing equipment. One change shaping the region is investment to expand domestic melting and forging capacity for defense and aerospace supply chains.
Europe Combines Specialty Alloy Production and Energy Transition Demand
Europe is a major nickel alloys market with strong specialty alloy production and energy transition demand. VDM Metals in Germany, Aubert & Duval in France, and Outokumpu in Finland produce high-performance alloys. Rolls-Royce, Safran, and Siemens Energy are major users. Chemical industries in Germany, the Netherlands, and Belgium use corrosion-resistant alloys. Hydrogen and nuclear programs, including new reactors in France, add demand. The Critical Raw Materials Act supports supply security for nickel and other metals. High energy costs challenge local producers and mills. One opportunity is supplying alloys for electrolyzers and new reactors.
Which Region Is Leading the Nickel Alloys Market?
Asia Pacific is leading the nickel alloys market with a 41.2% share in 2026. China has large chemical, petrochemical, power, and aerospace industries, along with fast-growing domestic alloy producers such as Fushun Special Steel and Baosteel. Japan has advanced producers such as Nippon Yakin Kogyo and supplies engine and industrial components. South Korea has shipbuilding, LNG carrier, and petrochemical demand. Indonesia dominates nickel mining and processing, giving regional producers access to raw materials. Refineries in Vietnam, Thailand, and Malaysia add corrosion-resistant alloy demand. One change shaping the region is the rapid expansion of domestic superalloy production in China.
Which Country Is Growing Fastest in the Nickel Alloys Market?
India is growing fastest in the nickel alloys market at a 6.8% CAGR through 2033. The country is expanding refineries, petrochemical complexes, chemical plants, and fertilizer production that need corrosion-resistant alloys. Defense manufacturing under the Make in India program increases demand for aerospace alloys, while engine maintenance for growing airline fleets adds consumption. Nuclear power expansion plans require specialized steam generator alloys. Mishra Dhatu Nigam, a state-owned producer, supplies defense, space, and nuclear programs. Reliance on imports for high-end alloys remains a key challenge. One opportunity is local production of certified aerospace and energy alloys.
Latin America Uses Nickel Alloys in Oil and Gas and Mining
Latin America is an emerging nickel alloys market where oil and gas, mining, and chemical industries drive demand. Brazil’s Petrobras operates deepwater fields that require corrosion-resistant alloys in subsea equipment and pipelines. Mexico has state-owned refineries and a growing aerospace manufacturing cluster in Querétaro. Chile and Peru use nickel alloys in copper mining, leaching, and metal processing equipment exposed to acids. Key barriers include limited local alloy production, reliance on imports, long delivery times, and economic volatility that delays large industrial projects. One clear opportunity is supplying deepwater oil and gas projects in Brazil and Guyana.
Middle East & Africa Uses Nickel Alloys in Oil, Gas, and Desalination
Middle East & Africa is a developing nickel alloys market where oil, gas, petrochemicals, and desalination drive demand. Saudi Arabia, the United Arab Emirates, and Qatar operate large refineries, sour gas facilities, LNG plants, and desalination plants that need corrosion-resistant alloys. Qatar’s large North Field LNG expansion adds major demand. In Africa, South Africa has large mining and chemical industries, while Nigeria and Angola have oil and gas operations. Key barriers include limited local manufacturing, reliance on imported mill products, and long lead times for certified materials. One opportunity is supplying green hydrogen projects in the Gulf.
Competitive Landscape
The nickel alloys market is moderately concentrated. Precision Castparts with its Special Metals unit, ATI, Carpenter Technology, and Acerinox, which owns VDM Metals and Haynes International, lead in high-performance alloys. Aperam, Outokumpu, Sandvik, Nippon Yakin Kogyo, Aubert & Duval, Rolled Alloys, and Chinese producers such as Fushun Special Steel compete in specific products and regions. Distributors and service centers play important roles in supplying fabricators.
Companies compete on alloy portfolio, quality certification, delivery times, technical support, and price. Aerospace and nuclear customers require long qualification processes, creating strong relationships and high entry barriers. Industrial customers are more price-sensitive and compare nickel alloys with stainless steels and other materials. Producers increasingly differentiate through powders, recycling, and alloys designed for additive manufacturing and hydrogen service.
Strategic moves show how competition is changing. In November 2024, Acerinox completed its acquisition of Haynes International, combining it with VDM Metals to create a larger high-performance alloys business. In April 2025, Indonesia raised nickel ore royalties, affecting raw material costs. In October 2025, ASME released a code case for VDM Metals’ Alloy 699 XA. In February 2026, 6K Additive agreed to recycle nickel alloy powder for Siemens Energy. These moves show competition shifting toward consolidation, new energy applications, and circular supply.
Three themes shape vendor strategy. First, companies are consolidating to gain scale. Second, they are developing alloys for hydrogen, nuclear, and additive manufacturing. Third, they are securing raw materials and recycling.
Nickel Alloys Market Industry Leaders
- Precision Castparts (Special Metals)
- ATI
- Haynes International (Acerinox)
- VDM Metals (Acerinox)
- Carpenter Technology
Recent Industry Developments
- February 2026: 6K Additive signed a long-term agreement with Siemens Energy to recycle spent nickel alloy powder - supports circular supply.
- October 2025: ASME released a code case for VDM Metals’ Alloy 699 XA - enables use in high-temperature equipment.
- April 2025: Indonesia introduced progressive nickel ore royalties of 14% to 19% - raises raw material cost uncertainty.
- November 2024: Acerinox completed its acquisition of Haynes International - consolidates high-performance alloy production.
Companies Covered in the Report
- Precision Castparts (Special Metals)
- ATI
- Haynes International (Acerinox)
- VDM Metals (Acerinox)
- Carpenter Technology
- Aperam
- Outokumpu
- Sandvik
- Nippon Yakin Kogyo
- Rolled Alloys
- Aubert & Duval
- Fushun Special Steel
Nickel Alloys Market Report Scope
This report covers nickel-based alloys, including corrosion-resistant, heat-resistant, and electronic alloys, in forms such as bars and rods, sheets and plates, pipes and tubes, wire, and powder, used in aerospace and defense, energy and power, oil and gas, chemical processing, and other industries. It excludes primary nickel, stainless steels, and battery nickel. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Function
- Corrosion-resistant Alloys
- Heat-resistant Alloys
- Electronic & Magnetic Alloys
- Others
Product Form
- Bars & Rods
- Sheets & Plates
- Pipes & Tubes
- Wire
- Powder
End User
- Aerospace & Defense
- Energy & Power
- Oil & Gas
- Chemical & Petrochemical
- Marine
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
1. Executive Summary
1.1. Global Nickel Alloys Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Aerospace and Defense Production Is Driving Nickel Alloys Demand
2.3.1.2. Energy and Chemical Infrastructure Is Expanding Nickel Alloys Use
2.3.2. Restraints
2.3.2.1. Nickel Price Volatility Creates Cost Uncertainty for Nickel Alloys
2.3.2.2. High Processing Costs and Substitutes Limit Nickel Alloys Adoption
2.3.3. Market Opportunities
2.3.3.1. Hydrogen and Nuclear Power Open a New Nickel Alloys Revenue Pool
2.3.3.2. Additive Manufacturing and Recycling Create a Nickel Alloy Powder Revenue Pool
3. Global Nickel Alloys Market Outlook, 2020-2033
3.1. Global Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
3.1.1. Corrosion-resistant Alloys
3.1.2. Heat-resistant Alloys
3.1.3. Electronic & Magnetic Alloys
3.1.4. Others
3.2. Global Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
3.2.1. Bars & Rods
3.2.2. Sheets & Plates
3.2.3. Pipes & Tubes
3.2.4. Wire
3.2.5. Powder
3.3. Global Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
3.3.1. Aerospace & Defense
3.3.2. Energy & Power
3.3.3. Oil & Gas
3.3.4. Chemical & Petrochemical
3.3.5. Marine
3.3.6. Others
3.4. Global Nickel Alloys Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Nickel Alloys Market Outlook, 2020-2033
4.1. North America Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
4.1.1. Corrosion-resistant Alloys
4.1.2. Heat-resistant Alloys
4.1.3. Electronic & Magnetic Alloys
4.1.4. Others
4.2. North America Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
4.2.1. Bars & Rods
4.2.2. Sheets & Plates
4.2.3. Pipes & Tubes
4.2.4. Wire
4.2.5. Powder
4.3. North America Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
4.3.1. Aerospace & Defense
4.3.2. Energy & Power
4.3.3. Oil & Gas
4.3.4. Chemical & Petrochemical
4.3.5. Marine
4.3.6. Others
4.4. North America Nickel Alloys Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Nickel Alloys Market Outlook, by Function, 2020-2033
4.4.2. United States Nickel Alloys Market Outlook, by Product Form, 2020-2033
4.4.3. United States Nickel Alloys Market Outlook, by End User, 2020-2033
4.4.4. Canada Nickel Alloys Market Outlook, by Function, 2020-2033
4.4.5. Canada Nickel Alloys Market Outlook, by Product Form, 2020-2033
4.4.6. Canada Nickel Alloys Market Outlook, by End User, 2020-2033
5. Europe Nickel Alloys Market Outlook, 2020-2033
5.1. Europe Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
5.1.1. Corrosion-resistant Alloys
5.1.2. Heat-resistant Alloys
5.1.3. Electronic & Magnetic Alloys
5.1.4. Others
5.2. Europe Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
5.2.1. Bars & Rods
5.2.2. Sheets & Plates
5.2.3. Pipes & Tubes
5.2.4. Wire
5.2.5. Powder
5.3. Europe Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
5.3.1. Aerospace & Defense
5.3.2. Energy & Power
5.3.3. Oil & Gas
5.3.4. Chemical & Petrochemical
5.3.5. Marine
5.3.6. Others
5.4. Europe Nickel Alloys Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Germany Nickel Alloys Market Outlook, by Function, 2020-2033
5.4.2. Germany Nickel Alloys Market Outlook, by Product Form, 2020-2033
5.4.3. Germany Nickel Alloys Market Outlook, by End User, 2020-2033
5.4.4. France Nickel Alloys Market Outlook, by Function, 2020-2033
5.4.5. France Nickel Alloys Market Outlook, by Product Form, 2020-2033
5.4.6. France Nickel Alloys Market Outlook, by End User, 2020-2033
5.4.7. Finland Nickel Alloys Market Outlook, by Function, 2020-2033
5.4.8. Finland Nickel Alloys Market Outlook, by Product Form, 2020-2033
5.4.9. Finland Nickel Alloys Market Outlook, by End User, 2020-2033
5.4.10. Netherlands Nickel Alloys Market Outlook, by Function, 2020-2033
5.4.11. Netherlands Nickel Alloys Market Outlook, by Product Form, 2020-2033
5.4.12. Netherlands Nickel Alloys Market Outlook, by End User, 2020-2033
5.4.13. Belgium Nickel Alloys Market Outlook, by Function, 2020-2033
5.4.14. Belgium Nickel Alloys Market Outlook, by Product Form, 2020-2033
5.4.15. Belgium Nickel Alloys Market Outlook, by End User, 2020-2033
6. Asia Pacific Nickel Alloys Market Outlook, 2020-2033
6.1. Asia Pacific Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
6.1.1. Corrosion-resistant Alloys
6.1.2. Heat-resistant Alloys
6.1.3. Electronic & Magnetic Alloys
6.1.4. Others
6.2. Asia Pacific Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
6.2.1. Bars & Rods
6.2.2. Sheets & Plates
6.2.3. Pipes & Tubes
6.2.4. Wire
6.2.5. Powder
6.3. Asia Pacific Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
6.3.1. Aerospace & Defense
6.3.2. Energy & Power
6.3.3. Oil & Gas
6.3.4. Chemical & Petrochemical
6.3.5. Marine
6.3.6. Others
6.4. Asia Pacific Nickel Alloys Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. China Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.2. China Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.3. China Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.4. Japan Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.5. Japan Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.6. Japan Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.7. South Korea Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.8. South Korea Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.9. South Korea Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.10. Indonesia Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.11. Indonesia Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.12. Indonesia Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.13. Vietnam Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.14. Vietnam Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.15. Vietnam Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.16. Thailand Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.17. Thailand Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.18. Thailand Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.19. Malaysia Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.20. Malaysia Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.21. Malaysia Nickel Alloys Market Outlook, by End User, 2020-2033
6.4.22. India Nickel Alloys Market Outlook, by Function, 2020-2033
6.4.23. India Nickel Alloys Market Outlook, by Product Form, 2020-2033
6.4.24. India Nickel Alloys Market Outlook, by End User, 2020-2033
7. Latin America Nickel Alloys Market Outlook, 2020-2033
7.1. Latin America Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
7.1.1. Corrosion-resistant Alloys
7.1.2. Heat-resistant Alloys
7.1.3. Electronic & Magnetic Alloys
7.1.4. Others
7.2. Latin America Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
7.2.1. Bars & Rods
7.2.2. Sheets & Plates
7.2.3. Pipes & Tubes
7.2.4. Wire
7.2.5. Powder
7.3. Latin America Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
7.3.1. Aerospace & Defense
7.3.2. Energy & Power
7.3.3. Oil & Gas
7.3.4. Chemical & Petrochemical
7.3.5. Marine
7.3.6. Others
7.4. Latin America Nickel Alloys Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Nickel Alloys Market Outlook, by Function, 2020-2033
7.4.2. Brazil Nickel Alloys Market Outlook, by Product Form, 2020-2033
7.4.3. Brazil Nickel Alloys Market Outlook, by End User, 2020-2033
7.4.4. Mexico Nickel Alloys Market Outlook, by Function, 2020-2033
7.4.5. Mexico Nickel Alloys Market Outlook, by Product Form, 2020-2033
7.4.6. Mexico Nickel Alloys Market Outlook, by End User, 2020-2033
7.4.7. Chile Nickel Alloys Market Outlook, by Function, 2020-2033
7.4.8. Chile Nickel Alloys Market Outlook, by Product Form, 2020-2033
7.4.9. Chile Nickel Alloys Market Outlook, by End User, 2020-2033
7.4.10. Peru Nickel Alloys Market Outlook, by Function, 2020-2033
7.4.11. Peru Nickel Alloys Market Outlook, by Product Form, 2020-2033
7.4.12. Peru Nickel Alloys Market Outlook, by End User, 2020-2033
7.4.13. Guyana Nickel Alloys Market Outlook, by Function, 2020-2033
7.4.14. Guyana Nickel Alloys Market Outlook, by Product Form, 2020-2033
7.4.15. Guyana Nickel Alloys Market Outlook, by End User, 2020-2033
8. Middle East & Africa Nickel Alloys Market Outlook, 2020-2033
8.1. Middle East & Africa Nickel Alloys Market Outlook, by Function, Value (US$ Billion), 2020-2033
8.1.1. Corrosion-resistant Alloys
8.1.2. Heat-resistant Alloys
8.1.3. Electronic & Magnetic Alloys
8.1.4. Others
8.2. Middle East & Africa Nickel Alloys Market Outlook, by Product Form, Value (US$ Billion), 2020-2033
8.2.1. Bars & Rods
8.2.2. Sheets & Plates
8.2.3. Pipes & Tubes
8.2.4. Wire
8.2.5. Powder
8.3. Middle East & Africa Nickel Alloys Market Outlook, by End User, Value (US$ Billion), 2020-2033
8.3.1. Aerospace & Defense
8.3.2. Energy & Power
8.3.3. Oil & Gas
8.3.4. Chemical & Petrochemical
8.3.5. Marine
8.3.6. Others
8.4. Middle East & Africa Nickel Alloys Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. Saudi Arabia Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.2. Saudi Arabia Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.3. Saudi Arabia Nickel Alloys Market Outlook, by End User, 2020-2033
8.4.4. United Arab Emirates Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.5. United Arab Emirates Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.6. United Arab Emirates Nickel Alloys Market Outlook, by End User, 2020-2033
8.4.7. Qatar Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.8. Qatar Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.9. Qatar Nickel Alloys Market Outlook, by End User, 2020-2033
8.4.10. South Africa Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.11. South Africa Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.12. South Africa Nickel Alloys Market Outlook, by End User, 2020-2033
8.4.13. Nigeria Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.14. Nigeria Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.15. Nigeria Nickel Alloys Market Outlook, by End User, 2020-2033
8.4.16. Angola Nickel Alloys Market Outlook, by Function, 2020-2033
8.4.17. Angola Nickel Alloys Market Outlook, by Product Form, 2020-2033
8.4.18. Angola Nickel Alloys Market Outlook, by End User, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Precision Castparts (Special Metals)
9.5.2. ATI
9.5.3. Haynes International (Acerinox)
9.5.4. VDM Metals (Acerinox)
9.5.5. Carpenter Technology
9.5.6. Aperam
9.5.7. Outokumpu
9.5.8. Sandvik
9.5.9. Nippon Yakin Kogyo
9.5.10. Rolled Alloys
9.5.11. Aubert & Duval
9.5.12. Fushun Special Steel
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Base Year | 2025 |
|---|---|
| Historical Data | 2020–2025 |
| Forecast Period | 2026–2033 |
| Units | Value: US$ Billion |
| Function |
|
| Product Form |
|
| End User |
|
| Regions |
|
| Companies Covered |
|
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The nickel alloys market is valued at US$ 15.40 billion in 2026, led by corrosion-resistant alloys used in demanding industrial environments.
The market is projected to reach US$ 21.50 billion by 2033, growing at a 4.9% CAGR and adding US$ 6.10 billion.
Energy & Power is growing fastest at a 6.3% CAGR through 2033, driven by hydrogen, nuclear, and gas-fired power projects.
India is growing fastest at a 6.8% CAGR through 2033, driven by chemical, refining, defense, and aerospace manufacturing growth.
Asia Pacific holds the largest share at 41.2% in 2026, supported by chemical, power, and aerospace industries in China and Japan.
Related Reports
Non-Woven Abrasives Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Non-Woven Abrasives Market is projected to grow from US$ 2.89 billion in 2026 to US$ 4.03 billion by 2033 at a 4.9% CAGR. See key products and trends.
Agricultural Lubricant Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The agricultural lubricant market is valued at US$ 6.58 billion in 2026 and projected to reach US$ 8.71 billion by 2033 at a CAGR of 4.1%.
Acaricides Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the acaricides market, valued at US$ 393.98 million in 2026 and projected to reach US$ 521.95 million by 2033 at a CAGR of 4.1%.
Rigid Bulk Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global rigid bulk packaging market is valued at US$68.5 billion in 2026, reaching US$96.4 billion by 2033, growing at a 5.0% CAGR
Probiotics Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the probiotics packaging market, valued at US$ 1.4 billion in 2026 and projected to reach US$ 2.4 billion by 2033, growing at an 8.0% CAGR.
Epoxy Composites Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the epoxy composites market, projected to reach US$ 22.3 billion by 2033 at a 6.7% CAGR, with resin, reinforcement and regional insights.