


Roofing Market
Roofing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
How Big Is the Global Roofing Market in 2026?
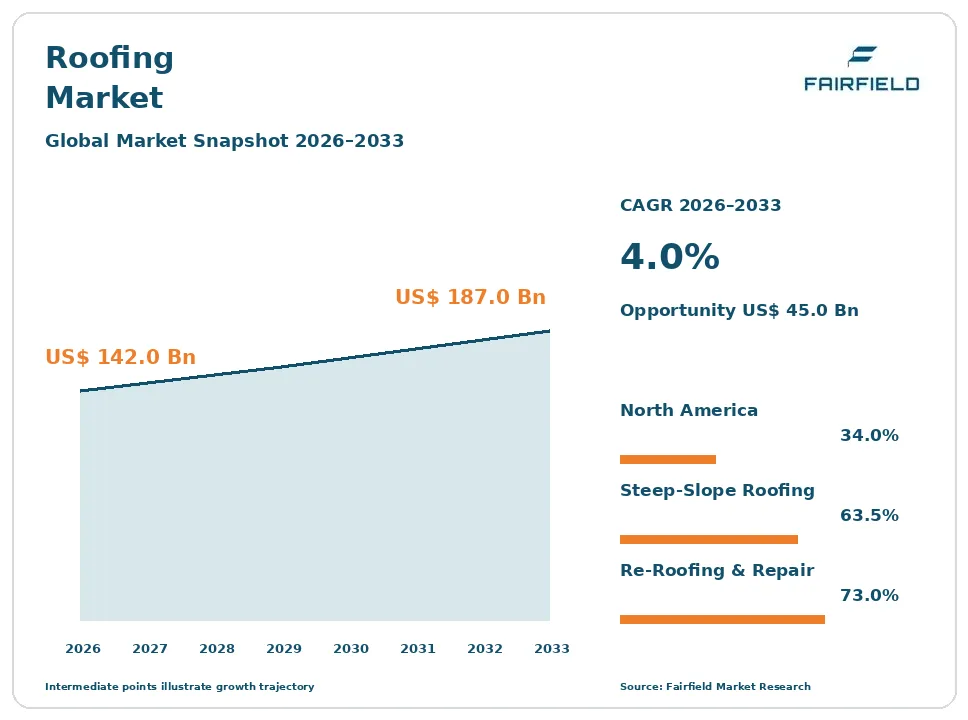
The global Roofing market size is expected to be valued at US$ 142.0 billion in 2026 and projected to reach US$ 187.0 billion by 2033, growing at a CAGR of 4.0% between 2026 and 2033.
The market expanded at a 3.8% CAGR between 2020 and 2025, reaching US$ 136.8 billion, with growth tied far more closely to roof failure than to construction starts. Three factors set the pace. First, a large installed base of roofs is passing the end of its service life, and shingles laid during earlier housing booms are now due. Second, hail, wind and wildfire events are destroying roofs faster than they age out in exposed regions. Third, asphalt, resin and coated-steel input costs have pushed average selling prices up without destroying volume. The direction is steady rather than cyclical: replacement work keeps the market growing even when permit activity for new buildings weakens.
Key Report Takeaways
- By Product Type: Asphalt and bituminous shingles held 31.8% share in 2026, while single-ply membranes are projected to expand at a 5.3% CAGR through 2033, driven by thermoplastic polyolefin recover work on warehouses and distribution centers.
- By Roof Slope: Steep-slope roofing held 63.5% share in 2026, while low-slope roofing is projected to grow at a 4.6% CAGR through 2033, supported by logistics and data center floorplates with very large roof areas.
- By Installation Type: Re-roofing and repair held 73.0% share in 2026, while new construction is projected to advance at a 4.5% CAGR through 2033, reflecting housing completions across emerging economies rather than mature markets.
- By End Use: Residential buildings held 57.5% share in 2026, while commercial buildings are projected to grow at a 4.7% CAGR through 2033, as institutional owners fund envelope work under building performance standards.
- By Geography: North America held 34.0% share in 2026, while Asia Pacific is projected to expand at a 5.4% CAGR through 2033, on urban housing completions and a shift from site-made to manufactured roofing systems.
Global Roofing Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Aging installed roof stock reaching end of service life | High | Global, strongest in North America and Europe | Long term ≥4 years |
| Severe weather losses forcing unplanned roof replacement | High | North America, Asia Pacific, Middle East & Africa | Short term ≤2 years |
Two demand forces explain most of the growth in roofing materials between 2026 and 2033.
Aging Roof Stock Makes Roofing a Replacement Business Before It Is a Construction Business
Roofing demand is created by failure, not by preference. Roughly 73% of material volume goes into re-roofing and repair rather than onto new buildings, because a roof is bought when the old one leaks, curls, loses granules or fails an inspection. That makes the installed base, not the permit pipeline, the governing variable. A typical asphalt shingle roof lasts 15 to 25 years, a single-ply membrane 20 to 30 years, so each construction wave schedules its own replacement wave two to three decades later.
The mechanism is mechanical and documented. Asphalt oxidizes, membranes shrink at seams, fasteners back out and flashings separate, and the failure is visible to the owner as water ingress. Property transactions force the issue, because lenders and inspectors routinely require remaining roof life before closing. Insurance underwriting does the same at renewal, pushing deferred work into the current year.
Storm Frequency and Insured Loss Settlements Set the Timing of Roofing Replacement
Weather moves the roofing market more than interest rates do. A single severe convective storm season can add hundreds of thousands of replacement roofs in one region within months, which is why distributor inventories and manufacturer shipments track hail maps rather than macroeconomic forecasts. Hurricane landfall, straight-line wind and wildfire ember events produce the same effect, and the resulting work is non-discretionary because the building is no longer weathertight. Demand is therefore lumpy by geography and sharply seasonal.
The causal chain runs through the claim. Insurers settle a damaged roof, the settlement funds a full tear-off rather than a patch, and codes then require the replacement to meet current wind-uplift and fastening rules. Miami-Dade County product approvals and FM Approvals wind ratings decide which assemblies qualify, so storm losses quietly upgrade the installed base toward higher-specification roofing systems.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Shortage of trained roofing installers and crew capacity | High | North America, Europe, Middle East & Africa | Long term ≥4 years |
| Property insurance tightening in storm-exposed regions | Medium | North America, Latin America, Asia Pacific | Medium term 2–4 years |
Two constraints limit how much roofing can actually be sold and fitted each year.
Installer Shortage Caps How Much Roofing Can Be Fitted Regardless of Demand
The binding constraint on roofing is crew capacity, not order intake. Roofing is physically demanding, weather-dependent and carries one of the highest fall-injury rates in construction, so recruitment is difficult and attrition is high. When a storm hits, contractors cannot scale quickly, backlogs stretch from weeks to many months, and homeowners wait under tarpaulins. Manufacturers can ship bundles faster than contractors can install them, which converts latent demand into delayed revenue rather than lost revenue.
The underlying cause is demographic and structural. The experienced workforce is retiring, apprenticeship pipelines into roofing are thin, and the trade competes for the same labor pool as framing and solar installation, which offer easier conditions. Seasonal shutdowns in cold climates compress the working year further. The practical consequence is pricing power for contractors, upward pressure on installed cost, and a steady shift toward lighter, faster-to-install roofing systems.
Insurance Tightening in Storm Regions Limits Who Can Afford a Roof Replacement
Changes in property insurance are reducing the number of roofs that actually get replaced after damage. In storm-exposed regions, carriers have raised wind and hail deductibles sharply, moved older roofs onto actual-cash-value settlement rather than replacement cost, imposed roof-age schedules, and in some zones withdrawn coverage altogether. A depreciated settlement on an eighteen-year-old roof may cover only part of a tear-off, so owners patch instead and defer the full replacement.
The cause is underwriting loss experience combined with higher reinsurance pricing, which carriers pass through as terms rather than price alone. Material cost volatility compounds it: asphalt flux, polypropylene and polyvinyl chloride resin, and coated-steel coil prices all move with energy and commodity cycles, so the uninsured gap widens exactly when claims are heaviest. The result is a slower, more price-sensitive replacement cycle in the most storm-affected markets.
Market Opportunities
Cool and Reflective Roofing Opens a Code-Pulled Premium Tier in Roofing Products
Reflective roofing is becoming a specification requirement rather than an upgrade, creating a premium revenue pool inside an otherwise commoditized category. Prescriptive solar reflectance and thermal emittance thresholds already govern low-slope roof replacement in hot climates, and urban heat policies in dense cities are extending them to steep-slope work. Because the requirement attaches to the replacement event, it monetizes the existing re-roofing stream at a higher price per square rather than depending on new demand.
Manufacturers with white thermoplastic membranes, reflective granule technology, coated metal and liquid-applied coatings can capture it directly. Demand comes from commercial property owners, school districts and public agencies that must demonstrate compliance with the International Energy Conservation Code and California Title 24 cool roof provisions, and from ENERGY STAR labeled product requirements written into public procurement specifications.
Solar-Ready Roof Assemblies Create an Attachment and Warranty Revenue Pool in Roofing
Rooftop solar has turned the roof into a mounting platform, and that creates a distinct revenue pool for roofing manufacturers in attachments, flashings, reinforced membranes and extended system warranties. The commercial logic is simple: a solar array lasts longer than an aging roof beneath it, so owners increasingly replace the roof first and buy an assembly engineered for penetrations, ballast loads and future array maintenance. Each installation adds specified accessories that carry higher margins than the base membrane.
System suppliers and membrane manufacturers are positioned to capture this, selling into commercial property owners, warehouse operators and residential contractors who want a single warranty covering both roof and attachment. Building codes requiring solar-ready zones on new low-slope roofs, and wind-uplift testing of ballasted and mechanically attached arrays, support the specification.
Segment Analysis
By Product Type: Asphalt Shingles Hold the Base While Single-Ply Membranes Gain Share
Asphalt and bituminous shingles led the roofing materials market with 31.8% share in 2026, because they remain the lowest installed-cost way to make a pitched roof weathertight and are backed by the deepest contractor familiarity and distribution network. Single-ply membranes are the fastest-growing product type at a 5.3% CAGR to 2033, led by thermoplastic polyolefin and supported by ethylene propylene diene monomer and polyvinyl chloride sheet. Growth comes from recover work on existing commercial roofs, where a new membrane can be installed over the old assembly with less tear-off. Metal roofing, clay and concrete tile, slate, and liquid-applied and spray polyurethane foam systems occupy a smaller premium tier where longevity, fire performance and wind resistance justify higher cost. The implication is a slow mix shift toward engineered systems sold with warranties rather than individual roofing materials sold by the bundle.
By Roof Slope: Steep-Slope Dominates Volume as Low-Slope Roofing Scales With Logistics Floorplates
Steep-slope roofing accounted for 63.5% of the market in 2026, reflecting the dominance of single-family and low-rise residential buildings in the global building stock and the higher material intensity of pitched assemblies with underlayment, flashing and ridge accessories. Low-slope roofing is growing faster at a 4.6% CAGR through 2033, because warehouse, cold storage, data center and manufacturing floorplates have grown enormously and each adds tens of thousands of square meters of flat roof area per building. Low-slope work also carries more insulation board, which raises value per square meter under energy codes. Wind-uplift classification through FM Approvals and fire classification under UL 790 govern assembly selection on these buildings. For manufacturers, the two slopes behave as separate businesses with different channels, different installer bases and different competitive sets.
By Installation Type: Re-Roofing Carries the Market While New Construction Grows From a Smaller Base
Re-roofing and repair represented 73.0% of roofing demand in 2026, confirming that this is a replacement market in which the installed base, weather history and roof age determine volume. The channel is resilient because a failed roof cannot be deferred indefinitely without secondary damage to decking, insulation and interiors. New construction is the faster-growing installation type at a 4.5% CAGR to 2033, but from a much smaller base, and almost all of that growth sits in economies still adding housing and industrial floorspace at scale. The business implication is significant for forecasting: roofing revenue correlates weakly with building permits and strongly with storm seasons, housing turnover and the age profile of existing roofs, so manufacturers plan capacity around replacement cycles rather than construction starts.
By End Use: Residential Buildings Lead While Commercial Roofing Expands on Performance Mandates
Residential buildings held 57.5% of roofing demand in 2026, simply because houses are the most numerous roofed structures and their roofs are replaced on the shortest cycle. Commercial buildings are the fastest-growing end use at a 4.7% CAGR through 2033, as offices, retail centers, schools, hospitals and warehouses undertake envelope work driven by building performance standards, insurance requirements and deferred maintenance backlogs. Commercial owners buy differently: they specify tested assemblies, demand long-term warranties, and weigh insulation thickness and reflectivity alongside price. Industrial and institutional buildings form a steady third tier where chemical resistance and fire classification matter most. The implication is that roofing manufacturers increasingly need two go-to-market models, one running through residential contractors and distributors and one through architects, consultants and approved commercial applicators.
Geography Analysis
Which Region Is Leading the Roofing Market?
North America leads the global roofing market with 34.0% share in 2026, driven by the United States, where an enormous stock of asphalt-shingled houses reaches replacement age every year and severe hail and wind seasons accelerate the cycle. Canada adds freeze-thaw and ice-damming damage that shortens roof life further. The region has the deepest contractor and distributor network in roofing, which converts storm damage into shipments quickly. Mexico contributes growing demand for metal and concrete tile roofing in housing. Insurance behavior is the key variable: deductible structures and settlement terms decide how much damaged roofing is replaced versus patched. The main change ahead is the spread of cool-roof and high-wind provisions through state code adoption, which raises the specification of each replacement roof and lifts revenue per job even where unit volumes are flat.
Europe’s Roofing Demand Is Anchored in Energy Renovation of the Existing Building Stock
Europe held 26.0% of the roofing market in 2026, with Germany, France, Italy, the United Kingdom and Poland accounting for most volume. The regional profile differs sharply from storm-driven markets: clay and concrete tile dominate pitched roofs, bituminous membranes and single-ply cover flat roofs, and the demand trigger is energy renovation rather than catastrophe. Building performance standards and national renovation programs push owners to upgrade roof insulation when the covering is replaced, which raises material content per project. Harmonized product rules matter commercially, because CE marking and declarations of performance under the Construction Products Regulation determine market access for every roofing product sold. Slow new-build activity and high renovation costs restrain volume. The opportunity lies in insulation-plus-covering packages sold as a single compliant roofing system rather than as separate components.
Which Region Is Growing Fastest in the Roofing Market?
Asia Pacific is the fastest-growing roofing market at a 5.4% CAGR between 2026 and 2033, and also the second-largest with 30.0% share in 2026. China and India supply most of the volume, with Indonesia, Vietnam and Japan adding significant demand. Three forces drive it. Urban housing completions continue at scale, industrial and warehouse construction is expanding rapidly, and roofs are shifting from site-made concrete and plain metal sheet to manufactured systems with underlayment, insulation and tested fixings. Typhoon and monsoon exposure across coastal markets makes wind and water performance a selling point rather than an afterthought. Japan and Australia behave as mature replacement markets within the region. The main constraint is price sensitivity, which keeps premium membranes and architectural shingles confined to commercial and higher-income residential projects.
Latin America’s Roofing Market Runs on Metal Sheet and Self-Build Housing
Latin America accounted for 5.5% of roofing demand in 2026, led by Brazil and Mexico, with Colombia, Chile and Argentina following. The regional roofing mix is distinctive: corrugated and coated metal sheet, fiber cement sheet and concrete tile dominate, and a large share of residential roofing is bought in small quantities by self-builders through retail outlets rather than specified by contractors. Hurricane exposure in the Caribbean basin and heavy rainfall in tropical zones create recurring replacement demand. Barriers are real, including currency volatility that raises the cost of imported coil and resin, uneven code enforcement, and limited availability of trained installers for membrane systems. The clearest opportunity is the gradual formalization of housing finance, which moves buyers from the cheapest available sheet toward warrantied roofing products with longer service life.
Middle East & Africa Roofing Demand Follows Gulf Projects and Thermal Performance Rules
Middle East & Africa represented 4.5% of the roofing market in 2026, concentrated in Saudi Arabia, the United Arab Emirates, Qatar, Egypt and South Africa. Demand is weighted toward low-slope roofing on commercial, hospitality, logistics and institutional buildings, where bituminous and single-ply membranes with high-reflectance surfaces manage extreme solar load. Thermal insulation requirements in Gulf building regulations have made insulation board a standard part of the roof assembly rather than an option. Barriers include dependence on imported materials, thin local installer training, and exposure to construction payment cycles tied to public programs. In much of Africa, metal sheet roofing remains the practical default and formal roofing systems are limited to commercial projects. The opportunity is reflective and insulated roofing specified for cooling-load reduction in the hottest urban markets.
Competitive Landscape
The roofing market is moderately concentrated, and the degree of concentration varies sharply by product. Asphalt shingle manufacturing in mature markets is dominated by a handful of vertically integrated producers with their own mat, granule and distribution assets, because the economics depend on plant scale and freight radius. Commercial single-ply and insulation are similarly concentrated, since membrane extrusion and polyisocyanurate board production are capital-intensive. Clay and concrete tile, metal roofing and liquid-applied systems are far more fragmented, with strong regional and national producers serving local architectural preferences. Consolidation has continued steadily, with building-envelope platforms assembling membranes, insulation, accessories and services under one roof.
Competition runs on distribution reach, warranty strength, code and approval coverage, and contractor loyalty rather than on list price alone. Holding UL fire and wind classifications, FM Approvals ratings and high-velocity hurricane zone product approvals is effectively a licence to bid on specified work. Contractor programs that certify installers and unlock extended warranties lock in channel share. New approaches are coming from liquid-applied and spray foam specialists, from synthetic slate and composite shingle producers targeting the premium tier, and from suppliers pairing roofing with solar attachment hardware.
Strategic activity has centered on building out complete envelope systems rather than selling single components, adding insulation and accessory capacity close to demand, and strengthening contractor networks and digital ordering tools. Several manufacturers have broadened from residential shingles into commercial membranes, or the reverse, to balance the storm-driven residential cycle against steadier commercial maintenance work. Investment in recycled-content shingles and asphalt shingle recycling has grown as landfill costs rise.
Strategic direction is converging on three themes: selling tested assemblies with single-source warranties, raising the energy and resilience performance of standard products to match tightening codes, and defending margin through distribution control rather than through price competition in a market where volume is set by failure rates.
Roofing Industry Leaders
- Owens Corning
- Standard Industries
- Carlisle Companies
- Holcim
- Kingspan Group
Recent Industry Developments
- January 2024: The eighth edition of the Florida Building Code became the governing code for new permit applications, tightening roof-deck attachment, secondary water barrier and high-velocity hurricane zone product approval requirements – it raises the specification of every replacement roof in the most storm-exposed state market.
- April 2024: The United States Department of Housing and Urban Development and the United States Department of Agriculture adopted the 2021 International Energy Conservation Code as the minimum energy standard for new federally financed housing – it pulls roof insulation levels upward across a large block of affordable housing construction.
- January 2026: The California Energy Commission’s updated Building Energy Efficiency Standards took effect under Title 24, carrying forward prescriptive solar reflectance and thermal emittance requirements for roof replacement – it sustains the pull for cool roofing products in the largest state building market.
Companies Covered in the Report
- Owens Corning
- Standard Industries
- Carlisle Companies
- Holcim
- Kingspan Group
- Saint-Gobain
- IKO Industries
- TAMKO Building Products
- Etex Group
- Johns Manville
- Sika AG
- Soprema Group
- Wienerberger AG
Roofing Market Report Scope
This report covers roofing materials and systems valued at manufacturer level, including shingles, single-ply membranes, modified bitumen, metal, tile, slate and liquid-applied systems, together with underlayments, insulation boards, flashings and fasteners sold with them. Installation labor is excluded, since including it would roughly double the market value. The base year is 2025 and the forecast period runs from 2026 to 2033, valued in US$ Billion.
Product Type
- Asphalt and Bituminous Shingles
- Single-Ply Membranes (TPO, EPDM, PVC)
- Modified Bitumen and Built-Up Roofing
- Metal Roofing
- Clay and Concrete Tile
- Slate and Synthetic Slate
- Liquid-Applied and Spray Polyurethane Foam Systems
- Underlayments, Insulation and Accessories
Roof Slope
- Steep-Slope Roofing
- Low-Slope Roofing
Installation Type
- Re-Roofing and Repair
- New Construction
End Use
- Residential Buildings
- Commercial Buildings
- Industrial and Institutional Buildings
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the roofing market in 2026?
The roofing market is valued at US$ 142.0 billion in 2026, measured at manufacturer level for roofing materials and systems excluding installation labor.
What is the roofing market forecast and CAGR to 2033?
The market is projected to reach US$ 187.0 billion by 2033, growing at a 4.0% CAGR and adding US$ 45.0 billion in absolute dollar opportunity.
Which roofing product type holds the largest share?
Asphalt and bituminous shingles lead with 31.8% share in 2026, supported by the lowest installed cost and the widest contractor and distributor coverage.
Which roofing segment is growing fastest through 2033?
Single-ply membranes grow fastest at a 5.3% CAGR, driven by thermoplastic polyolefin recover work on commercial, warehouse and distribution building roofs.
Which region leads the roofing market and how competitive is it?
North America leads with 34.0% share in 2026, and the market is moderately concentrated, with scale producers strongest in shingles, membranes and insulation.
1. Executive Summary
1.1. Global Roofing Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Aging Roof Stock Makes Roofing a Replacement Business Before It Is a Construction Business
2.3.1.2. Storm Frequency and Insured Loss Settlements Set the Timing of Roofing Replacement
2.3.2. Restraints
2.3.2.1. Installer Shortage Caps How Much Roofing Can Be Fitted Regardless of Demand
2.3.2.2. Insurance Tightening in Storm Regions Limits Who Can Afford a Roof Replacement
2.3.3. Market Opportunities
2.3.3.1. Cool and Reflective Roofing Opens a Code-Pulled Premium Tier in Roofing Products
2.3.3.2. Solar-Ready Roof Assemblies Create an Attachment and Warranty Revenue Pool in Roofing
3. Global Roofing Market Outlook, 2020–2033
3.1. Global Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
3.1.1. Asphalt and Bituminous Shingles
3.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
3.1.3. Modified Bitumen and Built-Up Roofing
3.1.4. Metal Roofing
3.1.5. Clay and Concrete Tile
3.1.6. Slate and Synthetic Slate
3.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
3.1.8. Underlayments, Insulation and Accessories
3.2. Global Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
3.2.1. Steep-Slope Roofing
3.2.2. Low-Slope Roofing
3.3. Global Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
3.3.1. Re-Roofing and Repair
3.3.2. New Construction
3.4. Global Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
3.4.1. Residential Buildings
3.4.2. Commercial Buildings
3.4.3. Industrial and Institutional Buildings
3.5. Global Roofing Market Outlook, by Region, Value (US$ Billion), 2020–2033
3.5.1. North America
3.5.2. Europe
3.5.3. Asia Pacific
3.5.4. Latin America
3.5.5. Middle East & Africa
4. North America Roofing Market Outlook, 2020–2033
4.1. North America Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
4.1.1. Asphalt and Bituminous Shingles
4.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
4.1.3. Modified Bitumen and Built-Up Roofing
4.1.4. Metal Roofing
4.1.5. Clay and Concrete Tile
4.1.6. Slate and Synthetic Slate
4.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
4.1.8. Underlayments, Insulation and Accessories
4.2. North America Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
4.2.1. Steep-Slope Roofing
4.2.2. Low-Slope Roofing
4.3. North America Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
4.3.1. Re-Roofing and Repair
4.3.2. New Construction
4.4. North America Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
4.4.1. Residential Buildings
4.4.2. Commercial Buildings
4.4.3. Industrial and Institutional Buildings
4.5. North America Roofing Market Outlook, by Country, Value (US$ Billion), 2020–2033
4.5.1. United States Roofing Market Outlook, by Product Type, 2020–2033
4.5.2. United States Roofing Market Outlook, by Roof Slope, 2020–2033
4.5.3. United States Roofing Market Outlook, by Installation Type, 2020–2033
4.5.4. United States Roofing Market Outlook, by End Use, 2020–2033
4.5.5. Canada Roofing Market Outlook, by Product Type, 2020–2033
4.5.6. Canada Roofing Market Outlook, by Roof Slope, 2020–2033
4.5.7. Canada Roofing Market Outlook, by Installation Type, 2020–2033
4.5.8. Canada Roofing Market Outlook, by End Use, 2020–2033
4.5.9. Mexico Roofing Market Outlook, by Product Type, 2020–2033
4.5.10. Mexico Roofing Market Outlook, by Roof Slope, 2020–2033
4.5.11. Mexico Roofing Market Outlook, by Installation Type, 2020–2033
4.5.12. Mexico Roofing Market Outlook, by End Use, 2020–2033
5. Europe Roofing Market Outlook, 2020–2033
5.1. Europe Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
5.1.1. Asphalt and Bituminous Shingles
5.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
5.1.3. Modified Bitumen and Built-Up Roofing
5.1.4. Metal Roofing
5.1.5. Clay and Concrete Tile
5.1.6. Slate and Synthetic Slate
5.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
5.1.8. Underlayments, Insulation and Accessories
5.2. Europe Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
5.2.1. Steep-Slope Roofing
5.2.2. Low-Slope Roofing
5.3. Europe Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
5.3.1. Re-Roofing and Repair
5.3.2. New Construction
5.4. Europe Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
5.4.1. Residential Buildings
5.4.2. Commercial Buildings
5.4.3. Industrial and Institutional Buildings
5.5. Europe Roofing Market Outlook, by Country, Value (US$ Billion), 2020–2033
5.5.1. Germany Roofing Market Outlook, by Product Type, 2020–2033
5.5.2. Germany Roofing Market Outlook, by Roof Slope, 2020–2033
5.5.3. Germany Roofing Market Outlook, by Installation Type, 2020–2033
5.5.4. Germany Roofing Market Outlook, by End Use, 2020–2033
5.5.5. France Roofing Market Outlook, by Product Type, 2020–2033
5.5.6. France Roofing Market Outlook, by Roof Slope, 2020–2033
5.5.7. France Roofing Market Outlook, by Installation Type, 2020–2033
5.5.8. France Roofing Market Outlook, by End Use, 2020–2033
5.5.9. Italy Roofing Market Outlook, by Product Type, 2020–2033
5.5.10. Italy Roofing Market Outlook, by Roof Slope, 2020–2033
5.5.11. Italy Roofing Market Outlook, by Installation Type, 2020–2033
5.5.12. Italy Roofing Market Outlook, by End Use, 2020–2033
5.5.13. United Kingdom Roofing Market Outlook, by Product Type, 2020–2033
5.5.14. United Kingdom Roofing Market Outlook, by Roof Slope, 2020–2033
5.5.15. United Kingdom Roofing Market Outlook, by Installation Type, 2020–2033
5.5.16. United Kingdom Roofing Market Outlook, by End Use, 2020–2033
5.5.17. Poland Roofing Market Outlook, by Product Type, 2020–2033
5.5.18. Poland Roofing Market Outlook, by Roof Slope, 2020–2033
5.5.19. Poland Roofing Market Outlook, by Installation Type, 2020–2033
5.5.20. Poland Roofing Market Outlook, by End Use, 2020–2033
6. Asia Pacific Roofing Market Outlook, 2020–2033
6.1. Asia Pacific Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
6.1.1. Asphalt and Bituminous Shingles
6.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
6.1.3. Modified Bitumen and Built-Up Roofing
6.1.4. Metal Roofing
6.1.5. Clay and Concrete Tile
6.1.6. Slate and Synthetic Slate
6.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
6.1.8. Underlayments, Insulation and Accessories
6.2. Asia Pacific Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
6.2.1. Steep-Slope Roofing
6.2.2. Low-Slope Roofing
6.3. Asia Pacific Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
6.3.1. Re-Roofing and Repair
6.3.2. New Construction
6.4. Asia Pacific Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
6.4.1. Residential Buildings
6.4.2. Commercial Buildings
6.4.3. Industrial and Institutional Buildings
6.5. Asia Pacific Roofing Market Outlook, by Country, Value (US$ Billion), 2020–2033
6.5.1. China Roofing Market Outlook, by Product Type, 2020–2033
6.5.2. China Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.3. China Roofing Market Outlook, by Installation Type, 2020–2033
6.5.4. China Roofing Market Outlook, by End Use, 2020–2033
6.5.5. India Roofing Market Outlook, by Product Type, 2020–2033
6.5.6. India Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.7. India Roofing Market Outlook, by Installation Type, 2020–2033
6.5.8. India Roofing Market Outlook, by End Use, 2020–2033
6.5.9. Indonesia Roofing Market Outlook, by Product Type, 2020–2033
6.5.10. Indonesia Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.11. Indonesia Roofing Market Outlook, by Installation Type, 2020–2033
6.5.12. Indonesia Roofing Market Outlook, by End Use, 2020–2033
6.5.13. Vietnam Roofing Market Outlook, by Product Type, 2020–2033
6.5.14. Vietnam Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.15. Vietnam Roofing Market Outlook, by Installation Type, 2020–2033
6.5.16. Vietnam Roofing Market Outlook, by End Use, 2020–2033
6.5.17. Japan Roofing Market Outlook, by Product Type, 2020–2033
6.5.18. Japan Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.19. Japan Roofing Market Outlook, by Installation Type, 2020–2033
6.5.20. Japan Roofing Market Outlook, by End Use, 2020–2033
6.5.21. Australia Roofing Market Outlook, by Product Type, 2020–2033
6.5.22. Australia Roofing Market Outlook, by Roof Slope, 2020–2033
6.5.23. Australia Roofing Market Outlook, by Installation Type, 2020–2033
6.5.24. Australia Roofing Market Outlook, by End Use, 2020–2033
7. Latin America Roofing Market Outlook, 2020–2033
7.1. Latin America Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
7.1.1. Asphalt and Bituminous Shingles
7.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
7.1.3. Modified Bitumen and Built-Up Roofing
7.1.4. Metal Roofing
7.1.5. Clay and Concrete Tile
7.1.6. Slate and Synthetic Slate
7.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
7.1.8. Underlayments, Insulation and Accessories
7.2. Latin America Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
7.2.1. Steep-Slope Roofing
7.2.2. Low-Slope Roofing
7.3. Latin America Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
7.3.1. Re-Roofing and Repair
7.3.2. New Construction
7.4. Latin America Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
7.4.1. Residential Buildings
7.4.2. Commercial Buildings
7.4.3. Industrial and Institutional Buildings
7.5. Latin America Roofing Market Outlook, by Country, Value (US$ Billion), 2020–2033
7.5.1. Brazil Roofing Market Outlook, by Product Type, 2020–2033
7.5.2. Brazil Roofing Market Outlook, by Roof Slope, 2020–2033
7.5.3. Brazil Roofing Market Outlook, by Installation Type, 2020–2033
7.5.4. Brazil Roofing Market Outlook, by End Use, 2020–2033
7.5.5. Mexico Roofing Market Outlook, by Product Type, 2020–2033
7.5.6. Mexico Roofing Market Outlook, by Roof Slope, 2020–2033
7.5.7. Mexico Roofing Market Outlook, by Installation Type, 2020–2033
7.5.8. Mexico Roofing Market Outlook, by End Use, 2020–2033
7.5.9. Colombia Roofing Market Outlook, by Product Type, 2020–2033
7.5.10. Colombia Roofing Market Outlook, by Roof Slope, 2020–2033
7.5.11. Colombia Roofing Market Outlook, by Installation Type, 2020–2033
7.5.12. Colombia Roofing Market Outlook, by End Use, 2020–2033
7.5.13. Chile Roofing Market Outlook, by Product Type, 2020–2033
7.5.14. Chile Roofing Market Outlook, by Roof Slope, 2020–2033
7.5.15. Chile Roofing Market Outlook, by Installation Type, 2020–2033
7.5.16. Chile Roofing Market Outlook, by End Use, 2020–2033
7.5.17. Argentina Roofing Market Outlook, by Product Type, 2020–2033
7.5.18. Argentina Roofing Market Outlook, by Roof Slope, 2020–2033
7.5.19. Argentina Roofing Market Outlook, by Installation Type, 2020–2033
7.5.20. Argentina Roofing Market Outlook, by End Use, 2020–2033
8. Middle East & Africa Roofing Market Outlook, 2020–2033
8.1. Middle East & Africa Roofing Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
8.1.1. Asphalt and Bituminous Shingles
8.1.2. Single-Ply Membranes (TPO, EPDM, PVC)
8.1.3. Modified Bitumen and Built-Up Roofing
8.1.4. Metal Roofing
8.1.5. Clay and Concrete Tile
8.1.6. Slate and Synthetic Slate
8.1.7. Liquid-Applied and Spray Polyurethane Foam Systems
8.1.8. Underlayments, Insulation and Accessories
8.2. Middle East & Africa Roofing Market Outlook, by Roof Slope, Value (US$ Billion), 2020–2033
8.2.1. Steep-Slope Roofing
8.2.2. Low-Slope Roofing
8.3. Middle East & Africa Roofing Market Outlook, by Installation Type, Value (US$ Billion), 2020–2033
8.3.1. Re-Roofing and Repair
8.3.2. New Construction
8.4. Middle East & Africa Roofing Market Outlook, by End Use, Value (US$ Billion), 2020–2033
8.4.1. Residential Buildings
8.4.2. Commercial Buildings
8.4.3. Industrial and Institutional Buildings
8.5. Middle East & Africa Roofing Market Outlook, by Country, Value (US$ Billion), 2020–2033
8.5.1. Saudi Arabia Roofing Market Outlook, by Product Type, 2020–2033
8.5.2. Saudi Arabia Roofing Market Outlook, by Roof Slope, 2020–2033
8.5.3. Saudi Arabia Roofing Market Outlook, by Installation Type, 2020–2033
8.5.4. Saudi Arabia Roofing Market Outlook, by End Use, 2020–2033
8.5.5. United Arab Emirates Roofing Market Outlook, by Product Type, 2020–2033
8.5.6. United Arab Emirates Roofing Market Outlook, by Roof Slope, 2020–2033
8.5.7. United Arab Emirates Roofing Market Outlook, by Installation Type, 2020–2033
8.5.8. United Arab Emirates Roofing Market Outlook, by End Use, 2020–2033
8.5.9. Qatar Roofing Market Outlook, by Product Type, 2020–2033
8.5.10. Qatar Roofing Market Outlook, by Roof Slope, 2020–2033
8.5.11. Qatar Roofing Market Outlook, by Installation Type, 2020–2033
8.5.12. Qatar Roofing Market Outlook, by End Use, 2020–2033
8.5.13. Egypt Roofing Market Outlook, by Product Type, 2020–2033
8.5.14. Egypt Roofing Market Outlook, by Roof Slope, 2020–2033
8.5.15. Egypt Roofing Market Outlook, by Installation Type, 2020–2033
8.5.16. Egypt Roofing Market Outlook, by End Use, 2020–2033
8.5.17. South Africa Roofing Market Outlook, by Product Type, 2020–2033
8.5.18. South Africa Roofing Market Outlook, by Roof Slope, 2020–2033
8.5.19. South Africa Roofing Market Outlook, by Installation Type, 2020–2033
8.5.20. South Africa Roofing Market Outlook, by End Use, 2020–2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Owens Corning
9.5.2. Standard Industries
9.5.3. Carlisle Companies
9.5.4. Holcim
9.5.5. Kingspan Group
9.5.6. Saint-Gobain
9.5.7. IKO Industries
9.5.8. TAMKO Building Products
9.5.9. Etex Group
9.5.10. Johns Manville
9.5.11. Sika AG
9.5.12. Soprema Group
9.5.13. Wienerberger AG
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Product Type | Asphalt and Bituminous Shingles, Single-Ply Membranes (TPO, EPDM, PVC), Modified Bitumen and Built-Up Roofing, Metal Roofing, Clay and Concrete Tile, Slate and Synthetic Slate, Liquid-Applied and Spray Polyurethane Foam Systems, Underlayments, Insulation and Accessories |
| Roof Slope | Steep-Slope Roofing, Low-Slope Roofing |
| Installation Type | Re-Roofing and Repair, New Construction |
| End Use | Residential Buildings, Commercial Buildings, Industrial and Institutional Buildings |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The roofing market is valued at US$ 142.0 billion in 2026, measured at manufacturer level for roofing materials and systems excluding installation labor.
The market is projected to reach US$ 187.0 billion by 2033, growing at a 4.0% CAGR and adding US$ 45.0 billion in absolute dollar opportunity.
Asphalt and bituminous shingles lead with 31.8% share in 2026, supported by the lowest installed cost and the widest contractor and distributor coverage.
Single-ply membranes grow fastest at a 5.3% CAGR, driven by thermoplastic polyolefin recover work on commercial, warehouse and distribution building roofs.
North America leads with 34.0% share in 2026, and the market is moderately concentrated, with scale producers strongest in shingles, membranes and insulation.
Related Reports
Ethyl Acetate Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The ethyl acetate market is projected to grow from US$4.6 billion in 2026 to US$6.1 billion by 2033, at a CAGR of 4.1%, led by Asia Pacific packaging demand.
Flooring Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The flooring market is projected to grow from US$265.0 billion in 2026 to US$373.0 billion by 2033, at a CAGR of 5.0%, led by renovation and resilient floors.
Carbon Fiber Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The carbon fiber market is projected to grow from US$16.8 billion in 2026 to US$32.3 billion by 2033, at a CAGR of 9.8%, led by aerospace and wind energy.
Polymer Emulsion Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Polymer emulsion market to grow from US$44.8 Bn in 2026 to US$66.5 Bn by 2033 at 5.8% CAGR. Explore products, applications, end-use industries and regions.
On The Go Packaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
On the go packaging market to grow from US$2.19 Bn in 2026 to US$3.00 Bn by 2033 at 4.6% CAGR. Explore materials, products, applications and regions.
Nylon 6 Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Nylon 6 market to reach US$ 26.95 billion by 2033 at a 5.6% CAGR. Explore product forms, applications, feedstocks, leading companies and regional trends.