


Smart Lighting Market
Smart Lighting Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Smart Lighting Market Size and Trend Analysis
How Fast Is the Smart Lighting Market Growing?
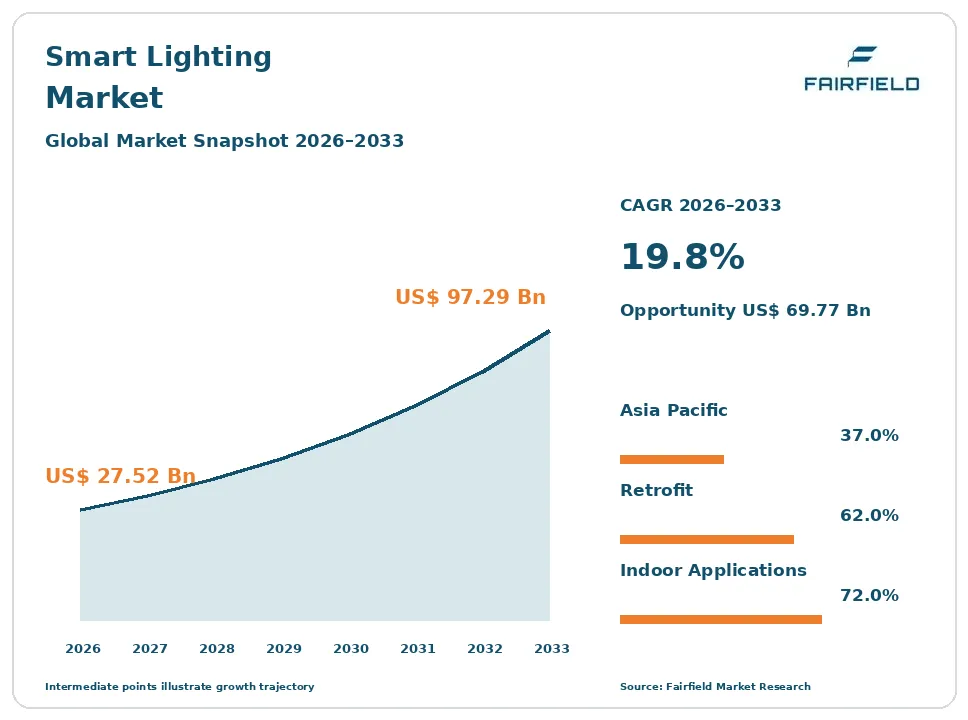
The global smart lighting market size is expected to be valued at US$ 27.52 billion in 2026 and projected to reach US$ 97.29 billion by 2033, growing at a CAGR of 19.8% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 17.5%, as LED prices fell and homeowners, businesses, and cities adopted lights they could control through apps, sensors, and voice assistants. Smart lighting combines LED lamps and fixtures with wireless chips, sensors, and software, forming connected lighting systems linked to the IoT. Three factors now drive growth: government rules and incentives for energy savings in buildings, the spread of smart homes and the Matter standard that lets devices from different brands work together, and city projects for smart street lighting. The market is shifting toward AI-driven lighting that adjusts to occupancy and daylight, lighting that doubles as a sensor network for building management, and human-centric lighting that supports health and comfort. New products in 2025, such as Signify’s Philips Hue Bridge Pro and AI assistant, show the move toward smarter home systems.
Key Report Takeaways
- By Product Type: Smart Lamps and Fixtures held 54.0% share in 2026, while Control Systems are projected to expand at a 20.2% CAGR through 2033, driven by demand for sensors, gateways, and software that manage whole buildings.
- By Installation Type: Retrofit held 62.0% share in 2026, while New Construction is projected to expand at a 20.1% CAGR through 2033, driven by building codes that require lighting controls in new projects.
- By Application: Indoor held 72.0% share in 2026, while Outdoor is projected to expand at a 21.4% CAGR through 2033, driven by smart street lighting in cities and highways.
- By Region: Asia Pacific held 37.0% share in 2026, while Middle East & Africa is projected to expand at a 20.7% CAGR through 2033, driven by smart city projects in Saudi Arabia and the United Arab Emirates.
Global Smart Lighting Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Energy efficiency rules and building codes | High | North America, Europe, Asia Pacific | Medium term (2-4 years) |
| Smart home adoption and interoperability | High | Global | Long term (≥4 years) |
Two drivers carry the strongest influence on smart lighting demand during the forecast period.
Energy Efficiency Rules Are Driving the Smart Lighting Market
Energy efficiency rules and building codes are the strongest driver of the smart lighting market. Governments want to cut electricity use and carbon emissions from buildings.
The mechanism is regulation combined with clear energy savings. Lighting uses a large share of electricity in offices, schools, hospitals, and warehouses, and smart controls that dim lights or switch them off when rooms are empty can cut lighting energy use by half or more. Building codes in the United States, such as ASHRAE 90.1 and California’s Title 24, require occupancy sensors and daylight controls in many new buildings. The European Union’s Energy Performance of Buildings Directive pushes for smarter, low-energy buildings. Utilities offer rebates for networked lighting controls. Companies set climate targets that include lighting upgrades. These factors make smart lighting a standard choice in commercial projects.
Smart Home Growth Is Expanding the Smart Lighting Market
Smart home adoption and better interoperability are expanding the smart lighting market. Lighting is often the first smart device people buy.
The cause is falling prices and easier setup. Smart bulbs, light strips, and switches can be installed without an electrician and controlled through smartphones and voice assistants from Amazon, Google, and Apple. The Matter standard, backed by major technology firms, lets products from different brands work together, reducing confusion for buyers. Many smart lights also connect to security cameras, sensors, and entertainment systems. Signify launched the Philips Hue Bridge Pro and an AI assistant in 2025, adding new home automation features. Xiaomi, Wyze, and Govee sell low-cost products. These trends broaden the customer base beyond technology fans.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| High upfront costs and complex installation | High | Global | Short term (≤2 years) |
| Cybersecurity and interoperability concerns | Medium | North America, Europe | Medium term (2-4 years) |
Two restraints limit how quickly the smart lighting market grows.
High Upfront Costs Slow the Smart Lighting Market
High upfront costs and complex installation slow the smart lighting market. Smart systems cost more than standard LED lighting.
The specific causes are hardware, software, and design costs. A smart bulb can cost several times more than a basic LED bulb, and commercial systems need sensors, gateways, software licenses, and commissioning by trained installers. Large building projects often require lighting designers and IT teams to work together, adding complexity. Many building owners focus on the lowest upfront price rather than long-term energy savings. Small businesses and landlords may not see enough benefit to justify the cost. Payback periods can stretch to several years in places with cheap electricity. Rising prices for chips and components after 2021 also raised product costs for a time. These factors slow adoption, especially in developing countries and older buildings.
Security Concerns Restrict the Smart Lighting Market
Cybersecurity and interoperability concerns restrict the smart lighting market. Connected lights can become entry points for hackers.
The underlying causes are weak device security and fragmented standards. Low-cost smart bulbs may use outdated software that is not updated, and researchers have shown how hackers can use smart lights to break into home networks. Businesses worry about connecting lighting to the same networks as computers and sensitive data. Many systems still use different wireless protocols, such as Zigbee, Bluetooth, and Wi-Fi, which do not always work together. Products from companies that shut down can stop working if they depend on cloud services. Large companies often require security reviews before approving connected building systems, which adds time to projects. New cybersecurity rules for connected devices in Europe and the United States will raise compliance costs for makers. These factors make some buyers cautious and slow upgrades.
Market Opportunities
Smart Street Lighting Opens a Public Infrastructure Revenue Pool
Smart street lighting opens a public infrastructure revenue pool in the smart lighting market. Cities want to cut energy costs and improve public services.
Suppliers with outdoor lighting and city software can capture this opportunity. Connected street lights can dim when roads are empty, report faults automatically, and host cameras, air quality sensors, EV chargers, and 5G small cells. Cities in India, China, Saudi Arabia, the United Arab Emirates, Brazil, and Mexico are replacing old street lights with smart LED systems. Energy savings help pay for upgrades through performance contracts. Signify and Acuity Brands offer street lighting management platforms. Long-term service contracts add steady revenue. Smart poles can also earn rental income from telecom carriers that place equipment on them, helping cities fund upgrades.
Lighting as a Building Data Platform Creates a Software Revenue Pool
Lighting as a building data platform creates a software revenue pool in the smart lighting market. Light fixtures are spread across every room, making them ideal for sensors.
Suppliers that combine lighting with software and analytics can capture this opportunity. Smart fixtures with occupancy and environmental sensors can track how spaces are used, guide heating and cooling, and help with indoor navigation and asset tracking. Building owners use this data to cut energy use and redesign offices. Acuity Brands agreed to buy QSC in 2024 to strengthen its intelligent spaces business. Software subscriptions and data services raise revenue per building. These offerings also create long-term customer relationships. Integration with IoT platforms for heating, security, and space booking makes lighting central to smart buildings. Hybrid work has increased demand for data on how offices are actually used.
Segment Analysis
By Product Type: Smart Lamps and Fixtures Lead While Control Systems Grow Fastest
Smart Lamps and Fixtures held 54.0% share in 2026. This group includes smart bulbs, light strips, ceiling fixtures, and outdoor luminaires with built-in wireless chips. Consumers buy smart bulbs for homes, while businesses install connected fixtures in offices, stores, and warehouses. Signify, Acuity Brands, Cree Lighting, Xiaomi, and Opple Lighting sell large volumes.
Control Systems are the fastest-growing product type, expanding at a 20.2% CAGR through 2033. This group includes sensors, switches, dimmers, gateways, and software that manage many lights at once. Lutron Electronics, Legrand, Eaton, and Hubbell lead in controls. Building codes, energy targets, and corporate climate goals drive demand for networked controls. For the market, control growth raises software and service revenue.
By Installation Type: Retrofit Leads While New Construction Grows Fastest
Retrofit held 62.0% share in 2026. Most buildings that exist today will still be in use for decades, so upgrading their lighting is the biggest near-term opportunity for suppliers. Wireless smart bulbs and controls make retrofits easier because they do not need new wiring. Utility rebates and energy service contracts support upgrades in offices, schools, and warehouses.
New Construction is the fastest-growing installation type, expanding at a 20.1% CAGR through 2033. New buildings increasingly include smart lighting from the design stage to meet codes and green building standards. Smart cities and new urban projects add demand, and developers use smart lighting to earn green building certifications that raise property values. For the market, new construction growth supports integrated systems.
By Application: Indoor Leads While Outdoor Grows Fastest
Indoor held 72.0% share in 2026. Homes, offices, retail stores, hotels, hospitals, and factories make up most smart lighting demand. Residential smart lighting is the largest consumer segment, while commercial buildings buy larger systems with sensors and central software. Human-centric lighting that changes color temperature during the day is growing in offices, schools, and hospitals.
Outdoor is the fastest-growing application, expanding at a 21.4% CAGR through 2033. Smart street lighting, parking lots, stadiums, and highways use connected lights to cut energy use and improve safety. Cities are adding sensors, cameras, and EV chargers to street poles. Sports venues use connected lighting for light shows and broadcast quality. For the market, outdoor growth adds public sector projects.
Geography Analysis
North America Advances the Smart Lighting Market Through Building Codes
North America is a major smart lighting market. The United States has strict energy codes in states such as California, high smart home adoption, and large commercial building stock. Acuity Brands, Lutron Electronics, Hubbell, Eaton, and Cree Lighting are based here. Utility rebate programs support networked lighting controls in offices, schools, and warehouses. Canada has similar energy programs. Smart home brands such as Wyze, Nanoleaf, and Feit Electric compete in consumer retail. Key barriers include high costs for small buildings and cybersecurity worries. One change shaping the region is lighting linked to building management.
Europe Builds the Smart Lighting Market Through Climate Targets
Europe is a mature smart lighting market. The European Union’s climate and building rules push for energy-efficient lighting, and many countries have phased out older lamps. Signify is based in the Netherlands, Legrand in France, and Zumtobel Group in Austria. Germany, the United Kingdom, France, and Italy have large commercial and residential markets. Spain, Sweden, and Denmark are leaders in smart street lighting. Ecodesign rules also require longer-lasting, repairable products. Key barriers include data privacy concerns and slow public procurement. One opportunity is street light upgrades funded by EU recovery and climate programs.
Which Region Is Leading the Smart Lighting Market?
Asia Pacific is leading the smart lighting market with a 37.0% share in 2026. China is the largest single market and the main manufacturing hub for LED products, with companies such as Xiaomi and Opple Lighting. India is replacing millions of street lights with LEDs and building smart cities. Japan and South Korea have high smart home use, with Panasonic and Samsung active in connected homes. Australia and Singapore have strict energy rules for commercial buildings. Key barriers include price competition and low-quality products. One change shaping the region is smart city investment across China and India.
Latin America Grows the Smart Lighting Market Through Street Light Upgrades
Latin America is a growing smart lighting market. Brazil and Mexico have large city street light replacement programs in major urban areas, often run through public-private partnerships. Argentina, Chile, and Colombia are adopting smart lighting in cities and commercial buildings. Cities such as São Paulo and Mexico City have replaced hundreds of thousands of street lights with LEDs, and many are adding remote management. Smart home products are growing among urban consumers, sold mainly through online stores. Key barriers include limited budgets, currency swings, and theft of street lighting equipment. One opportunity is energy service contracts that pay for upgrades through savings.
Which Region Is Growing Fastest in the Smart Lighting Market?
Middle East & Africa is growing fastest in the smart lighting market at a 20.7% CAGR through 2033. Saudi Arabia is building new cities and tourism projects with smart infrastructure, and the United Arab Emirates is investing in smart buildings in Dubai and Abu Dhabi. Qatar, Oman, and Israel add demand from new buildings and stadiums. South Africa and Egypt are upgrading street lighting. Hotels, airports, and malls across the region use connected lighting to cut cooling and energy costs. Key barriers include high costs and limited local expertise. One change shaping the region is giga-projects.
Competitive Landscape
The smart lighting market is moderately concentrated. Signify, Acuity Brands, Lutron Electronics, Legrand, Hubbell, Eaton, and Cree Lighting lead in professional and commercial lighting, while Samsung, Xiaomi, Panasonic, Opple Lighting, Wyze, Nanoleaf, and Feit Electric compete strongly in consumer products. Zumtobel Group and EGLO are important in Europe.
Companies compete on product range, ease of use, design, compatibility with Matter and voice assistants, software features, reliability, and price. Professional lighting firms focus on complete systems for buildings, while consumer brands compete on design and cost. Partnerships with technology platforms and building management firms are important. Chinese makers compete strongly on price in consumer products, while large firms defend premium positions with software and service. Acquisitions help companies add new technology and customers quickly. Distribution through electrical wholesalers, retailers, and online stores also shapes market share.
Strategic moves show how competition is changing. In October 2024, Acuity Brands agreed to acquire QSC for US$ 1.215 billion. In November 2024, the Connectivity Standards Alliance released Matter 1.4, adding support for more energy devices. In September 2025, Signify launched the Philips Hue Bridge Pro and an AI assistant. These moves show competition shifting toward software and platforms.
Three themes shape vendor strategy. First, companies are adding AI to automate lighting scenes and energy use. Second, they are supporting Matter so products work across platforms. Third, they are buying software and audio-visual firms to offer complete building solutions.
Smart Lighting Market Industry Leaders
- Signify
- Acuity Brands
- Lutron Electronics
- Legrand
- Hubbell
Recent Industry Developments
- September 2025: Signify launched the Philips Hue Bridge Pro and new AI assistant features, along with new lamps and a video doorbell - expands Hue into wider smart home control.
- November 2024: The Connectivity Standards Alliance released Matter 1.4, extending the common smart home standard to more device types - improves interoperability for connected lighting.
- October 2024: Acuity Brands agreed to acquire QSC for US$ 1.215 billion - strengthens its intelligent spaces and building software business.
Companies Covered in the Report
- Signify
- Acuity Brands
- Lutron Electronics
- Legrand
- Hubbell
- Eaton
- Cree Lighting
- Samsung Electronics
- Xiaomi
- Panasonic
- Opple Lighting
- Zumtobel Group
Smart Lighting Market Report Scope
This report covers smart lighting products and systems, including smart lamps and fixtures, control systems, and software, for retrofit and new construction, used in indoor residential, commercial, and industrial spaces and outdoor street, highway, and public areas. It includes wired and wireless systems. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Product Type
- Smart Lamps and Fixtures
- Control Systems
- Software and Services
Installation Type
- Retrofit
- New Construction
Application
- Indoor
- Outdoor
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the smart lighting market in 2026?
The smart lighting market is valued at US$ 27.52 billion in 2026, led by smart lamps and fixtures in Asia Pacific.
What is the smart lighting market forecast to 2033?
The market is projected to reach US$ 97.29 billion by 2033, growing at a 19.8% CAGR and adding US$ 69.77 billion.
Which product type is growing fastest in the smart lighting market?
Control systems are growing fastest at a 20.2% CAGR through 2033, driven by sensors, gateways, and software for whole buildings.
Which region is growing fastest in the smart lighting market?
Middle East & Africa is growing fastest at a 20.7% CAGR through 2033, driven by smart city and giga-projects in Saudi Arabia.
Which region holds the largest smart lighting market share?
Asia Pacific holds the largest share at 37.0% in 2026, supported by China’s manufacturing base and large smart city programs.
1. Executive Summary
1.1. Global Smart Lighting Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Energy Efficiency Rules Are Driving the Smart Lighting Market
2.3.1.2. Smart Home Growth Is Expanding the Smart Lighting Market
2.3.2. Restraints
2.3.2.1. High Upfront Costs Slow the Smart Lighting Market
2.3.2.2. Security Concerns Restrict the Smart Lighting Market
2.3.3. Market Opportunities
2.3.3.1. Smart Street Lighting Opens a Public Infrastructure Revenue Pool
2.3.3.2. Lighting as a Building Data Platform Creates a Software Revenue Pool
3. Global Smart Lighting Market Outlook, 2020-2033
3.1. Global Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
3.1.1. Smart Lamps and Fixtures
3.1.2. Control Systems
3.1.3. Software and Services
3.2. Global Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
3.2.1. Retrofit
3.2.2. New Construction
3.3. Global Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
3.3.1. Indoor
3.3.2. Outdoor
3.4. Global Smart Lighting Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Smart Lighting Market Outlook, 2020-2033
4.1. North America Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
4.1.1. Smart Lamps and Fixtures
4.1.2. Control Systems
4.1.3. Software and Services
4.2. North America Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
4.2.1. Retrofit
4.2.2. New Construction
4.3. North America Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
4.3.1. Indoor
4.3.2. Outdoor
4.4. North America Smart Lighting Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Smart Lighting Market Outlook, by Product Type, 2020-2033
4.4.2. United States Smart Lighting Market Outlook, by Installation Type, 2020-2033
4.4.3. United States Smart Lighting Market Outlook, by Application, 2020-2033
4.4.4. Canada Smart Lighting Market Outlook, by Product Type, 2020-2033
4.4.5. Canada Smart Lighting Market Outlook, by Installation Type, 2020-2033
4.4.6. Canada Smart Lighting Market Outlook, by Application, 2020-2033
5. Europe Smart Lighting Market Outlook, 2020-2033
5.1. Europe Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
5.1.1. Smart Lamps and Fixtures
5.1.2. Control Systems
5.1.3. Software and Services
5.2. Europe Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
5.2.1. Retrofit
5.2.2. New Construction
5.3. Europe Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
5.3.1. Indoor
5.3.2. Outdoor
5.4. Europe Smart Lighting Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Netherlands Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.2. Netherlands Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.3. Netherlands Smart Lighting Market Outlook, by Application, 2020-2033
5.4.4. France Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.5. France Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.6. France Smart Lighting Market Outlook, by Application, 2020-2033
5.4.7. Austria Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.8. Austria Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.9. Austria Smart Lighting Market Outlook, by Application, 2020-2033
5.4.10. Germany Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.11. Germany Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.12. Germany Smart Lighting Market Outlook, by Application, 2020-2033
5.4.13. United Kingdom Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.14. United Kingdom Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.15. United Kingdom Smart Lighting Market Outlook, by Application, 2020-2033
5.4.16. Italy Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.17. Italy Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.18. Italy Smart Lighting Market Outlook, by Application, 2020-2033
5.4.19. Spain Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.20. Spain Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.21. Spain Smart Lighting Market Outlook, by Application, 2020-2033
5.4.22. Sweden Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.23. Sweden Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.24. Sweden Smart Lighting Market Outlook, by Application, 2020-2033
5.4.25. Denmark Smart Lighting Market Outlook, by Product Type, 2020-2033
5.4.26. Denmark Smart Lighting Market Outlook, by Installation Type, 2020-2033
5.4.27. Denmark Smart Lighting Market Outlook, by Application, 2020-2033
6. Asia Pacific Smart Lighting Market Outlook, 2020-2033
6.1. Asia Pacific Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
6.1.1. Smart Lamps and Fixtures
6.1.2. Control Systems
6.1.3. Software and Services
6.2. Asia Pacific Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
6.2.1. Retrofit
6.2.2. New Construction
6.3. Asia Pacific Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
6.3.1. Indoor
6.3.2. Outdoor
6.4. Asia Pacific Smart Lighting Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. China Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.2. China Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.3. China Smart Lighting Market Outlook, by Application, 2020-2033
6.4.4. India Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.5. India Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.6. India Smart Lighting Market Outlook, by Application, 2020-2033
6.4.7. Japan Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.8. Japan Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.9. Japan Smart Lighting Market Outlook, by Application, 2020-2033
6.4.10. South Korea Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.11. South Korea Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.12. South Korea Smart Lighting Market Outlook, by Application, 2020-2033
6.4.13. Australia Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.14. Australia Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.15. Australia Smart Lighting Market Outlook, by Application, 2020-2033
6.4.16. Singapore Smart Lighting Market Outlook, by Product Type, 2020-2033
6.4.17. Singapore Smart Lighting Market Outlook, by Installation Type, 2020-2033
6.4.18. Singapore Smart Lighting Market Outlook, by Application, 2020-2033
7. Latin America Smart Lighting Market Outlook, 2020-2033
7.1. Latin America Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
7.1.1. Smart Lamps and Fixtures
7.1.2. Control Systems
7.1.3. Software and Services
7.2. Latin America Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
7.2.1. Retrofit
7.2.2. New Construction
7.3. Latin America Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
7.3.1. Indoor
7.3.2. Outdoor
7.4. Latin America Smart Lighting Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Smart Lighting Market Outlook, by Product Type, 2020-2033
7.4.2. Brazil Smart Lighting Market Outlook, by Installation Type, 2020-2033
7.4.3. Brazil Smart Lighting Market Outlook, by Application, 2020-2033
7.4.4. Mexico Smart Lighting Market Outlook, by Product Type, 2020-2033
7.4.5. Mexico Smart Lighting Market Outlook, by Installation Type, 2020-2033
7.4.6. Mexico Smart Lighting Market Outlook, by Application, 2020-2033
7.4.7. Argentina Smart Lighting Market Outlook, by Product Type, 2020-2033
7.4.8. Argentina Smart Lighting Market Outlook, by Installation Type, 2020-2033
7.4.9. Argentina Smart Lighting Market Outlook, by Application, 2020-2033
7.4.10. Chile Smart Lighting Market Outlook, by Product Type, 2020-2033
7.4.11. Chile Smart Lighting Market Outlook, by Installation Type, 2020-2033
7.4.12. Chile Smart Lighting Market Outlook, by Application, 2020-2033
7.4.13. Colombia Smart Lighting Market Outlook, by Product Type, 2020-2033
7.4.14. Colombia Smart Lighting Market Outlook, by Installation Type, 2020-2033
7.4.15. Colombia Smart Lighting Market Outlook, by Application, 2020-2033
8. Middle East & Africa Smart Lighting Market Outlook, 2020-2033
8.1. Middle East & Africa Smart Lighting Market Outlook, by Product Type, Value (US$ Billion), 2020-2033
8.1.1. Smart Lamps and Fixtures
8.1.2. Control Systems
8.1.3. Software and Services
8.2. Middle East & Africa Smart Lighting Market Outlook, by Installation Type, Value (US$ Billion), 2020-2033
8.2.1. Retrofit
8.2.2. New Construction
8.3. Middle East & Africa Smart Lighting Market Outlook, by Application, Value (US$ Billion), 2020-2033
8.3.1. Indoor
8.3.2. Outdoor
8.4. Middle East & Africa Smart Lighting Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. Saudi Arabia Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.2. Saudi Arabia Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.3. Saudi Arabia Smart Lighting Market Outlook, by Application, 2020-2033
8.4.4. United Arab Emirates Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.5. United Arab Emirates Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.6. United Arab Emirates Smart Lighting Market Outlook, by Application, 2020-2033
8.4.7. Qatar Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.8. Qatar Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.9. Qatar Smart Lighting Market Outlook, by Application, 2020-2033
8.4.10. Oman Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.11. Oman Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.12. Oman Smart Lighting Market Outlook, by Application, 2020-2033
8.4.13. Israel Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.14. Israel Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.15. Israel Smart Lighting Market Outlook, by Application, 2020-2033
8.4.16. South Africa Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.17. South Africa Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.18. South Africa Smart Lighting Market Outlook, by Application, 2020-2033
8.4.19. Egypt Smart Lighting Market Outlook, by Product Type, 2020-2033
8.4.20. Egypt Smart Lighting Market Outlook, by Installation Type, 2020-2033
8.4.21. Egypt Smart Lighting Market Outlook, by Application, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Signify
9.5.2. Acuity Brands
9.5.3. Lutron Electronics
9.5.4. Legrand
9.5.5. Hubbell
9.5.6. Eaton
9.5.7. Cree Lighting
9.5.8. Samsung Electronics
9.5.9. Xiaomi
9.5.10. Panasonic
9.5.11. Opple Lighting
9.5.12. Zumtobel Group
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Product Type | Smart Lamps and Fixtures, Control Systems, Software and Services |
| Installation Type | Retrofit, New Construction |
| Application | Indoor, Outdoor |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The smart lighting market is valued at US$ 27.52 billion in 2026, led by smart lamps and fixtures in Asia Pacific.
The market is projected to reach US$ 97.29 billion by 2033, growing at a 19.8% CAGR and adding US$ 69.77 billion.
Control systems are growing fastest at a 20.2% CAGR through 2033, driven by sensors, gateways, and software for whole buildings.
Middle East & Africa is growing fastest at a 20.7% CAGR through 2033, driven by smart city and giga-projects in Saudi Arabia.
Asia Pacific holds the largest share at 37.0% in 2026, supported by China’s manufacturing base and large smart city programs.
Related Reports
Wearable Cameras Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global wearable cameras market is valued at US$8.80 billion in 2026, reaching US$20.80 billion by 2033, growing at a 13.1% CAGR
Spend Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global spend analytics market is valued at US$3.90 billion in 2026, reaching US$10.40 billion by 2033, growing at a 15.0% CAGR
IoT Security Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global IoT security market is valued at US$21.40 billion in 2026, reaching US$66.60 billion by 2033, growing at a 17.6% CAGR
Insurance Analytics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global insurance analytics market is valued at US$17.30 billion in 2026, reaching US$39.70 billion by 2033, growing at a 12.6% CAGR
Lit Fiber Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The lit fiber market is projected to grow from US$7.13 billion in 2026 to US$20.52 billion by 2033, at a 16.3% CAGR, driven by AI and cloud connectivity.
Laser Processing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The laser processing market is projected to grow from US$27.97 billion in 2026 to US$47.32 billion by 2033, at a 7.8% CAGR, driven by precision manufacturing.