


Sustainable Alternative Fuels Market
Sustainable Alternative Fuels Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Sustainable Alternative Fuels Market Size and Trend Analysis
How Fast Will Sustainable Alternative Fuels Grow by 2033?
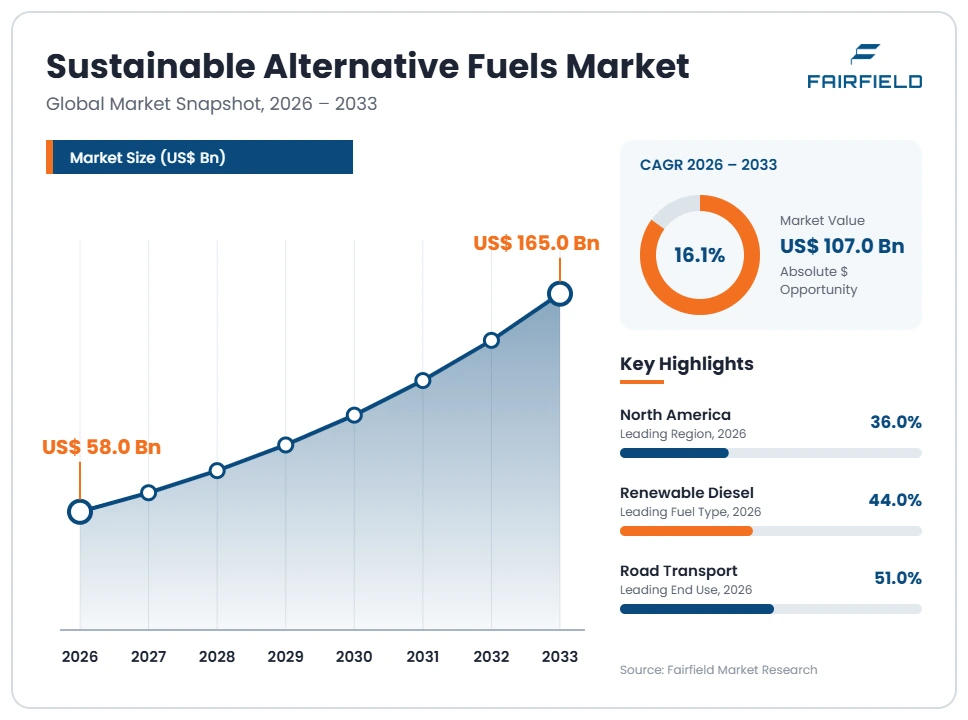
The global Sustainable Alternative Fuels market size is expected to be valued at US$ 58.0 billion in 2026 and projected to reach US$ 165.0 billion by 2033, growing at a CAGR of 16.1% between 2026 and 2033.
This figure counts sustainable aviation fuel, renewable diesel, biomethane and bio-LNG, renewable methanol and ammonia for marine use, and renewable fuels of non-biological origin together. The boundary matters, because renewable diesel alone accounts for most current revenue and excluding it roughly halves the market. Between 2020 and 2025 the sector grew at approximately a 34% CAGR from a very small base, led by renewable diesel capacity conversions. Forecast growth is slower but far larger in absolute terms, and it is mandate-driven rather than demand-driven. Blending obligations, not voluntary purchasing, set volumes. Feedstock availability and the cost premium over fossil fuels remain the binding constraints on how fast supply can follow.
Key Report Takeaways
- By Fuel Type: Renewable diesel held 44% share in 2026, while sustainable aviation fuel is projected to expand at a 24.8% CAGR through 2033, as escalating blending obligations at airports convert aviation demand from voluntary purchasing into legal compliance.
- By Production Pathway: Hydroprocessed esters and fatty acids held 68% share in 2026, while power-to-liquid is projected to grow at a 38.5% CAGR through 2033 from a near-zero base, supported by dedicated synthetic fuel sub-targets.
- By Feedstock: Waste oils and fats held 59% share in 2026, while agricultural and forestry residues are projected to expand at a 23.4% CAGR through 2033, because lignocellulosic supply is the only route past the waste lipid ceiling.
- By End Use: Road transport held 51% share in 2026, while marine shipping is projected to grow at a 27.2% CAGR through 2033, driven by greenhouse gas intensity limits applied to ships calling at European ports.
- By Geography: North America held 36% share in 2026, while Asia Pacific is projected to grow at a 21.5% CAGR through 2033, as national blending mandates and refinery conversions advance across China, India, Japan and Singapore.
Global Sustainable Alternative Fuels Market Trends and Insights
Drivers Impact Analysis
Two policy instruments account for almost all of the incremental volume expected through the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Escalating aviation and maritime fuel blending obligations | High | Europe, North America, Asia Pacific | Long term ≥4 years |
| Production tax credits that narrow the cost gap with fossil fuels | High | North America | Medium term 2–4 years |
Legally Binding Blending Quotas Convert Aviation and Shipping Demand Into Guaranteed Offtake
Mandates, not customer preference, create the demand curve in this market. Airlines and shipowners buy low-carbon fuel because non-compliance carries penalties, so volumes rise on a published schedule regardless of the price premium. That certainty is what makes project finance possible for plants whose output would otherwise have no committed buyer.
The mechanism is written into law. Regulation (EU) 2023/2405, known as ReFuelEU Aviation, obliges fuel suppliers at Union airports to blend a rising minimum share of sustainable aviation fuel, starting at 2% and escalating through the 2030s with a separate synthetic fuel sub-obligation. Regulation (EU) 2023/1805, FuelEU Maritime, applies a declining greenhouse gas intensity limit to energy used by ships calling at Union ports. Both instruments measure compliance in energy terms, which rewards fuels with verified lifecycle emissions reductions.
Clean Fuel Production Credits Compress the Premium That Blocks Voluntary Purchasing
Fiscal support changes the economics at the point of production rather than at the point of sale. A per-gallon credit tied to carbon intensity lowers the delivered cost of compliant fuel, narrowing the gap against fossil jet and diesel that would otherwise make purchases uneconomic outside a mandate. Where the credit is large enough, blending becomes commercially rational before any obligation applies.
The specific instrument is the United States clean fuel production credit established under the Inflation Reduction Act, which pays producers according to the lifecycle carbon intensity of the fuel and applies a higher rate to aviation fuel. The SAF Grand Challenge sets a complementary national production target. Because the credit scales with carbon intensity, it also steers investment toward lower-intensity feedstocks and pathways rather than simply rewarding volume.
Restraints Impact Analysis
Two hard constraints limit how quickly supply can expand, regardless of policy ambition.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Finite and contested supply of waste lipid feedstock | High | Global | Short term ≤2 years |
| Persistent cost premium over fossil jet fuel and diesel | High | Global | Long term ≥4 years |
Waste Lipid Scarcity Caps How Much Hydroprocessed Fuel the Industry Can Actually Produce
Feedstock is the binding constraint on this market, and it is a physical one. Hydroprocessing depends on used cooking oil, animal tallow, distillers corn oil and similar waste lipids, and the world generates only a limited quantity of these materials each year. That pool is already contested between renewable diesel producers, aviation fuel plants and conventional oleochemical buyers, so new capacity competes for a supply that does not grow with demand.
The consequence is visible in pricing and in integrity risk. Waste oil prices now track the value of the finished fuel rather than the cost of collection, which transfers margin from processors to collectors. Certification fraud has been a documented problem, with concerns about virgin oil being mislabelled as waste, prompting tighter verification under ISCC and RSB schemes. Those controls add cost and slow feedstock qualification.
The Cost Premium Over Fossil Fuel Keeps Uptake Tied to Obligation Rather Than Demand
Price is the second hard limit. Sustainable aviation fuel typically costs several times as much as conventional jet fuel, and synthetic routes cost more still. Fuel is one of the largest line items for airlines and shipping operators, both industries with thin margins, so no commercial buyer absorbs that premium voluntarily at scale. Uptake therefore stops at the level the mandate requires.
The cost structure explains why the gap persists. For hydroprocessed fuel, feedstock represents the dominant share of production cost, so process efficiency gains cannot close it. For power-to-liquid, the cost is renewable electricity and electrolyser capital, both of which must fall substantially before output competes on price. Advanced gasification and alcohol-to-jet plants carry high capital intensity, unproven operating records and long construction schedules, so lenders price that risk into financing and push the delivered cost higher still.
Market Opportunities
Alcohol-to-Jet and Gasification Routes Open a Feedstock Pool Beyond Waste Lipids
Breaking the lipid ceiling is the largest untapped revenue pool in this market. Alcohol-to-jet conversion uses ethanol and other alcohols, while Fischer-Tropsch gasification accepts agricultural residues, forestry waste and the organic fraction of municipal waste. These feedstocks exist in far greater volume than waste oils, are not already fully contracted, and are geographically distributed rather than concentrated in a few collection networks.
Capture favours players who can combine process licensing, large capital and feedstock aggregation. The demand comes from airlines facing obligations that will exceed what hydroprocessing can physically supply later in the forecast period. The supporting instrument is Directive (EU) 2023/2413, the recast renewable energy framework, which sets advanced biofuel sub-targets that specifically reward residue-based and waste-based routes over crop-derived and lipid-derived fuels. That sub-target gives residue projects a policy premium independent of the wider blending quota.
Marine Methanol and Ammonia Bunkering Creates a New Port-Side Fuel Supply Business
Marine fuel is an emerging revenue pool distinct from the aviation and road markets. Shipowners facing tightening greenhouse gas intensity limits need bunkering infrastructure for renewable methanol and, later, ammonia at major ports. That requires storage, barge fleets, transfer equipment, crew training and safety procedures, almost none of which exists today at commercial scale.
The opportunity belongs to port authorities, fuel traders, terminal operators and energy companies with bunkering licences rather than to refiners alone. Demand concentrates at a limited number of high-traffic bunkering hubs, because ships refuel where routes already converge. FuelEU Maritime supplies the regulatory pull by penalising energy with high greenhouse gas intensity, while ISCC certification provides the chain-of-custody evidence that compliance accounting requires. Methanol is the near-term fuel; ammonia follows once safety frameworks mature.
Segment Analysis
- By Fuel Type: Renewable Diesel Leads Today While Sustainable Aviation Fuel Scales Fastest
Renewable diesel held 44% share in 2026, the largest position by value, because it is chemically interchangeable with fossil diesel, needs no engine or infrastructure change, and benefits from a decade of refinery conversions already completed. Biomethane and bio-LNG follow, supported by established anaerobic digestion assets. Sustainable aviation fuel is the fastest-growing fuel at a 24.8% CAGR through 2033, driven entirely by blending obligations at airports rather than by airline preference. Renewable methanol and ammonia remain small but are the designated marine solutions, while renewable fuels of non-biological origin stay negligible in volume through most of the period. The implication is a deliberate reallocation of molecules: producers are redirecting existing hydroprocessing capacity from diesel toward jet fuel, because aviation carries both the stricter mandate and the higher credit value.
- By Production Pathway: Hydroprocessing Dominates While Power-to-Liquid Grows From Near Zero
Hydroprocessed esters and fatty acids accounted for 68% of 2026 output value, overwhelmingly the dominant pathway, because the technology is mature, certified for blending, and deployable by converting existing refinery hydrotreaters. Anaerobic digestion with upgrading supplies the biomethane stream. Alcohol-to-jet and Fischer-Tropsch gasification are advancing but remain capital-intensive and largely pre-commercial. Power-to-liquid is the fastest-growing pathway at a 38.5% CAGR through 2033, a rate that reflects an extremely small starting base rather than commercial maturity. Its growth depends on cheap renewable electricity, electrolyser cost reduction and the delegated act rules on additionality and temporal correlation. The business implication is that the industry’s near-term output is locked into one pathway, which means feedstock risk and technology risk are concentrated rather than diversified.
- By Feedstock: Waste Oils and Fats Lead Supply While Residues Grow Fastest
Waste oils and fats held 59% share in 2026, reflecting the dominance of hydroprocessing. Used cooking oil, animal tallow and distillers corn oil are collected through established networks and convert efficiently, but global supply is finite and already contested across multiple industries. Agricultural and forestry residues are the fastest-growing feedstock at a 23.4% CAGR through 2033, because they are the only abundant resource capable of lifting the industry past the lipid ceiling. Municipal and industrial waste follows a similar logic. Energy crops remain constrained by land-use and food-competition rules, while green hydrogen with captured carbon dioxide underpins synthetic routes. The implication is that feedstock strategy now determines competitive position more than conversion technology, since every producer uses broadly similar hydroprocessing and the differentiator is secured, certified supply.
- By End Use: Road Transport Holds the Volume While Marine Shipping Accelerates
Road transport represented 51% of 2026 value, the largest end use, because renewable diesel substitutes directly into existing truck and fleet operations and because road fuel mandates have been in place far longer than aviation or marine obligations. Aviation is the second outlet and the one attracting most new investment. Marine shipping is the fastest-growing end use at a 27.2% CAGR through 2033, driven by greenhouse gas intensity limits on energy used by ships calling at European ports and by the sector’s need for fuels that work on long ocean routes. Rail, off-highway and industrial heat absorb smaller volumes. The implication is a shift in customer type: the buyer base is moving from fleet operators and fuel retailers toward airlines, shipping lines and port bunkering operators with very different contracting practices.
Geography Analysis
- Which Region Is Leading the Sustainable Alternative Fuels Market?
North America leads the sustainable alternative fuels market with 36% share in 2026, built on the largest installed renewable diesel capacity anywhere. The United States dominates, with Canada contributing through its clean fuel regulations and western feedstock supply. Three causes explain the position. Refinery conversions to hydroprocessing happened earlier and at greater scale here than elsewhere. The clean fuel production credit created under the Inflation Reduction Act pays according to lifecycle carbon intensity and applies a premium rate to aviation fuel, which directly improves project returns. State-level low carbon fuel standards add a second revenue stream through tradable credits. The SAF Grand Challenge sets a national production target that anchors long-term planning. The constraint is the same everywhere: domestic waste lipid collection cannot supply the installed capacity, so feedstock is increasingly imported.
- Europe Turns Binding Aviation and Maritime Quotas Into the Deepest Compliance Market
Europe holds 33% share in 2026 and operates the most prescriptive policy framework in the study. Germany, France, the Netherlands, Spain, Sweden and Finland account for most regional supply and demand. What distinguishes the region is that obligations apply to specific sectors with escalating quantitative targets rather than relying on a general carbon price. ReFuelEU Aviation obliges suppliers at Union airports to blend rising shares of sustainable aviation fuel, FuelEU Maritime tightens the greenhouse gas intensity of energy used by ships, and Directive (EU) 2023/2413 sets transport targets with dedicated sub-targets for advanced fuels and renewable fuels of non-biological origin. Rotterdam and the Nordic countries concentrate production and bunkering activity. The barrier is feedstock import dependence, which has made certification integrity a political as well as a commercial issue.
- Which Region Is Growing Fastest in the Sustainable Alternative Fuels Market?
Asia Pacific is growing fastest at a 21.5% CAGR between 2026 and 2033, from the smallest base of the three major regions at 19% share in 2026. China, India, Japan, Singapore, South Korea and Australia drive the expansion. Several forces combine. The region supplies a very large share of the world’s used cooking oil, and governments are increasingly choosing to process that feedstock domestically rather than export it as raw material. Singapore is the world’s largest bunkering port and is building methanol supply capability to protect that position. Japan and India have introduced national aviation fuel blending targets, and refiners in both countries are converting units to hydroprocessing. Airlines based in the region face obligations when operating into Union airports. The barrier is cost, since credit support is weaker than elsewhere.
- Latin America Supplies Feedstock and Ethanol While Domestic Mandates Remain Narrow
Latin America accounts for 8% share in 2026, a position based more on feedstock and intermediate supply than on finished low-carbon fuel consumption. Brazil is the anchor, with the world’s deepest sugarcane ethanol industry, a long-established biodiesel blending programme and growing biomethane production from vinasse and agricultural waste. Argentina, Colombia and Chile add soy-based and waste-based capacity. The structural advantage is obvious: abundant biomass, low-cost ethanol suited to alcohol-to-jet conversion, and existing agro-industrial logistics. The barriers are equally clear. Domestic aviation and marine mandates are limited, project finance is expensive, and certification to internationally recognised sustainability schemes adds cost that only export-oriented producers can justify. The change worth watching is Brazilian legislation setting national aviation and diesel decarbonisation targets, which would create domestic demand alongside the export role.
- Middle East & Africa Leverages Refining Capacity and Low-Cost Renewable Electricity
Middle East & Africa holds 4% share in 2026, the smallest position but one with unusual structural assets. The United Arab Emirates, Saudi Arabia, Oman, Morocco and South Africa are the active markets. The region combines large existing refining and petrochemical capability with some of the lowest solar and wind electricity costs in the world, which is the single most important input for synthetic fuel production. Several Gulf states and Morocco have announced green hydrogen and derivative fuel ambitions aimed at export markets. The barriers are substantial: almost no domestic blending obligations, limited waste lipid collection infrastructure, scarce water for electrolysis in Gulf locations, and dependence on offtake contracts signed in jurisdictions with mandates. The opportunity is bunkering and export supply, given that major shipping lanes pass through the Suez and Hormuz corridors.
Competitive Landscape
The sustainable alternative fuels market is highly concentrated at the production end, far more so than conventional refining. A small number of operators control most hydroprocessing capacity, because conversion requires an existing refinery, access to hydrogen and secured waste lipid supply. Neste Oyj holds the largest dedicated renewable fuel capacity base globally and is the most visible aviation fuel supplier. Valero Energy Corporation participates through its renewable diesel joint venture, while TotalEnergies SE, Shell plc, Eni S.p.A., Repsol S.A., BP p.l.c., Chevron Corporation and Phillips 66 have each converted or built units. Concentration is lower in biomethane, where many small anaerobic digestion operators supply upgraded gas into grids.
Competition rests principally on feedstock access, not on conversion technology, because hydroprocessing is broadly comparable across operators. Secured long-term waste oil contracts, collection networks and the ability to certify chain of custody under ISCC or RSB determine who can run assets at high utilisation. Carbon intensity scoring is the second differentiator, since credit revenue and compliance value both scale with verified lifecycle emissions. Technology licensors and developers such as LanzaJet Inc., Gevo Inc., Velocys plc and Nordic Electrofuel AS compete differently, selling process routes and project development rather than molecules, while Darling Ingredients Inc. competes from the feedstock side.
Strategic activity concentrates on securing inputs and on positioning for the next pathway. Producers are integrating backward into rendering and used oil collection, co-processing renewable feedstock in existing refineries to add volume cheaply, and taking stakes in alcohol-to-jet and gasification developers.
Strategic direction across the sector is consistent: lock in feedstock, lower certified carbon intensity, and build optionality into pathways whose economics are not yet proven.
Recent Industry Developments
- August 2022: The United States enacted the Inflation Reduction Act, establishing the sustainable aviation fuel credit and the clean fuel production credit that pays according to lifecycle carbon intensity – creating the most significant production-side support mechanism in the sector.
- September 2023: Regulation (EU) 2023/1805, FuelEU Maritime, was published, setting a declining limit on the greenhouse gas intensity of energy used by ships calling at Union ports – opening marine methanol and ammonia as a distinct fuel demand pool.
- October 2023: Regulation (EU) 2023/2405, ReFuelEU Aviation, was published, obliging fuel suppliers at Union airports to blend escalating minimum shares of sustainable aviation fuel with a separate synthetic fuel sub-obligation – converting aviation demand into guaranteed offtake.
- November 2023: Directive (EU) 2023/2413, the recast renewable energy directive, entered into force with transport targets and dedicated sub-targets for advanced biofuels and renewable fuels of non-biological origin – steering investment toward residue-based and synthetic routes.
- January 2025: The first binding compliance obligations under ReFuelEU Aviation and FuelEU Maritime took effect – marking the point at which low-carbon fuel purchasing became a legal requirement rather than a voluntary commitment.
Companies Covered in the Report
- Neste Oyj
- TotalEnergies SE
- Valero Energy Corporation
- Shell plc
- BP p.l.c.
- Chevron Corporation
- Phillips 66
- Eni S.p.A.
- Repsol S.A.
- World Energy LLC
- Gevo Inc.
- LanzaJet Inc.
- Velocys plc
- Darling Ingredients Inc.
- Nordic Electrofuel AS
Sustainable Alternative Fuels Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 58.0 Billion |
| Market Size 2033 | US$ 165.0 Billion |
| CAGR 2026–2033 | 16.1% |
| Absolute Dollar Opportunity | US$ 107.0 Billion |
| Largest Market | North America (36% share in 2026) |
| Fastest-Growing Market | Asia Pacific (21.5% CAGR) |
| Market Concentration | High |
| Major Players | Neste Oyj, TotalEnergies SE, Valero Energy Corporation, Shell plc, World Energy LLC |
Sustainable Alternative Fuels Market Segmentation
Fuel Type
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
Production Pathway
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
Feedstock
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
End Use
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Sustainable Alternative Fuels Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Legally Binding Blending Quotas Convert Aviation and Shipping Demand Into Guaranteed Offtake
- Clean Fuel Production Credits Compress the Premium That Blocks Voluntary Purchasing
- Restraints
- Waste Lipid Scarcity Caps How Much Hydroprocessed Fuel the Industry Can Actually Produce
- The Cost Premium Over Fossil Fuel Keeps Uptake Tied to Obligation Rather Than Demand
- Market Opportunities
- Alcohol-to-Jet and Gasification Routes Open a Feedstock Pool Beyond Waste Lipids
- Marine Methanol and Ammonia Bunkering Creates a New Port-Side Fuel Supply Business
- Drivers
- Global Sustainable Alternative Fuels Market Outlook, 2020–2033
- Global Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- Global Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- Global Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- Global Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- Global Sustainable Alternative Fuels Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- North America Sustainable Alternative Fuels Market Outlook, 2020–2033
- North America Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- North America Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- North America Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- North America Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- North America Sustainable Alternative Fuels Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- United States Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- United States Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- United States Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Canada Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Canada Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Canada Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Canada Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- North America Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Europe Sustainable Alternative Fuels Market Outlook, 2020–2033
- Europe Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- Europe Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- Europe Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- Europe Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- Europe Sustainable Alternative Fuels Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Germany Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Germany Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Germany Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- France Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- France Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- France Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- France Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Netherlands Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Netherlands Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Netherlands Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Netherlands Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Spain Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Spain Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Spain Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Spain Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Sweden Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Sweden Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Sweden Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Sweden Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Finland Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Finland Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Finland Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Finland Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Nordic countries Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Nordic countries Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Nordic countries Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Nordic countries Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Europe Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Asia Pacific Sustainable Alternative Fuels Market Outlook, 2020–2033
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- China Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- China Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- China Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- India Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- India Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- India Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- India Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Japan Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Japan Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Japan Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Japan Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Singapore Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Singapore Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Singapore Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Singapore Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- South Korea Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- South Korea Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- South Korea Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- South Korea Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Australia Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Australia Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Australia Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Australia Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Asia Pacific Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Latin America Sustainable Alternative Fuels Market Outlook, 2020–2033
- Latin America Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- Latin America Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- Latin America Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- Latin America Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- Latin America Sustainable Alternative Fuels Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Brazil Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Brazil Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Brazil Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Argentina Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Argentina Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Argentina Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Argentina Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Colombia Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Colombia Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Colombia Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Colombia Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Chile Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Chile Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Chile Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Chile Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Latin America Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, 2020–2033
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by Production Pathway, Value (US$ Billion), 2020–2033
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by Feedstock, Value (US$ Billion), 2020–2033
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by End Use, Value (US$ Billion), 2020–2033
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- United Arab Emirates Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- United Arab Emirates Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- United Arab Emirates Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Saudi Arabia Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Saudi Arabia Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Saudi Arabia Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Saudi Arabia Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Oman Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Oman Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Oman Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Oman Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Morocco Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- Morocco Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- Morocco Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- Morocco Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- South Africa Sustainable Alternative Fuels Market Outlook, by Fuel Type, 2020–2033
- South Africa Sustainable Alternative Fuels Market Outlook, by Production Pathway, 2020–2033
- South Africa Sustainable Alternative Fuels Market Outlook, by Feedstock, 2020–2033
- South Africa Sustainable Alternative Fuels Market Outlook, by End Use, 2020–2033
- Middle East & Africa Sustainable Alternative Fuels Market Outlook, by Fuel Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Neste Oyj
- TotalEnergies SE
- Valero Energy Corporation
- Shell plc
- BP p.l.c.
- Chevron Corporation
- Phillips 66
- Eni S.p.A.
- Repsol S.A.
- World Energy LLC
- Gevo Inc.
- LanzaJet Inc.
- Velocys plc
- Darling Ingredients Inc.
- Nordic Electrofuel AS
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Fuel Type
- Sustainable Aviation Fuel
- Renewable Diesel
- Biomethane and Bio-LNG
- Renewable Methanol and Ammonia
- Renewable Fuels of Non-Biological Origin
Production Pathway
- Hydroprocessed Esters and Fatty Acids
- Alcohol-to-Jet
- Fischer-Tropsch Gasification
- Anaerobic Digestion and Upgrading
- Power-to-Liquid
Feedstock
- Waste Oils and Fats
- Agricultural and Forestry Residues
- Municipal and Industrial Waste
- Energy Crops
- Green Hydrogen and Captured Carbon Dioxide
End Use
- Aviation
- Road Transport
- Marine Shipping
- Rail and Off-Highway
- Industrial Heat and Power
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 58.0 billion in 2026, counting sustainable aviation fuel, renewable diesel, biomethane, renewable methanol, ammonia and synthetic fuels together.
The market is projected to reach US$ 165.0 billion by 2033, growing at a 16.1% CAGR and adding an absolute opportunity of US$ 107.0 billion.
Renewable diesel leads with 44% share in 2026, because it drops directly into existing diesel engines and distribution infrastructure without modification.
Sustainable aviation fuel grows fastest among fuels at a 24.8% CAGR, while Asia Pacific leads geographies at a 21.5% CAGR through 2033.
North America holds 36% share in 2026, supported by early refinery conversions, carbon-intensity-linked production credits and state low carbon fuel standards.
Related Reports
Intelligent Pumps Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global intelligent pumps market is valued at US$10.8 billion in 2026, reaching US$19.6 billion by 2033, growing at an 8.9% CAGR
Automated Mooring Systems Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global automated mooring systems market is valued at US$0.5 billion in 2026, reaching US$1.1 billion by 2033, growing at an 11.9% CAGR
Toroidal Transformers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global toroidal transformers market is valued at US$1.2 billion in 2026, reaching US$1.8 billion by 2033, growing at a 6.0% CAGR
Marine Lithium-ion Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global marine lithium-ion battery market is valued at US$1.1 billion in 2026, reaching US$3.6 billion by 2033, growing at an 18.5% CAGR
IoT in Energy Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global IoT in energy market is valued at US$30.0 billion in 2026, reaching US$68.0 billion by 2033, growing at a 12.4% CAGR
Zinc-ion Battery Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global zinc-ion battery market is valued at US$0.413 billion in 2026, reaching US$0.548 billion by 2033, growing at a 4.1% CAGR