


Veterinary Telehealth Market
Veterinary Telehealth Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Veterinary Telehealth Market Size and Trend Analysis
How Fast Is the Veterinary Telehealth Market Growing?
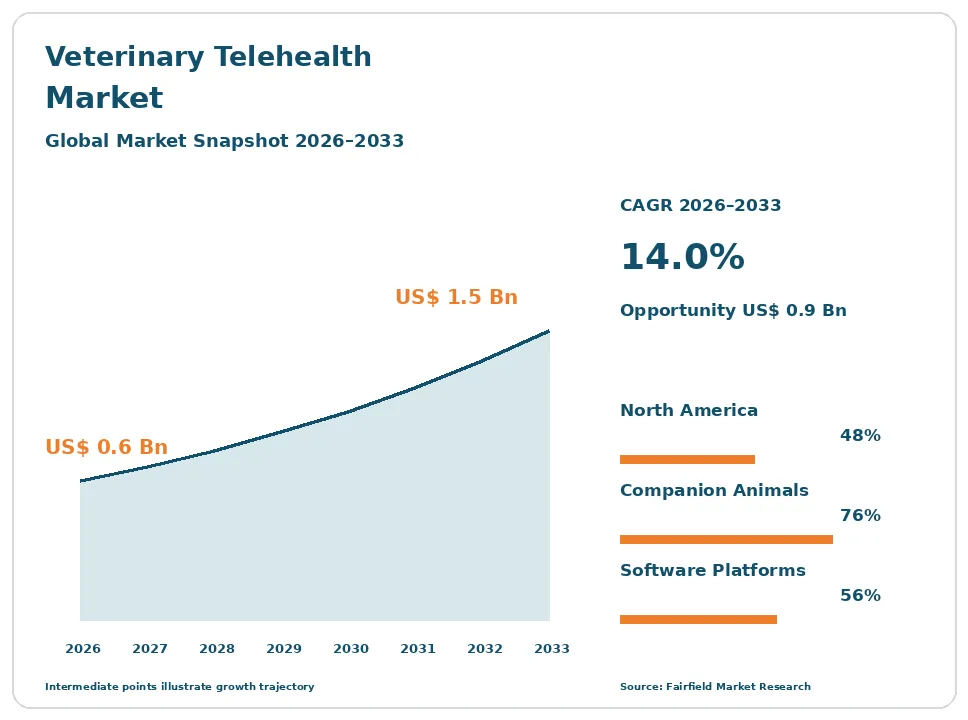
The global veterinary telehealth market size is expected to be valued at US$ 0.6 billion in 2026 and projected to reach US$ 1.5 billion by 2033, growing at a CAGR of 14.0% between 2026 and 2033.
Between 2020 and 2025 the category expanded at close to a 22.0% CAGR from a very small base created by pandemic-era service disruption. Growth since then is slower and more structural. Three factors carry it. Veterinary workforce shortages push practices to sort cases remotely before booking clinic time. Pet owners who already use human telehealth expect comparable access for animals. Consolidation of independent clinics into larger groups creates buyers able to fund platforms, records integration and payment tooling. The direction of travel is toward remote care embedded inside existing practices rather than standalone consumer applications. Absolute scale stays modest because prescribing authority, not technology, sets the ceiling on what a remote service may deliver.
Key Report Takeaways
- By Service Type: Teletriage and teleadvice held 34% share in 2026, while remote patient monitoring is projected to expand at an 18.2% CAGR through 2033, as connected collars and glucose sensors feed structured data into clinical records.
- By Animal Type: Companion animals held 76% share in 2026, while production animals are projected to expand at a 16.4% CAGR through 2033, driven by herd health contracts that price veterinary time against travel distance.
- By Delivery Model: Practice-owned services held 41% share in 2026, while insurer and retailer programmes are projected to expand at a 16.9% CAGR through 2033, because advice lines are cheap loyalty instruments for policy and subscription businesses.
- By Component: Software platforms held 56% share in 2026, while connected monitoring devices are projected to expand at a 17.5% CAGR through 2033, reflecting hardware attachment to chronic condition follow-up programmes.
- By Geography: North America held 48% share in 2026, while Asia Pacific is projected to expand at a 17.8% CAGR through 2033, supported by urban pet ownership growth and mobile-first service design in China, Japan and Australia.
Veterinary Telehealth Market Growth Drivers
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Veterinary workforce shortage and practice capacity limits | High | North America, Europe, Australia | Medium term (2–4 years) |
| Consolidation of practices into corporate veterinary groups | Medium | North America, United Kingdom | Long term (≥4 years) |
Two forces account for most of the forecast growth in remote veterinary care.
Veterinary Workforce Shortages Push Case Sorting Into Remote Veterinary Telehealth Channels
Staffing limits are the clearest commercial reason practices buy remote care tools. Clinics in North America, the United Kingdom and Australia report unfilled veterinarian and technician posts, and appointment backlogs follow. Remote triage lets a practice sort which cases need a physical examination and which can wait, which raises the value of each occupied consulting room. The purchase is framed as capacity management rather than as a new service line.
The mechanism is scheduling. A teletriage interaction takes less staff time than an in-clinic visit and can be handled by a registered veterinary nurse or technician under supervision where practice acts permit it. Platform vendors accordingly sell scheduling, records integration and payment capture together, because the saving only appears when remote contacts feed the same diary and client record as physical appointments.
Corporate Veterinary Group Consolidation Creates Buyers Able to Fund Veterinary Telehealth Platforms
Ownership consolidation changes who can afford this software. Independent single-site clinics rarely carry the capital or the technical staff to run a remote care channel. Veterinary groups operating dozens or hundreds of sites can amortise one platform across the estate, negotiate enterprise pricing and standardise clinical protocols. That shift has moved the buying decision from the practice owner to a procurement function with a multi-year horizon.
The causal chain runs through data. Groups already operate shared practice management systems, so adding a remote channel is an integration project rather than a new system purchase. Central ownership also makes out-of-hours cover economic, since one remote rota can serve many sites. Vendors respond by selling to group head offices and by building interfaces to the records systems those groups have standardised on.
Veterinary Telehealth Market Restraints
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Divergent rules on establishing the veterinarian-client-patient relationship remotely | High | Global, with sharp variation across United States states | Long term (≥4 years) |
| Out-of-pocket payment and low pet insurance penetration | Medium | Latin America, Asia Pacific, Middle East & Africa | Medium term (2–4 years) |
The binding constraints on this market are legal and economic rather than technical.
Veterinarian-Client-Patient Relationship Rules Cap Veterinary Telehealth at Advice in Most Jurisdictions
One regulatory concept sets the ceiling on this market. Whether a veterinarian may diagnose, prescribe or treat remotely depends on whether a veterinarian-client-patient relationship can be established without a physical examination. Jurisdictions answer differently. Some permit the relationship to be formed electronically, others require a prior in-person visit, and prescribing authority follows that line. That single rule decides whether a remote business is a full care provider or an advice and triage service.
The consequence is a split market with two very different revenue profiles. Where electronic establishment is permitted, a platform can complete an episode of care and bill for it. Where it is not, the same platform can only direct the client to a clinic. The US Food and Drug Administration applies the relationship test to extralabel drug use under the Animal Medicinal Drug Use Clarification Act, so federal drug rules reinforce the state-level divergence.
Out-of-Pocket Payment and Low Pet Insurance Penetration Limit Veterinary Telehealth Pricing
Payment structure caps what providers can charge. Most remote veterinary contacts are paid directly by the owner, because pet insurance penetration stays in the low single digits across much of Asia Pacific, Latin America and the Middle East & Africa, and well below human health coverage even in Sweden and the United Kingdom where it is highest. Price sensitivity follows, and advice-only services struggle to sustain a fee that covers veterinarian time.
The cost source is clinician minutes, not infrastructure. A qualified veterinarian on a video call is the dominant line item, and it does not fall with volume the way software cost does. Advice-only models predictably show weak unit economics unless they are subsidised by an insurer, a retailer or a practice that recovers the margin on a follow-up visit, diagnostics or dispensing.
Veterinary Telehealth Market Opportunities
Two revenue pools sit outside the crowded companion animal advice segment.
Production Animal Remote Monitoring Opens a Herd Health Contract Pool in Veterinary Telehealth
Production animal work is the least contested revenue pool in remote veterinary care. Dairy, swine and poultry operations already run sensor systems for activity, rumination, temperature and milk parameters, and the veterinary input is advisory and contractual rather than episodic. Selling a monitoring subscription with scheduled remote herd reviews converts irregular call-out income into recurring revenue, which is a materially better business than per-consultation companion animal advice.
Producers, integrators and cooperatives create this demand, because their purchase decision is operational rather than emotional. Equine practice shows a similar pattern, since travel time between yards dominates the cost of a visit and remote review of a case reduces unproductive mileage. Vendors able to combine device data, a veterinary record and a scheduled review cycle can capture budget that currently sits with farm management software suppliers.
Specialist Teleradiology and Telepathology Build a Veterinarian-to-Veterinarian Revenue Pool
Store-and-forward specialist work is a business-to-business pool with cleaner regulatory standing. A general practice sends radiographs, computed tomography studies or slides to a board-certified specialist for interpretation, and the referring veterinarian retains the client relationship and the prescribing decision. The veterinarian-client-patient relationship question does not arise in the same form, so the service can be sold in jurisdictions where direct-to-owner telemedicine is restricted.
Referral hospitals, diagnostic laboratories and specialist networks are positioned to capture this, and general practices create the demand because specialist recruitment is harder than specialist access. Chronic condition follow-up is a second adjacent pool, where scheduled remote reviews of an already examined animal sit inside an existing relationship. Both depend on image transfer, reporting turnaround and integration with laboratory results rather than on consumer application design.
Segment Analysis
By Service Type: Teletriage and Teleadvice Lead While Remote Patient Monitoring Accelerates
Teletriage and teleadvice held 34% of 2026 revenue because they are lawful almost everywhere. Neither requires a formed veterinarian-client-patient relationship, so consumer platforms, insurers and retailers can offer them without jurisdictional engineering. Teleconsultation and prescribing-enabled telemedicine together hold a smaller share concentrated in permissive jurisdictions. Remote patient monitoring is the fastest-growing service at an 18.2% CAGR to 2033, as wearable collars, implantable identification readers and continuous glucose sensors generate data a veterinarian can review asynchronously. Store-and-forward teleradiology and telepathology remain a steady specialist block sold between veterinarians rather than to owners. The business implication is that service mix determines regulatory exposure as much as it determines margin: an operator weighted toward advice carries little prescribing risk and little pricing power, while an operator weighted toward telemedicine carries both at once.
By Animal Type: Companion Animal Demand Dominates as Production Animal Work Grows Quickest
Companion animals accounted for 76% of 2026 revenue, a reflection of household numbers, owner willingness to pay directly and the consumer application channel built around dogs and cats. Equine practice contributes a small but high-value slice, since remote review reduces the travel that dominates equine visit cost. Production animals form the fastest-growing group at a 16.4% CAGR through 2033, because herd monitoring contracts attach veterinary oversight to sensor systems already installed for productivity reasons. Antimicrobial stewardship rules in the European Union also require veterinary involvement in livestock medicine decisions, which creates a documented reason for scheduled remote review. For vendors, the implication is that companion animal volume funds the platform while production animal contracts supply predictable recurring revenue.
By Delivery Model: Practice-Owned Services Hold Share While Insurer and Retailer Programmes Scale
Practice-owned remote services held 41% share in 2026 because an existing client relationship solves both the regulatory and the payment problem. The practice has already examined the animal, so prescribing authority is intact where local rules allow follow-up remotely. Standalone consumer platforms hold the next largest block and compete on availability rather than continuity. Insurer and retailer programmes are the fastest-growing model at a 16.9% CAGR to 2033, because Trupanion, Nationwide and online retailers such as Chewy treat advice access as a retention instrument rather than a profit centre. Specialist referral networks remain a distinct business-to-business channel. The implication is pricing pressure on independent advice-only applications, which must compete with services bundled at no incremental cost to the owner.
By Component: Software Platforms Carry Revenue While Connected Devices Expand Fastest
Software platforms represented 56% of 2026 spending, covering video consultation, scheduling, triage workflow, records integration and payment capture. Buyers treat these as extensions of practice systems, so interface quality with existing records software decides deals more often than consultation features. Professional and support services, including implementation and clinical protocol design, form the balance. Connected monitoring devices are the fastest-expanding component at a 17.5% CAGR through 2033, attached mainly to chronic condition follow-up and production animal programmes. Device margins differ sharply from software margins, which matters for vendor mix and for how investors read reported growth. In-clinic practice management software and in-person consultation services sit outside the boundary of this market, so a vendor’s counted revenue here is only the remote-care portion of what it sells to the practice.
Geography Analysis
Which Region Is Leading the Veterinary Telehealth Market?
North America leads the market with 48% share in 2026, driven by the United States and Canada. Three conditions align there: high household spending per animal, the largest concentration of corporate veterinary groups, and a workforce shortage severe enough to make capacity tools a board-level topic. State veterinary practice acts diverge sharply, and a growing group of states now permits the veterinarian-client-patient relationship to be established electronically, which has created genuine telemedicine businesses alongside advice services. California enacted legislation on telehealth establishment of that relationship with effect from 2024. Federal drug rules still apply the relationship test to extralabel use. The region’s main change is consolidation of fragmented applications into platforms sold to multi-site groups rather than to individual clinics.
Europe Anchors Remote Veterinary Care in Prescribing Rules and Data Protection Obligations
Europe holds 26% of 2026 revenue, with the United Kingdom, Germany, France, the Netherlands and Sweden as the principal contributors. The regulatory frame is tighter and more uniform than in North America. The Royal College of Veterinary Surgeons has kept a physical examination requirement before prescribing prescription-only veterinary medicines, and its review of remote prescribing remains the single most watched policy question for operators there. The European Union veterinary medicinal products regulation governs prescription and distance selling of veterinary medicines, which constrains how online services handle dispensing. Data protection rules apply to client records held by platforms, adding a compliance cost. High pet insurance penetration in Sweden supports bundled advice services, and insurer-linked models are more developed than elsewhere.
Which Region Is Growing Fastest in the Veterinary Telehealth Market?
Asia Pacific is growing fastest at a 17.8% CAGR between 2026 and 2033, from a small base. China, Japan, Australia and India drive it. Urban pet ownership has risen quickly, service design is mobile-first, and payment runs through consumer wallets rather than insurance, which suits low-ticket advice products. Australia and New Zealand have the most developed professional frameworks and the clearest rules on remote consultation, while regulation elsewhere is still forming. Production animal monitoring is a second engine, since large integrated poultry and swine operations already run sensor infrastructure. The constraint is specialist supply: board-certified veterinary specialists are scarce, which limits teleradiology and telepathology capacity and pushes operators toward cross-border interpretation arrangements.
Latin America Builds Remote Veterinary Services Around Urban Clinics and Livestock Operations
Latin America accounts for 5% of 2026 revenue, concentrated in Brazil, Mexico, Chile and Argentina. Demand splits between urban companion animal clinics in large cities and the region’s substantial cattle, poultry and swine sectors. Barriers are specific. Pet insurance is close to absent, so every companion animal contact is paid out of pocket at prices well below those in North America. Veterinary practice rules in several countries do not address remote care explicitly, which leaves operators uncertain about prescribing. Connectivity in rural production zones is uneven. The change worth watching is herd health monitoring tied to export-oriented livestock operations, where traceability and residue control requirements already demand documented veterinary oversight.
Middle East & Africa Remote Veterinary Demand Concentrates in Gulf Cities and Export Livestock
Middle East & Africa holds 4% of 2026 revenue, the smallest regional block. Activity concentrates in the United Arab Emirates, Saudi Arabia, Israel and South Africa. Gulf cities have high-spending companion animal and equine owners, and equine practice is commercially significant because travel between stables is costly. Barriers dominate the rest of the region: limited veterinarian density, payment capacity, and the absence of practice act provisions covering remote consultation. Cross-border licensing is unresolved, which complicates services delivered from outside the country. The clearest opportunity is export-oriented livestock, where importing countries require veterinary certification and health monitoring, giving producers a commercial reason to fund remote oversight of herd and flock health.
Competitive Landscape
The veterinary telehealth market is fragmented and concentration is low. No vendor holds a dominant global position, and the market divides into groups that rarely compete head-on: diagnostics companies selling specialist interpretation, practice software companies adding remote channels, consumer platforms selling direct to pet owners, and insurers and retailers bundling advice into other products. IDEXX Laboratories and Covetrus approach the market from established clinic relationships, while Vetster, Airvet and Dutch Pet built consumer-facing businesses first. Consolidation is gradual and mostly takes the form of larger animal health and retail businesses absorbing smaller remote-care applications rather than mergers among equals.
Competition turns on four things. The first is integration with practice management systems, because a remote contact that does not write into the clinical record creates work rather than saving it. The second is veterinarian supply and rota coverage, since availability at the moment of need is the product. The third is regulatory footprint, as operating in jurisdictions that permit electronic establishment of the veterinarian-client-patient relationship allows a richer service than advice alone. The fourth is distribution, where insurer and retailer partnerships deliver customers at a cost no standalone application can match.
Strategic direction is converging on embedded models. Vendors increasingly position remote care as a module inside a practice’s existing workflow rather than as a competing destination for the pet owner, which reduces channel conflict with the clinics that control prescribing. Specialist teleconsulting networks are expanding their coverage of imaging modalities and turnaround commitments. Device-linked monitoring is being added to create recurring revenue beyond the consultation fee. Across the group, vendor strategy is shaped less by technology differentiation than by the regulatory geography each operator can lawfully serve.
Veterinary Telehealth Industry Leaders
- IDEXX Laboratories
- Covetrus
- Chewy
- Vetster
- Airvet
Recent Industry Developments
- March 2020: The US Food and Drug Administration issued a temporary enforcement policy relaxing certain veterinarian-client-patient relationship requirements for extralabel drug use during the public health emergency; the policy was later withdrawn, restoring the examination-based test – this established remote care as a live federal policy question rather than a state-only matter.
- January 2022: The European Union regulation on veterinary medicinal products became applicable across member states, setting common rules on veterinary prescriptions and on distance selling of veterinary medicines – it defined the boundaries within which online veterinary services in Europe may operate.
- January 2023: The Royal College of Veterinary Surgeons Council approved revised guidance on animals under veterinary care, which took effect in September 2023 and retained the requirement for physical examination before prescribing prescription-only veterinary medicines – this kept the United Kingdom market weighted toward advice and triage rather than remote prescribing.
- October 2023: California enacted legislation permitting the veterinarian-client-patient relationship to be established by telehealth, with effect from January 2024 – the largest United States state to do so, widening the gap between permissive and examination-first jurisdictions.
Companies Covered in the Report
- IDEXX Laboratories
- Zoetis
- Covetrus
- Mars Veterinary Health
- Chewy
- Trupanion
- Nationwide
- Airvet
- Vetster
- Dutch Pet
- PetDesk
- FirstVet
- Joii Pet Care
Veterinary Telehealth Market Report Scope
This report covers remote veterinary care and its enabling technology: teletriage, teleadvice and teleconsultation, telemedicine where a veterinarian-client-patient relationship permits it, remote monitoring using wearables and connected devices, store-and-forward teleradiology, telepathology and specialist teleconsulting between veterinarians, and the platform, scheduling, records integration and payment software carrying them. In-clinic practice management software and in-person services are excluded. The base year is 2025 and the forecast period runs from 2026 to 2033 in US$ Billion.
Service Type
- Teletriage and Teleadvice
- Teleconsultation
- Telemedicine
- Remote Patient Monitoring
- Store-and-Forward Specialist Teleconsulting
Animal Type
- Companion Animals
- Equine
- Production Animals
Delivery Model
- Practice-Owned Services
- Standalone Consumer Platforms
- Insurer and Retailer Programmes
- Specialist Referral Networks
Component
- Software Platforms
- Connected Monitoring Devices
- Professional and Support Services
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the veterinary telehealth market in 2026?
The veterinary telehealth market is valued at US$ 0.6 billion in 2026, a small category relative to total veterinary services spending worldwide.
What is the veterinary telehealth market forecast to 2033?
The market is projected to reach US$ 1.5 billion by 2033, growing at a 14.0% CAGR and adding US$ 0.9 billion of absolute opportunity.
Which service type leads the veterinary telehealth market?
Teletriage and teleadvice lead with 34% share in 2026, because they can be offered without a formed veterinarian-client-patient relationship in most jurisdictions.
Which geography is growing fastest in veterinary telehealth?
Asia Pacific is the fastest-growing geography at a 17.8% CAGR through 2033, supported by urban pet ownership growth and mobile-first service design.
How concentrated is the veterinary telehealth competitive structure?
Concentration is low and the market is fragmented, with diagnostics firms, practice software vendors, consumer platforms, insurers and retailers competing from different starting positions.
1. Executive Summary
1.1. Global Veterinary Telehealth Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Veterinary Workforce Shortages Push Case Sorting Into Remote Veterinary Telehealth Channels
2.3.1.2. Corporate Veterinary Group Consolidation Creates Buyers Able to Fund Veterinary Telehealth Platforms
2.3.2. Restraints
2.3.2.1. Veterinarian-Client-Patient Relationship Rules Cap Veterinary Telehealth at Advice in Most Jurisdictions
2.3.2.2. Out-of-Pocket Payment and Low Pet Insurance Penetration Limit Veterinary Telehealth Pricing
2.3.3. Market Opportunities
2.3.3.1. Production Animal Remote Monitoring Opens a Herd Health Contract Pool in Veterinary Telehealth
2.3.3.2. Specialist Teleradiology and Telepathology Build a Veterinarian-to-Veterinarian Revenue Pool
3. Global Veterinary Telehealth Market Outlook, 2020–2033
3.1. Global Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
3.1.1. Teletriage and Teleadvice
3.1.2. Teleconsultation
3.1.3. Telemedicine
3.1.4. Remote Patient Monitoring
3.1.5. Store-and-Forward Specialist Teleconsulting
3.2. Global Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
3.2.1. Companion Animals
3.2.2. Equine
3.2.3. Production Animals
3.3. Global Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
3.3.1. Practice-Owned Services
3.3.2. Standalone Consumer Platforms
3.3.3. Insurer and Retailer Programmes
3.3.4. Specialist Referral Networks
3.4. Global Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
3.4.1. Software Platforms
3.4.2. Connected Monitoring Devices
3.4.3. Professional and Support Services
3.5. Global Veterinary Telehealth Market Outlook, by Region, Value (US$ Billion), 2020–2033
3.5.1. North America
3.5.2. Europe
3.5.3. Asia Pacific
3.5.4. Latin America
3.5.5. Middle East & Africa
4. North America Veterinary Telehealth Market Outlook, 2020–2033
4.1. North America Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
4.1.1. Teletriage and Teleadvice
4.1.2. Teleconsultation
4.1.3. Telemedicine
4.1.4. Remote Patient Monitoring
4.1.5. Store-and-Forward Specialist Teleconsulting
4.2. North America Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
4.2.1. Companion Animals
4.2.2. Equine
4.2.3. Production Animals
4.3. North America Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
4.3.1. Practice-Owned Services
4.3.2. Standalone Consumer Platforms
4.3.3. Insurer and Retailer Programmes
4.3.4. Specialist Referral Networks
4.4. North America Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
4.4.1. Software Platforms
4.4.2. Connected Monitoring Devices
4.4.3. Professional and Support Services
4.5. North America Veterinary Telehealth Market Outlook, by Country, Value (US$ Billion), 2020–2033
4.5.1. United States Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
4.5.2. United States Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
4.5.3. United States Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
4.5.4. United States Veterinary Telehealth Market Outlook, by Component, 2020–2033
4.5.5. Canada Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
4.5.6. Canada Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
4.5.7. Canada Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
4.5.8. Canada Veterinary Telehealth Market Outlook, by Component, 2020–2033
5. Europe Veterinary Telehealth Market Outlook, 2020–2033
5.1. Europe Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
5.1.1. Teletriage and Teleadvice
5.1.2. Teleconsultation
5.1.3. Telemedicine
5.1.4. Remote Patient Monitoring
5.1.5. Store-and-Forward Specialist Teleconsulting
5.2. Europe Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
5.2.1. Companion Animals
5.2.2. Equine
5.2.3. Production Animals
5.3. Europe Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
5.3.1. Practice-Owned Services
5.3.2. Standalone Consumer Platforms
5.3.3. Insurer and Retailer Programmes
5.3.4. Specialist Referral Networks
5.4. Europe Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
5.4.1. Software Platforms
5.4.2. Connected Monitoring Devices
5.4.3. Professional and Support Services
5.5. Europe Veterinary Telehealth Market Outlook, by Country, Value (US$ Billion), 2020–2033
5.5.1. United Kingdom Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
5.5.2. United Kingdom Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
5.5.3. United Kingdom Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
5.5.4. United Kingdom Veterinary Telehealth Market Outlook, by Component, 2020–2033
5.5.5. Germany Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
5.5.6. Germany Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
5.5.7. Germany Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
5.5.8. Germany Veterinary Telehealth Market Outlook, by Component, 2020–2033
5.5.9. France Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
5.5.10. France Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
5.5.11. France Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
5.5.12. France Veterinary Telehealth Market Outlook, by Component, 2020–2033
5.5.13. Netherlands Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
5.5.14. Netherlands Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
5.5.15. Netherlands Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
5.5.16. Netherlands Veterinary Telehealth Market Outlook, by Component, 2020–2033
5.5.17. Sweden Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
5.5.18. Sweden Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
5.5.19. Sweden Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
5.5.20. Sweden Veterinary Telehealth Market Outlook, by Component, 2020–2033
6. Asia Pacific Veterinary Telehealth Market Outlook, 2020–2033
6.1. Asia Pacific Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
6.1.1. Teletriage and Teleadvice
6.1.2. Teleconsultation
6.1.3. Telemedicine
6.1.4. Remote Patient Monitoring
6.1.5. Store-and-Forward Specialist Teleconsulting
6.2. Asia Pacific Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
6.2.1. Companion Animals
6.2.2. Equine
6.2.3. Production Animals
6.3. Asia Pacific Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
6.3.1. Practice-Owned Services
6.3.2. Standalone Consumer Platforms
6.3.3. Insurer and Retailer Programmes
6.3.4. Specialist Referral Networks
6.4. Asia Pacific Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
6.4.1. Software Platforms
6.4.2. Connected Monitoring Devices
6.4.3. Professional and Support Services
6.5. Asia Pacific Veterinary Telehealth Market Outlook, by Country, Value (US$ Billion), 2020–2033
6.5.1. China Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
6.5.2. China Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
6.5.3. China Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
6.5.4. China Veterinary Telehealth Market Outlook, by Component, 2020–2033
6.5.5. Japan Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
6.5.6. Japan Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
6.5.7. Japan Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
6.5.8. Japan Veterinary Telehealth Market Outlook, by Component, 2020–2033
6.5.9. Australia Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
6.5.10. Australia Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
6.5.11. Australia Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
6.5.12. Australia Veterinary Telehealth Market Outlook, by Component, 2020–2033
6.5.13. India Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
6.5.14. India Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
6.5.15. India Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
6.5.16. India Veterinary Telehealth Market Outlook, by Component, 2020–2033
6.5.17. New Zealand Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
6.5.18. New Zealand Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
6.5.19. New Zealand Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
6.5.20. New Zealand Veterinary Telehealth Market Outlook, by Component, 2020–2033
7. Latin America Veterinary Telehealth Market Outlook, 2020–2033
7.1. Latin America Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
7.1.1. Teletriage and Teleadvice
7.1.2. Teleconsultation
7.1.3. Telemedicine
7.1.4. Remote Patient Monitoring
7.1.5. Store-and-Forward Specialist Teleconsulting
7.2. Latin America Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
7.2.1. Companion Animals
7.2.2. Equine
7.2.3. Production Animals
7.3. Latin America Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
7.3.1. Practice-Owned Services
7.3.2. Standalone Consumer Platforms
7.3.3. Insurer and Retailer Programmes
7.3.4. Specialist Referral Networks
7.4. Latin America Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
7.4.1. Software Platforms
7.4.2. Connected Monitoring Devices
7.4.3. Professional and Support Services
7.5. Latin America Veterinary Telehealth Market Outlook, by Country, Value (US$ Billion), 2020–2033
7.5.1. Brazil Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
7.5.2. Brazil Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
7.5.3. Brazil Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
7.5.4. Brazil Veterinary Telehealth Market Outlook, by Component, 2020–2033
7.5.5. Mexico Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
7.5.6. Mexico Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
7.5.7. Mexico Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
7.5.8. Mexico Veterinary Telehealth Market Outlook, by Component, 2020–2033
7.5.9. Chile Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
7.5.10. Chile Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
7.5.11. Chile Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
7.5.12. Chile Veterinary Telehealth Market Outlook, by Component, 2020–2033
7.5.13. Argentina Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
7.5.14. Argentina Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
7.5.15. Argentina Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
7.5.16. Argentina Veterinary Telehealth Market Outlook, by Component, 2020–2033
8. Middle East & Africa Veterinary Telehealth Market Outlook, 2020–2033
8.1. Middle East & Africa Veterinary Telehealth Market Outlook, by Service Type, Value (US$ Billion), 2020–2033
8.1.1. Teletriage and Teleadvice
8.1.2. Teleconsultation
8.1.3. Telemedicine
8.1.4. Remote Patient Monitoring
8.1.5. Store-and-Forward Specialist Teleconsulting
8.2. Middle East & Africa Veterinary Telehealth Market Outlook, by Animal Type, Value (US$ Billion), 2020–2033
8.2.1. Companion Animals
8.2.2. Equine
8.2.3. Production Animals
8.3. Middle East & Africa Veterinary Telehealth Market Outlook, by Delivery Model, Value (US$ Billion), 2020–2033
8.3.1. Practice-Owned Services
8.3.2. Standalone Consumer Platforms
8.3.3. Insurer and Retailer Programmes
8.3.4. Specialist Referral Networks
8.4. Middle East & Africa Veterinary Telehealth Market Outlook, by Component, Value (US$ Billion), 2020–2033
8.4.1. Software Platforms
8.4.2. Connected Monitoring Devices
8.4.3. Professional and Support Services
8.5. Middle East & Africa Veterinary Telehealth Market Outlook, by Country, Value (US$ Billion), 2020–2033
8.5.1. United Arab Emirates Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
8.5.2. United Arab Emirates Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
8.5.3. United Arab Emirates Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
8.5.4. United Arab Emirates Veterinary Telehealth Market Outlook, by Component, 2020–2033
8.5.5. Saudi Arabia Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
8.5.6. Saudi Arabia Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
8.5.7. Saudi Arabia Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
8.5.8. Saudi Arabia Veterinary Telehealth Market Outlook, by Component, 2020–2033
8.5.9. Israel Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
8.5.10. Israel Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
8.5.11. Israel Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
8.5.12. Israel Veterinary Telehealth Market Outlook, by Component, 2020–2033
8.5.13. South Africa Veterinary Telehealth Market Outlook, by Service Type, 2020–2033
8.5.14. South Africa Veterinary Telehealth Market Outlook, by Animal Type, 2020–2033
8.5.15. South Africa Veterinary Telehealth Market Outlook, by Delivery Model, 2020–2033
8.5.16. South Africa Veterinary Telehealth Market Outlook, by Component, 2020–2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. IDEXX Laboratories
9.5.2. Zoetis
9.5.3. Covetrus
9.5.4. Mars Veterinary Health
9.5.5. Chewy
9.5.6. Trupanion
9.5.7. Nationwide
9.5.8. Airvet
9.5.9. Vetster
9.5.10. Dutch Pet
9.5.11. PetDesk
9.5.12. FirstVet
9.5.13. Joii Pet Care
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Service Type | Teletriage and Teleadvice, Teleconsultation, Telemedicine, Remote Patient Monitoring, Store-and-Forward Specialist Teleconsulting |
| Animal Type | Companion Animals, Equine, Production Animals |
| Delivery Model | Practice-Owned Services, Standalone Consumer Platforms, Insurer and Retailer Programmes, Specialist Referral Networks |
| Component | Software Platforms, Connected Monitoring Devices, Professional and Support Services |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The veterinary telehealth market is valued at US$ 0.6 billion in 2026, a small category relative to total veterinary services spending worldwide.
The market is projected to reach US$ 1.5 billion by 2033, growing at a 14.0% CAGR and adding US$ 0.9 billion of absolute opportunity.
Teletriage and teleadvice lead with 34% share in 2026, because they can be offered without a formed veterinarian-client-patient relationship in most jurisdictions.
Asia Pacific is the fastest-growing geography at a 17.8% CAGR through 2033, supported by urban pet ownership growth and mobile-first service design.
Concentration is low and the market is fragmented, with diagnostics firms, practice software vendors, consumer platforms, insurers and retailers competing from different starting positions.
Related Reports
Chemical Peel Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The chemical peel market is projected to grow from US$2.4 billion in 2026 to US$4.3 billion by 2033, at an 8.7% CAGR. Explore segments and regional trends.
Smart Home Health Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The smart home health market is projected to grow from US$5.80 billion in 2026 to US$9.90 billion by 2033, at a 7.9% CAGR, driven by aging and home monitoring.
Population Health Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The population health management market is projected to grow from US$46.93 billion in 2026 to US$132.63 billion by 2033, at a 16.0% CAGR, led by value-based care.
Medical Second Opinion Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The medical second opinion market is projected to grow from US$9.69 billion in 2026 to US$28.55 billion by 2033, at a 16.7% CAGR, led by virtual care.
Patient Blood Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the patient blood management market, reaching US$ 25.61 billion by 2033 at 6.4% CAGR, with product and regional insights.
Medical Fraud Detection Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore medical fraud detection management, reaching US$ 11.47 billion by 2033 at 17.4% CAGR, with deployment and regional insights.