


Medical Second Opinion Market
Medical Second Opinion Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Medical Second Opinion Market Size and Trend Analysis
How Fast Is the Medical Second Opinion Market Growing?
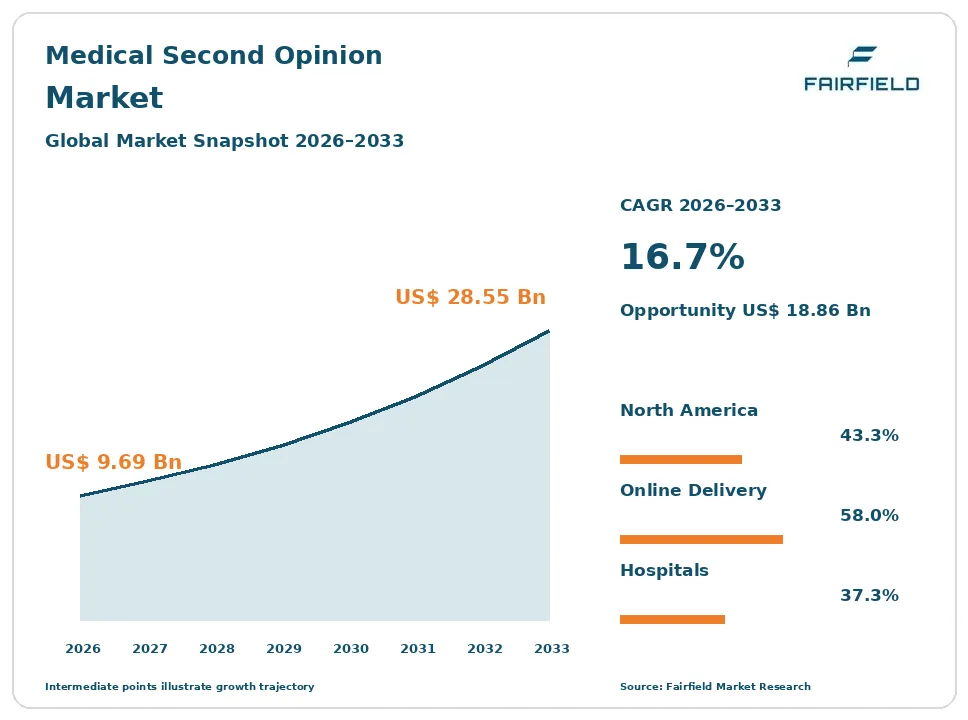
The global medical second opinion market size is expected to be valued at US$ 9.69 billion in 2026 and projected to reach US$ 28.55 billion by 2033, growing at a CAGR of 16.7% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 14.5%, as telemedicine made it easy for patients to have their records reviewed by top specialists without traveling. A medical second opinion is a review of a diagnosis or treatment plan by another doctor, often an expert at a leading hospital. Three factors now drive growth: the rising number of complex conditions such as cancer, heart disease, and neurological disorders, concern about misdiagnosis and unnecessary surgery, and employers and insurers offering expert medical opinion services as a benefit. The market is shifting toward virtual second opinion platforms, AI diagnostics that support radiology and pathology reviews, and cross-border services connecting patients with specialists abroad. In 2026, Cedars-Sinai expanded its virtual program to 39 states, showing strong demand.
Key Report Takeaways
- By Condition: Cancer held 27.4% share in 2026, while Neurological Disorders are projected to expand at an 18.9% CAGR through 2033, driven by complex diagnoses such as dementia, epilepsy, and multiple sclerosis.
- By Service Provider: Hospitals held 37.3% share in 2026, while Online Second Opinion Platforms are projected to expand at a 19.5% CAGR through 2033, driven by employer benefits and direct-to-patient services.
- By Delivery Mode: Online held 58.0% share in 2026 and is projected to expand at an 18.4% CAGR through 2033, outpacing In-Person as video and digital record sharing spread.
- By Region: North America held 43.3% share in 2026, while Asia Pacific is projected to expand at a 19.6% CAGR through 2033, driven by rising cancer cases and telemedicine in India and China.
Global Medical Second Opinion Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising complex diseases and misdiagnosis concerns | High | Global | Long term (≥4 years) |
| Employer and insurer adoption of second opinion benefits | High | North America, Europe | Medium term (2-4 years) |
Two drivers carry the strongest influence on medical second opinion demand during the forecast period.
Complex Diseases Are Driving the Medical Second Opinion Market
The rising number of complex diseases and concern about misdiagnosis are the strongest driver of the medical second opinion market. Patients want certainty before major treatment.
The mechanism is the high stakes of serious diagnoses. Cancer, heart disease, rare diseases, and neurological conditions often involve difficult choices about surgery, chemotherapy, or long-term drugs. Studies show that second opinions often change the diagnosis or treatment plan, and Cleveland Clinic reports that many reviews lead to modified treatment. Global cancer cases continue to rise with aging populations. Patients with access to online information and patient communities are more likely to question their first diagnosis. Cancer diagnosis reviews by expert pathologists and radiologists can catch errors that affect survival. Doctors themselves increasingly refer difficult cases to tumor boards and outside experts. These factors push patients and doctors to seek expert reviews.
Employer Benefits Are Expanding the Medical Second Opinion Market
Employer and insurer adoption of second opinion benefits is expanding the medical second opinion market. Large employers want to reduce costly and unnecessary care.
The cause is rising healthcare costs. In the United States, employers pay for most workers’ health insurance, and surgeries and cancer treatments are among their largest costs. Expert medical opinion services can prevent unnecessary procedures and steer patients to better treatments, saving money. Companies such as Included Health, Teladoc Health, and 2nd.MD, now part of Transcarent after its 2025 merger with Accolade, sell second opinion programs to employers and health plans. Insurers in Europe and Asia Pacific also add these services to policies. Some employers require or reward second opinions before major surgery, such as spine or joint operations. These trends grow the number of covered patients.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Limited insurance coverage and out-of-pocket costs | High | Global | Medium term (2-4 years) |
| Licensing rules and data-sharing barriers | Medium | North America, Europe | Long term (≥4 years) |
Two restraints limit how quickly the medical second opinion market grows.
Cost and Coverage Gaps Slow the Medical Second Opinion Market
Limited insurance coverage and out-of-pocket costs slow the medical second opinion market. Many patients must pay for second opinions themselves.
The specific causes are payer policies and price. Many health plans do not cover virtual second opinions from out-of-network hospitals, and fees can range from several hundred to several thousand dollars. Cedars-Sinai notes that insurance does not cover its virtual service, although health savings accounts may reimburse it. In developing countries, few people have insurance that pays for specialist reviews. Some patients do not know that second opinions are available or worry about upsetting their own doctor or delaying treatment. Collecting records, scans, and tissue samples from several providers also takes time. These factors limit demand among lower-income and older patients.
Licensing and Data Barriers Restrict the Medical Second Opinion Market
Licensing rules and data-sharing barriers restrict the medical second opinion market. Doctors cannot always advise patients across state or national borders.
The underlying causes are medical regulations and fragmented records. In the United States, doctors usually need a license in the patient’s state, which is why programs list the states they serve. Cross-border opinions face even stricter rules. Transferring imaging files, pathology slides, and health records between hospitals can be slow and costly, and systems do not always work together. Privacy laws limit data sharing. Some specialists have long waiting lists. Malpractice concerns also make some specialists cautious about advising patients they have not examined in person. Differences in treatment guidelines between countries can confuse patients. These factors slow service growth and raise costs.
Market Opportunities
AI-Assisted Reviews Open a Productivity Revenue Pool
AI diagnostics open a productivity revenue pool in the medical second opinion market. AI tools can help specialists review cases faster and more accurately.
Providers and technology firms that combine AI with expert review can capture this opportunity. AI can flag possible errors in radiology scans and pathology slides, summarize long medical records, and suggest guideline-based treatment options. Digital pathology lets experts review tissue samples remotely. Imaging startups offer AI-supported radiology second opinions at lower prices. Faster reviews let providers handle more cases with the same number of specialists. Hospitals can extend their reach to smaller community hospitals through digital consult services, as the Ohio State University Comprehensive Cancer Center has done with digital pathology consults. Regulators are clearing more AI tools for medical imaging each year. Lower costs could make second opinions affordable for more patients.
Cross-Border Expert Access Creates an International Revenue Pool
Cross-border expert access creates an international revenue pool in the medical second opinion market. Patients worldwide seek opinions from leading hospitals.
Leading hospitals and international platforms can capture this opportunity. Patients in Middle East & Africa, Asia Pacific, and Latin America often seek advice from centers in the United States, Germany, the United Kingdom, and India. Virtual reviews remove travel costs and delays. Hospitals such as Mayo Clinic, Cleveland Clinic, and Apollo Hospitals run international patient programs. Governments and insurers in Saudi Arabia and the United Arab Emirates pay for overseas expert opinions. Translation and record services add value. Medical tourism agencies and insurers act as referral partners. Hospitals that offer fast reviews, clear pricing, and follow-up treatment options win more international patients.
Segment Analysis
By Condition: Cancer Leads While Neurological Disorders Grow Fastest
Cancer held 27.4% share in 2026. Cancer cases are rising worldwide, and treatment choices are complex and high-stakes. Second opinions on cancer diagnosis, tumor type, genetic test results, and treatment plans can change outcomes. Major cancer centers such as MD Anderson Cancer Center, Memorial Sloan Kettering, and Mayo Clinic provide many reviews, often including pathology slide checks.
Neurological Disorders are the fastest-growing condition, expanding at an 18.9% CAGR through 2033. Conditions such as dementia, Parkinson’s disease, epilepsy, and multiple sclerosis are hard to diagnose and treat. New Alzheimer’s drugs require careful patient selection, raising demand for expert reviews. Cardiovascular, orthopedic, and rare diseases are other key areas. For the market, neurology growth adds complex cases.
By Service Provider: Hospitals Lead While Online Second Opinion Platforms Grow Fastest
Hospitals held 37.3% share in 2026. Academic medical centers and large hospital systems, such as Cleveland Clinic, Johns Hopkins Medicine, Cedars-Sinai, and Apollo Hospitals, offer second opinion services in person and online. Their reputations attract patients.
Online Second Opinion Platforms are the fastest-growing provider type, expanding at a 19.5% CAGR through 2033. Platforms such as 2nd.MD, Included Health, and WorldCare connect patients with large networks of specialists at top hospitals, often through employer benefits. Specialty clinics and physician groups also provide reviews for orthopedic, heart, and eye conditions. Platforms often include care navigation, helping patients choose doctors and hospitals after the review. Many charge employers a fixed fee per member. For the market, platform growth widens access.
By Delivery Mode: Online Leads and Grows Fastest
Online held 58.0% share in 2026 and is projected to expand at an 18.4% CAGR through 2033. Virtual second opinion services let patients upload records and talk with specialists by video, saving travel time and costs. Most reports are delivered within days, and patients can join video calls to discuss results. Digital pathology and cloud imaging allow experts to review slides and scans from anywhere. Patient portals make it easy to share records.
In-Person holds the remaining share. Some cases need physical exams or new tests, and some patients prefer face-to-face visits with specialists. Hospitals often use in-person visits when second opinions lead to treatment at their own facilities. For the market, online growth expands reach to rural and international patients.
Geography Analysis
Which Region Is Leading the Medical Second Opinion Market?
North America is leading the medical second opinion market with a 43.3% share in 2026. The United States has many leading hospitals, such as Mayo Clinic, Cleveland Clinic, Johns Hopkins Medicine, and Cedars-Sinai, and a large employer benefits market served by Transcarent, Included Health, and Teladoc Health. High healthcare costs make second opinions valuable. Canada also has growing demand because of long specialist wait times. Interstate licensing compacts are making it easier for doctors to serve patients in more states. Key barriers include state licensing rules and limited insurance coverage. One change shaping the region is virtual program expansion.
Europe Builds the Medical Second Opinion Market Through Patient Rights
Europe is a major medical second opinion market. Germany gives patients a legal right to second opinions for certain planned surgeries, and Charité and other university hospitals offer international services. The United Kingdom, France, Spain, and Switzerland have strong demand. Private insurers include second opinions in many health and critical illness policies. Public health systems in the Netherlands and Denmark also support patients seeking second opinions within the country. The EU cross-border healthcare directive allows patients to seek some care in other member states. Key barriers include language differences and different rules. One opportunity is cross-border care.
Which Region Is Growing Fastest in the Medical Second Opinion Market?
Asia Pacific is growing fastest in the medical second opinion market at a 19.6% CAGR through 2033. India has large hospital groups, including Apollo Hospitals, Fortis Healthcare, and Medanta, that offer online second opinions to domestic and international patients. China and Japan face rising cancer cases. South Korea and Singapore attract medical tourists from across the region. Many patients from Bangladesh, Nepal, and Sri Lanka seek opinions from Indian hospitals. Growing private insurance in China and India adds demand. Key barriers include cost and limited specialist time. One change shaping the region is telemedicine growth.
Latin America Develops the Medical Second Opinion Market Through Private Health Plans
Latin America is a developing medical second opinion market. Brazil and Mexico have growing private health plans that add second opinion benefits, and patients seek reviews from hospitals in the United States. Argentina, Chile, and Colombia have strong private hospitals that partner with foreign centers. Cancer centers in Brazil, such as Hospital Israelita Albert Einstein, run online consult services. Rising cancer and heart disease rates across the region add demand. Telehealth rules in Brazil now allow remote consultations. Key barriers include cost and limited insurance coverage. One opportunity is employer programs offered through multinational companies.
Middle East & Africa Expands the Medical Second Opinion Market Through International Referrals
Middle East & Africa is a growing medical second opinion market. Saudi Arabia, the United Arab Emirates, Qatar, and Kuwait fund overseas care and expert opinions for citizens. Israel has advanced hospitals. South Africa, Nigeria, and Egypt have limited specialists. Many patients travel to Germany, the United Kingdom, India, and the United States for advanced treatment, and virtual opinions can help them choose. Hospitals in the United Arab Emirates partner with Cleveland Clinic and Mayo Clinic. Key barriers include cost and limited digital records. One opportunity is virtual referrals funded by governments.
Competitive Landscape
The medical second opinion market is fragmented. Leading academic hospitals such as Cleveland Clinic, Mayo Clinic, Johns Hopkins Medicine, Cedars-Sinai, Apollo Hospitals, and Charité compete with platforms such as Transcarent with 2nd.MD, Included Health, Teladoc Health, and WorldCare.
Companies compete mainly on specialist reputation, turnaround time, price, ease of use, patient support, and employer and insurer contracts. Well-known hospital brands attract patients seeking top experts and advanced treatment options, while platforms win employer contracts by offering wide specialist networks, fast turnaround, and care navigation. Technology, including AI and digital pathology, is becoming important. Partnerships between hospitals and digital platforms are very common, letting platforms offer famous names and letting hospitals reach new patients. Price competition is growing as smaller providers and imaging startups offer low-cost online reviews. Clear outcome data, such as how often reviews change treatment, helps providers win employer contracts.
Strategic moves show how competition is changing. In January 2025, Transcarent agreed to acquire Accolade for US$ 621 million. In April 2025, the deal closed, bringing 2nd.MD into Transcarent. In March 2026, Cedars-Sinai expanded its virtual program to 39 states. These moves show competition shifting toward scale, virtual reach, and direct-to-patient services.
Three themes shape vendor strategy. First, companies are consolidating to win large employer contracts. Second, they are expanding virtual services to more states and countries. Third, they are adding AI to speed up reviews and lower costs.
Medical Second Opinion Market Industry Leaders
- Cleveland Clinic
- Mayo Clinic
- Transcarent
- Included Health
- Teladoc Health
Recent Industry Developments
- March 2026: Cedars-Sinai expanded its Virtual Second Opinion program to residents of 39 states, covering more than 600 conditions - widens access to virtual second opinion services.
- April 2025: Transcarent completed its merger with Accolade, including the 2nd.MD second opinion business - creates a larger employer-focused provider.
- January 2025: Transcarent agreed to acquire Accolade for US$ 621 million, combining care navigation, virtual care, and second opinions - consolidates expert medical opinion services for employers.
Companies Covered in the Report
- Cleveland Clinic
- Mayo Clinic
- Johns Hopkins Medicine
- Cedars-Sinai
- Transcarent
- Included Health
- Teladoc Health
- WorldCare
- Apollo Hospitals
- Fortis Healthcare
- Medanta
- Charité
Medical Second Opinion Market Report Scope
This report covers medical second opinion services for cancer, cardiovascular, neurological, orthopedic, and other conditions, delivered online and in person by hospitals, online platforms, and specialty clinics, and paid by patients, employers, and insurers. It includes expert reviews of diagnoses, imaging, pathology, and treatment plans. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Condition
- Cancer
- Cardiovascular Diseases
- Neurological Disorders
- Orthopedic Conditions
- Others
Service Provider
- Hospitals
- Online Second Opinion Platforms
- Specialty Clinics
Delivery Mode
- Online
- In-Person
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the medical second opinion market in 2026?
The medical second opinion market is valued at US$ 9.69 billion in 2026, led by cancer reviews and North America.
What is the medical second opinion market forecast to 2033?
The market is projected to reach US$ 28.55 billion by 2033, growing at a 16.7% CAGR and adding US$ 18.86 billion.
Which condition is growing fastest in the medical second opinion market?
Neurological disorders are growing fastest at an 18.9% CAGR through 2033, driven by complex dementia, epilepsy, and multiple sclerosis cases.
Which region is growing fastest in the medical second opinion market?
Asia Pacific is growing fastest at a 19.6% CAGR through 2033, driven by rising cancer cases and telemedicine in India and China.
Which region holds the largest medical second opinion market share?
North America holds the largest share at 43.3% in 2026, supported by leading hospitals and employer-paid second opinion programs.
1. Executive Summary
1.1. Global Medical Second Opinion Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. Complex Diseases Are Driving the Medical Second Opinion Market
2.3.1.2. Employer Benefits Are Expanding the Medical Second Opinion Market
2.3.2. Restraints
2.3.2.1. Cost and Coverage Gaps Slow the Medical Second Opinion Market
2.3.2.2. Licensing and Data Barriers Restrict the Medical Second Opinion Market
2.3.3. Market Opportunities
2.3.3.1. AI-Assisted Reviews Open a Productivity Revenue Pool
2.3.3.2. Cross-Border Expert Access Creates an International Revenue Pool
3. Global Medical Second Opinion Market Outlook, 2020-2033
3.1. Global Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
3.1.1. Cancer
3.1.2. Cardiovascular Diseases
3.1.3. Neurological Disorders
3.1.4. Orthopedic Conditions
3.1.5. Others
3.2. Global Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
3.2.1. Hospitals
3.2.2. Online Second Opinion Platforms
3.2.3. Specialty Clinics
3.3. Global Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
3.3.1. Online
3.3.2. In-Person
3.4. Global Medical Second Opinion Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Medical Second Opinion Market Outlook, 2020-2033
4.1. North America Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
4.1.1. Cancer
4.1.2. Cardiovascular Diseases
4.1.3. Neurological Disorders
4.1.4. Orthopedic Conditions
4.1.5. Others
4.2. North America Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
4.2.1. Hospitals
4.2.2. Online Second Opinion Platforms
4.2.3. Specialty Clinics
4.3. North America Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
4.3.1. Online
4.3.2. In-Person
4.4. North America Medical Second Opinion Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Medical Second Opinion Market Outlook, by Condition, 2020-2033
4.4.2. United States Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
4.4.3. United States Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
4.4.4. Canada Medical Second Opinion Market Outlook, by Condition, 2020-2033
4.4.5. Canada Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
4.4.6. Canada Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5. Europe Medical Second Opinion Market Outlook, 2020-2033
5.1. Europe Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
5.1.1. Cancer
5.1.2. Cardiovascular Diseases
5.1.3. Neurological Disorders
5.1.4. Orthopedic Conditions
5.1.5. Others
5.2. Europe Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
5.2.1. Hospitals
5.2.2. Online Second Opinion Platforms
5.2.3. Specialty Clinics
5.3. Europe Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
5.3.1. Online
5.3.2. In-Person
5.4. Europe Medical Second Opinion Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Germany Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.2. Germany Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.3. Germany Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.4. United Kingdom Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.5. United Kingdom Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.6. United Kingdom Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.7. France Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.8. France Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.9. France Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.10. Spain Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.11. Spain Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.12. Spain Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.13. Switzerland Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.14. Switzerland Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.15. Switzerland Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.16. Netherlands Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.17. Netherlands Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.18. Netherlands Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
5.4.19. Denmark Medical Second Opinion Market Outlook, by Condition, 2020-2033
5.4.20. Denmark Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
5.4.21. Denmark Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6. Asia Pacific Medical Second Opinion Market Outlook, 2020-2033
6.1. Asia Pacific Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
6.1.1. Cancer
6.1.2. Cardiovascular Diseases
6.1.3. Neurological Disorders
6.1.4. Orthopedic Conditions
6.1.5. Others
6.2. Asia Pacific Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
6.2.1. Hospitals
6.2.2. Online Second Opinion Platforms
6.2.3. Specialty Clinics
6.3. Asia Pacific Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
6.3.1. Online
6.3.2. In-Person
6.4. Asia Pacific Medical Second Opinion Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. India Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.2. India Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.3. India Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.4. China Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.5. China Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.6. China Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.7. Japan Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.8. Japan Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.9. Japan Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.10. South Korea Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.11. South Korea Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.12. South Korea Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.13. Singapore Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.14. Singapore Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.15. Singapore Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.16. Bangladesh Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.17. Bangladesh Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.18. Bangladesh Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.19. Nepal Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.20. Nepal Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.21. Nepal Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
6.4.22. Sri Lanka Medical Second Opinion Market Outlook, by Condition, 2020-2033
6.4.23. Sri Lanka Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
6.4.24. Sri Lanka Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
7. Latin America Medical Second Opinion Market Outlook, 2020-2033
7.1. Latin America Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
7.1.1. Cancer
7.1.2. Cardiovascular Diseases
7.1.3. Neurological Disorders
7.1.4. Orthopedic Conditions
7.1.5. Others
7.2. Latin America Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
7.2.1. Hospitals
7.2.2. Online Second Opinion Platforms
7.2.3. Specialty Clinics
7.3. Latin America Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
7.3.1. Online
7.3.2. In-Person
7.4. Latin America Medical Second Opinion Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Medical Second Opinion Market Outlook, by Condition, 2020-2033
7.4.2. Brazil Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
7.4.3. Brazil Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
7.4.4. Mexico Medical Second Opinion Market Outlook, by Condition, 2020-2033
7.4.5. Mexico Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
7.4.6. Mexico Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
7.4.7. Argentina Medical Second Opinion Market Outlook, by Condition, 2020-2033
7.4.8. Argentina Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
7.4.9. Argentina Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
7.4.10. Chile Medical Second Opinion Market Outlook, by Condition, 2020-2033
7.4.11. Chile Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
7.4.12. Chile Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
7.4.13. Colombia Medical Second Opinion Market Outlook, by Condition, 2020-2033
7.4.14. Colombia Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
7.4.15. Colombia Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8. Middle East & Africa Medical Second Opinion Market Outlook, 2020-2033
8.1. Middle East & Africa Medical Second Opinion Market Outlook, by Condition, Value (US$ Billion), 2020-2033
8.1.1. Cancer
8.1.2. Cardiovascular Diseases
8.1.3. Neurological Disorders
8.1.4. Orthopedic Conditions
8.1.5. Others
8.2. Middle East & Africa Medical Second Opinion Market Outlook, by Service Provider, Value (US$ Billion), 2020-2033
8.2.1. Hospitals
8.2.2. Online Second Opinion Platforms
8.2.3. Specialty Clinics
8.3. Middle East & Africa Medical Second Opinion Market Outlook, by Delivery Mode, Value (US$ Billion), 2020-2033
8.3.1. Online
8.3.2. In-Person
8.4. Middle East & Africa Medical Second Opinion Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. Saudi Arabia Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.2. Saudi Arabia Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.3. Saudi Arabia Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.4. United Arab Emirates Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.5. United Arab Emirates Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.6. United Arab Emirates Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.7. Qatar Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.8. Qatar Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.9. Qatar Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.10. Kuwait Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.11. Kuwait Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.12. Kuwait Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.13. Israel Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.14. Israel Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.15. Israel Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.16. South Africa Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.17. South Africa Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.18. South Africa Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.19. Nigeria Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.20. Nigeria Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.21. Nigeria Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
8.4.22. Egypt Medical Second Opinion Market Outlook, by Condition, 2020-2033
8.4.23. Egypt Medical Second Opinion Market Outlook, by Service Provider, 2020-2033
8.4.24. Egypt Medical Second Opinion Market Outlook, by Delivery Mode, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Cleveland Clinic
9.5.2. Mayo Clinic
9.5.3. Johns Hopkins Medicine
9.5.4. Cedars-Sinai
9.5.5. Transcarent
9.5.6. Included Health
9.5.7. Teladoc Health
9.5.8. WorldCare
9.5.9. Apollo Hospitals
9.5.10. Fortis Healthcare
9.5.11. Medanta
9.5.12. Charité
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Condition | Cancer, Cardiovascular Diseases, Neurological Disorders, Orthopedic Conditions, Others |
| Service Provider | Hospitals, Online Second Opinion Platforms, Specialty Clinics |
| Delivery Mode | Online, In-Person |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The medical second opinion market is valued at US$ 9.69 billion in 2026, led by cancer reviews and North America.
The market is projected to reach US$ 28.55 billion by 2033, growing at a 16.7% CAGR and adding US$ 18.86 billion.
Neurological disorders are growing fastest at an 18.9% CAGR through 2033, driven by complex dementia, epilepsy, and multiple sclerosis cases.
Asia Pacific is growing fastest at a 19.6% CAGR through 2033, driven by rising cancer cases and telemedicine in India and China.
North America holds the largest share at 43.3% in 2026, supported by leading hospitals and employer-paid second opinion programs.
Related Reports
Smart Home Health Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The smart home health market is projected to grow from US$5.80 billion in 2026 to US$9.90 billion by 2033, at a 7.9% CAGR, driven by aging and home monitoring.
Population Health Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The population health management market is projected to grow from US$46.93 billion in 2026 to US$132.63 billion by 2033, at a 16.0% CAGR, led by value-based care.
Patient Blood Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the patient blood management market, reaching US$ 25.61 billion by 2033 at 6.4% CAGR, with product and regional insights.
Medical Fraud Detection Management Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore medical fraud detection management, reaching US$ 11.47 billion by 2033 at 17.4% CAGR, with deployment and regional insights.
Bioinformatics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the bioinformatics market, reaching US$ 44.10 billion by 2033 at 13.1% CAGR, with offering, technology and regional insights.
Drug Modeling Software Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The drug modeling software market is projected to grow from US$9.70 billion in 2026 to US$18.20 billion by 2033, at a 9.4% CAGR, driven by AI drug discovery.