


3D Food Printing Market
3D Food Printing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
3D Food Printing Market Size and Trend Analysis
Is 3D Food Printing Growing Beyond Pilot Scale?
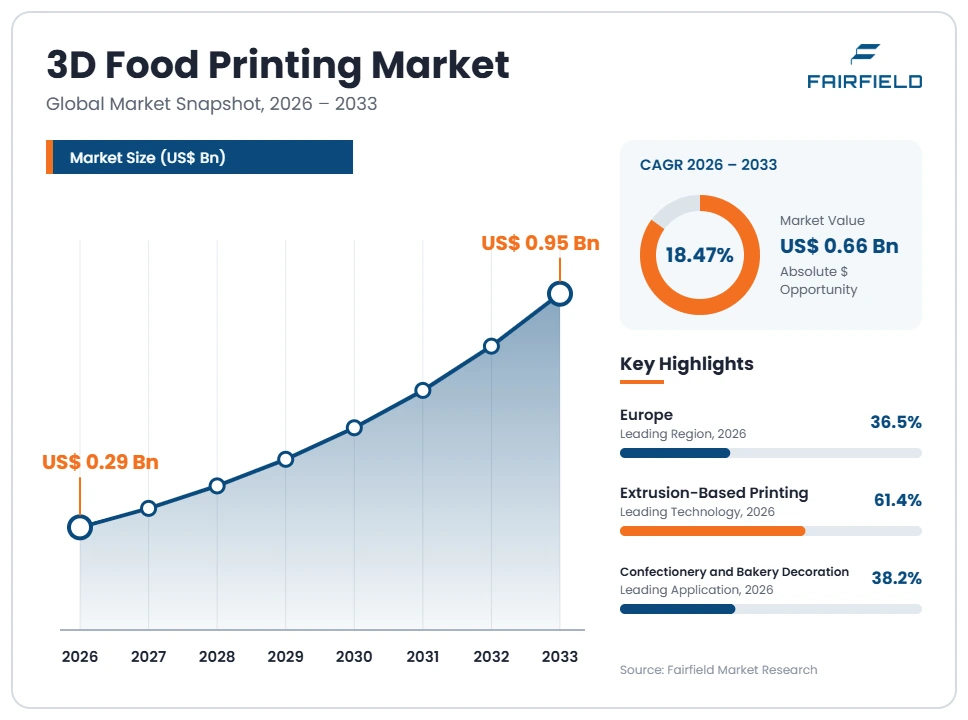
The global 3D Food Printing market size is expected to be valued at US$ 0.29 billion in 2026 and projected to reach US$ 0.95 billion by 2033, growing at a CAGR of 18.47% between 2026 and 2033.
The market grew at a 20.1% CAGR from 2020 to 2025, reaching US$ 245 million in 2025 from a very small base of roughly US$ 98 million in 2020. Three factors carry growth forward. Confectionery and bakery decoration now uses printers as routine production tools rather than demonstration pieces. Plant-based protein producers use extrusion printing to align fibres into whole-cut textures. Institutional kitchens print texture-modified meals for residents with swallowing difficulties. Outside those three uses the technology remains at pilot scale, so absolute revenue stays modest despite the strong percentage growth rate.
Key Report Takeaways
- By Technology: Extrusion-Based Printing held 61.4% share in 2026, while Inkjet Printing is projected to expand at a 21.8% CAGR through 2033, because surface decoration of confectionery and baked goods needs no structural build.
- By Material: Chocolate and Confectionery Pastes held 33.8% share in 2026, while Plant-Based Protein Formulations are projected to expand at a 23.4% CAGR through 2033, as whole-cut analogue producers scale fibre-alignment printing lines.
- By Application: Confectionery and Bakery Decoration held 38.2% share in 2026, while Texture-Modified and Personalised Nutrition is projected to expand at a 22.6% CAGR through 2033, supported by swallowing-safe catering standards in care settings.
- By End User: Food Manufacturers held 31.5% share in 2026, while Healthcare and Elderly Care Facilities are projected to expand at a 24.1% CAGR through 2033, as central production kitchens replace hand-moulded purée meals.
- By Geography: Europe held 36.5% share in 2026, while Asia Pacific is projected to expand at a 21.3% CAGR through 2033, led by equipment manufacturing and dessert printing in China, Japan, and South Korea.
Global 3D Food Printing Market Trends and Insights
Drivers Impact Analysis
Two commercially proven uses account for most equipment and edible material sales through 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Confectionery and bakery decoration replacing hand-finishing labour | High | Europe, North America, Asia Pacific | Short term ≤2 years |
| Fibre-structuring of plant-based protein into whole-cut formats | High | Europe, North America | Medium term 2–4 years |
Confectionery Decoration Economics Make 3D Food Printing a Routine Bakery Production Tool
Decoration is the one application where printed food already pays for itself. Hand-piping chocolate filigree, sugar lattices, and personalised cake toppers is slow, skill-dependent, and hard to staff. A printer reproduces the same design hundreds of times without variation, which lets a bakery sell premium finishing at a predictable labour cost.
The mechanism is simple material behaviour combined with low regulatory friction. Tempered chocolate and sugar pastes have a workable viscosity window and set quickly, so deposition is reliable without exotic process control. The ingredients are already approved foods, which avoids any assessment under Regulation (EU) 2015/2283 on novel foods. Contact parts must still comply with Regulation (EC) No 1935/2004 on food contact materials and Regulation (EU) No 10/2011 on plastics, but compliant nozzles and cartridges are commercially available, so adoption rests on commercial judgement rather than approval timelines.
Fibre Alignment in Printed Plant Protein Lifts Industrial Demand for Extrusion Food Printers
Whole-cut plant-based products are the largest industrial pull on food printing equipment. Mince and patty formats never needed printing, but steak, fillet, and bacon analogues require anisotropic fibre structure and fat marbling that mixing and moulding cannot produce. Extrusion printing deposits protein and fat phases in controlled layers, which is why producers buy printing lines rather than conventional formers.
The causal chain runs from consumer rejection of early analogues to process investment. Buyers accepted ground formats but criticised texture in premium cuts, which stalled category growth and pushed producers toward structuring technology. Printing gives formulators direct control over layer thickness, fat distribution, and bite, and it allows rapid recipe iteration without new tooling. Scale-up remains the limiting factor, so most installations today sit between pilot line and modest commercial throughput rather than at full industrial volume.
Restraints Impact Analysis
Two operational constraints keep printed food confined to niche and pilot-scale production.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Low throughput and cleaning validation time between production batches | High | Global | Long term ≥4 years |
| Narrow ingredient rheology windows and high cost per printed portion | High | Global | Medium term 2–4 years |
Throughput and Between-Batch Cleaning Validation Cap 3D Food Printer Output per Shift
Output per hour is the single biggest barrier to commercial food printing. A printer builds one item at a time in layers, while a depositor or moulding line produces thousands of units in the same period. That difference confines printing to high-value, low-volume items and keeps it out of mainstream manufacturing.
The specific cost sources are downtime and hygiene compliance. Regulation (EC) No 852/2004 on the hygiene of foodstuffs requires operators to run procedures based on HACCP principles, and the Food Safety Modernization Act imposes comparable preventive control duties in the United States. Printheads, hoppers, tubing, and nozzles contain narrow passages that must be dismantled, cleaned, and verified between recipes, particularly where allergens change. Cleaning and reassembly can consume as much shift time as printing itself, which destroys the economics of any high-mix production schedule.
Narrow Rheology Windows and Cost per Portion Keep Printed Food Off Mainstream Menus
Material behaviour limits what can be printed and at what price. A paste must flow through a fine nozzle under pressure, then hold its shape immediately and survive cooking or setting without slumping. Most everyday foods fail at least one of those tests without reformulation, which narrows the commercial menu sharply.
Three cost sources follow from that. Reformulation adds hydrocolloids, starches, and stabilisers that raise ingredient cost and must each be declared on the label. Purpose-made cartridges and sealed pastes sell at a clear premium over bulk ingredients, and where a printed ingredient has no significant consumption history in the European Union it falls under Regulation (EU) 2015/2283 and requires authorisation before sale. Skilled operator time for calibration and recipe tuning completes a cost per portion that most food service price points cannot absorb.
Market Opportunities
Texture-Modified Meals Under the IDDSI Framework Open an Institutional Catering Pool
Swallowing-safe catering is the clearest funded application for printed food. Hospitals, care homes, and rehabilitation facilities serve large volumes of purée meals that are nutritionally adequate but visually unappetising, which contributes to poor intake. Printing restores recognisable shapes to purées at consistent texture, creating a repeatable institutional contract rather than a novelty sale.
Central production kitchens and contract caterers are placed to capture this pool, and demand comes from clinical nutrition and catering managers rather than from chefs. The IDDSI framework gives a common vocabulary and testing method for texture levels, which lets a supplier specify a printed product against an agreed standard and lets a buyer verify it. That shared definition is what converts a pilot into a tender. Equipment, moulded purée bases, and validation support can all be sold into the same account.
Printable Edible Material Cartridges Open a Recurring Pool Beyond Printer Hardware Sales
Edible materials, not machines, represent the durable revenue pool in this market. A bakery or care kitchen buys one printer but consumes chocolate, protein, purée, and icing cartridges every week, so the installed base generates annuity revenue far larger than the original equipment sale over a machine’s life.
Material formulators and ingredient houses are best placed to capture it, and demand comes from operators who want a guaranteed print result rather than a bulk commodity. Sealed cartridges also simplify hygiene duties under Regulation (EC) No 852/2004, because a closed system reduces open handling and cleaning between recipes. Contact surfaces must comply with Regulation (EC) No 1935/2004, and in the United States packaging and contact components may require a food contact substance notification to the FDA. Certified consumables therefore carry both convenience and compliance value.
Segment Analysis
- By Technology: Extrusion Carries Volume While Inkjet Decoration Advances Fastest
Extrusion-Based Printing led with 61.4% share in 2026, because most edible materials are pastes and it handles chocolate, dough, purée, and protein formulations with the same basic deposition mechanism. Equipment is also the cheapest to build and maintain. Inkjet Printing grows fastest at a 21.8% CAGR to 2033, since depositing edible inks onto a finished surface avoids all structural build problems.
Binder Jetting serves sugar sculpture and powder-based confectionery where fine geometric detail matters more than throughput. Laser-Based Sintering and Cooking remains largely a research technology, applied to selective cooking and caramelisation rather than production. For vendors, the practical implication is that decoration-focused systems reach commercial payback quickly, while structural printing platforms still require a patient industrial customer.
- By Material: Confectionery Pastes Dominate Today While Plant Protein Scales Quickest
Chocolate and Confectionery Pastes held 33.8% share in 2026, reflecting predictable viscosity, fast setting, and an existing premium price point that absorbs printing cost. Bakeries and chocolatiers buy them continuously. Plant-Based Protein Formulations expand fastest at a 23.4% CAGR through 2033, because whole-cut analogue producers need printed fibre alignment that conventional forming cannot deliver.
Dough and Bakery Mixes support printed pastry and pizza bases, Dairy and Purée-Based Materials underpin texture-modified catering, and Fruit, Vegetable and Algae Pastes serve plated garnish and nutrition applications. Where an ingredient lacks significant consumption history in the European Union, Regulation (EU) 2015/2283 applies and authorisation must be obtained before launch. The implication for suppliers is that material certification and documented safety, rather than printer specification, is becoming the main barrier to entry in this market.
- By Application: Bakery Decoration Leads While Texture-Modified Nutrition Grows Fastest
Confectionery and Bakery Decoration was the largest application at 38.2% share in 2026, because it is the only use with proven unit economics at small scale. A printed topper sells at a premium and replaces skilled hand-finishing labour. Texture-Modified and Personalised Nutrition grows fastest at a 22.6% CAGR to 2033, driven by institutional catering for residents with swallowing difficulties.
Plant-Based Meat Analogues represent the largest industrial ambition, Snacks and Ready Meals remain mostly experimental, and Research and Product Development sustains equipment sales into universities and corporate innovation centres. The IDDSI framework gives the nutrition application something that the other uses currently lack: an agreed, testable specification with defined texture levels. That measurability is the reason institutional buyers can write printed meals into a formal tender document.
- By End User: Food Manufacturers Buy Most While Care Facilities Expand Fastest
Food Manufacturers accounted for 31.5% of spending in 2026, because industrial buyers purchase multi-head systems, integration engineering, and material development together rather than single machines. Their projects also fund the largest material volumes. Healthcare and Elderly Care Facilities grow fastest at a 24.1% CAGR through 2033, as central production kitchens replace hand-moulded purée with printed shapes at controlled texture levels.
Restaurants and Hospitality use printers for plated signature items and event catering, Bakeries and Confectioneries form the steadiest small-unit customer base, and Research Institutes drive method development. Hygiene duties based on HACCP principles under Regulation (EC) No 852/2004 apply across all of them. For vendors, the institutional channel matters because it buys on multi-year catering contracts rather than on seasonal menu changes.
Geography Analysis
- North America Scales Printed Protein and Decoration Through Commercial Kitchens
North America held 30.2% share in 2026, with the United States accounting for most of it and Canada contributing through food innovation centres in Ontario and Quebec. Demand concentrates in commercial bakery groups, hospitality operators, and alternative protein developers rather than in household use.
Regulation shapes purchasing. The Food Safety Modernization Act requires preventive controls and documented hazard analysis, so buyers favour machines with cleanable, verifiable contact paths. Contact components may require a food contact substance notification to the FDA before use, which adds a documentation step for equipment importers.
Venture-funded alternative protein developers remain concentrated in California and the Midwest. The regional opportunity is contract manufacturing, where a single printing line serves several brands and spreads capital cost across customers.
- Which Region Is Leading the 3D Food Printing Market?
Europe leads with 36.5% share in 2026, because the region hosts most established printer developers and the clearest institutional demand. The Netherlands, Spain, Germany, Italy, and Israel supply the bulk of equipment design, while Nordic and Dutch care systems fund texture-modified meal programmes.
Three causes explain the position. Public research funding for food technology has supported printing projects for over a decade, giving the region deep applied expertise. Care catering for residents with swallowing difficulties is organised centrally, which makes institutional purchasing possible. Chocolate and patisserie traditions create a large premium decoration market that absorbs equipment cost.
Regulatory clarity also helps: Regulation (EC) No 1935/2004 and Regulation (EU) No 10/2011 give manufacturers defined compliance targets for contact parts. The main regional change is the move from laboratory pilots to catering tenders.
- Which Region Is Growing Fastest in the 3D Food Printing Market?
Asia Pacific is growing fastest at a 21.3% CAGR between 2026 and 2033, from 25.4% share in 2026, because China, Japan, and South Korea combine low-cost equipment manufacturing with strong consumer appetite for novel dessert and confectionery formats.
The causes are manufacturing and demography. Chinese electronics and machinery suppliers build extrusion and inkjet food printers at prices well below European equivalents, which widens access for small operators. Japan’s ageing population has created organised demand for softened and shaped meals in care settings, supported by national texture classification practice. South Korean and Singaporean innovation agencies fund alternative protein and personalised nutrition projects.
The change shaping the region is domestic cartridge supply, which removes the import premium that previously made printed food uneconomic for small kitchens.
- Latin America Adopts Printed Decoration Through Premium Bakery and Hospitality Operators
Latin America held 4.1% share in 2026, with Brazil, Mexico, Chile, Argentina, and Colombia accounting for nearly all activity. Adoption sits almost entirely in premium patisserie, hotel groups, and event catering, where printed chocolate and sugar decoration commands a visible price premium.
Culinary innovation centres in São Paulo and Mexico City have run printing projects with universities, and a small number of plant-based protein start-ups are evaluating structuring equipment for domestic launch.
Barriers are economic. Import duties and currency movement raise machine prices sharply, certified cartridges must be shipped from Europe at long lead times, and technical service coverage is thin outside major cities. The opportunity lies in locally formulated pastes made from regional ingredients such as cocoa, maize, and fruit purées, which would cut both cost and lead time.
- Middle East & Africa Builds Capacity Around Hospitality Showpieces and Food Security Research
Middle East & Africa represented 3.8% share in 2026, the smallest regional position, concentrated in the United Arab Emirates, Saudi Arabia, Qatar, Egypt, and South Africa. Luxury hotels and event caterers in Dubai, Doha, and Riyadh buy printers for showpiece desserts and branded confectionery.
National food security programmes in the Gulf states fund research into alternative protein and locally produced ingredients, which has placed printing equipment in new research facilities and culinary institutes.
Constraints are substantial. Trained operators are scarce, humidity complicates chocolate and sugar printing without climate-controlled rooms, and import dependence lengthens spare part supply. The clearest opportunity is hospitality service contracts, in which a vendor supplies the printer, cartridges, design files, and operator training as a single managed package rather than as a capital sale.
Competitive Landscape
The market is fragmented and remains early in its commercial life. No supplier holds a dominant position, and the field divides into three groups: desktop and professional printer developers such as Natural Machines, byFlow, and Print2Taste; alternative protein producers such as Revo Foods, Redefine Meat, and Steakholder Foods that use printing as a production process rather than selling machines; and industrial integrators such as Cocuus System Ibérica that build lines for food manufacturers. Low barriers to building an extrusion machine keep attracting entrants, particularly from Chinese electronics manufacturing, which prevents consolidation.
Competition turns on applications rather than hardware specification. Buyers compare print speed against hand-finishing labour cost, cleaning time between recipes, availability of certified cartridges, and whether a supplier can deliver validated recipes for a specific product. Food safety documentation for contact parts under Regulation (EC) No 1935/2004 has become a baseline expectation in European tenders. New approaches arrive from adjacent engineering fields, including industrial dosing, confectionery depositing, and additive manufacturing, where firms already understand viscous material handling at production rates.
Strategic activity clusters around three themes. Printer developers are pairing machines with proprietary cartridge ranges to build recurring revenue, since hardware margins alone cannot support the business. Alternative protein firms are seeking contract manufacturing partners to reach commercial volumes without funding their own factories. Equipment suppliers are courting institutional catering groups, because a single central production kitchen contract delivers more predictable volume than dozens of restaurant sales.
The prevailing direction is narrowing focus. Rather than positioning printers as general-purpose kitchen appliances, vendors are specialising in one proven use, building certified materials around it, and selling an outcome instead of a machine.
Recent Industry Developments
- April 2004: The European Union adopted Regulation (EC) No 852/2004 on the hygiene of foodstuffs – made HACCP-based procedures mandatory for food operators, defining the cleaning and verification duties that printing equipment must satisfy.
- October 2004: The European Union adopted Regulation (EC) No 1935/2004 on materials and articles intended to come into contact with food – set the framework requirements that printer nozzles, hoppers, and cartridges must meet.
- January 2011: The Food Safety Modernization Act was signed into law in the United States – shifted oversight toward preventive controls, raising documentation expectations for new food production equipment.
- January 2011: The European Union adopted Regulation (EU) No 10/2011 on plastic materials and articles intended to come into contact with food – established migration limits that constrain the polymers used in printer contact parts.
- November 2015: The European Union adopted Regulation (EU) 2015/2283 on novel foods – created the authorisation route that printed ingredients without significant consumption history must follow before sale.
Companies Covered in the Report
- Natural Machines
- byFlow B.V.
- Print2Taste GmbH
- Revo Foods GmbH
- Redefine Meat Ltd.
- Steakholder Foods Ltd.
- Cocuus System Ibérica S.L.
- Biozoon Food Innovations GmbH
- BeeHex, Inc.
- Wiiboox Technology Co., Ltd.
3D Food Printing Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 0.29 Billion |
| Market Size 2033 | US$ 0.95 Billion |
| CAGR 2026–2033 | 18.47% |
| Absolute Dollar Opportunity | US$ 0.66 Billion |
| Largest Market | Europe |
| Fastest-Growing Market | Asia Pacific |
| Market Concentration | Low |
| Major Players | Natural Machines, byFlow, Print2Taste, Revo Foods, Redefine Meat |
3D Food Printing Market Segmentation
Technology
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
Material
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
Application
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
End User
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global 3D Food Printing Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Confectionery Decoration Economics Make 3D Food Printing a Routine Bakery Production Tool
- Fibre Alignment in Printed Plant Protein Lifts Industrial Demand for Extrusion Food Printers
- Restraints
- Throughput and Between-Batch Cleaning Validation Cap 3D Food Printer Output per Shift
- Narrow Rheology Windows and Cost per Portion Keep Printed Food Off Mainstream Menus
- Market Opportunities
- Texture-Modified Meals Under the IDDSI Framework Open an Institutional Catering Pool
- Printable Edible Material Cartridges Open a Recurring Pool Beyond Printer Hardware Sales
- Drivers
- Global 3D Food Printing Market Outlook, 2020–2033
- Global 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- Global 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- Global 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- Global 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- Global 3D Food Printing Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- North America 3D Food Printing Market Outlook, 2020–2033
- North America 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- North America 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- North America 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- North America 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- North America 3D Food Printing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States 3D Food Printing Market Outlook, by Technology, 2020–2033
- United States 3D Food Printing Market Outlook, by Material, 2020–2033
- United States 3D Food Printing Market Outlook, by Application, 2020–2033
- United States 3D Food Printing Market Outlook, by End User, 2020–2033
- Canada 3D Food Printing Market Outlook, by Technology, 2020–2033
- Canada 3D Food Printing Market Outlook, by Material, 2020–2033
- Canada 3D Food Printing Market Outlook, by Application, 2020–2033
- Canada 3D Food Printing Market Outlook, by End User, 2020–2033
- North America 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Europe 3D Food Printing Market Outlook, 2020–2033
- Europe 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- Europe 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- Europe 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- Europe 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- Europe 3D Food Printing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Netherlands 3D Food Printing Market Outlook, by Technology, 2020–2033
- Netherlands 3D Food Printing Market Outlook, by Material, 2020–2033
- Netherlands 3D Food Printing Market Outlook, by Application, 2020–2033
- Netherlands 3D Food Printing Market Outlook, by End User, 2020–2033
- Spain 3D Food Printing Market Outlook, by Technology, 2020–2033
- Spain 3D Food Printing Market Outlook, by Material, 2020–2033
- Spain 3D Food Printing Market Outlook, by Application, 2020–2033
- Spain 3D Food Printing Market Outlook, by End User, 2020–2033
- Germany 3D Food Printing Market Outlook, by Technology, 2020–2033
- Germany 3D Food Printing Market Outlook, by Material, 2020–2033
- Germany 3D Food Printing Market Outlook, by Application, 2020–2033
- Germany 3D Food Printing Market Outlook, by End User, 2020–2033
- Italy 3D Food Printing Market Outlook, by Technology, 2020–2033
- Italy 3D Food Printing Market Outlook, by Material, 2020–2033
- Italy 3D Food Printing Market Outlook, by Application, 2020–2033
- Italy 3D Food Printing Market Outlook, by End User, 2020–2033
- Europe 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Asia Pacific 3D Food Printing Market Outlook, 2020–2033
- Asia Pacific 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- Asia Pacific 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- Asia Pacific 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- Asia Pacific 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- Asia Pacific 3D Food Printing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China 3D Food Printing Market Outlook, by Technology, 2020–2033
- China 3D Food Printing Market Outlook, by Material, 2020–2033
- China 3D Food Printing Market Outlook, by Application, 2020–2033
- China 3D Food Printing Market Outlook, by End User, 2020–2033
- Japan 3D Food Printing Market Outlook, by Technology, 2020–2033
- Japan 3D Food Printing Market Outlook, by Material, 2020–2033
- Japan 3D Food Printing Market Outlook, by Application, 2020–2033
- Japan 3D Food Printing Market Outlook, by End User, 2020–2033
- South Korea 3D Food Printing Market Outlook, by Technology, 2020–2033
- South Korea 3D Food Printing Market Outlook, by Material, 2020–2033
- South Korea 3D Food Printing Market Outlook, by Application, 2020–2033
- South Korea 3D Food Printing Market Outlook, by End User, 2020–2033
- Asia Pacific 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Latin America 3D Food Printing Market Outlook, 2020–2033
- Latin America 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- Latin America 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- Latin America 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- Latin America 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- Latin America 3D Food Printing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil 3D Food Printing Market Outlook, by Technology, 2020–2033
- Brazil 3D Food Printing Market Outlook, by Material, 2020–2033
- Brazil 3D Food Printing Market Outlook, by Application, 2020–2033
- Brazil 3D Food Printing Market Outlook, by End User, 2020–2033
- Mexico 3D Food Printing Market Outlook, by Technology, 2020–2033
- Mexico 3D Food Printing Market Outlook, by Material, 2020–2033
- Mexico 3D Food Printing Market Outlook, by Application, 2020–2033
- Mexico 3D Food Printing Market Outlook, by End User, 2020–2033
- Chile 3D Food Printing Market Outlook, by Technology, 2020–2033
- Chile 3D Food Printing Market Outlook, by Material, 2020–2033
- Chile 3D Food Printing Market Outlook, by Application, 2020–2033
- Chile 3D Food Printing Market Outlook, by End User, 2020–2033
- Argentina 3D Food Printing Market Outlook, by Technology, 2020–2033
- Argentina 3D Food Printing Market Outlook, by Material, 2020–2033
- Argentina 3D Food Printing Market Outlook, by Application, 2020–2033
- Argentina 3D Food Printing Market Outlook, by End User, 2020–2033
- Colombia 3D Food Printing Market Outlook, by Technology, 2020–2033
- Colombia 3D Food Printing Market Outlook, by Material, 2020–2033
- Colombia 3D Food Printing Market Outlook, by Application, 2020–2033
- Colombia 3D Food Printing Market Outlook, by End User, 2020–2033
- Latin America 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Middle East & Africa 3D Food Printing Market Outlook, 2020–2033
- Middle East & Africa 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
- Middle East & Africa 3D Food Printing Market Outlook, by Material, Value (US$ Billion), 2020–2033
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
- Middle East & Africa 3D Food Printing Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
- Middle East & Africa 3D Food Printing Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
- Middle East & Africa 3D Food Printing Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United Arab Emirates 3D Food Printing Market Outlook, by Technology, 2020–2033
- United Arab Emirates 3D Food Printing Market Outlook, by Material, 2020–2033
- United Arab Emirates 3D Food Printing Market Outlook, by Application, 2020–2033
- United Arab Emirates 3D Food Printing Market Outlook, by End User, 2020–2033
- Saudi Arabia 3D Food Printing Market Outlook, by Technology, 2020–2033
- Saudi Arabia 3D Food Printing Market Outlook, by Material, 2020–2033
- Saudi Arabia 3D Food Printing Market Outlook, by Application, 2020–2033
- Saudi Arabia 3D Food Printing Market Outlook, by End User, 2020–2033
- Qatar 3D Food Printing Market Outlook, by Technology, 2020–2033
- Qatar 3D Food Printing Market Outlook, by Material, 2020–2033
- Qatar 3D Food Printing Market Outlook, by Application, 2020–2033
- Qatar 3D Food Printing Market Outlook, by End User, 2020–2033
- Egypt 3D Food Printing Market Outlook, by Technology, 2020–2033
- Egypt 3D Food Printing Market Outlook, by Material, 2020–2033
- Egypt 3D Food Printing Market Outlook, by Application, 2020–2033
- Egypt 3D Food Printing Market Outlook, by End User, 2020–2033
- South Africa 3D Food Printing Market Outlook, by Technology, 2020–2033
- South Africa 3D Food Printing Market Outlook, by Material, 2020–2033
- South Africa 3D Food Printing Market Outlook, by Application, 2020–2033
- South Africa 3D Food Printing Market Outlook, by End User, 2020–2033
- Middle East & Africa 3D Food Printing Market Outlook, by Technology, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Natural Machines
- byFlow B.V.
- Print2Taste GmbH
- Revo Foods GmbH
- Redefine Meat Ltd.
- Steakholder Foods Ltd.
- Cocuus System Ibérica S.L.
- Biozoon Food Innovations GmbH
- BeeHex, Inc.
- Wiiboox Technology Co., Ltd.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Technology
- Extrusion-Based Printing
- Binder Jetting
- Inkjet Printing
- Laser-Based Sintering and Cooking
Material
- Chocolate and Confectionery Pastes
- Dough and Bakery Mixes
- Plant-Based Protein Formulations
- Dairy and Purée-Based Materials
- Fruit, Vegetable and Algae Pastes
Application
- Confectionery and Bakery Decoration
- Plant-Based Meat Analogues
- Texture-Modified and Personalised Nutrition
- Snacks and Ready Meals
- Research and Product Development
End User
- Food Manufacturers
- Restaurants and Hospitality
- Healthcare and Elderly Care Facilities
- Bakeries and Confectioneries
- Research Institutes
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 0.29 billion in 2026, or about US$ 290 million, counting printing hardware and printable edible materials worldwide.
The market is projected to reach US$ 0.95 billion by 2033, growing at an 18.47% CAGR and adding US$ 0.66 billion in absolute opportunity.
Extrusion-Based Printing holds 61.4% share in 2026, because most edible materials are pastes suited to simple, low-cost deposition mechanisms.
Texture-Modified and Personalised Nutrition grows fastest at a 22.6% CAGR through 2033, supported by institutional catering for residents with swallowing difficulties.
Europe leads with 36.5% share in 2026, and competition is fragmented across printer developers, alternative protein producers, and industrial line integrators.
Related Reports
Oat Milk Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Oat milk market to reach US$ 13.72 billion by 2033 at a 16.8% CAGR. Explore product types, organic demand, distribution channels and regional trends.
Low Glycemic Index Rice Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Low glycemic index rice market to reach US$ 18.01 billion by 2033 at a 7.5% CAGR. Explore rice types, applications, channels and regional trends.
Yeast Ingredient Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the yeast ingredient market, reaching US$ 16.5 billion by 2033 at 6.2% CAGR, with product, application and regional insights.
Vegan Yoghurt Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the vegan yoghurt market, reaching US$ 6.0 billion by 2033 at 6.3% CAGR, with base types, formats, distribution and regional insights.
Sourdough Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the sourdough market, reaching US$ 10.2 billion by 2033 at 6.9% CAGR, with product, fermentation, distribution and regional insights.
Phytogenic Feed Additives Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the phytogenic feed additives market, reaching US$ 2.7 billion by 2033 at 9.8% CAGR, with type, livestock and regional insights.