


Agricultural Biologicals Market
Agricultural Biologicals Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Agricultural Biologicals Market Size and Trend Analysis
How Fast Is the Agricultural Biologicals Market Growing?
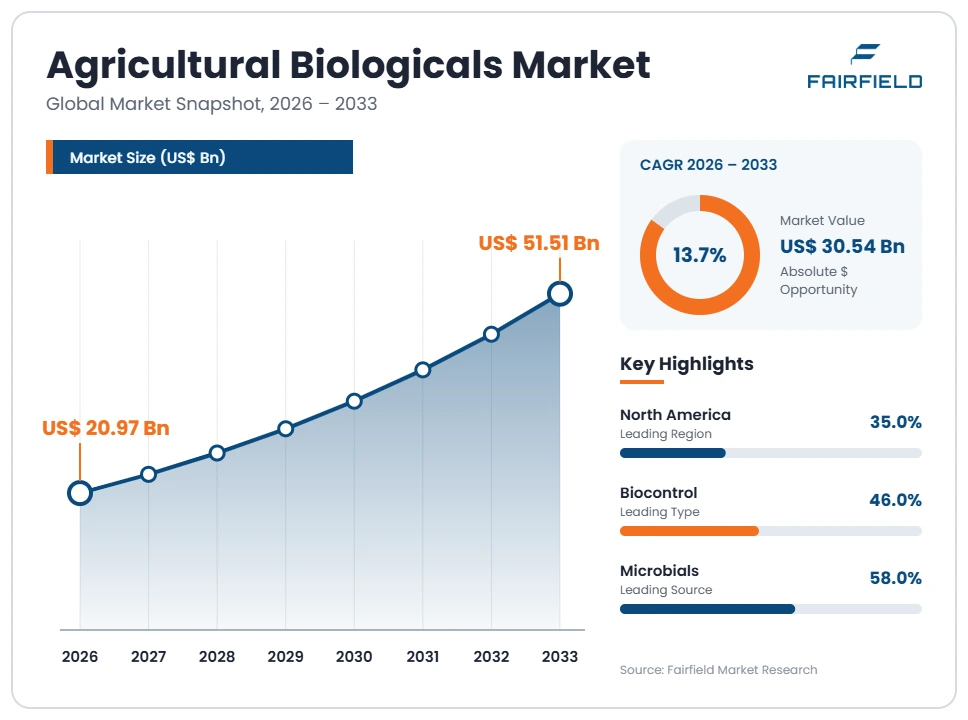
The global agricultural biologicals market size is expected to be valued at US$ 20.97 billion in 2026 and projected to reach US$ 51.51 billion by 2033, growing at a CAGR of 13.7% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 12.4%, as farmers faced stricter limits on chemical pesticides, retailers demanded lower residues, and large crop protection companies bought or partnered with biological specialists. Agricultural biologicals are products made from living organisms or natural materials, including biopesticides, biostimulants, and biofertilizers, used to protect crops, improve plant growth, and boost soil health. Three factors now drive growth: regulatory pressure on synthetic chemicals, demand for sustainable agriculture and residue-free food, and rising resistance of pests and diseases to conventional products. The market is shifting toward microbial products with proven field performance, combination programs that pair biologicals with chemicals, seed treatments, and precision application. In March 2025, Syngenta launched NETURE, a biological insecticide for soybean and corn, showing how major companies are expanding biological portfolios for row crops.
Key Report Takeaways
- By Type: Biocontrol held 46.0% share in 2026 and is also projected to expand fastest at a 15.2% CAGR through 2033, driven by biopesticides that manage resistant pests with low residues and short pre-harvest intervals.
- By Source: Microbials held 58.0% share in 2026, while Semiochemicals are projected to expand at a 16.0% CAGR through 2033, driven by pheromone-based mating disruption in orchards, vineyards, and row crops.
- By Crop Type: Fruits & Vegetables held 41.0% share in 2026 and is also projected to expand fastest at a 14.4% CAGR through 2033, driven by export residue limits and high crop values.
- By Region: North America held 35.0% share in 2026, while Latin America is projected to expand at a 15.6% CAGR through 2033, driven by rapid adoption of biological seed and soil treatments in Brazil and Argentina.
Global Agricultural Biologicals Market Trends and Insights
Drivers Impact Analysis
Two drivers carry the strongest influence on agricultural biologicals demand during the forecast period.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Regulatory pressure on chemical pesticides | High | Europe, North America | Long term (≥4 years) |
| Demand for sustainable, residue-free food | High | Global | Long term (≥4 years) |
Regulatory Pressure Is Driving the Agricultural Biologicals Market
Regulatory pressure on chemical pesticides is the strongest driver of the agricultural biologicals market. Farmers are losing many older chemical tools.
The mechanism is stricter rules on pesticide safety. The European Union has removed approval for many active ingredients and set targets to reduce chemical pesticide use and risk, while promoting sustainable agriculture and integrated pest management. The U.S. Environmental Protection Agency offers faster review for many biopesticides, which have lower risks. Maximum residue limits in export markets push growers of fruits and vegetables to use products that leave little or no residue. Developing new synthetic chemicals costs hundreds of millions of dollars and takes about a decade, while biologicals are often faster and cheaper to register. As chemical options shrink, farmers turn to biopesticides and biostimulants to protect yields. These shifts make biologicals a core part of crop protection plans.
Sustainability Demand Is Expanding the Agricultural Biologicals Market
Demand for sustainable, residue-free food is expanding the agricultural biologicals market. Consumers, retailers, and food companies want greener farming.
The cause is changing expectations across the food chain. Supermarkets and food brands set sustainability and residue standards for suppliers. Organic farming is growing in Europe, North America, and Asia Pacific. Biofertilizers and microbial inoculants reduce the need for synthetic nitrogen, which lowers costs and greenhouse gas emissions. Regenerative agriculture programs promote soil health products. Carbon credit and sustainability programs reward farmers who adopt low-impact practices. Pest and disease resistance to chemicals also pushes growers to rotate in biological modes of action. These trends broaden demand from specialty crops into row crops such as soybean, corn, and wheat, where even small adoption rates create large volumes.
Restraints Impact Analysis
Two restraints limit how quickly the agricultural biologicals market grows.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Variable field performance and farmer skepticism | High | Global | Medium term (2–4 years) |
| Short shelf life and complex regulation | Medium | Asia Pacific, Europe | Medium term (2–4 years) |
Variable Performance Slows the Agricultural Biologicals Market
Variable field performance and farmer skepticism slow the agricultural biologicals market. Living products can work differently in different conditions.
The specific causes are biological complexity and past disappointments. Microbes depend on temperature, humidity, soil type, and crop stage, so results can vary from field to field and season to season. Biologicals often act more slowly than chemicals and may need repeated applications. Some low-quality products sold without proper testing have damaged farmer trust. Farmers need clear data showing return on investment before switching. Advisors and distributors may lack training. These factors slow adoption, especially among large row crop farmers who value consistency. Leading companies now run large, multi-year field trial networks and publish independent results to prove performance. Better formulations that protect microbes and extend activity are also improving reliability.
Shelf Life and Regulation Restrict the Agricultural Biologicals Market
Short shelf life and complex regulation restrict the agricultural biologicals market. Living products need careful handling.
The underlying causes are product stability and inconsistent rules. Many microbial products must be stored at controlled temperatures and used within limited periods, which complicates distribution in hot climates and rural areas. Rules for registering biostimulants differ widely between countries, and some places lack clear categories, creating uncertainty. The European Union introduced a new framework for biostimulants under its fertilizing products rules, but approvals for microbial biopesticides can still be slow. Quality control and counterfeit products are concerns in some markets. These factors raise costs and slow market entry. Advances in formulation, such as encapsulation and dry powders, are extending shelf life and reducing the need for cold storage, which helps distribution in tropical markets.
Market Opportunities
Row Crops and Seed Treatments Open a Fast-Growth Revenue Pool
Row crops and seed treatments open a fast-growth revenue pool in the agricultural biologicals market. Large acreage crops offer huge volume potential.
Crop protection companies and seed firms can capture this opportunity. Soybean, corn, wheat, and cotton cover vast areas, and biological seed treatments, nitrogen-fixing microbes, and nematode controls can be applied at low cost per hectare. Brazil has become a global leader in on-farm and commercial biological use in soybean and sugarcane. BASF pre-launched Votivo Prime, a biological nematicide, in Argentina in February 2025. Bioceres Crop Solutions received Brazilian approval for three products based on its Burkholderia platform in May 2024. Products that fit existing seed and spray equipment can scale quickly, because farmers do not need to change their routines or buy new machinery.
Combination Programs and Digital Agronomy Create a Value Revenue Pool
Combination programs and digital agronomy create a value revenue pool in the agricultural biologicals market. Biologicals work best as part of integrated plans.
Large agrochemical companies and agtech firms can capture this opportunity. Programs that combine biologicals with reduced chemical doses deliver reliable results while cutting residues and resistance risk. Digital tools and sensors help time applications for best effect. Data from field trials builds farmer confidence. BASF completed its acquisition of AgBiTech in March 2026 to expand biological insect control. Syngenta, Corteva, Bayer, and UPL are building biological units. Companies that offer full agronomic support can win premium business. Retailers and cooperatives that sell to farmers are also training staff to recommend biologicals, and digital platforms track which products work best in each region and soil type. Gene sequencing helps companies discover new beneficial microbes faster.
Segment Analysis
- By Type: Biocontrol Leads and Grows Fastest
Biocontrol held 46.0% share in 2026 and is also the fastest-growing type, expanding at a 15.2% CAGR through 2033. Biopesticides, including microbial insecticides, fungicides, nematicides, and beneficial insects, control pests and diseases with low residues. Koppert, BioFirst Group, Certis Biologicals, and Syngenta are leading suppliers.
Biostimulants, made from seaweed extracts, humic acids, amino acids, and microbes, improve stress tolerance and nutrient uptake. Biofertilizers supply or unlock nitrogen and phosphorus through microbes. For the market, biocontrol growth replaces lost chemical tools. Biostimulants are one of the fastest-developing categories in Europe after new regulation created a clear path to market, and they help crops cope with drought, heat, and salinity linked to climate change. Biofertilizers are widely used in India and Brazil.
- By Source: Microbials Lead While Semiochemicals Grow Fastest
Microbials held 58.0% share in 2026. Bacteria such as Bacillus and Pseudomonas, fungi such as Trichoderma and Beauveria, and viruses form the largest group of biological products and are used in all crop types. Novonesis is a major microbial supplier.
Semiochemicals are the fastest-growing source, expanding at a 16.0% CAGR through 2033. Pheromones disrupt insect mating without killing beneficial species. Natural products and macrobials are other sources. For the market, semiochemical growth adds targeted solutions. Pheromone dispensers are standard in many apple, pear, grape, and stone fruit orchards, and new sprayable formulations are bringing the technology to row crops such as corn and cotton. Macrobials, such as predatory mites and parasitic wasps, are widely used in greenhouses. Natural products include plant extracts, oils, and minerals.
- By Crop Type: Fruits & Vegetables Lead and Grow Fastest
Fruits & Vegetables held 41.0% share in 2026 and are also the fastest-growing crop type, expanding at a 14.4% CAGR through 2033. High crop values and strict residue limits make biologicals attractive for fruits, vegetables, grapes, and berries.
Cereals and grains and oilseeds and pulses are growing as row crop farmers adopt seed treatments and biofertilizers. Turf, golf courses, and ornamentals also use biologicals. For the market, row crop growth expands volume. Soybean is the largest row crop user of biologicals, especially in Brazil, where nitrogen-fixing inoculants have long been standard and biocontrol use is spreading fast. Corn, wheat, and cotton growers are adopting seed treatments and nematode controls. Greenhouse vegetable growers in Spain and the Netherlands rely heavily on biological pest control.
Geography Analysis
- Which Region Is Leading the Agricultural Biologicals Market?
North America is leading the agricultural biologicals market with a 35.0% share in 2026. The United States has a large specialty crop sector, fast regulatory review for biopesticides, and strong research and startup activity. Certis Biologicals, Corteva, and Valent BioSciences are active. Canada adds demand from canola and pulse growers. California and Florida fruit and vegetable growers are major users of biopesticides. Startups in the region are developing new microbial and RNA-based products. Key barriers include farmer skepticism and variable results in some row crops. One change shaping the region is row crop adoption of biological seed treatments and nitrogen-fixing products.
- Europe Builds the Agricultural Biologicals Market Through Regulation
Europe is a major agricultural biologicals market. Spain, Italy, France, the Netherlands, and Germany face strict pesticide rules and high organic farming shares. Koppert in the Netherlands and BioFirst Group in Belgium are global leaders. Greenhouse growers in Spain and the Netherlands use beneficial insects and mites as standard practice, and organic farming continues to expand under EU policies. Biostimulants gained a clear legal category under the EU fertilizing products regulation. Key barriers include slow registration of microbial biopesticides and differing national rules. One opportunity is greenhouse crops, orchards, and vineyards that need low-residue protection.
- Asia Pacific Builds the Agricultural Biologicals Market Through Large Farm Base
Asia Pacific is a large agricultural biologicals market. India promotes biofertilizers and natural farming, China encourages lower chemical use, and Australia and Japan use biologicals in horticulture. UPL is based in India and sells biologicals worldwide. India subsidizes biofertilizers and promotes natural farming through national schemes, and many small companies produce microbial products locally. China has policies to cut chemical fertilizer and pesticide use, and its biopesticide industry is expanding. Japan and South Korea use biologicals in high-value fruits and vegetables. Key barriers include quality control and product counterfeiting. One opportunity is government programs that support farmers switching to biological inputs.
- Which Region Is Growing Fastest in the Agricultural Biologicals Market?
Latin America is growing fastest in the agricultural biologicals market at a 15.6% CAGR through 2033. Brazil uses biologicals widely in soybean, sugarcane, and coffee, and has fast product approvals. Argentina and Mexico are growing. Brazilian regulators have created faster approval pathways for biological products, and many farms produce microbes on site. Argentina uses biologicals and inoculants widely in soybean and wheat, while Mexico applies them in export vegetables and avocados. Key barriers include quality control of on-farm products and uneven technical support. One change shaping the region is on-farm production combined with commercial products from large suppliers.
- Middle East & Africa Expands the Agricultural Biologicals Market Through Export Horticulture
Middle East & Africa is an emerging agricultural biologicals market. Morocco, Kenya, and South Africa grow export fruits and vegetables that must meet residue limits. Growers in Morocco and Egypt export tomatoes, citrus, and berries to Europe, which requires strict residue compliance. Flower growers in Kenya use beneficial insects and mites in their greenhouses. Saudi Arabia and the United Arab Emirates are investing in high-tech greenhouses and sustainable farming for food security. Key barriers include low farmer awareness, limited distribution networks, and high product costs. One opportunity is export-oriented horticulture that must meet European residue standards.
Competitive Landscape
The agricultural biologicals market is fragmented. Syngenta, UPL, Koppert, and BioFirst Group are leading players, while Novonesis is a major microbial supplier. BASF, Bayer, Corteva, FMC Corporation, Certis Biologicals, Bioceres Crop Solutions, and Rovensa also compete, along with many startups.
Companies compete on field performance, product range, shelf life, registrations, distribution, price, and agronomic support. Large agrochemical companies acquire specialists to gain new products, microbial libraries, and know-how. Specialist firms such as Koppert and BioFirst Group compete on deep expertise in greenhouse and horticulture crops. Startups bring new technologies, such as RNA-based products and engineered microbes, but often need partners for registration and distribution. Distributors and retailers play a key role in reaching farmers. Regional producers in India and Brazil compete strongly on price.
Strategic moves show how competition is changing. In February 2025, BASF pre-launched Votivo Prime in Argentina. In March 2025, Syngenta launched NETURE. In March 2026, BASF completed its acquisition of AgBiTech. These moves show competition shifting toward large row crops such as soybean and corn, where major agrochemical companies can use their scale, distribution networks, and farmer relationships to grow biological sales quickly.
Three themes shape vendor strategy. First, companies are buying specialist biological firms. Second, they are targeting large row crops. Third, they are combining biological and chemical products in integrated programs. Vendors that combine proven performance, broad registrations, and strong field support are best placed to win share.
Recent Industry Developments
- March 2026: BASF Agricultural Solutions completed its acquisition of AgBiTech, expanding its biological insect control offerings – strengthens biopesticides for row crops.
- March 2025: Syngenta launched NETURE, a biological insecticide for soybean and corn – expands biological use in row crops.
- February 2025: BASF pre-launched Votivo Prime, a biological nematicide, in Argentina – targets nematode control in large-acre crops.
- May 2024: Bioceres Crop Solutions received approval from Brazil’s Ministry of Agriculture for three bio-insecticidal and bio-nematicidal products – grows options in Latin America.
Companies Covered in the Report
- Syngenta
- UPL
- Koppert
- BioFirst Group
- Novonesis
- BASF
- Bayer
- Corteva Agriscience
- FMC Corporation
- Certis Biologicals
- Bioceres Crop Solutions
- Rovensa
Agricultural Biologicals Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 20.97 Billion |
| Market Size 2033 | US$ 51.51 Billion |
| CAGR 2026–2033 | 13.7% |
| Absolute Dollar Opportunity | US$ 30.54 Billion |
| Largest Market | North America |
| Fastest-Growing Market | Latin America |
| Market Concentration | Fragmented |
| Major Players | Syngenta, UPL, Koppert, BioFirst Group, Novonesis |
Agricultural Biologicals Market Segmentation
Type
- Biocontrol
- Biostimulants
- Biofertilizers
Source
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
Crop Type
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Agricultural Biologicals Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Regulatory Pressure Is Driving the Agricultural Biologicals Market
- Sustainability Demand Is Expanding the Agricultural Biologicals Market
- Restraints
- Variable Performance Slows the Agricultural Biologicals Market
- Shelf Life and Regulation Restrict the Agricultural Biologicals Market
- Market Opportunities
- Row Crops and Seed Treatments Open a Fast-Growth Revenue Pool
- Combination Programs and Digital Agronomy Create a Value Revenue Pool
- Drivers
- Global Agricultural Biologicals Market Outlook, 2020-2033
- Global Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- Global Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- Global Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- Global Agricultural Biologicals Market Outlook, by Region, Value (US$ Billion), 2020-2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- North America Agricultural Biologicals Market Outlook, 2020-2033
- North America Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- North America Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- North America Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- North America Agricultural Biologicals Market Outlook, by Country, Value (US$ Billion), 2020-2033
- United States Agricultural Biologicals Market Outlook, by Type, 2020-2033
- United States Agricultural Biologicals Market Outlook, by Source, 2020-2033
- United States Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Canada Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Canada Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Canada Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- North America Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Europe Agricultural Biologicals Market Outlook, 2020-2033
- Europe Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- Europe Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- Europe Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- Europe Agricultural Biologicals Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Spain Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Spain Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Spain Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Italy Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Italy Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Italy Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- France Agricultural Biologicals Market Outlook, by Type, 2020-2033
- France Agricultural Biologicals Market Outlook, by Source, 2020-2033
- France Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Netherlands Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Netherlands Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Netherlands Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Germany Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Germany Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Germany Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Belgium Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Belgium Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Belgium Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Europe Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Asia Pacific Agricultural Biologicals Market Outlook, 2020-2033
- Asia Pacific Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- Asia Pacific Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- Asia Pacific Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- Asia Pacific Agricultural Biologicals Market Outlook, by Country, Value (US$ Billion), 2020-2033
- India Agricultural Biologicals Market Outlook, by Type, 2020-2033
- India Agricultural Biologicals Market Outlook, by Source, 2020-2033
- India Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- China Agricultural Biologicals Market Outlook, by Type, 2020-2033
- China Agricultural Biologicals Market Outlook, by Source, 2020-2033
- China Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Australia Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Australia Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Australia Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Japan Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Japan Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Japan Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- South Korea Agricultural Biologicals Market Outlook, by Type, 2020-2033
- South Korea Agricultural Biologicals Market Outlook, by Source, 2020-2033
- South Korea Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Asia Pacific Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Latin America Agricultural Biologicals Market Outlook, 2020-2033
- Latin America Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- Latin America Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- Latin America Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- Latin America Agricultural Biologicals Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Brazil Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Brazil Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Brazil Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Argentina Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Argentina Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Argentina Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Mexico Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Mexico Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Mexico Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Latin America Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Middle East & Africa Agricultural Biologicals Market Outlook, 2020-2033
- Middle East & Africa Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Biocontrol
- Biostimulants
- Biofertilizers
- Middle East & Africa Agricultural Biologicals Market Outlook, by Source, Value (US$ Billion), 2020-2033
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
- Middle East & Africa Agricultural Biologicals Market Outlook, by Crop Type, Value (US$ Billion), 2020-2033
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
- Middle East & Africa Agricultural Biologicals Market Outlook, by Country, Value (US$ Billion), 2020-2033
- Morocco Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Morocco Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Morocco Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Kenya Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Kenya Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Kenya Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- South Africa Agricultural Biologicals Market Outlook, by Type, 2020-2033
- South Africa Agricultural Biologicals Market Outlook, by Source, 2020-2033
- South Africa Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Egypt Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Egypt Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Egypt Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Saudi Arabia Agricultural Biologicals Market Outlook, by Type, 2020-2033
- Saudi Arabia Agricultural Biologicals Market Outlook, by Source, 2020-2033
- Saudi Arabia Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- United Arab Emirates Agricultural Biologicals Market Outlook, by Type, 2020-2033
- United Arab Emirates Agricultural Biologicals Market Outlook, by Source, 2020-2033
- United Arab Emirates Agricultural Biologicals Market Outlook, by Crop Type, 2020-2033
- Middle East & Africa Agricultural Biologicals Market Outlook, by Type, Value (US$ Billion), 2020-2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Syngenta
- UPL
- Koppert
- BioFirst Group
- Novonesis
- BASF
- Bayer
- Corteva Agriscience
- FMC Corporation
- Certis Biologicals
- Bioceres Crop Solutions
- Rovensa
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Type
- Biocontrol
- Biostimulants
- Biofertilizers
Source
- Microbials
- Natural Products
- Macrobials
- Semiochemicals
Crop Type
- Fruits & Vegetables
- Cereals & Grains
- Oilseeds & Pulses
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The agricultural biologicals market is valued at US$ 20.97 billion in 2026, led by biocontrol and North America.
The market is projected to reach US$ 51.51 billion by 2033, growing at a 13.7% CAGR and adding US$ 30.54 billion.
Semiochemicals are growing fastest at a 16.0% CAGR through 2033, driven by pheromone-based mating disruption in orchards and vineyards.
Latin America is growing fastest at a 15.6% CAGR through 2033, driven by biological seed and soil treatments in Brazil and Argentina.
North America holds the largest share at 35.0% in 2026, supported by large specialty crops and fast biopesticide review.
Related Reports
Coconut Sugar Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the coconut sugar market outlook for 2026–2033, with organic sourcing, product formats, application trends, regional insights, and competition.
Baby Infant Formula Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the baby infant formula market outlook for 2026–2033, including product trends, ingredient bases, regional insights, and competitive analysis.
Margarine Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The margarine market is projected to grow from US$23.5 billion in 2026 to US$27.0 billion by 2033 at a 2.0% CAGR.
Low Fat Cheese Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global low fat cheese market is valued at US$6.8 billion in 2026, reaching US$9.2 billion by 2033, growing at a 4.4% CAGR
Instant Beverage Premix Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global instant beverage premix market is valued at US$24.0 billion in 2026, reaching US$36.5 billion by 2033, growing at a 6.2% CAGR
Infant Nutrition Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global infant nutrition market is valued at US$103.18 billion in 2026, reaching US$153.09 billion by 2033, growing at a 5.8% CAGR