


Biocompatible Materials Market
Biocompatible Materials Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
How Fast Is the Biocompatible Materials Market Growing?
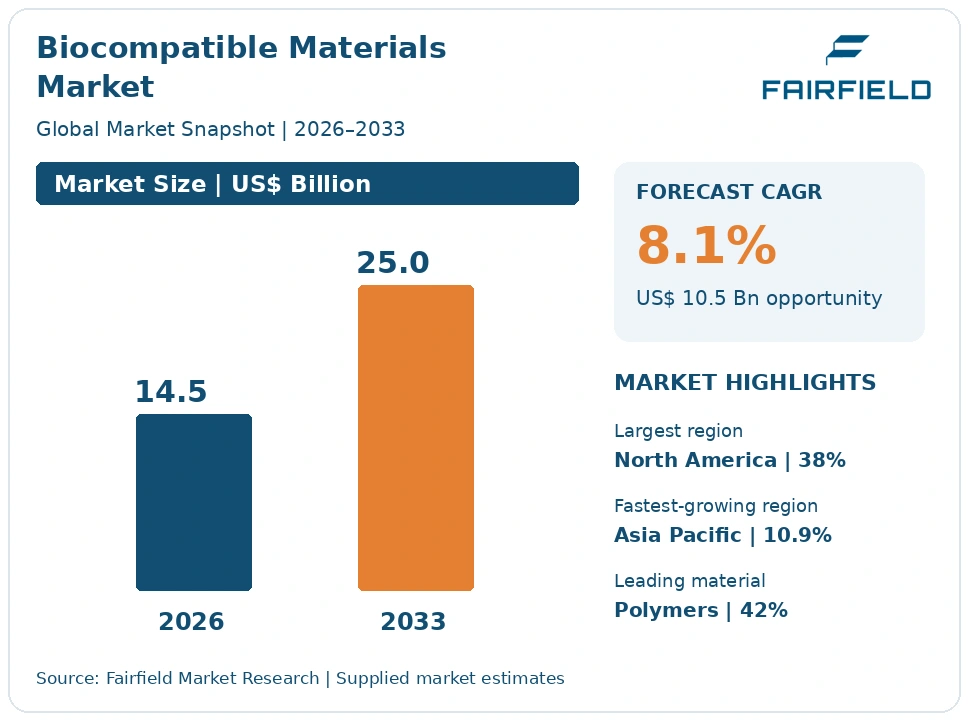
The global biocompatible materials market size is expected to be valued at US$ 14.5 billion in 2026 and projected to reach US$ 25.0 billion by 2033, growing at a CAGR of 8.1% between 2026 and 2033.
The market expanded at an estimated 7.2% CAGR between 2020 and 2025, ending that period near US$ 13.4 billion. Three factors explain the current trajectory. Implant and interventional procedure volumes continue to rise in ageing populations across Japan, Germany and the United States. Device manufacturers are specifying documented medical grades in place of industrial grades, which raises the value captured per kilogram. Tighter clinical evidence rules under the European Union Medical Device Regulation push producers toward suppliers that can furnish complete biological evaluation files. The direction is steady rather than explosive, because qualification timelines pace adoption more than material innovation does.
Key Report Takeaways
- By Material Type: Polymers held 42% share in 2026, while natural and biologic materials are projected to expand at a 10.4% CAGR through 2033, driven by demand for decellularised matrices and collagen scaffolds in soft tissue repair.
- By Application: Orthopaedics held 28% share in 2026, while drug delivery is projected to expand at a 10.8% CAGR through 2033, driven by long-acting injectable formulations that depend on resorbable polyester carriers.
- By Form: Resins and pellets held 38% share in 2026, while powders for additive manufacturing are projected to expand at a 12.1% CAGR through 2033, driven by patient-matched implant programmes qualifying printable titanium and PEEK grades.
- By End User: Medical device manufacturers held 64% share in 2026, while contract manufacturing organisations are projected to expand at a 10.6% CAGR through 2033, driven by outsourcing of implant machining and moulding by mid-sized device firms.
- By Geography: North America held 38% share in 2026, while Asia Pacific is projected to expand at a 10.9% CAGR through 2033, driven by domestic implant manufacturing in China, India and South Korea.
Global Biocompatible Materials Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the forecast growth in qualified medical-grade material volumes.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Rising implant and interventional procedure volumes in ageing populations | High | North America, Europe, Asia Pacific | Long term ≥4 years |
| Tighter biological evaluation and traceability expectations under device regulation | Medium | Europe, North America | Medium term 2–4 years |
Ageing Populations Lift Implant Volumes and Pull Qualified Material Through the Supply Chain
Procedure growth is the single largest source of demand for biocompatible materials. Joint reconstruction, spinal fusion, dental restoration and structural heart work all consume qualified polymer, metal and ceramic stock. Because each implant carries a fixed material content, rising case counts translate almost directly into kilograms shipped. Suppliers report the steadiest order books in titanium alloy bar, medical-grade silicone and UHMWPE.
The mechanism is demographic rather than technological. The share of people over 65 is rising fastest in Japan, Italy, Germany and South Korea, and these countries carry high per-capita implant rates. Reimbursement systems in those markets fund elective reconstruction, so volume follows demographics closely. Ambulatory surgery expansion in the United States has added capacity for lower-acuity cases, lifting consumption of polymer and ceramic components without requiring new hospital construction.
Documented Biological Evaluation Shifts Spending Toward Suppliers With Full Regulatory Files
Regulation is converting material selection into a documentation decision, and that raises realised prices for compliant suppliers. Device makers increasingly refuse grades that arrive without biological evaluation data, change-control commitments and long-term supply letters. The premium attached to a documented grade over a chemically identical industrial grade can be several multiples, and buyers accept it to protect submission timelines.
The cause is the evidence burden imposed by the ISO 10993 series and by the European Union Medical Device Regulation, which tightened clinical evidence and notified-body scrutiny. Risk management under ISO 14971 requires manufacturers to trace material characterisation into their files, while USP Class VI testing and the US Pharmacopeia plastics chapters remain common purchase conditions. Suppliers that maintain master files and formal change notification capture a growing share of qualified spend.
Restraints Impact Analysis
Two structural constraints hold the market below the growth rate that procedure volumes alone would imply.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Cost and duration of biological evaluation and material qualification | High | Global | Long term ≥4 years |
| Supplier withdrawal from small-volume implant programmes over liability exposure | Medium | North America, Europe | Medium term 2–4 years |
Multi-Year Qualification Timelines Keep New Biocompatible Grades Out of Production
Qualification length, not material performance, is the main brake on adoption. A new grade entering an implant programme typically needs chemical characterisation, a biological evaluation plan, process validation and design-freeze testing before any commercial shipment. Device makers therefore defer material changes until a platform redesign, which can leave an improved grade commercially idle for years after launch.
The cost sources are specific and unavoidable. Extractables and leachables studies, cytotoxicity, sensitisation and irritation testing, and implantation studies each carry laboratory fees and calendar time, and toxicological risk assessment under the ISO 10993 series must be repeated when a formulation or process changes. Sterilisation compatibility work adds another cycle. Because the burden falls on the device manufacturer rather than the material supplier, buyers resist switching even when a newer grade offers better processability or cost.
Liability Exposure Pushes Suppliers Away From Low-Volume Implant Applications
Supply access, not supply capacity, limits several niche implant categories. Chemical companies routinely decline permanent-implant applications because the revenue is small relative to the potential claim exposure, a pattern long visible in silicones, polyurethanes and certain fluoropolymers. Small device firms consequently struggle to secure contractual supply, and some redesign around less suitable but more available materials.
The underlying cause is the mismatch between order size and legal risk. An implant programme may consume only a few hundred kilograms each year, yet the supplier inherits reputational and litigation exposure tied to the finished device. Insurance for implant-grade supply is expensive and sometimes unavailable, and indemnity negotiations lengthen contracting. Specialist distributors and compounders have partly filled the gap by aggregating demand, but they add margin and another qualified node to the supply chain.
Market Opportunities
Two revenue pools sit outside the installed base of conventional implant materials.
Resorbable Polymers, Magnesium and Zinc Open a Replacement Pool in Fixation and Vascular Devices
Resorbable materials create a new revenue pool because they replace permanent hardware rather than compete on price. Resorbable polyesters such as PLA and PLGA, together with magnesium and zinc alloys, are being qualified for fixation screws, anchors, barrier membranes and vascular scaffolds. Price per kilogram is far above commodity implant stock, and the grades carry heavy documentation value.
Material suppliers with fermentation-derived polymer capacity and specialist alloy producers are positioned to capture this pool. The demand comes from orthopaedic trauma, sports medicine, dental and paediatric device programmes, where device removal is a cost and workflow issue for providers. Published consensus standards from the ASTM F04 committee on degradable materials have made qualification paths clearer, and that clarity is what converts laboratory interest into purchase orders for qualified lots.
Additive-Manufacturing-Ready Powders and Antimicrobial Surfaces Create a Premium Grade Tier
Printable powders and functional surface treatments form a second pool with distinctly higher margins. Patient-matched and porous-structure implants require tightly controlled titanium, cobalt-chromium and tantalum powders with validated particle size distribution and reuse limits, and printable PEEK filaments are entering the same tier. Antimicrobial and osteoconductive coatings based on hydroxyapatite, bioactive glass and silver chemistries extend the premium further.
Powder producers, atomisation specialists and coating service providers can capture this revenue, often alongside the device maker rather than through it. Demand originates in spinal, craniomaxillofacial, orthopaedic trauma and dental programmes where implant geometry is patient-specific and conventional machining is uneconomic. Qualification remains demanding, since powder reuse limits and surface chemistry must be documented under the ISO 10993 series and characterised against ASTM F04 committee standards, but the per-kilogram economics justify the work for suppliers able to support it.
Segment Analysis
By Material Type: Polymers Lead While Natural and Biologic Materials Gain Momentum
Polymers held 42% of biocompatible material revenue in 2026, the largest share of any material class. The position reflects breadth: medical-grade silicone, PEEK and other high-performance thermoplastics, UHMWPE, polyurethanes, resorbable polyesters and hydrogels appear across nearly every device category, from catheters to bearing surfaces. Polymers also dominate disposable and single-use components, which recur annually rather than once per implant.
Natural and biologic materials are the fastest-growing class at a 10.4% CAGR through 2033. Collagen, chitosan, alginate and decellularised matrices are being qualified for wound care, dural repair, hernia reinforcement and tissue engineering scaffolds, and they command high prices per unit mass. Metals remain essential in load-bearing implants, while alumina, zirconia, hydroxyapatite and bioactive glass hold durable positions in dental and bearing applications. For suppliers, the implication is that growth and volume now sit in different material classes.
By Application: Orthopaedics Holds the Largest Share as Drug Delivery Expands Fastest
Orthopaedics accounted for 28% of material demand in 2026, more than any other application. Joint reconstruction, trauma fixation and spinal devices consume heavy mass per procedure, especially in titanium alloy, cobalt-chromium and UHMWPE, so the segment leads on tonnage as well as value. Established reimbursement and high procedure counts keep the base stable.
Drug delivery is expanding fastest at a 10.8% CAGR through 2033. Long-acting injectable and implantable formulations rely on resorbable polyester carriers, and pharmaceutical developers qualify these polymers under pharmacopeial and biological evaluation requirements rather than conventional device rules. Cardiovascular, dental, ophthalmic, wound care and neurology applications fill the remainder, each with distinct material preferences. The practical implication is that suppliers increasingly serve pharmaceutical customers with device-grade documentation, which changes account management and contract structures.
By Form: Resins and Pellets Dominate Supply While Printable Powders Scale Quickest
Resins and pellets represented 38% of shipments in 2026, the leading form in which biocompatible materials reach device manufacturers. Moulding and extrusion remain the dominant conversion routes for polymer components, and pelletised supply simplifies lot traceability and change control. Films, sheets, fibres, textiles and bar stock make up most of the remaining conventional supply.
Powders for additive manufacturing are growing fastest at a 12.1% CAGR through 2033, from a small base. Patient-matched implants, porous lattices and craniomaxillofacial plates require qualified metal powders with documented reuse limits, and printable polymer feedstocks are following. Coatings and surface treatments form a smaller but high-value form category. The business implication is that form, not chemistry, increasingly determines margin, because powders and coatings carry qualification obligations that commodity pellet supply does not.
By End User: Device Manufacturers Buy Most Volume While Contract Manufacturers Grow Faster
Medical device manufacturers purchased 64% of biocompatible materials in 2026, reflecting their ownership of design files and regulatory submissions. These buyers specify grades, hold the biological evaluation documentation and sign long-term supply agreements, so they anchor supplier relationships and pricing.
Contract manufacturing organisations are the fastest-growing buyer group at a 10.6% CAGR through 2033. Mid-sized device firms are outsourcing implant machining, moulding and finishing to conserve capital, and contract manufacturers increasingly buy qualified stock directly against customer-approved specifications. Research institutes and tissue engineering companies form a small but strategically useful segment, because early-stage programmes often determine which grade enters a future product. The implication for suppliers is a widening customer base with uneven technical literacy, which raises the value of applications support and documentation packages.
Geography Analysis
Which Region Is Leading the Biocompatible Materials Market?
North America leads the biocompatible materials market with a 38% share in 2026, supported by the largest concentration of implant manufacturers and the highest per-capita procedure rates. The United States accounts for most regional demand, with clusters in Indiana, Minnesota, Massachusetts and Tennessee that buy qualified polymer, alloy and ceramic stock in volume. Canada contributes through orthopaedic and dental manufacturing.
Three causes underpin the position. Device makers headquartered in the region set global material specifications, so qualification decisions made there propagate worldwide. The US Food and Drug Administration recognises consensus standards including the ISO 10993 series, which gives suppliers a predictable evidence route. Ambulatory surgery growth has added procedure capacity. The main change ahead is reshoring of critical component supply, which is drawing new compounding and powder capacity closer to device assembly sites.
Europe Converts Regulatory Rigor Into Supplier Advantage in Implant Materials
Europe held 28% of biocompatible material revenue in 2026, anchored by Germany, Switzerland, Ireland, France and the United Kingdom. The region hosts several of the largest specialty polymer, silicone and technical ceramic producers serving implant programmes, and it exports qualified material worldwide.
Regulation shapes demand more here than anywhere else. The Medical Device Regulation tightened clinical evidence and notified-body requirements, and its provisions on carcinogenic, mutagenic and reprotoxic substances and on endocrine disruptors in invasive devices have forced reformulation work. REACH and the restriction of certain phthalates removed established plasticiser options. The proposed restriction on per- and polyfluoroalkyl substances is the most consequential open question, because fluoropolymers are widely used in device components and no drop-in substitute exists. Suppliers with substitution programmes and complete files are gaining qualified positions.
Which Region Is Growing Fastest in the Biocompatible Materials Market?
Asia Pacific is growing fastest in the biocompatible materials market at a 10.9% CAGR between 2026 and 2033, from a 23% base share in 2026. China, India, South Korea and Japan drive the expansion, with Australia adding specialist demand.
The causes are industrial as much as clinical. Domestic implant manufacturing has scaled sharply in China and India, and volume-based procurement has pushed device makers to localise component and material sourcing. Japan and South Korea contribute high-specification demand in dental, ophthalmic and interventional devices. Regional producers of titanium, zirconia and medical-grade polymers are investing in documentation capability to serve exporters. The opportunity is qualification support: local device firms entering European Union and United States markets need suppliers who can supply evidence packages, not only material.
Latin America Builds Implant Material Demand Against Import and Currency Constraints
Latin America accounted for 6% of the market in 2026, with Brazil and Mexico supplying most demand. Mexico is the more important manufacturing base, because its northern border device clusters assemble catheters, orthopaedic components and disposables for export. Brazil demand is driven chiefly by domestic procedure volumes and local implant producers.
Barriers are real. Import dependence for qualified material exposes buyers to currency movements and extended lead times, and customs documentation for controlled medical grades adds delay. Registration processes administered by national health authorities can lengthen product introduction, and smaller device firms lack the scale to hold qualified inventory. The change worth watching is the maturing contract manufacturing base in Mexico, which concentrates purchasing and makes direct supply agreements with material producers commercially viable.
Middle East & Africa Expands From a Small Base as Local Device Assembly Begins
Middle East & Africa represented 5% of global demand in 2026, the smallest regional share. Saudi Arabia, the United Arab Emirates, Israel and South Africa account for most activity, with Israel contributing a disproportionate share through its medical device development sector.
Growth is constrained by limited local conversion capacity, so most qualified material arrives embedded in finished devices rather than as raw stock. Fragmented regulatory frameworks across African markets raise the cost of serving them, and procurement is often tender-driven and price-sensitive. Skilled polymer and metallurgical processing capacity is scarce outside a few centres. The shaping change is industrial policy in the Gulf Cooperation Council states, where healthcare localisation programmes are funding device assembly and sterilisation capacity that will, over time, create direct demand for qualified biocompatible material.
Competitive Landscape
The biocompatible materials market is moderately concentrated, with a medium concentration profile that differs sharply by material class. Specialty polymers are the most concentrated tier, because only a handful of producers maintain implant-grade silicone, PEEK and resorbable polyester lines with full regulatory support. Medical alloys and technical ceramics are somewhat more fragmented, with regional mills and ceramic specialists holding defensible positions. Consolidation has been steady rather than dramatic, usually taking the form of large chemical groups acquiring niche medical-grade specialists to obtain qualified customer positions rather than capacity.
Competition rests on qualification support more than on material properties. Buyers evaluate suppliers on the completeness of biological evaluation data, master file access, change-notification discipline, lot traceability and guaranteed supply duration. Because a formulation or process change can force a device maker to repeat testing, change control is itself a product feature. Price matters mainly at the point of initial qualification; afterwards switching costs dominate and incumbents retain the position. New entrants are appearing in metal powders for additive manufacturing, in bioresorbable polymers and in coating services, where qualification paths are newer and incumbency is weaker.
Strategic activity concentrates on capability rather than scale. Suppliers are extending applications laboratories, building regulatory affairs teams that work directly with device customers, and widening documentation packages to cover additive processes and surface treatments. Several have pursued backward integration into monomer or alloy feedstock to protect supply continuity commitments.
Strategic direction across the field is converging on three themes: substitution planning ahead of restrictions on fluorinated chemistries and plasticisers, documentation depth as a commercial differentiator, and selective participation in implant applications where liability exposure is manageable. Vendors are also investing in supply-chain transparency, since device customers now audit upstream feedstock as part of their own risk management obligations.
Biocompatible Materials Industry Leaders
- Evonik Industries AG
- Celanese Corporation
- Solvay S.A.
- Victrex plc
- Carpenter Technology Corporation
Recent Industry Developments
July 2020: The restriction on four phthalates under REACH became applicable in the European Union, removing established plasticiser options from polymer formulations used in medical applications – this forced early reformulation work across flexible device materials.
May 2021: The European Union Medical Device Regulation became fully applicable, tightening clinical evidence and notified-body requirements – material suppliers with complete biological evaluation files gained a qualification advantage over those without.
February 2023: The European Chemicals Agency published a proposal from five national authorities to restrict per- and polyfluoroalkyl substances, opening a six-month consultation – this is the most significant open threat to fluoropolymer use in medical devices.
March 2023: The European Union adopted an amending regulation extending the transitional periods of the Medical Device Regulation – the extension eased certificate expiry pressure and slowed, without removing, the reformulation timetable for legacy device materials.
Biocompatible Materials Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 14.5 Billion |
| Market Size 2033 | US$ 25.0 Billion |
| CAGR 2026–2033 | 8.1% |
| Absolute Dollar Opportunity | US$ 10.5 Billion |
| Largest Market | North America — 38% share in 2026 |
| Fastest-Growing Market | Asia Pacific — 10.9% CAGR |
| Market Concentration | Medium |
| Major Players | Evonik Industries AG, Celanese Corporation, Solvay S.A., Victrex plc, Carpenter Technology Corporation |
This report sizes sales of materials qualified for contact with living tissue to medical device manufacturers, covering polymers, metals, ceramics and natural or biologic materials used in devices, implants, drug delivery and tissue engineering. Finished devices are excluded, since that market is far larger. The base year is 2025, the forecast period runs from 2026 to 2033, and all values are reported in US$ Billion.
Biocompatible Materials Market Segmentation
Material Type
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
Application
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
Form
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
End User
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Biocompatible Materials Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Ageing Populations Lift Implant Volumes and Pull Qualified Material Through the Supply Chain
- Documented Biological Evaluation Shifts Spending Toward Suppliers With Full Regulatory Files
- Restraints
- Multi-Year Qualification Timelines Keep New Biocompatible Grades Out of Production
- Liability Exposure Pushes Suppliers Away From Low-Volume Implant Applications
- Market Opportunities
- Resorbable Polymers, Magnesium and Zinc Open a Replacement Pool in Fixation and Vascular Devices
- Additive-Manufacturing-Ready Powders and Antimicrobial Surfaces Create a Premium Grade Tier
- Drivers
- Global Biocompatible Materials Market Outlook, 2020–2033
- Global Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- Global Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- Global Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- Global Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- Global Biocompatible Materials Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- North America Biocompatible Materials Market Outlook, 2020–2033
- North America Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- North America Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- North America Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- North America Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- North America Biocompatible Materials Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- United States Biocompatible Materials Market Outlook, by Application, 2020–2033
- United States Biocompatible Materials Market Outlook, by Form, 2020–2033
- United States Biocompatible Materials Market Outlook, by End User, 2020–2033
- Canada Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Canada Biocompatible Materials Market Outlook, by Application, 2020–2033
- Canada Biocompatible Materials Market Outlook, by Form, 2020–2033
- Canada Biocompatible Materials Market Outlook, by End User, 2020–2033
- North America Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Europe Biocompatible Materials Market Outlook, 2020–2033
- Europe Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- Europe Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- Europe Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- Europe Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- Europe Biocompatible Materials Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Germany Biocompatible Materials Market Outlook, by Application, 2020–2033
- Germany Biocompatible Materials Market Outlook, by Form, 2020–2033
- Germany Biocompatible Materials Market Outlook, by End User, 2020–2033
- Switzerland Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Switzerland Biocompatible Materials Market Outlook, by Application, 2020–2033
- Switzerland Biocompatible Materials Market Outlook, by Form, 2020–2033
- Switzerland Biocompatible Materials Market Outlook, by End User, 2020–2033
- Ireland Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Ireland Biocompatible Materials Market Outlook, by Application, 2020–2033
- Ireland Biocompatible Materials Market Outlook, by Form, 2020–2033
- Ireland Biocompatible Materials Market Outlook, by End User, 2020–2033
- France Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- France Biocompatible Materials Market Outlook, by Application, 2020–2033
- France Biocompatible Materials Market Outlook, by Form, 2020–2033
- France Biocompatible Materials Market Outlook, by End User, 2020–2033
- United Kingdom Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- United Kingdom Biocompatible Materials Market Outlook, by Application, 2020–2033
- United Kingdom Biocompatible Materials Market Outlook, by Form, 2020–2033
- United Kingdom Biocompatible Materials Market Outlook, by End User, 2020–2033
- Europe Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Asia Pacific Biocompatible Materials Market Outlook, 2020–2033
- Asia Pacific Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- Asia Pacific Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- Asia Pacific Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- Asia Pacific Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- Asia Pacific Biocompatible Materials Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- China Biocompatible Materials Market Outlook, by Application, 2020–2033
- China Biocompatible Materials Market Outlook, by Form, 2020–2033
- China Biocompatible Materials Market Outlook, by End User, 2020–2033
- India Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- India Biocompatible Materials Market Outlook, by Application, 2020–2033
- India Biocompatible Materials Market Outlook, by Form, 2020–2033
- India Biocompatible Materials Market Outlook, by End User, 2020–2033
- South Korea Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- South Korea Biocompatible Materials Market Outlook, by Application, 2020–2033
- South Korea Biocompatible Materials Market Outlook, by Form, 2020–2033
- South Korea Biocompatible Materials Market Outlook, by End User, 2020–2033
- Japan Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Japan Biocompatible Materials Market Outlook, by Application, 2020–2033
- Japan Biocompatible Materials Market Outlook, by Form, 2020–2033
- Japan Biocompatible Materials Market Outlook, by End User, 2020–2033
- Australia Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Australia Biocompatible Materials Market Outlook, by Application, 2020–2033
- Australia Biocompatible Materials Market Outlook, by Form, 2020–2033
- Australia Biocompatible Materials Market Outlook, by End User, 2020–2033
- Asia Pacific Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Latin America Biocompatible Materials Market Outlook, 2020–2033
- Latin America Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- Latin America Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- Latin America Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- Latin America Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- Latin America Biocompatible Materials Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Brazil Biocompatible Materials Market Outlook, by Application, 2020–2033
- Brazil Biocompatible Materials Market Outlook, by Form, 2020–2033
- Brazil Biocompatible Materials Market Outlook, by End User, 2020–2033
- Mexico Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Mexico Biocompatible Materials Market Outlook, by Application, 2020–2033
- Mexico Biocompatible Materials Market Outlook, by Form, 2020–2033
- Mexico Biocompatible Materials Market Outlook, by End User, 2020–2033
- Latin America Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Middle East & Africa Biocompatible Materials Market Outlook, 2020–2033
- Middle East & Africa Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
- Middle East & Africa Biocompatible Materials Market Outlook, by Application, Value (US$ Billion), 2020–2033
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
- Middle East & Africa Biocompatible Materials Market Outlook, by Form, Value (US$ Billion), 2020–2033
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
- Middle East & Africa Biocompatible Materials Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
- Middle East & Africa Biocompatible Materials Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Saudi Arabia Biocompatible Materials Market Outlook, by Application, 2020–2033
- Saudi Arabia Biocompatible Materials Market Outlook, by Form, 2020–2033
- Saudi Arabia Biocompatible Materials Market Outlook, by End User, 2020–2033
- United Arab Emirates Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- United Arab Emirates Biocompatible Materials Market Outlook, by Application, 2020–2033
- United Arab Emirates Biocompatible Materials Market Outlook, by Form, 2020–2033
- United Arab Emirates Biocompatible Materials Market Outlook, by End User, 2020–2033
- Israel Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- Israel Biocompatible Materials Market Outlook, by Application, 2020–2033
- Israel Biocompatible Materials Market Outlook, by Form, 2020–2033
- Israel Biocompatible Materials Market Outlook, by End User, 2020–2033
- South Africa Biocompatible Materials Market Outlook, by Material Type, 2020–2033
- South Africa Biocompatible Materials Market Outlook, by Application, 2020–2033
- South Africa Biocompatible Materials Market Outlook, by Form, 2020–2033
- South Africa Biocompatible Materials Market Outlook, by End User, 2020–2033
- Middle East & Africa Biocompatible Materials Market Outlook, by Material Type, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Evonik Industries AG
- Celanese Corporation
- Solvay S.A.
- Victrex plc
- Covestro AG
- BASF SE
- Dow Inc.
- Wacker Chemie AG
- Elkem ASA
- Corbion N.V.
- Carpenter Technology Corporation
- ATI Inc.
- CeramTec GmbH
- CoorsTek, Inc.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Material Type
- Polymers
- Metals
- Ceramics
- Natural and Biologic Materials
Application
- Orthopaedics
- Cardiovascular
- Dental
- Ophthalmic
- Wound Care
- Neurology
- Drug Delivery
Form
- Resins and Pellets
- Films and Sheets
- Fibres and Textiles
- Powders for Additive Manufacturing
- Coatings and Surface Treatments
End User
- Medical Device Manufacturers
- Contract Manufacturing Organisations
- Research and Academic Institutes
- Tissue Engineering Companies
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The market is valued at US$ 14.5 billion in 2026, measured as sales of qualified medical-grade materials to device manufacturers rather than finished devices.
The market is projected to reach US$ 25.0 billion by 2033, growing at an 8.1% CAGR and adding US$ 10.5 billion over the forecast period.
Polymers lead with 42% share in 2026, because medical-grade silicone, PEEK, UHMWPE and polyurethanes appear across almost every device category.
Powders for additive manufacturing grow fastest at a 12.1% CAGR, ahead of natural and biologic materials at 10.4% and drug delivery applications at 10.8%.
North America holds 38% share in 2026, while Asia Pacific grows fastest at a 10.9% CAGR on domestic implant manufacturing in China and India.
Related Reports
Immune Checkpoint Inhibitors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global immune checkpoint inhibitors market is valued at US$52.0 billion in 2026, reaching US$68.0 billion by 2033, growing at a 3.91% CAGR
Geriatric Medicines Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global geriatric medicines market is valued at US$412.0 billion in 2026, reaching US$538.0 billion by 2033, growing at a 3.9% CAGR
Pharmaceutical Temperature Controlled Packaging Solutions Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pharmaceutical temperature controlled packaging solutions market to grow from US$ 6.86 billion in 2026 to US$ 13.98 billion by 2033 at a 10.7% CAGR.
Dermatology CRO Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the dermatology CRO market, projected to reach US$ 9.7 billion by 2033 at a 6.6% CAGR, with service, indication and regional insights.
Acetaminophen Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acetaminophen market is valued at US$11.70 billion in 2026, reaching US$15.93 billion by 2033, growing at a 4.5% CAGR
Allergy Diagnostics and Therapeutics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global allergy diagnostics and therapeutics market is valued at US$41.50 billion in 2026, reaching US$88.30 billion by 2033, growing at an 11.4% CAGR