


Gas Sensors Market
Gas Sensors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Gas Sensors Market Size and Trend Analysis
How Fast Will the Gas Sensors Market Grow?
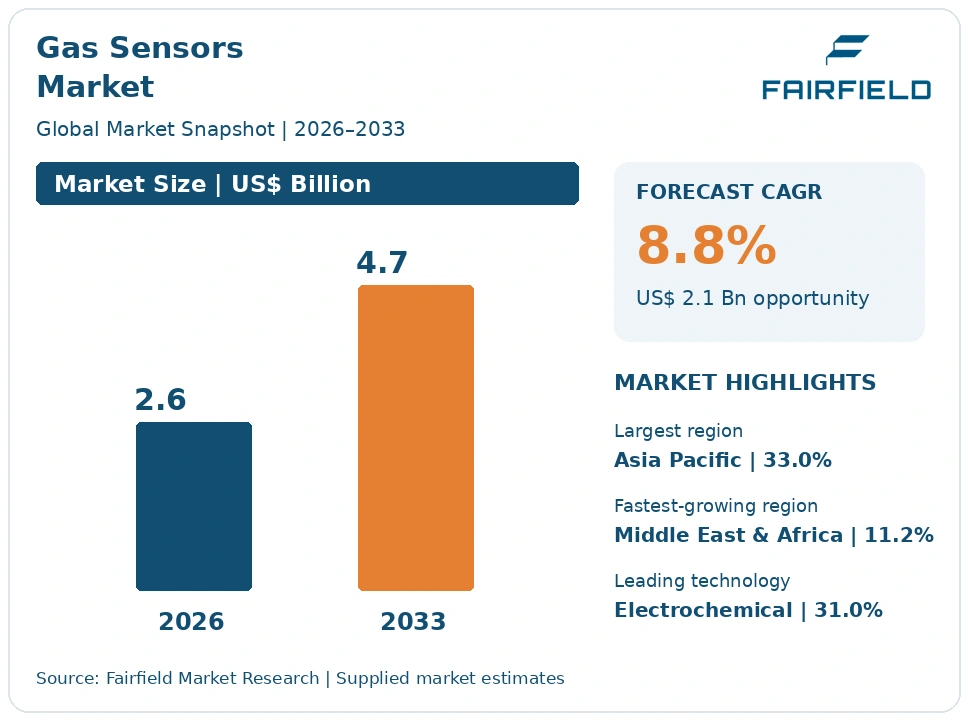
The global Gas Sensors market size is expected to be valued at US$ 2.6 billion in 2026 and projected to reach US$ 4.7 billion by 2033, growing at a CAGR of 8.8% between 2026 and 2033.
Sensing element and module revenue grew at close to a 7.5% CAGR between 2020 and 2025, with indoor air quality demand rising sharply after the pandemic and then settling. Three factors set the forward path. Leak-detection duties under fluorinated gas and methane rules create a recurring installed base of fixed sensing points at operating sites. Tighter ambient air quality limits are expanding reference and supplementary monitoring networks across cities. Hydrogen production, storage and refuelling infrastructure introduces a gas that needs dedicated detection wherever it is handled. Growth is steady and regulation-led rather than cyclical, because most demand follows compliance deadlines.
Key Report Takeaways
- By Sensor Technology: Electrochemical sensors held 31.0% share in 2026, while MEMS Gas Sensors are projected to expand at a 13.6% CAGR through 2033, as wafer-scale production brings module prices down to consumer device budgets.
- By Gas Type: Combustible Gases held 24.0% share in 2026, while Hydrogen sensing is projected to grow at a 16.2% CAGR through 2033, following electrolyser, storage and refuelling infrastructure build-out.
- By Configuration: Fixed installations held 58.0% share in 2026, while Wearable sensors are projected to grow at a 12.8% CAGR through 2033, driven by confined-space entry procedures and lone-worker monitoring rules.
- By End-Use Industry: Industrial Safety and Gas Detection held 29.0% share in 2026, while Building HVAC and Indoor Air Quality is projected to grow at an 11.8% CAGR through 2033, supported by ventilation standards and carbon dioxide-based demand control.
- By Geography: Asia Pacific held 33.0% share in 2026, while Middle East & Africa is projected to grow at an 11.2% CAGR through 2033, led by hydrocarbon processing and new hydrogen projects.
Global Gas Sensors Market Trends and Insights
Drivers Impact Analysis
Two regulatory forces account for most incremental demand for gas detection sensors through 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Mandatory leak detection under fluorinated gas and methane rules | High | Europe, North America, Middle East & Africa | Medium term (2–4 years) |
| Tighter ambient air quality limits and ventilation standards expanding monitoring points | High | Europe, Asia Pacific, North America | Long term (≥4 years) |
Refrigerant and Methane Leak Rules Create a Permanent Installed Base of Fixed Sensing Points
Leak-detection mandates convert gas sensing from an optional safeguard into a condition of operation, which is why they dominate demand growth. The EU F-gas Regulation, Regulation (EU) 2024/573, requires leak checks on equipment containing fluorinated greenhouse gases and permits reduced check frequency where a fixed detection system is installed. Methane rules in the European Union and the United States impose survey and repair obligations on oil, gas and coal operators, creating steady demand for both fixed and survey-grade sensing.
The mechanism is economic as much as legal. Operators install permanent detection because it lowers inspection labour, documents compliance automatically and reduces the quantity of reportable release. Supermarkets, cold stores, data centres and industrial chillers fit refrigerant sensing to protect charge value as well as to satisfy inspectors. Each installed point then carries a replacement and calibration cycle, which gives suppliers recurring volume rather than a single sale.
Tightening Air Quality Limits and Ventilation Standards Multiply Monitoring Points
Air quality regulation is expanding the number of locations where gases must be measured, both outdoors and inside buildings. The recast EU Ambient Air Quality Directive tightens limit values and strengthens monitoring obligations, which obliges authorities to extend networks and supplement reference stations with denser supplementary measurement. Building ventilation standards including ASHRAE 62.1 underpin demand-controlled ventilation, where carbon dioxide measurement sets fan speed and outdoor air intake.
The causal chain runs from limit value to measurement obligation to procurement. Tighter numerical limits reduce the margin authorities have before exceedance, so they need more measurement locations to show compliance and to target action. In buildings, energy codes push operators to cut ventilation when spaces are empty, which is only permissible with reliable occupancy-linked air quality sensing. Both effects favour non-dispersive infrared modules for carbon dioxide and electrochemical cells for nitrogen dioxide.
Restraints Impact Analysis
Both constraints concern measurement integrity over time, which is the hardest attribute for this product class to guarantee.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Cross-sensitivity and baseline drift requiring scheduled recalibration | High | Global | Long term (≥4 years) |
| Limited electrochemical cell life and the credibility gap against reference-grade instruments | Medium | Europe, North America, Asia Pacific | Medium term (2–4 years) |
Cross-Sensitivity and Drift Force Recalibration That Raises Lifetime Cost of Ownership
Measurement reliability over time, not initial accuracy, is the main obstacle to wider deployment. Most sensing principles respond to gases other than the target: electrochemical cells for carbon monoxide react to hydrogen, catalytic beads respond to any combustible, and metal oxide elements shift with humidity and temperature. Baselines drift as electrolytes deplete and catalytic surfaces age, so a reading that was correct at commissioning will not stay correct without intervention.
The cost source is the calibration regime rather than the sensor price. Fixed installations require periodic bump testing with certified gas and full span calibration on a documented schedule, each visit consuming technician time, calibration gas cylinders and site access permits. In hazardous areas, that access needs permits and sometimes shutdown. Over a typical service life, calibration and replacement labour comfortably exceeds the purchase price of the sensing element.
Limited Sensor Life and Weak Credibility Against Reference Instruments Cap Low-Cost Deployments
Short service life and unproven data quality together restrict where inexpensive sensing can be used. Electrochemical cells consume their own electrolyte and electrode material whether or not gas is present, giving most types a useful life of two to three years and shorter in hot or dry conditions. Replacement is then a scheduled operating cost, which weakens the economics of very large distributed networks.
Credibility is the second limit. Regulators accept reference-grade analysers for compliance measurement, and low-cost modules are generally admitted only as supplementary or indicative data. Field studies repeatedly show divergence between inexpensive modules and reference instruments once humidity, temperature and interfering gases vary, so network operators must add co-location, correction models and ongoing quality assurance. Those overheads erode the cost advantage that made dense deployment attractive.
Market Opportunities
Hydrogen Infrastructure Creates a New Certified Detection Installed Base
Hydrogen handling opens a sensing pool that barely existed at industrial scale a decade ago. Electrolyser halls, compression and storage yards, refuelling stations, blended gas networks and fuel cell installations all need detection, because hydrogen is odourless, ignites across a very wide concentration range and disperses quickly. ISO 26142 addresses performance requirements for hydrogen detection apparatus, and equipment for explosive atmospheres must satisfy the IEC 60079 series and the ATEX directives in the European Union.
Sensor suppliers with certified product and fast response characteristics are positioned to capture this demand. The buyers are industrial gas producers, energy utilities building electrolyser capacity, vehicle refuelling operators and equipment makers integrating fuel cells. Certification is the entry barrier and the commercial protection, because approval against hazardous-area and hydrogen-specific requirements takes time and testing cost that casual entrants will not absorb.
Low-Cost MEMS Modules Open a Volume Design-In Pool in Buildings and Consumer Devices
Miniaturised sensing modules create a unit-volume opportunity that traditional industrial sensors cannot address. Wafer-scale manufacture brings module cost low enough for thermostats, air purifiers, ventilation units, range hoods, vehicle cabins and portable monitors, where the sensor is one component inside a product rather than a standalone instrument. Volumes in these applications run orders of magnitude above fixed industrial detection, even though revenue per unit is far smaller.
Semiconductor-process sensor makers and component suppliers with consumer-grade supply chains are best placed to serve it. Demand comes from heating and ventilation equipment manufacturers, appliance brands and vehicle interior suppliers responding to indoor air quality expectations and ventilation efficiency rules. Integration of compensation algorithms onto the module itself is the enabling development, because it lets a device maker add air quality sensing without employing measurement specialists.
Segment Analysis
By Sensor Technology: Electrochemical Cells Hold the Largest Share While MEMS Devices Advance Fastest
Electrochemical sensors held 31.0% of market value in 2026, the leading technology, because they combine low power draw with good selectivity for toxic gases such as carbon monoxide, hydrogen sulphide, oxygen deficiency and nitrogen dioxide. They dominate portable and wearable safety detection. Infrared sensing, including non-dispersive and photoacoustic types, is the second largest and is preferred for carbon dioxide, hydrocarbons and refrigerants because it does not poison or deplete.
MEMS Gas Sensors are the fastest-growing technology at a 13.6% CAGR through 2033. Wafer-scale fabrication, millimetre-scale packages and integrated compensation make them viable inside consumer and building equipment where conventional cells are too large or costly. Catalytic bead, photoionisation and thermal conductivity sensors retain defensible niches in flammable gas, volatile organic compound and high-concentration measurement. The implication is a widening split between certified safety products and high-volume commodity modules.
By Gas Type: Combustible Gas Detection Leads as Hydrogen Sensing Grows Fastest
Combustible Gases accounted for 24.0% of demand in 2026, the largest category, reflecting the universal requirement to detect methane, propane and solvent vapours wherever fuels are processed, stored or burned. Carbon Monoxide and Oxygen follow, driven by confined space entry and domestic safety requirements. Carbon Dioxide holds a substantial share through demand-controlled ventilation and refrigeration leak monitoring.
Hydrogen is the fastest-growing gas type at a 16.2% CAGR to 2033, from a small base. Electrolysers, storage installations, refuelling stations and blended gas distribution each require detection, and the gas is difficult to detect by smell or sight. Refrigerant sensing is also expanding as flammable low global warming potential blends replace older fluids. For suppliers, these shifts reward certified and gas-specific product portfolios over general-purpose catalogues.
By Configuration: Fixed Installations Dominate Revenue While Wearables Expand Quickest
Fixed sensing represented 58.0% of market value in 2026, the leading configuration, because plant-wide detection systems in refineries, chemical sites, water treatment works, car parks and plant rooms run continuously and use many points per site. These installations also carry the highest certification requirements and the most consistent replacement cycle. Portable instruments hold the second position, used for pre-entry checks, leak surveys and maintenance work.
Wearable sensing is growing fastest at a 12.8% CAGR through 2033. Confined space entry procedures, lone-worker monitoring policies and connected safety programmes that log exposure have moved personal detection from discretionary to standard issue in several industries. Connectivity is the differentiator, since employers want exposure records and real-time alarm escalation. The commercial effect is that sensor makers must supply small, low-power elements able to survive daily handling.
By End-Use Industry: Industrial Safety Buys the Most While Building Air Quality Grows Fastest
Industrial Safety and Gas Detection accounted for 29.0% of demand in 2026, the largest end use, covering chemical plants, water treatment, mining, utilities and manufacturing sites where detection is a statutory duty. Oil and Gas is the second largest, with upstream, midstream and refining sites operating dense fixed networks and extensive survey programmes. Environmental monitoring, automotive and medical applications follow.
Building HVAC and Indoor Air Quality is the fastest-growing end use at an 11.8% CAGR to 2033. Ventilation standards, energy codes that reward demand-controlled air supply, and occupant expectations after the pandemic have put carbon dioxide and volatile organic compound sensing into offices, schools and residential units. Volumes here are large and prices low. The consequence is a market where two business models coexist: certified low-volume safety sensing and high-volume embedded modules.
Geography Analysis
North America Anchors Gas Sensor Demand in Oil and Gas Operations and Worker Safety Rules
North America held 27.0% of global sensing element revenue in 2026 and is forecast to grow at an 8.2% CAGR through 2033. The United States drives the position through the scale of its upstream and midstream hydrocarbon operations, where methane survey and repair obligations have added a continuing workload of leak detection across wellpads, compressor stations and processing plants. Refining and petrochemical sites operate large fixed detection networks.
Workplace safety enforcement supports a second demand layer, with confined space entry, hydrogen sulphide exposure limits and respiratory protection requirements keeping portable and wearable instruments in constant replacement. Canada adds oil sands, mining and cold-climate building ventilation demand, while Mexico contributes refining and industrial manufacturing. The change worth noting is the spread of continuous optical and point-sensing monitoring in place of periodic manual survey work at larger facilities.
Europe Sets Gas Sensor Specification Through Explosive Atmosphere and Refrigerant Rules
Europe accounted for 26.0% of the market in 2026 and is forecast to grow at an 8.0% CAGR through 2033. Regulation determines product specification here more than price does. Equipment for use in potentially explosive atmospheres must meet the IEC 60079 series and the ATEX directives, and gas detection apparatus using software is assessed against EN 50271, which effectively sets a software quality threshold for every certified product sold.
The EU F-gas Regulation sustains refrigerant detection demand in commercial refrigeration and heat pumps, while the recast Ambient Air Quality Directive expands municipal monitoring. Germany, France, Italy, the Netherlands and the Nordic countries lead both consumption and manufacture, with several specialist cell and module producers based in the region. Hydrogen projects in industrial clusters are the clearest growth change, adding certified detection in facilities that previously handled no hydrogen.
Which Region Is Leading the Gas Sensors Market?
Asia Pacific leads the gas sensors market with a 33.0% revenue share in 2026 and is forecast to grow at a 9.6% CAGR through 2033. The region leads because it combines heavy process industry with the manufacture of the devices that embed sensing modules, so it consumes both certified safety sensors and very large volumes of low-cost elements.
China is the largest single market, with extensive chemical, steel, mining and power operations under tightened workplace and emissions enforcement, alongside domestic module manufacture at scale. Japan is a long-established source of metal oxide and catalytic sensing technology and supplies much of the world’s automotive and appliance demand. South Korea adds semiconductor fabrication, where toxic and pyrophoric gas monitoring is standard. India contributes refining, fertiliser and municipal air quality network expansion, with urban monitoring programmes growing quickly.
Latin America Expands Gas Sensing Through Refining, Mining and Municipal Air Monitoring
Latin America held 7.0% of global revenue in 2026 and is projected to grow at an 8.8% CAGR through 2033. Brazil is the largest market, combining offshore oil production, refining, ethanol processing and a sizeable commercial refrigeration base that uses refrigerant detection. Chile and Peru contribute underground and open-pit mining demand, where methane, carbon monoxide and oxygen monitoring are mandatory, and Mexico adds petrochemical and manufacturing requirements.
Barriers include uneven enforcement of workplace monitoring duties outside large operators, import duties and currency exposure on certified equipment, and limited local calibration laboratory capacity, which lengthens instrument turnaround. The most useful change is the growth of municipal air quality networks in major cities, where authorities are supplementing a small number of reference stations with denser indicative monitoring to identify pollution sources between official measurement points.
Which Region Is Growing Fastest in the Gas Sensors Market?
Middle East & Africa is growing fastest in the gas sensors market, at an 11.2% CAGR between 2026 and 2033, from a 7.0% share in 2026. Hydrocarbon processing explains the base, with Saudi Arabia, the United Arab Emirates, Qatar and Kuwait operating gas processing, liquefaction and petrochemical complexes that use dense fixed detection networks and large portable instrument fleets.
The acceleration comes from new build rather than replacement. Large hydrogen and ammonia projects, expanded liquefied natural gas capacity and industrial diversification programmes specify detection at the design stage. South Africa adds mining demand, and Egypt, Nigeria and Algeria contribute oil and gas work. Barriers are real: calibration and maintenance skills are scarce, extreme heat and dust shorten sensor life, and much equipment is imported with long lead times for replacement cells.
Competitive Landscape
The gas sensors market is moderately concentrated, and the degree of concentration varies sharply by layer. Certified industrial sensing for hazardous areas is held by a limited group able to carry approval costs, with Honeywell International Inc., Drägerwerk AG & Co. KGaA, MSA Safety Incorporated and Teledyne Technologies Incorporated strong in safety detection, and Amphenol Corporation and Alphasense Ltd. supplying electrochemical and infrared elements to instrument builders. Component-level supply is more fragmented, with Figaro Engineering Inc., Nemoto & Co., Ltd., Membrapor AG and SGX Sensortech Limited holding long-standing positions in specific cell chemistries. In consumer and building modules, semiconductor-process suppliers including Sensirion AG, ams-OSRAM AG and Robert Bosch GmbH compete on size, power and price rather than certification.
Competition rests on certification coverage, measurement stability over life, cross-sensitivity performance and the availability of compensation data. Instrument makers qualify a sensing element once and keep it for years, so design-in position is durable and switching is slow. New entrants, mostly from China, have gained ground in uncertified and price-sensitive applications, with Zhengzhou Winsen Electronics Technology Co., Ltd. among the volume suppliers.
Consolidation has been incremental, with instrument manufacturers acquiring sensing element producers to secure supply and protect margin, and component groups adding specialist chemistries to widen their catalogues. Vertical integration between cell maker and instrument builder is common and is becoming more pronounced in refrigerant and hydrogen detection.
Strategic direction centres on extending service life, embedding compensation and diagnostics on the module, and winning early certification for hydrogen and low global warming potential refrigerants, where specifications are still being set.
Gas Sensors Industry Leaders
- Honeywell International Inc.
- Figaro Engineering Inc.
- Sensirion AG
- Amphenol Corporation
- Drägerwerk AG & Co. KGaA
Recent Industry Developments
March 2024: The EU F-gas Regulation, Regulation (EU) 2024/573, became applicable, maintaining leak-check duties on equipment containing fluorinated greenhouse gases and allowing reduced inspection frequency where fixed detection is fitted – this made permanent refrigerant sensing the cheaper compliance route for commercial refrigeration operators.
August 2024: The EU Methane Regulation entered into force, introducing measurement, reporting and leak detection and repair obligations for oil, gas and coal operators – survey and continuous monitoring demand now rests on a legal duty rather than a voluntary programme.
December 2024: The recast EU Ambient Air Quality Directive entered into force, tightening limit values that apply from 2030 and strengthening monitoring obligations – authorities must expand measurement coverage well before the deadline, which supports both reference instruments and supplementary sensing networks.
Gas Sensors Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 2.6 Billion |
| Market Size 2033 | US$ 4.7 Billion |
| CAGR 2026–2033 | 8.8% |
| Absolute Dollar Opportunity | US$ 2.1 Billion |
| Largest Market | Asia Pacific (33.0% share in 2026) |
| Fastest-Growing Market | Middle East & Africa (11.2% CAGR) |
| Market Concentration | Medium |
| Major Players | Honeywell International Inc., Figaro Engineering Inc., Sensirion AG, Amphenol Corporation, Drägerwerk AG & Co. KGaA |
This report sizes the gas sensors market at the sensing element and sensor module level only, covering electrochemical, catalytic bead, infrared, semiconductor metal oxide, photoionisation, thermal conductivity and MEMS devices. Complete detection instruments, transmitters and analysers are excluded, which keeps the figure materially smaller than the detection equipment market. The base year is 2025, the forecast period runs from 2026 to 2033, and values are in US$ Billion.
Gas Sensors Market Segmentation
Sensor Technology
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
Gas Type
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
Configuration
- Fixed
- Portable
- Wearable
End-Use Industry
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Gas Sensors Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Refrigerant and Methane Leak Rules Create a Permanent Installed Base of Fixed Sensing Points
- Tightening Air Quality Limits and Ventilation Standards Multiply Monitoring Points
- Restraints
- Cross-Sensitivity and Drift Force Recalibration That Raises Lifetime Cost of Ownership
- Limited Sensor Life and Weak Credibility Against Reference Instruments Cap Low-Cost Deployments
- Market Opportunities
- Hydrogen Infrastructure Creates a New Certified Detection Installed Base
- Low-Cost MEMS Modules Open a Volume Design-In Pool in Buildings and Consumer Devices
- Drivers
- Global Gas Sensors Market Outlook, 2020–2033
- Global Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- Global Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- Global Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- Global Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- Global Gas Sensors Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- North America Gas Sensors Market Outlook, 2020–2033
- North America Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- North America Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- North America Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- North America Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- North America Gas Sensors Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- United States Gas Sensors Market Outlook, by Gas Type, 2020–2033
- United States Gas Sensors Market Outlook, by Configuration, 2020–2033
- United States Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Canada Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Canada Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Canada Gas Sensors Market Outlook, by Configuration, 2020–2033
- Canada Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Mexico Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Mexico Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Mexico Gas Sensors Market Outlook, by Configuration, 2020–2033
- Mexico Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- North America Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Europe Gas Sensors Market Outlook, 2020–2033
- Europe Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- Europe Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- Europe Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- Europe Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- Europe Gas Sensors Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Germany Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Germany Gas Sensors Market Outlook, by Configuration, 2020–2033
- Germany Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- France Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- France Gas Sensors Market Outlook, by Gas Type, 2020–2033
- France Gas Sensors Market Outlook, by Configuration, 2020–2033
- France Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Italy Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Italy Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Italy Gas Sensors Market Outlook, by Configuration, 2020–2033
- Italy Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Netherlands Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Netherlands Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Netherlands Gas Sensors Market Outlook, by Configuration, 2020–2033
- Netherlands Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Nordic countries Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Nordic countries Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Nordic countries Gas Sensors Market Outlook, by Configuration, 2020–2033
- Nordic countries Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Europe Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Asia Pacific Gas Sensors Market Outlook, 2020–2033
- Asia Pacific Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- Asia Pacific Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- Asia Pacific Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- Asia Pacific Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- Asia Pacific Gas Sensors Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- China Gas Sensors Market Outlook, by Gas Type, 2020–2033
- China Gas Sensors Market Outlook, by Configuration, 2020–2033
- China Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Japan Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Japan Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Japan Gas Sensors Market Outlook, by Configuration, 2020–2033
- Japan Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- South Korea Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- South Korea Gas Sensors Market Outlook, by Gas Type, 2020–2033
- South Korea Gas Sensors Market Outlook, by Configuration, 2020–2033
- South Korea Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- India Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- India Gas Sensors Market Outlook, by Gas Type, 2020–2033
- India Gas Sensors Market Outlook, by Configuration, 2020–2033
- India Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Asia Pacific Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Latin America Gas Sensors Market Outlook, 2020–2033
- Latin America Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- Latin America Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- Latin America Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- Latin America Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- Latin America Gas Sensors Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Brazil Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Brazil Gas Sensors Market Outlook, by Configuration, 2020–2033
- Brazil Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Chile Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Chile Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Chile Gas Sensors Market Outlook, by Configuration, 2020–2033
- Chile Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Peru Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Peru Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Peru Gas Sensors Market Outlook, by Configuration, 2020–2033
- Peru Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Latin America Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Middle East & Africa Gas Sensors Market Outlook, 2020–2033
- Middle East & Africa Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
- Middle East & Africa Gas Sensors Market Outlook, by Gas Type, Value (US$ Billion), 2020–2033
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
- Middle East & Africa Gas Sensors Market Outlook, by Configuration, Value (US$ Billion), 2020–2033
- Fixed
- Portable
- Wearable
- Middle East & Africa Gas Sensors Market Outlook, by End-Use Industry, Value (US$ Billion), 2020–2033
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
- Middle East & Africa Gas Sensors Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Saudi Arabia Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Saudi Arabia Gas Sensors Market Outlook, by Configuration, 2020–2033
- Saudi Arabia Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- United Arab Emirates Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- United Arab Emirates Gas Sensors Market Outlook, by Gas Type, 2020–2033
- United Arab Emirates Gas Sensors Market Outlook, by Configuration, 2020–2033
- United Arab Emirates Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Qatar Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Qatar Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Qatar Gas Sensors Market Outlook, by Configuration, 2020–2033
- Qatar Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Kuwait Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Kuwait Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Kuwait Gas Sensors Market Outlook, by Configuration, 2020–2033
- Kuwait Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- South Africa Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- South Africa Gas Sensors Market Outlook, by Gas Type, 2020–2033
- South Africa Gas Sensors Market Outlook, by Configuration, 2020–2033
- South Africa Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Egypt Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Egypt Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Egypt Gas Sensors Market Outlook, by Configuration, 2020–2033
- Egypt Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Nigeria Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Nigeria Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Nigeria Gas Sensors Market Outlook, by Configuration, 2020–2033
- Nigeria Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Algeria Gas Sensors Market Outlook, by Sensor Technology, 2020–2033
- Algeria Gas Sensors Market Outlook, by Gas Type, 2020–2033
- Algeria Gas Sensors Market Outlook, by Configuration, 2020–2033
- Algeria Gas Sensors Market Outlook, by End-Use Industry, 2020–2033
- Middle East & Africa Gas Sensors Market Outlook, by Sensor Technology, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Honeywell International Inc.
- Figaro Engineering Inc.
- Sensirion AG
- Amphenol Corporation
- Drägerwerk AG & Co. KGaA
- MSA Safety Incorporated
- Teledyne Technologies Incorporated
- Alphasense Ltd.
- Nemoto & Co., Ltd.
- Membrapor AG
- SGX Sensortech Limited
- Robert Bosch GmbH
- ams-OSRAM AG
- Zhengzhou Winsen Electronics Technology Co., Ltd.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Sensor Technology
- Electrochemical
- Catalytic Bead
- Infrared
- Semiconductor Metal Oxide
- Photoionisation Detector
- Thermal Conductivity
- MEMS Gas Sensors
Gas Type
- Oxygen
- Carbon Dioxide
- Carbon Monoxide
- Combustible Gases
- Hydrogen
- Volatile Organic Compounds
- Nitrogen Oxides and Sulphur Dioxide
- Refrigerants
Configuration
- Fixed
- Portable
- Wearable
End-Use Industry
- Industrial Safety and Gas Detection
- Oil and Gas
- Environmental and Air Quality Monitoring
- Building HVAC and Indoor Air Quality
- Automotive
- Medical
- Consumer Electronics
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The gas sensors market is valued at US$ 2.6 billion in 2026, measured at the sensing element and module level rather than complete instruments.
The market is projected to reach US$ 4.7 billion by 2033, growing at an 8.8% CAGR and adding US$ 2.1 billion over the period.
Electrochemical sensors lead with 31.0% share in 2026, because they offer good selectivity for toxic gases at very low power draw.
Hydrogen sensing grows fastest at a 16.2% CAGR, as electrolysers, storage sites and refuelling stations each require dedicated certified detection.
Asia Pacific holds 33.0% share in 2026, combining heavy process industry with large-scale manufacture of devices that embed sensing modules.
Related Reports
Multi-Access Edge Computing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the multi-access edge computing market, valued at US$ 4.2 billion in 2026 and projected to reach US$ 9.8 billion by 2033 at a 12.9% CAGR.
M-commerce Payment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the m-commerce payment market, valued at US$ 10.05 billion in 2026 and forecast to reach US$ 22.70 billion by 2033, growing at a 12.3% CAGR.
Irrigation Automation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Irrigation automation market to grow from US$ 6.2 billion in 2026 to US$ 18.5 billion by 2033 at a 16.9% CAGR. Explore components, end users and regional trends.
Underwater LiDAR Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the underwater LiDAR market, projected to reach US$0.9 billion by 2033 at 12.3% CAGR, with platform, application and regional insights.
Aerial Imaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global aerial imaging market is valued at US$3.83 billion in 2026, reaching US$8.13 billion by 2033, growing at an 11.4% CAGR
Satcom Terminal Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The satcom terminal market is projected to grow from US$8.6 billion in 2026 to US$20.6 billion by 2033, at a 13.3% CAGR. Explore segments and key trends.