


Smart Cities Market
Smart Cities Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Smart Cities Market Size and Trend Analysis
How Big Is the Smart Cities Technology Market?
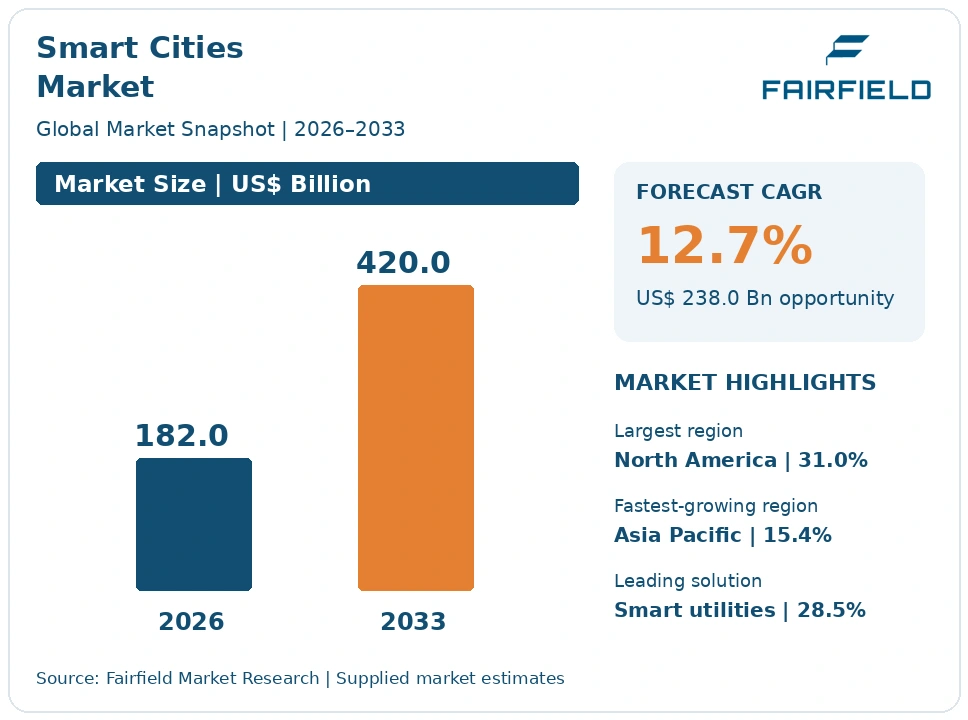
The global Smart Cities market size is expected to be valued at US$ 182.0 billion in 2026 and projected to reach US$ 420.0 billion by 2033, growing at a CAGR of 12.7% between 2026 and 2033.
Urban technology spending grew at close to an 11.0% CAGR between 2020 and 2025, with metering and public safety absorbing most of the money. Three factors set the forward path. Utility-funded programmes in electricity, gas and water give vendors a billable customer and a rate-recovered budget. Road pricing, tolling and paid parking schemes turn mobility systems into revenue-generating assets rather than cost centres. Data-sharing and network-security rules in the European Union are forcing cities to replace isolated systems with interoperable ones. Growth is steady rather than sudden, because municipal procurement cycles run long and many programmes stay at pilot scale for years before any city-wide award.
Key Report Takeaways
- By Solution: Smart Utilities held 28.5% share in 2026, while City Operating Platforms and Digital Twins are projected to expand at a 16.8% CAGR through 2033, driven by rules that require departments to share operational data across one interface.
- By Component: Hardware held 44.0% share in 2026, while Software is projected to expand at a 15.2% CAGR through 2033, as cities shift from buying meters and cameras to buying the analytics that make them useful.
- By Connectivity Technology: Cellular held 38.0% share in 2026, while Low-Power Wide-Area Networks are projected to grow at a 15.6% CAGR through 2033, because battery-powered water and waste sensors need a decade of life.
- By End User: Municipal Governments held 36.0% share in 2026, while Utilities are projected to grow at a 14.9% CAGR through 2033, since grid and water operators can recover technology costs through approved tariffs.
- By Geography: North America held 31.0% share in 2026, while Asia Pacific is projected to grow at a 15.4% CAGR through 2033, supported by national urban programmes in India and China.
Global Smart Cities Market Trends and Insights
Drivers Impact Analysis
Two forces account for most of the incremental vendor revenue in connected city platforms through 2033.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Utility metering and grid modernisation programmes carrying a rate-recovered budget | High | North America, Europe, Asia Pacific | Medium term (2–4 years) |
| Road pricing, tolling and paid parking schemes that fund intelligent transportation systems | Medium | Europe, Asia Pacific, Middle East & Africa | Long term (≥4 years) |
Rate-Recovered Utility Metering Gives Smart City Vendors Their Most Reliable Budget
Metering and network sensing form the largest single block of smart city technology spending because they carry a billable return. Electricity, gas and water utilities recover meters, communications and head-end software through approved tariffs, so these purchases survive changes of administration in a way that showcase projects do not. Water operators apply the same logic, using district metering and acoustic leak sensing to cut non-revenue water. Urban technology spending concentrates where an operator already bills a customer.
The mechanism is regulatory rather than technical. Energy and water regulators allow metering and sensing assets into the regulated asset base, which turns a capital request into a recoverable cost. Vendors selling into this pool quote measurable loss reduction, outage duration and billing accuracy instead of civic benefit. That evidence is what city finance officers and utility boards accept when budgets are contested.
Congestion Charging and Tolling Turn Smart Mobility Into a Revenue-Generating Asset
Paid mobility schemes are the second dependable source of demand for smart infrastructure. Congestion charges, electronic tolls, low-emission zone enforcement and sensor-based parking all generate cash that services the systems installed to run them. Transit agencies extend the same model through account-based ticketing and fare gates. Because the business case is arithmetic rather than aspirational, these projects clear procurement faster than city dashboards or analytics pilots with no matching income line.
Enforcement rules are what create the demand. Low-emission and clean-air zones require automatic number plate recognition, roadside classification and a back office able to handle disputes and exemptions. Cities adopting distance-based or time-based charging need vehicle positioning, certified payment handling and audited records. Each rule converts a policy decision into a specified procurement for cameras, roadside units, edge processing and clearing software.
Restraints Impact Analysis
The two constraints below are procedural and financial rather than technical, which is why they persist across every region.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Fragmented municipal budgets and multi-year public procurement cycles | High | Global, sharpest in Europe and Latin America | Long term (≥4 years) |
| Pilot projects that never reach city-wide scale, stranding vendor investment | Medium | Global, sharpest in Asia Pacific and Middle East & Africa | Medium term (2–4 years) |
Split Municipal Budgets and Slow Procurement Hold Back Smart City Contract Awards
Procurement is the real brake on this market, not the maturity of the technology. A single city programme often needs money from transport, policing, housing, environment and the utility, each with its own approval calendar and reporting line. Capital grants arrive for the first installation but rarely cover the software subscriptions, calibration and support that follow. Vendors carry long pre-award costs and face bid-to-award periods measured in quarters.
The cause sits in public finance rules. Municipal accounting treats hardware as capital and software as operating expenditure, and the operating line is the one squeezed first when revenue falls. Competitive tendering rules require open specifications, which lengthens the drafting stage and invites challenges. Election cycles add further risk, because an incoming council can cancel a programme that has already passed technical evaluation but not yet reached signature.
Pilot-Stage Deployments Prevent Municipal Digital Services From Reaching Commercial Scale
A large share of smart city activity never leaves demonstration status, which caps realised revenue well below announced programme values. Cities run funded trials across a few streets or one district, publish results, then stop before city-wide rollout. Vendors absorb integration, training and support costs for volumes that never arrive. Digital twin and city dashboard projects show this pattern most clearly, because their benefits are hard to express as avoided cost.
The underlying reason is the absence of an operating budget owner after the grant ends. Trials are usually financed by national innovation funds or development banks, while the recurring cost falls to a department with no matching allocation. Data from a pilot is often locked in a supplier platform, so scaling means re-procurement rather than extension. Interoperability gaps between departmental systems then raise the cost of the second phase above the first.
Market Opportunities
Data-Sharing Obligations Open a Services Pool Around City Interoperability and Data Governance
Mandatory data access rules create a new revenue pool in data brokerage, cataloguing and integration services that did not exist as a standalone line five years ago. The EU Data Act gives users of connected products rights over the data those products generate, and the Data Governance Act sets the framework for re-use of public sector information. Cities must publish, describe and share operational data, which they cannot do with isolated departmental systems.
System integrators, platform vendors and specialist consultancies are positioned to capture this work. The buyers are city chief information officers, transport authorities and utilities that now need common data models, consent handling and audit trails. The ISO 37120 and ISO 37122 indicator standards give cities a vocabulary for what to publish, which converts a vague obligation into a defined scope that can be tendered and priced.
Cybersecurity Duties for Public Administration Create Recurring Compliance Revenue
Network security obligations convert a one-off hardware sale into a recurring service contract, which is the most valuable change in this market’s revenue mix. The NIS2 Directive places public administration entities, energy and water operators and transport authorities inside a formal risk-management and incident-reporting regime. Compliance is continuous, covering asset inventory, supply chain assessment, monitoring and board-level accountability, so it cannot be discharged by a single purchase.
Security vendors, managed service providers and the platform suppliers already operating city systems are best placed to serve it. Demand comes from municipal operators of water treatment, street lighting control and traffic signals, where connected endpoints were installed with little segmentation. Incident-reporting deadlines force cities to buy detection and response capability they can evidence, and that evidence requirement favours suppliers offering a monitored service rather than a product.
Segment Analysis
By Solution: Smart Utilities Lead While City Operating Platforms and Digital Twins Accelerate
Smart Utilities held 28.5% of the market in 2026, the largest share of any solution area, because metering, grid sensing and water network monitoring sit with operators that bill customers and recover costs through tariffs. Advanced metering infrastructure alone accounts for a steady replacement cycle running across North America and Europe. Smart Mobility and Traffic Management follows closely, carried by tolling and enforcement contracts.
City Operating Platforms and Digital Twins is the fastest-growing solution at a 16.8% CAGR to 2033, from a small base. Growth comes from data-sharing duties that require departments to expose operational data through one interface, and from flood, heat and utility planning use cases where a shared model saves measurable engineering time. The commercial implication is that platform suppliers increasingly sit between the sensor vendors and the city, which shifts margin toward software and away from devices.
By Component: Hardware Dominates Installed Spend as Software Takes the Growth
Hardware accounted for 44.0% of connected city platforms revenue in 2026, reflecting the weight of meters, cameras, roadside units, luminaires and gateways in every deployed programme. Equipment still dominates because most cities are in their first or second installation wave, and because hardware is funded from capital grants that are easier to secure than operating budgets. Services hold the second position, driven by integration work.
Software is the fastest-growing component at a 15.2% CAGR through 2033. Cities that installed devices in earlier phases now buy the analytics, asset management and data governance tools needed to use them, and security duties add monitoring subscriptions. The shift matters commercially because software renews annually and travels across departments, giving vendors a revenue line that does not depend on winning the next capital tender.
By Connectivity Technology: Cellular Carries the Traffic While Low-Power Networks Expand Quickest
Cellular networks carried 38.0% of smart infrastructure connections by value in 2026, supported by broad coverage, managed security and the bandwidth that video surveillance and traffic cameras require. Public safety and transit applications depend on it almost exclusively. Fibre and wireline hold a substantial share in intersection control and building connections, while Wi-Fi and mesh serve dense campus and depot environments.
Low-Power Wide-Area Networks are growing fastest at a 15.6% CAGR to 2033. Water meters, waste bin sensors, parking bays and environmental monitors need multi-year battery life and small, infrequent messages, which suits these networks and makes per-device cost very low. Satellite links are gaining a niche role for remote pumping and irrigation assets. The practical effect is that cities now run several networks at once, raising demand for management tools that treat connectivity as one estate.
By End User: Municipal Governments Buy Most, Utilities Grow Fastest
Municipal Governments represented 36.0% of buyers in 2026, since councils own street lighting, waste collection, parking, planning and the citizen-facing side of municipal digital services. Their purchasing is broad but budget-constrained, and it is the segment most exposed to election cycles and grant timing. Public Safety Agencies and Transit Agencies follow, each with dedicated capital programmes and clearer operational metrics.
Utilities are the fastest-growing end user at a 14.9% CAGR through 2033. Electricity, gas and water operators can place technology inside a regulated asset base and recover it through tariffs, so their spending is less sensitive to annual budget rounds. They also face statutory duties on leakage, outage reporting and network resilience that require measurement. For vendors, this is the segment where contracts are largest, longest and least likely to stop after the first phase.
Geography Analysis
Which Region Is Leading the Smart Cities Market?
North America leads the smart cities market with a 31.0% revenue share in 2026 and is forecast to grow at an 11.0% CAGR through 2033. The position rests on utility spending rather than municipal spending. Investor-owned and public power utilities in the United States have run two full waves of advanced metering, and water utilities are now replacing mechanical meters at scale under state conservation rules.
Canada adds transit modernisation and provincial grid programmes, while Mexico contributes tolling and distribution network sensing. Public safety is the second pillar, with large camera estates, gunshot detection and computer-aided dispatch upgrades funded through state and federal grants. The clearest change underway is scrutiny of surveillance procurement, with several city councils restricting facial recognition use, which pushes vendors toward analytics that do not identify individuals.
Europe Builds Its Smart City Demand on Data-Sharing and Network Security Rules
Europe accounted for 27.0% of the market in 2026 and is forecast to expand at an 11.3% CAGR through 2033. Regulation sets specifications here more directly than in any other region. The NIS2 Directive, Directive (EU) 2022/2555, brings public administration, energy, water and transport operators into a binding risk-management and incident-reporting regime, which has moved security from an optional line item to a condition of operation.
The EU Data Act and the Data Governance Act oblige cities to make operational data accessible and re-usable, favouring open platforms over closed vertical systems. The Artificial Intelligence Act, Regulation (EU) 2024/1689, restricts real-time remote biometric identification in publicly accessible spaces and is directly material to surveillance procurement. Germany, France, Spain and the Nordic countries lead deployment. Constrained municipal finances remain the brake on contract sizes.
Which Region Is Growing Fastest in the Smart Cities Market?
Asia Pacific is growing fastest in the smart cities market, at a 15.4% CAGR between 2026 and 2033, from a 30.0% share in 2026. National programmes rather than individual city budgets explain the pace. India’s national urban mission framework funded integrated command and control centres, metering and surveillance across a defined list of cities, and the follow-on phase is moving spending toward water, waste and transport operations.
China runs the largest national programmes, combining municipal platforms, traffic management and very large camera networks with domestic equipment supply. Japan and South Korea focus on ageing infrastructure monitoring and disaster response, while Singapore and Australia invest in transport and utility analytics. Indonesia and Vietnam are adding first-wave metering and traffic systems. Procurement capacity at municipal level, not funding, is the main limit on how quickly programmes convert to installations.
Latin America Advances Smart City Projects Through Transport Concessions and Utility Loss Reduction
Latin America held 6.5% of global revenue in 2026 and is projected to grow at a 12.4% CAGR through 2033. Brazil is the largest market, where distribution utilities invest in metering and network sensing to reduce commercial losses, and where municipal transport concessions fund fare systems and traffic control. Mexico, Chile and Colombia follow, with Bogota and Santiago notable for transit technology.
Barriers are substantial: municipal credit quality is uneven, currency exposure raises the cost of imported equipment, and public security concerns divert funds toward policing hardware rather than platforms. Procurement challenges and changes of mayoral administration frequently delay awards. The most useful change is the growth of concession and public-private partnership structures, which move technology cost onto an operator with a toll, fare or tariff income stream rather than onto the city budget.
Middle East & Africa Concentrates Smart City Investment in New Urban Districts and Water Networks
Middle East & Africa accounted for 5.5% of the market in 2026 and is forecast to grow at a 13.2% CAGR through 2033 from a small base. Saudi Arabia and the United Arab Emirates dominate activity, funding command centres, transport systems, district cooling controls and large camera estates inside new urban districts built from scratch, where systems are specified before construction rather than retrofitted.
Egypt, Morocco, Kenya, Nigeria and South Africa invest more narrowly, focusing on electricity metering, prepayment systems and water loss reduction where the financial return is immediate. Barriers include limited municipal borrowing capacity, unreliable grid supply, thin local integrator networks and skills shortages that make long-term operation harder than installation. The change worth watching is the spread of prepaid and smart metering into secondary cities, which gives utilities a measurable collections benefit.
Competitive Landscape
The smart cities market is fragmented, with low concentration and no supplier holding a commanding global position. The breadth of the definition is the reason: metering, traffic systems, surveillance, lighting controls, waste telemetry and city software are distinct businesses with different buyers, standards and sales cycles. Diversified industrial groups such as Siemens AG, Schneider Electric SE and Hitachi, Ltd. compete across several of these areas from an installed base in grids and buildings. Networking and computing suppliers including Cisco Systems, Inc. and International Business Machines Corporation approach the same cities from the platform and integration side, while metering specialists such as Itron, Inc. and Landis+Gyr Group AG hold deep positions in a single layer.
Competition turns on references, integration capability and the ability to meet public procurement conditions rather than on product specification alone. Cities buy from suppliers that can evidence a comparable deployment, pass security assessment and commit to long support terms. Open interfaces have become a scoring criterion in tenders, which weakens the position of closed vertical systems. Regional entrants matter more than in most technology markets, because language, local data residency rules and municipal relationships are hard to replicate at distance.
Consolidation has been continuous rather than dramatic. Metering, lighting controls and transport software assets have changed hands repeatedly as industrial groups assemble portfolios, and system integrators have absorbed specialist analytics firms to widen their bid coverage. Partnership structures between network operators, platform vendors and civil contractors are common, since few suppliers can deliver a whole programme alone.
Strategic direction is converging on recurring revenue. Suppliers are moving from equipment sales toward managed services, security monitoring and data platforms, because these survive the gap between capital grants. Compliance capability, particularly around data sharing and network security duties, is becoming a differentiator in its own right.
Smart Cities Industry Leaders
- Siemens AG
- Cisco Systems, Inc.
- International Business Machines Corporation
- Schneider Electric SE
- Huawei Technologies Co., Ltd.
Recent Industry Developments
October 2024: The transposition deadline for the NIS2 Directive, Directive (EU) 2022/2555, passed, bringing public administration entities and energy, water and transport operators into a binding cybersecurity and incident-reporting regime – this converted city security spending from discretionary to mandatory across the European Union.
February 2025: The prohibited-practices provisions of the Artificial Intelligence Act, Regulation (EU) 2024/1689, became applicable, restricting real-time remote biometric identification in publicly accessible spaces – public safety and surveillance procurement in Europe now requires a documented legal basis before deployment.
September 2025: The EU Data Act became applicable, giving users of connected products rights of access to the data those products generate – city platforms and metering systems must now expose data through defined interfaces, which favours open architectures over closed vertical systems.
August 2026: The main body of obligations under the Artificial Intelligence Act became applicable, covering high-risk systems and their documentation, logging and human-oversight duties – surveillance and traffic analytics suppliers must now evidence conformity before a city can place them in service.
Smart Cities Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 182.0 Billion |
| Market Size 2033 | US$ 420.0 Billion |
| CAGR 2026–2033 | 12.7% |
| Absolute Dollar Opportunity | US$ 238.0 Billion |
| Largest Market | North America (31.0% share in 2026) |
| Fastest-Growing Market | Asia Pacific (15.4% CAGR) |
| Market Concentration | Low |
| Major Players | Siemens AG, Cisco Systems, Inc., International Business Machines Corporation, Schneider Electric SE, Huawei Technologies Co., Ltd. |
This report sizes the smart cities market as vendor revenue from the technology layer sold to cities, utilities and transit agencies, covering mobility, utilities, public safety, street lighting, waste, city platforms, e-governance and supporting connectivity and edge infrastructure. Civil construction and heavy infrastructure spending, which is an order of magnitude larger, is excluded. The base year is 2025, the forecast period runs from 2026 to 2033, and all values are in US$ Billion.
Smart Cities Market Segmentation
Solution
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
Component
- Hardware
- Software
- Services
Connectivity Technology
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
End User
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Smart Cities Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Rate-Recovered Utility Metering Gives Smart City Vendors Their Most Reliable Budget
- Congestion Charging and Tolling Turn Smart Mobility Into a Revenue-Generating Asset
- Restraints
- Split Municipal Budgets and Slow Procurement Hold Back Smart City Contract Awards
- Pilot-Stage Deployments Prevent Municipal Digital Services From Reaching Commercial Scale
- Market Opportunities
- Data-Sharing Obligations Open a Services Pool Around City Interoperability and Data Governance
- Cybersecurity Duties for Public Administration Create Recurring Compliance Revenue
- Drivers
- Global Smart Cities Market Outlook, 2020–2033
- Global Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- Global Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Global Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- Global Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- Global Smart Cities Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- North America Smart Cities Market Outlook, 2020–2033
- North America Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- North America Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- North America Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- North America Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- North America Smart Cities Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Smart Cities Market Outlook, by Solution, 2020–2033
- United States Smart Cities Market Outlook, by Component, 2020–2033
- United States Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- United States Smart Cities Market Outlook, by End User, 2020–2033
- Canada Smart Cities Market Outlook, by Solution, 2020–2033
- Canada Smart Cities Market Outlook, by Component, 2020–2033
- Canada Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Canada Smart Cities Market Outlook, by End User, 2020–2033
- Mexico Smart Cities Market Outlook, by Solution, 2020–2033
- Mexico Smart Cities Market Outlook, by Component, 2020–2033
- Mexico Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Mexico Smart Cities Market Outlook, by End User, 2020–2033
- North America Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Europe Smart Cities Market Outlook, 2020–2033
- Europe Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- Europe Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Europe Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- Europe Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- Europe Smart Cities Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Smart Cities Market Outlook, by Solution, 2020–2033
- Germany Smart Cities Market Outlook, by Component, 2020–2033
- Germany Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Germany Smart Cities Market Outlook, by End User, 2020–2033
- France Smart Cities Market Outlook, by Solution, 2020–2033
- France Smart Cities Market Outlook, by Component, 2020–2033
- France Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- France Smart Cities Market Outlook, by End User, 2020–2033
- Spain Smart Cities Market Outlook, by Solution, 2020–2033
- Spain Smart Cities Market Outlook, by Component, 2020–2033
- Spain Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Spain Smart Cities Market Outlook, by End User, 2020–2033
- Nordic countries Smart Cities Market Outlook, by Solution, 2020–2033
- Nordic countries Smart Cities Market Outlook, by Component, 2020–2033
- Nordic countries Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Nordic countries Smart Cities Market Outlook, by End User, 2020–2033
- Europe Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Asia Pacific Smart Cities Market Outlook, 2020–2033
- Asia Pacific Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- Asia Pacific Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Asia Pacific Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- Asia Pacific Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- Asia Pacific Smart Cities Market Outlook, by Country, Value (US$ Billion), 2020–2033
- India Smart Cities Market Outlook, by Solution, 2020–2033
- India Smart Cities Market Outlook, by Component, 2020–2033
- India Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- India Smart Cities Market Outlook, by End User, 2020–2033
- China Smart Cities Market Outlook, by Solution, 2020–2033
- China Smart Cities Market Outlook, by Component, 2020–2033
- China Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- China Smart Cities Market Outlook, by End User, 2020–2033
- Japan Smart Cities Market Outlook, by Solution, 2020–2033
- Japan Smart Cities Market Outlook, by Component, 2020–2033
- Japan Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Japan Smart Cities Market Outlook, by End User, 2020–2033
- South Korea Smart Cities Market Outlook, by Solution, 2020–2033
- South Korea Smart Cities Market Outlook, by Component, 2020–2033
- South Korea Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- South Korea Smart Cities Market Outlook, by End User, 2020–2033
- Singapore Smart Cities Market Outlook, by Solution, 2020–2033
- Singapore Smart Cities Market Outlook, by Component, 2020–2033
- Singapore Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Singapore Smart Cities Market Outlook, by End User, 2020–2033
- Australia Smart Cities Market Outlook, by Solution, 2020–2033
- Australia Smart Cities Market Outlook, by Component, 2020–2033
- Australia Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Australia Smart Cities Market Outlook, by End User, 2020–2033
- Indonesia Smart Cities Market Outlook, by Solution, 2020–2033
- Indonesia Smart Cities Market Outlook, by Component, 2020–2033
- Indonesia Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Indonesia Smart Cities Market Outlook, by End User, 2020–2033
- Vietnam Smart Cities Market Outlook, by Solution, 2020–2033
- Vietnam Smart Cities Market Outlook, by Component, 2020–2033
- Vietnam Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Vietnam Smart Cities Market Outlook, by End User, 2020–2033
- Asia Pacific Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Latin America Smart Cities Market Outlook, 2020–2033
- Latin America Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- Latin America Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Latin America Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- Latin America Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- Latin America Smart Cities Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Brazil Smart Cities Market Outlook, by Solution, 2020–2033
- Brazil Smart Cities Market Outlook, by Component, 2020–2033
- Brazil Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Brazil Smart Cities Market Outlook, by End User, 2020–2033
- Chile Smart Cities Market Outlook, by Solution, 2020–2033
- Chile Smart Cities Market Outlook, by Component, 2020–2033
- Chile Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Chile Smart Cities Market Outlook, by End User, 2020–2033
- Colombia Smart Cities Market Outlook, by Solution, 2020–2033
- Colombia Smart Cities Market Outlook, by Component, 2020–2033
- Colombia Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Colombia Smart Cities Market Outlook, by End User, 2020–2033
- Latin America Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Middle East & Africa Smart Cities Market Outlook, 2020–2033
- Middle East & Africa Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
- Middle East & Africa Smart Cities Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Middle East & Africa Smart Cities Market Outlook, by Connectivity Technology, Value (US$ Billion), 2020–2033
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
- Middle East & Africa Smart Cities Market Outlook, by End User, Value (US$ Billion), 2020–2033
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
- Middle East & Africa Smart Cities Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Smart Cities Market Outlook, by Solution, 2020–2033
- Saudi Arabia Smart Cities Market Outlook, by Component, 2020–2033
- Saudi Arabia Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Saudi Arabia Smart Cities Market Outlook, by End User, 2020–2033
- United Arab Emirates Smart Cities Market Outlook, by Solution, 2020–2033
- United Arab Emirates Smart Cities Market Outlook, by Component, 2020–2033
- United Arab Emirates Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- United Arab Emirates Smart Cities Market Outlook, by End User, 2020–2033
- Egypt Smart Cities Market Outlook, by Solution, 2020–2033
- Egypt Smart Cities Market Outlook, by Component, 2020–2033
- Egypt Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Egypt Smart Cities Market Outlook, by End User, 2020–2033
- Morocco Smart Cities Market Outlook, by Solution, 2020–2033
- Morocco Smart Cities Market Outlook, by Component, 2020–2033
- Morocco Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Morocco Smart Cities Market Outlook, by End User, 2020–2033
- Kenya Smart Cities Market Outlook, by Solution, 2020–2033
- Kenya Smart Cities Market Outlook, by Component, 2020–2033
- Kenya Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Kenya Smart Cities Market Outlook, by End User, 2020–2033
- Nigeria Smart Cities Market Outlook, by Solution, 2020–2033
- Nigeria Smart Cities Market Outlook, by Component, 2020–2033
- Nigeria Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- Nigeria Smart Cities Market Outlook, by End User, 2020–2033
- South Africa Smart Cities Market Outlook, by Solution, 2020–2033
- South Africa Smart Cities Market Outlook, by Component, 2020–2033
- South Africa Smart Cities Market Outlook, by Connectivity Technology, 2020–2033
- South Africa Smart Cities Market Outlook, by End User, 2020–2033
- Middle East & Africa Smart Cities Market Outlook, by Solution, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Siemens AG
- Cisco Systems, Inc.
- International Business Machines Corporation
- Schneider Electric SE
- Huawei Technologies Co., Ltd.
- Hitachi, Ltd.
- Honeywell International Inc.
- Itron, Inc.
- Landis+Gyr Group AG
- Signify N.V.
- NEC Corporation
- Kapsch TrafficCom AG
- Johnson Controls International plc
- Motorola Solutions, Inc.
- Alphabet Inc.
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Solution
- Smart Mobility and Traffic Management
- Smart Utilities
- Public Safety and Surveillance
- Connected Street Lighting
- Smart Waste Management
- City Operating Platforms and Digital Twins
- E-Governance and Citizen Services
Component
- Hardware
- Software
- Services
Connectivity Technology
- Cellular
- Low-Power Wide-Area Networks
- Fibre and Wireline
- Wi-Fi and Mesh
- Satellite
End User
- Municipal Governments
- Utilities
- Transit Agencies
- Public Safety Agencies
- Waste Management Authorities
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The smart cities market is valued at US$ 182.0 billion in 2026, measured as vendor revenue from the technology layer sold to cities and utilities.
The market is projected to reach US$ 420.0 billion by 2033, growing at a 12.7% CAGR and adding US$ 238.0 billion over the forecast period.
Smart Utilities leads with 28.5% share in 2026, because metering and network programmes are recovered through tariffs rather than municipal budgets.
City Operating Platforms and Digital Twins is growing fastest at a 16.8% CAGR, supported by data-sharing duties that require departments to share operational data.
North America holds 31.0% share in 2026, led by utility metering programmes in the United States and large public safety estates.
Related Reports
Plastic Transistors Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global plastic transistors market is valued at US$0.4 billion in 2026, reaching US$0.9 billion by 2033, growing at a 12.3% CAGR
Multi-Access Edge Computing Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the multi-access edge computing market, valued at US$ 4.2 billion in 2026 and projected to reach US$ 9.8 billion by 2033 at a 12.9% CAGR.
M-commerce Payment Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the m-commerce payment market, valued at US$ 10.05 billion in 2026 and forecast to reach US$ 22.70 billion by 2033, growing at a 12.3% CAGR.
Irrigation Automation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Irrigation automation market to grow from US$ 6.2 billion in 2026 to US$ 18.5 billion by 2033 at a 16.9% CAGR. Explore components, end users and regional trends.
Underwater LiDAR Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the underwater LiDAR market, projected to reach US$0.9 billion by 2033 at 12.3% CAGR, with platform, application and regional insights.
Aerial Imaging Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global aerial imaging market is valued at US$3.83 billion in 2026, reaching US$8.13 billion by 2033, growing at an 11.4% CAGR