


Machine Vision Market
Machine Vision Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Machine Vision Market Size and Trend Analysis
How Fast Will the Machine Vision Market Grow by 2033?
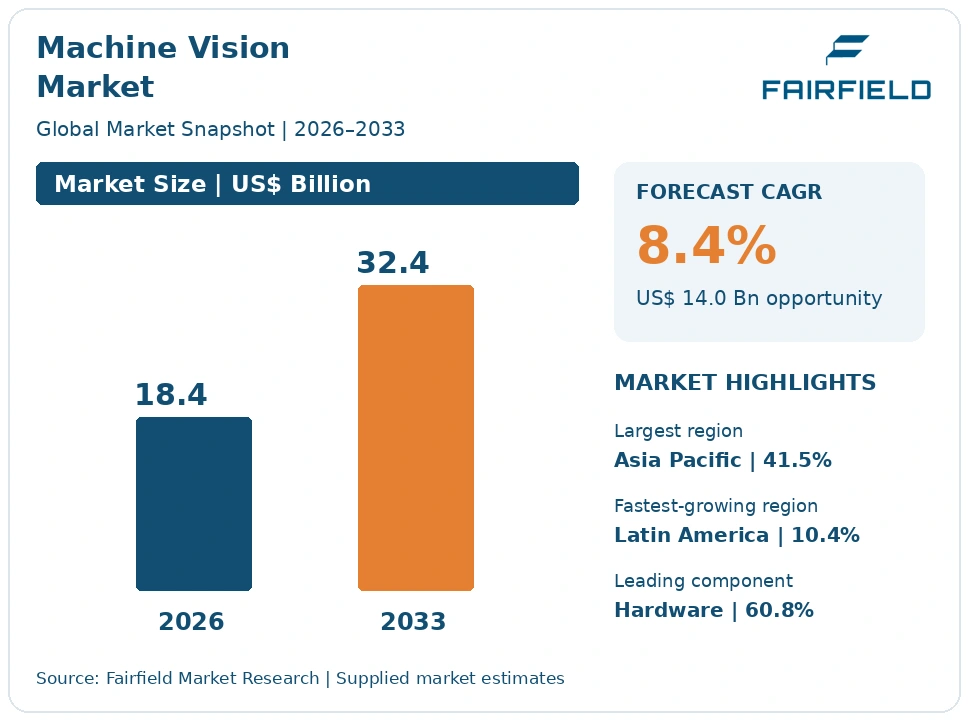
The global Machine Vision market size is expected to be valued at US$ 18.4 billion in 2026 and projected to reach US$ 32.4 billion by 2033, growing at a CAGR of 8.4% between 2026 and 2033.
Between 2020 and 2025 the industry expanded at a historical CAGR of close to 7.6%, with semiconductor and electronics inspection absorbing most incremental spending. Three factors set the pace for the forecast period. Deep-learning inspection software now handles variable surfaces that rule-based tools could never score reliably. Three-dimensional imaging has moved from laboratory trials into routine weld, seal and assembly verification. Battery cell and semiconductor packaging lines are adding inspection stations at several points in each process. The direction is steady rather than explosive: vision content per production line keeps rising, while the installed base of legacy two-dimensional systems is replaced on normal capital cycles rather than abandoned.
Key Report Takeaways
- By Component: Hardware held 60.8% share in 2026, while vision software is projected to expand at an 11.4% CAGR through 2033, driven by deep-learning inspection tools that are licensed and renewed separately from cameras.
- By Product Type: PC-based vision systems held 52.4% share in 2026, while embedded vision systems are projected to grow at a 12.1% CAGR through 2033, as system-on-module processors bring inference onto the camera body itself.
- By Imaging Technique: Two-dimensional vision held 73.5% share in 2026, while three-dimensional vision is projected to advance at a 12.8% CAGR through 2033, supported by cheaper structured-light and laser-triangulation sensor heads.
- By End-use Industry: Semiconductors and electronics held 26.5% share in 2026, while automotive and battery manufacturing is projected to rise at a 10.6% CAGR through 2033, reflecting new cell and module inspection points.
- By Geography: Asia Pacific held 41.5% share in 2026, while Latin America is projected to grow at a 10.4% CAGR through 2033, as nearshored electronics and vehicle plants install automated inspection from the start.
Global Machine Vision Market Trends and Insights
Drivers Impact Analysis
Two forces explain most of the forecast growth in automated optical inspection spending.
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Deep-learning defect detection on variable surfaces | High | Global, led by Asia Pacific and Europe | Medium term (2–4 years) |
| Inspection density in battery cell and semiconductor packaging | High | Asia Pacific, North America, Europe | Long term (≥4 years) |
Deep-Learning Defect Detection Opens Machine Vision Applications Rule-Based Tools Could Not Serve
Deep-learning classification has widened the addressable work for industrial imaging more than any hardware change this decade. Rule-based tools need a defect that can be described by geometry, contrast or position. Scratches on brushed metal, grain variation in castings, textile flaws and cosmetic blemishes on moulded plastic defeat that approach. Neural classifiers judge these parts against learned examples, so lines that were inspected by eye are now candidates for automation.
The mechanism is practical rather than theoretical. Inference now runs on general-purpose graphics processors or on embedded accelerators inside the camera, at line rates that match production. Vendors ship labelling, training and deployment inside the same software environment used for conventional tools, so an integrator can mix a measurement step with a learned classification step in one inspection sequence. That packaging, more than algorithm progress, is what converts interest into purchase orders.
Battery and Semiconductor Inspection Density Raises Machine Vision Content per Production Line
Cell manufacturing and advanced semiconductor packaging have pushed the number of inspection stations per line to levels no other industry matches. A single lithium-ion cell line checks electrode coating edges, notching burrs, stacking or winding alignment, tab welds and final seal integrity. Each of those steps is a separate camera, lens and lighting purchase, often with a three-dimensional sensor where a flat image cannot resolve height or weld quality.
The cause is the cost of escape. A defective cell that reaches a pack is expensive to recall and dangerous in service, so producers inspect every unit rather than sample. Semiconductor packaging follows the same logic as die sizes shrink and stacking increases. Both industries also need traceability, which pairs code reading with inspection data so a suspect unit can be identified later from its recorded images.
Restraints Impact Analysis
Two constraints hold back deployment even where the business case is clear.
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Shortage of vision engineers and qualified system integrators | High | Global, acute in Europe and North America | Long term (≥4 years) |
| Cost and difficulty of assembling labelled defect image sets | Medium | Global | Medium term (2–4 years) |
Shortage of Vision Engineers and Integrators Delays Machine Vision Projects Beyond Component Lead Times
The scarce resource in this industry is people, not cameras. Components ship in weeks, while a competent integrator may quote a start date months away. Manufacturers with several plants find they can buy identical hardware for each site but cannot staff the commissioning work in parallel, so rollouts stretch across years. Projects that stall at this stage are frequently cancelled rather than rescheduled.
The underlying cause is the breadth of the skill set. A working application needs optics selection, illumination design, mechanical fixturing, image processing, programmable logic controller integration and line-side support, and that combination is taught in few formal programmes. Experienced engineers concentrate in integrators and in vendor application teams, both of which prioritise large accounts. Smaller manufacturers absorb the delay, which caps adoption well below the level that plant-floor economics would otherwise justify.
Labelled Defect Image Sets Remain the Hidden Cost That Limits Machine Vision Deployment
Training data, not software licensing, is the cost that stops many deep-learning inspection projects. A classifier needs examples of each defect class, and genuine defects are rare on a line that already runs well. Collecting enough images can take months of production, and the parts must be kept, catalogued and labelled by someone who knows the quality standard. That labour is rarely budgeted at the quotation stage.
Labelling consistency is the deeper technical problem. Two inspectors often disagree on borderline cosmetic rejects, and a model trained on inconsistent labels inherits that disagreement as false calls. Teams then spend further weeks arbitrating the standard before the system can be signed off. Synthetic image generation and anomaly-detection methods that learn only from good parts reduce the burden, but neither removes the need for a validated reject set.
Market Opportunities
Three-Dimensional Vision for Robot Guidance Opens a Revenue Pool Beyond Flat-Part Inspection
Three-dimensional imaging is the clearest new revenue pool in industrial imaging, because it sells into guidance work that flat cameras cannot do at all. Random bin picking, depalletising of mixed loads, sealant bead verification and dimensional checks on formed parts all require height data. Sensor prices for structured-light and laser-triangulation heads have fallen far enough that these applications now clear ordinary payback thresholds.
Logistics operators and general manufacturers, rather than the traditional electronics buyers, create most of this demand. Parcel and warehouse automation needs pose estimation for unstructured items, and contract manufacturers need measurement where a coordinate measuring machine is too slow. Robot vendors packaging certified vision-guided picking kits with their arms make the purchase a single decision, which brings in buyers who would not specify an imaging system themselves.
Configurable Vision Software and Inspection Services Create Recurring Machine Vision Revenue
Software and service revenue is the pool that changes vendor economics, since both recur while a camera sells once. Licensed inspection environments, deep-learning training modules, deployment runtimes and hosted model management all carry renewals. Service contracts covering re-training after a product change, periodic optics cleaning and performance verification extend the relationship well past commissioning.
Smaller manufacturers are the customer group that makes this work. They cannot employ a vision engineer, so they buy an outcome: an inspection cell specified, installed and maintained under contract. Component vendors capture this through certified integrator networks, while software specialists sell directly into plants that already own suitable cameras. Standard interfaces such as GenICam, GigE Vision, USB3 Vision and CoaXPress make the software layer portable across hardware brands, which is precisely what allows it to be sold on its own.
Segment Analysis
By Component: Hardware Leads While Vision Software Scales Faster
Hardware accounted for 60.8% of machine vision revenue in 2026, covering area scan and line scan cameras, smart cameras, vision sensors, optics, lighting, frame grabbers and processors. It leads because every application needs a physical imaging chain, and because lighting and optics are bought per station rather than once per site. The EMVA 1288 characterisation standard lets buyers compare sensor and camera performance objectively, which keeps hardware competition tight on measurable specifications.
Vision software is the fastest-growing component at an 11.4% CAGR to 2033. Deep-learning defect detection, measurement libraries and deployment runtimes are increasingly licensed apart from the camera, and they are re-licensed when production changes. Services sit between the two, growing on commissioning and re-training work. The implication is a gradual margin shift toward vendors that own the software layer rather than only the imaging hardware.
By Product Type: PC-Based Systems Hold Scale as Embedded Vision Accelerates
PC-based vision systems held 52.4% share in 2026, because multi-camera inspection cells, high-resolution line scan work and heavy deep-learning inference still need a host with a frame grabber and a graphics processor. These systems also suit plants that already maintain industrial computers and want one platform across several stations.
Embedded vision systems are growing fastest at a 12.1% CAGR through 2033. System-on-module processors with neural accelerators now run classification on the camera body, which removes cabling, cuts cabinet space and lowers the installed cost of a single-check station. Smart cameras and vision sensors remain the entry point for presence, orientation and code reading tasks, and they bring first-time users into automated optical inspection. The business implication is a widening market at the low end, where the buyer is a plant engineer rather than a vision specialist.
By Imaging Technique: Two-Dimensional Inspection Dominates While Three-Dimensional Vision Closes the Gap
Two-dimensional vision represented 73.5% of the market in 2026. Most industrial checks, including print verification, code reading, surface defect classification and presence or absence tests, need only a flat image, and the optics, lighting and processing for these tasks are mature and inexpensive.
Three-dimensional vision is the fastest-growing technique at a 12.8% CAGR to 2033. Laser triangulation, structured light, stereo and time-of-flight methods each answer questions a flat image cannot: coplanarity of connector pins, weld bead volume, glue bead continuity and box pose on a pallet. Falling sensor costs and point-cloud tools built into mainstream software environments have removed the specialist barrier. As three-dimensional content rises, average system value per station increases, which supports revenue growth even where unit shipments of cameras grow slowly.
By End-use Industry: Electronics Inspection Leads While Battery and Vehicle Plants Grow Fastest
Semiconductors and electronics held 26.5% share in 2026, the largest single block of demand. Wafer handling, die attach, solder paste inspection, automated optical inspection of assembled boards and final package checks each use imaging, and tolerances there are tighter than in any other industry.
Automotive and battery manufacturing is expanding fastest at a 10.6% CAGR through 2033. New cell, module and pack lines design inspection in from the start, and vision also supports robot safety functions alongside equipment governed by ISO 10218, ISO/TS 15066 and IEC 61496. Food and beverage, pharmaceuticals and packaging contribute steady volume through code reading, fill level and seal integrity checks. Logistics and e-commerce add parcel dimensioning and label verification. Diversity across these industries cushions vendors against the semiconductor capital cycle.
Geography Analysis
North America Anchors Semiconductor, Pharmaceutical and Logistics Inspection Demand
North America held 24.0% of global machine vision revenue in 2026 and is forecast to grow at a 7.4% CAGR through 2033. The United States drives the position, with semiconductor fabrication and advanced packaging investment, pharmaceutical serialisation and packaging inspection, and very large parcel handling operations that dimension and read codes on every item. Canada and Mexico add vehicle and appliance assembly demand.
Integrator capacity is the main constraint, as qualified engineering teams are booked well ahead and labour costs are high. The region’s advantage is the depth of its software and deep-learning talent pool, which supports development of inspection models and hosted training services. The clearest change underway is the spread of vision-guided robotics into warehouses and food plants, where staffing difficulties make automated handling easier to justify than it was five years ago.
Europe Builds Machine Vision Demand on Automotive Metrology and Machinery Safety Rules
Europe accounted for 25.0% of the market in 2026, growing at a 6.8% CAGR to 2033. Germany is the centre of gravity, with vehicle body metrology, machine tool integration and a dense base of component and software suppliers. Italy contributes packaging machinery, France aerospace and pharmaceutical inspection, and the Nordic countries food processing applications.
Regulation shapes specification here more than elsewhere. Machinery safety duties, IEC 61496 requirements for electro-sensitive protective equipment and the robot safety provisions of ISO 10218 determine where vision may replace guarding. The EU Artificial Intelligence Act adds documentation and risk-management duties where learned models are used in regulated contexts, which favours vendors that can supply traceable training and validation records. Slower industrial capital spending is the brake, offset by battery plant construction and by reshoring of electronics assembly.
Which Region Is Leading the Machine Vision Market?
Asia Pacific leads the machine vision market with a 41.5% revenue share in 2026 and is forecast to grow at a 9.6% CAGR through 2033. The region leads because it hosts most of the world’s electronics assembly, semiconductor packaging and lithium-ion cell manufacturing, which are the three most inspection-intensive activities in industry.
China is the largest single market, combining domestic camera and vision software suppliers with very large installed capacity in consumer electronics and batteries. Japan and Korea supply components, sensors and inspection equipment while running advanced fabrication of their own. Taiwan anchors foundry and packaging demand, and India is adding electronics assembly and vehicle capacity that is being automated from the first line. Rising labour costs and tightening export quality requirements continue to push plants from sampling toward full automated optical inspection on every unit.
Which Region Is Growing Fastest in the Machine Vision Market?
Latin America is growing fastest in the machine vision market, at a 10.4% CAGR between 2026 and 2033, from a 5.5% share in 2026. Mexico supplies most of that growth, as vehicle, appliance and electronics production relocated closer to end markets arrives with inspection specified at the design stage rather than retrofitted. Brazil contributes food, beverage and packaging demand, with code reading and fill verification the common entry applications.
Barriers are real: integrator networks are thin outside a few industrial corridors, imported equipment carries duty and currency exposure, and spare parts logistics lengthen downtime. Training programmes run by vendors and technical institutes are slowly building local commissioning capability. The change that matters most is the arrival of plants whose quality requirements are set by customers elsewhere, which makes documented automated inspection a condition of supply.
Middle East & Africa Adds Machine Vision Capacity Around New Industrial and Logistics Zones
Middle East & Africa held 4.0% of the market in 2026 and is projected to grow at a 9.1% CAGR through 2033 from that small base. Saudi Arabia and the United Arab Emirates account for most activity, where industrial diversification programmes are funding food processing, pharmaceutical packaging, building products and large distribution centres that use code reading and dimensioning. South Africa adds vehicle component and beverage plant demand, and Egypt and Morocco contribute electronics and wiring harness assembly.
Constraints include a shortage of local integrators, dependence on imported hardware and limited after-sales support outside the main cities. Projects often rely on engineering firms brought in with the production line. The opportunity is greenfield construction: new plants can specify current interface standards and three-dimensional sensors immediately, with no legacy installed base to work around.
Competitive Landscape
The machine vision market is moderately concentrated. A small group of broad-line suppliers, including Cognex Corporation, Keyence Corporation, OMRON Corporation and Teledyne Technologies Incorporated, holds a substantial combined share of system-level revenue, while hundreds of specialist camera, optics, lighting and software firms serve particular niches. Concentration is highest in code reading and in packaged inspection systems, and lowest in components, where Basler AG, IDS Imaging Development Systems GmbH, Allied Vision Technologies GmbH and Baumer Holding AG compete alongside many regional producers. Ownership has drifted toward larger automation and instrumentation groups, which have absorbed several imaging and vision software businesses.
Competition turns on application engineering more than on component specification. Buyers compare how quickly a supplier can prove an inspection on their own parts, the breadth of lighting and optics available, the quality of the software environment, and local support when a line stops. Interoperability standards such as GenICam, GigE Vision, USB3 Vision, CoaXPress and Camera Link mean cameras from different vendors can be substituted, so differentiation migrates to software and service. EMVA 1288 data makes sensor performance claims directly comparable. New entrants arrive from two directions: Chinese camera and system suppliers competing hard on price, and software specialists such as MVTec Software GmbH selling deep-learning inspection tools independent of hardware.
Strategic behaviour centres on owning more of the application stack. Component vendors add software and certified integrator programmes, software vendors add deployment and model management, and automation groups bundle vision with robots and controls. Suppliers such as SICK AG, Datalogic S.p.A., Zebra Technologies Corporation and ISRA VISION GmbH combine sensing, identification and inspection in ways that fit factory and logistics buyers who prefer a single supplier. The common direction is to reduce the engineering effort a customer must supply, since integrator scarcity, rather than price, decides how many projects reach production.
Machine Vision Industry Leaders
- Cognex Corporation
- Keyence Corporation
- Teledyne Technologies Incorporated
- OMRON Corporation
- Basler AG
Recent Industry Developments
August 2024: The EU Artificial Intelligence Act entered into force, establishing a risk-based framework for artificial intelligence systems – deep-learning vision used in regulated or safety-related contexts now carries documentation and risk-management duties that favour suppliers able to evidence training and validation.
February 2025: The first obligations under the EU Artificial Intelligence Act became applicable, covering prohibited practices and artificial intelligence literacy requirements – vision deployments involving people in the workplace must be assessed against these limits before commissioning.
August 2025: Governance provisions and obligations for general-purpose artificial intelligence models under the EU Artificial Intelligence Act became applicable – vendors supplying pre-trained inspection models into Europe face clearer disclosure expectations about model provenance.
2025: Revised editions of the industrial robot safety standards ISO 10218-1 and ISO 10218-2 were published, consolidating collaborative operation requirements previously held in ISO/TS 15066 – this clarifies how vision-based sensing may be used in place of fixed guarding.
Machine Vision Market Report Scope
| Metric | Value |
| Study Period | 2020–2033 |
| Market Size 2026 | US$ 18.4 Billion |
| Market Size 2033 | US$ 32.4 Billion |
| CAGR 2026–2033 | 8.4% |
| Absolute Dollar Opportunity | US$ 14.0 Billion |
| Largest Market | Asia Pacific (41.5% share in 2026) |
| Fastest-Growing Market | Latin America (10.4% CAGR) |
| Market Concentration | Medium |
| Major Players | Cognex Corporation, Keyence Corporation, Teledyne Technologies Incorporated, OMRON Corporation |
This study sizes global machine vision revenue across hardware, software and services, covering cameras, optics, lighting, frame grabbers, processors, three-dimensional systems, code readers and inspection software. Consumer imaging, medical imaging and security surveillance are excluded. Machine vision is a component of the wider industrial automation market and is examined here in its own right. The base year is 2025, with forecasts for 2026–2033 stated in US$ Billion.
Machine Vision Market Segmentation
Component
- Hardware
- Software
- Services
Product Type
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
Imaging Technique
- Two-Dimensional Vision
- Three-Dimensional Vision
End-use Industry
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Executive Summary
- Global Machine Vision Market Snapshot
- Future Projections
- Key Report Takeaways
- Regional Snapshot
- Market Overview
- Market Definition and Report Scope
- Historical Trends 2020–2025
- Market Dynamics
- Drivers
- Deep-Learning Defect Detection Opens Machine Vision Applications Rule-Based Tools Could Not Serve
- Battery and Semiconductor Inspection Density Raises Machine Vision Content per Production Line
- Restraints
- Shortage of Vision Engineers and Integrators Delays Machine Vision Projects Beyond Component Lead Times
- Labelled Defect Image Sets Remain the Hidden Cost That Limits Machine Vision Deployment
- Market Opportunities
- Three-Dimensional Vision for Robot Guidance Opens a Revenue Pool Beyond Flat-Part Inspection
- Configurable Vision Software and Inspection Services Create Recurring Machine Vision Revenue
- Drivers
- Global Machine Vision Market Outlook, 2020–2033
- Global Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Global Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- Global Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- Global Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- Global Machine Vision Market Outlook, by Region, Value (US$ Billion), 2020–2033
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
- Global Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- North America Machine Vision Market Outlook, 2020–2033
- North America Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- North America Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- North America Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- North America Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- North America Machine Vision Market Outlook, by Country, Value (US$ Billion), 2020–2033
- United States Machine Vision Market Outlook, by Component, 2020–2033
- United States Machine Vision Market Outlook, by Product Type, 2020–2033
- United States Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- United States Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Canada Machine Vision Market Outlook, by Component, 2020–2033
- Canada Machine Vision Market Outlook, by Product Type, 2020–2033
- Canada Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Canada Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Mexico Machine Vision Market Outlook, by Component, 2020–2033
- Mexico Machine Vision Market Outlook, by Product Type, 2020–2033
- Mexico Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Mexico Machine Vision Market Outlook, by End-use Industry, 2020–2033
- North America Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Europe Machine Vision Market Outlook, 2020–2033
- Europe Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Europe Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- Europe Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- Europe Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- Europe Machine Vision Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Germany Machine Vision Market Outlook, by Component, 2020–2033
- Germany Machine Vision Market Outlook, by Product Type, 2020–2033
- Germany Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Germany Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Italy Machine Vision Market Outlook, by Component, 2020–2033
- Italy Machine Vision Market Outlook, by Product Type, 2020–2033
- Italy Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Italy Machine Vision Market Outlook, by End-use Industry, 2020–2033
- France Machine Vision Market Outlook, by Component, 2020–2033
- France Machine Vision Market Outlook, by Product Type, 2020–2033
- France Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- France Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Nordic countries Machine Vision Market Outlook, by Component, 2020–2033
- Nordic countries Machine Vision Market Outlook, by Product Type, 2020–2033
- Nordic countries Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Nordic countries Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Europe Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Asia Pacific Machine Vision Market Outlook, 2020–2033
- Asia Pacific Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Asia Pacific Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- Asia Pacific Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- Asia Pacific Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- Asia Pacific Machine Vision Market Outlook, by Country, Value (US$ Billion), 2020–2033
- China Machine Vision Market Outlook, by Component, 2020–2033
- China Machine Vision Market Outlook, by Product Type, 2020–2033
- China Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- China Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Japan Machine Vision Market Outlook, by Component, 2020–2033
- Japan Machine Vision Market Outlook, by Product Type, 2020–2033
- Japan Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Japan Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Korea Machine Vision Market Outlook, by Component, 2020–2033
- Korea Machine Vision Market Outlook, by Product Type, 2020–2033
- Korea Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Korea Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Taiwan Machine Vision Market Outlook, by Component, 2020–2033
- Taiwan Machine Vision Market Outlook, by Product Type, 2020–2033
- Taiwan Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Taiwan Machine Vision Market Outlook, by End-use Industry, 2020–2033
- India Machine Vision Market Outlook, by Component, 2020–2033
- India Machine Vision Market Outlook, by Product Type, 2020–2033
- India Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- India Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Asia Pacific Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Latin America Machine Vision Market Outlook, 2020–2033
- Latin America Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Latin America Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- Latin America Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- Latin America Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- Latin America Machine Vision Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Mexico Machine Vision Market Outlook, by Component, 2020–2033
- Mexico Machine Vision Market Outlook, by Product Type, 2020–2033
- Mexico Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Mexico Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Brazil Machine Vision Market Outlook, by Component, 2020–2033
- Brazil Machine Vision Market Outlook, by Product Type, 2020–2033
- Brazil Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Brazil Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Latin America Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Middle East & Africa Machine Vision Market Outlook, 2020–2033
- Middle East & Africa Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Hardware
- Software
- Services
- Middle East & Africa Machine Vision Market Outlook, by Product Type, Value (US$ Billion), 2020–2033
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
- Middle East & Africa Machine Vision Market Outlook, by Imaging Technique, Value (US$ Billion), 2020–2033
- Two-Dimensional Vision
- Three-Dimensional Vision
- Middle East & Africa Machine Vision Market Outlook, by End-use Industry, Value (US$ Billion), 2020–2033
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
- Middle East & Africa Machine Vision Market Outlook, by Country, Value (US$ Billion), 2020–2033
- Saudi Arabia Machine Vision Market Outlook, by Component, 2020–2033
- Saudi Arabia Machine Vision Market Outlook, by Product Type, 2020–2033
- Saudi Arabia Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Saudi Arabia Machine Vision Market Outlook, by End-use Industry, 2020–2033
- United Arab Emirates Machine Vision Market Outlook, by Component, 2020–2033
- United Arab Emirates Machine Vision Market Outlook, by Product Type, 2020–2033
- United Arab Emirates Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- United Arab Emirates Machine Vision Market Outlook, by End-use Industry, 2020–2033
- South Africa Machine Vision Market Outlook, by Component, 2020–2033
- South Africa Machine Vision Market Outlook, by Product Type, 2020–2033
- South Africa Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- South Africa Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Egypt Machine Vision Market Outlook, by Component, 2020–2033
- Egypt Machine Vision Market Outlook, by Product Type, 2020–2033
- Egypt Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Egypt Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Morocco Machine Vision Market Outlook, by Component, 2020–2033
- Morocco Machine Vision Market Outlook, by Product Type, 2020–2033
- Morocco Machine Vision Market Outlook, by Imaging Technique, 2020–2033
- Morocco Machine Vision Market Outlook, by End-use Industry, 2020–2033
- Middle East & Africa Machine Vision Market Outlook, by Component, Value (US$ Billion), 2020–2033
- Competitive Landscape
- Market Concentration and Industry Leaders
- Competitive Differentiation
- Strategic Moves and Market Direction
- Recent Industry Developments
- Company Profiles
- Cognex Corporation
- Keyence Corporation
- Basler AG
- Teledyne Technologies Incorporated
- OMRON Corporation
- SICK AG
- Datalogic S.p.A.
- Zebra Technologies Corporation
- Baumer Holding AG
- MVTec Software GmbH
- IDS Imaging Development Systems GmbH
- Allied Vision Technologies GmbH
- ISRA VISION GmbH
- Appendix
- Research Methodology
- Report Assumptions
- Acronyms and Abbreviations
Component
- Hardware
- Software
- Services
Product Type
- PC-Based Vision Systems
- Smart Camera-Based Systems
- Vision Sensors
- Embedded Vision Systems
Imaging Technique
- Two-Dimensional Vision
- Three-Dimensional Vision
End-use Industry
- Semiconductors and Electronics
- Automotive and Battery Manufacturing
- Food and Beverage
- Pharmaceuticals and Packaging
- Logistics and E-commerce
- Other Industrial
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The machine vision market is valued at US$ 18.4 billion in 2026, covering hardware, software and services sold for industrial imaging applications worldwide.
Revenue is projected to reach US$ 32.4 billion by 2033, a CAGR of 8.4%, giving an absolute dollar opportunity of US$ 14.0 billion over the period.
Hardware leads with 60.8% share in 2026, since cameras, optics, lighting and processors are purchased for every inspection station that is installed.
Vision software grows fastest among components at 11.4% CAGR, while Latin America is the fastest-growing geography at 10.4% CAGR to 2033.
Asia Pacific holds the largest share at 41.5% in 2026, supported by electronics assembly, semiconductor packaging and lithium-ion cell manufacturing capacity.
Related Reports
Contact Center as a Service Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the contact center as a service market outlook for 2026–2033, including cloud deployment, AI tooling, regional trends, and competitive insights.
Affiliate Software Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the affiliate software market outlook for 2026–2033, including tracking tools, payout trends, regional insights, and competitive analysis.
Mobile Wallet Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global mobile wallet market is valued at US$8.3 billion in 2026, reaching US$38.5 billion by 2033, growing at a 24.5% CAGR
Microwave Devices Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global microwave devices market is valued at US$8.4 billion in 2026, reaching US$14.2 billion by 2033, growing at a 7.8% CAGR
LED Drivers and Power Supplies for Horticulture Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global LED drivers and power supplies for horticulture market is valued at US$1.15 billion in 2026, reaching US$2.51 billion by 2033, growing at an 11.8% CAGR
Inkjet Printers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global inkjet printers market is valued at US$50.4 billion in 2026, reaching US$58.8 billion by 2033, growing at a 2.2% CAGR