


Nanoparticle Formulation Market
Nanoparticle Formulation Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
How Fast Is the Nanoparticle Formulation Market Growing?
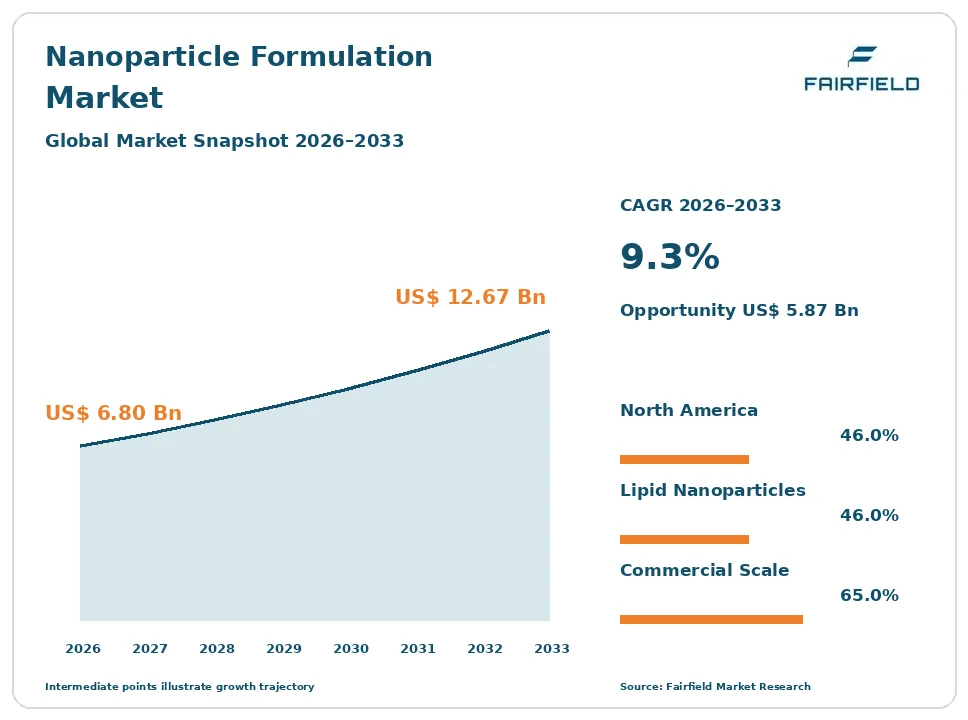
The global nanoparticle formulation market size is expected to be valued at US$ 6.80 billion in 2026 and projected to reach US$ 12.67 billion by 2033, growing at a CAGR of 9.3% between 2026 and 2033.
Between 2020 and 2025, the market grew at a CAGR of about 10.8%, boosted by the success of mRNA COVID-19 vaccines, which used lipid nanoparticles to carry genetic material into cells. Three factors now drive growth: the expanding pipeline of mRNA, siRNA, and gene editing therapies that need mRNA delivery systems, demand for targeted drug delivery in cancer, and the need to improve bioavailability of poorly soluble drugs. Drug developers increasingly outsource formulation to specialist companies with nanoparticle expertise and manufacturing capacity. The market is shifting toward tissue-targeting lipid nanoparticles, polymeric nanoparticles for controlled release, and in vivo cell therapies made inside the body. Large deals in 2026, including Eli Lilly’s planned acquisition of Orna Therapeutics, show strong interest from big pharma in nanoparticle-based medicines.
Key Report Takeaways
- By Nanoparticle Type: Lipid Nanoparticles held 46.0% share in 2026, while Polymeric Nanoparticles are projected to expand at an 11.6% CAGR through 2033, driven by controlled-release and targeted cancer drug programs.
- By Scale of Operation: Commercial held 65.0% share in 2026, while Clinical is projected to expand at a 10.8% CAGR through 2033, driven by many nanoparticle drugs entering early-stage trials.
- By Therapeutic Area: Oncology held 38.0% share in 2026, while Genetic Disorders are projected to expand at a 12.4% CAGR through 2033, driven by gene editing and RNA therapies.
- By Region: North America held 46.0% share in 2026, while Asia Pacific is projected to expand at a 12.1% CAGR through 2033, driven by biotech growth in China, India, and South Korea.
Global Nanoparticle Formulation Market Trends and Insights
Drivers Impact Analysis
| Driver | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Growth of RNA and gene therapy pipelines | High | North America, Europe, Asia Pacific | Long term (≥4 years) |
| Demand for targeted and improved drug delivery | High | Global | Medium term (2-4 years) |
Two drivers carry the strongest influence on nanoparticle formulation demand during the forecast period.
RNA Therapies Are Driving the Nanoparticle Formulation Market
The growth of RNA and gene therapy pipelines is the strongest driver of the nanoparticle formulation market. These medicines need carriers to reach cells safely.
The mechanism is basic biology. RNA and DNA break down quickly in the body and cannot enter cells on their own, so they must be packed into nanoparticles. Lipid nanoparticles proved this approach with mRNA COVID-19 vaccines from Pfizer, BioNTech, and Moderna. Hundreds of mRNA, siRNA, and CRISPR programs now target cancer, rare diseases, and infections. In vivo CAR-T therapies, such as Orna Therapeutics’ circular RNA program, also depend on nanoparticles. Eli Lilly agreed to acquire Orna for up to US$ 2.4 billion in 2026. Each new program needs custom formulation work. These factors keep demand high for nanoparticle design and manufacturing.
Targeted Delivery Is Expanding the Nanoparticle Formulation Market
Demand for targeted drug delivery and better drug performance is expanding the nanoparticle formulation market. Nanoparticles help drugs reach the right tissue.
The cause is the need for safer and more effective treatment. Cancer drugs often harm healthy cells, and nanoparticles can carry them to tumors and release them slowly, lowering side effects. Many new small-molecule drugs dissolve poorly in water, which limits bioavailability, and nanoparticle formulations improve absorption. Companies such as Nanoform and Ascendia Pharmaceuticals offer technologies to shrink particles and improve solubility. New tissue-targeting lipid designs aim to reach the liver, lungs, spleen, and immune cells. Nanoparticles can also cross barriers such as the skin and the lining of the gut, opening new routes of delivery. These trends widen nanoparticle use beyond vaccines into oncology and chronic disease.
Restraints Impact Analysis
| Restraint | Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
| Manufacturing complexity and scale-up challenges | High | Global | Medium term (2-4 years) |
| Regulatory hurdles and safety concerns | Medium | North America, Europe | Long term (≥4 years) |
Two restraints limit how quickly the nanoparticle formulation market grows.
Manufacturing Complexity Slows the Nanoparticle Formulation Market
Manufacturing complexity and scale-up challenges slow the nanoparticle formulation market. Making nanoparticles consistently at large scale is difficult.
The specific causes are technical. Nanoparticle size, charge, and drug loading must stay within tight limits, and small changes in mixing can change how a drug works. Methods that work in the lab often fail at commercial scale. Lipids and other raw materials can be costly and in short supply. Specialized equipment, such as microfluidic mixers, adds investment. Testing each batch requires advanced analytical tools. Few contract manufacturers have proven large-scale capacity outside a handful of leading firms. Stability is another challenge, since many lipid formulations need cold storage and have short shelf lives. These factors raise costs, extend timelines, and slow the move from trials to market.
Regulatory Hurdles Restrict the Nanoparticle Formulation Market
Regulatory hurdles and safety concerns restrict the nanoparticle formulation market. Regulators require detailed data on how nanoparticles behave in the body.
The underlying causes are the novelty of nanomedicines and concerns about long-term effects. Some nanoparticles build up in the liver or spleen or trigger immune reactions, and regulators ask for extra studies. Guidance for nanomedicines is still developing, and rules differ between the United States, Europe, China, and Japan. Patent disputes over lipid nanoparticle technology, involving Moderna, Pfizer, Arbutus Biopharma, and Genevant Sciences, add legal risk for new developers. Funding for biotech startups has also become tighter since 2022. Each change to a formulation after approval may need new data, which limits flexibility. These factors slow approvals and raise development costs.
Market Opportunities
In Vivo Cell Therapies Open a High-Value Revenue Pool
In vivo cell therapies open a high-value revenue pool in the nanoparticle formulation market. These therapies program immune cells inside the patient’s body.
Nanoparticle developers with targeted delivery skills can capture this opportunity. Traditional CAR-T therapies require removing, engineering, and returning a patient’s cells, which is slow and costly. In vivo approaches use nanoparticles to deliver genetic instructions directly, potentially cutting costs and treatment time. Eli Lilly’s planned acquisition of Orna Therapeutics shows big pharma interest. Autoimmune disease and cancer are the main targets. Formulation partners could earn development fees, milestones, and long-term supply contracts. Delivery systems that reach T cells without affecting other tissues are a key goal, and companies that solve this could command high licensing fees. Success here could make cell therapy available to far more patients.
Pandemic Preparedness Vaccines Create a Public-Funded Revenue Pool
Pandemic preparedness vaccines create a public-funded revenue pool in the nanoparticle formulation market. Governments and global health groups want vaccine platforms that can respond quickly to new outbreaks.
Platform developers and contract manufacturers can capture this opportunity. In 2026, CEPI awarded up to US$ 9.7 million to POP Biotechnologies to advance its SNAP nanoparticle vaccine platform against H5N1 bird flu. Nanoparticle vaccines can be adapted to new viruses in weeks. Governments are funding domestic vaccine production after COVID-19. Polymeric nanoparticles and protein nanoparticles also offer options beyond mRNA. These programs provide steady, low-risk revenue for formulation partners. Vaccines that stay stable without deep freezing are a priority for low-income countries, which favors new nanoparticle designs. Stockpiling contracts can add long-term orders.
Segment Analysis
By Nanoparticle Type: Lipid Nanoparticles Lead While Polymeric Nanoparticles Grow Fastest
Lipid Nanoparticles held 46.0% share in 2026. Lipid nanoparticles are the leading carriers for mRNA vaccines and siRNA drugs because they protect genetic material and help it enter cells. Liposomes, a related type, are used in cancer and antifungal drugs. Evonik Industries, Cytiva, and Acuitas Therapeutics supply lipid technology and formulation services. Organic nanoparticles as a group account for about 65% of the market.
Polymeric Nanoparticles are the fastest-growing type, expanding at an 11.6% CAGR through 2033. Polymeric nanoparticles made from biodegradable materials release drugs slowly and can be designed to target tumors. They are also more stable than some lipid formulations and may need less cold storage. For the market, this growth widens options for targeted drug delivery.
By Scale of Operation: Commercial Leads While Clinical Grows Fastest
Commercial held 65.0% share in 2026. Approved nanoparticle medicines, including mRNA vaccines, siRNA drugs, and liposomal cancer treatments, need large-scale, steady production. Lonza, Evonik Industries, and other contract manufacturers supply commercial batches under long-term contracts. Commercial work brings the most revenue per client, and long-term contracts give suppliers stable income. Liposomal cancer drugs and siRNA medicines for rare diseases add steady demand beyond vaccines.
Clinical is the fastest-growing scale of operation, expanding at a 10.8% CAGR through 2033. Many small biotechs are moving nanoparticle drugs into Phase 1 and Phase 2 trials, and they outsource formulation because they lack in-house capacity. Sapu Nano and POP Biotechnologies are among companies starting early trials. Clinical batches are small but need flexible equipment and fast turnaround. For the market, clinical work builds future commercial demand.
By Therapeutic Area: Oncology Leads While Genetic Disorders Grow Fastest
Oncology held 38.0% share in 2026. Nanoparticles deliver chemotherapy, RNA, and cancer vaccines to tumors while reducing harm to healthy tissue. Liposomal drugs such as doxorubicin have been used for years, and new mRNA cancer vaccines rely on lipid nanoparticles. Hopewell Therapeutics licensed tissue-targeting lipid formulations for a cancer vaccine in 2026.
Genetic Disorders are the fastest-growing therapeutic area, expanding at a 12.4% CAGR through 2033. Gene editing and RNA therapies for rare inherited diseases, such as liver and blood disorders, need nanoparticles to reach target organs. Approved siRNA medicines prove the approach, and the first CRISPR therapies delivered by lipid nanoparticles are in late trials. Infectious diseases remain a large area, driven by mRNA vaccines. For the market, this growth adds high-value programs.
Geography Analysis
Which Region Is Leading the Nanoparticle Formulation Market?
North America is leading the nanoparticle formulation market with a 46.0% share in 2026. The United States is home to Moderna, Pfizer, Eli Lilly, Alnylam Pharmaceuticals, and hundreds of RNA and nanomedicine startups. Strong venture funding and government research support from the National Institutes of Health sustain development. Canada hosts Acuitas Therapeutics, NanoVation Therapeutics, and Precision NanoSystems, now part of Cytiva. Many contract manufacturers have facilities in the region. Key barriers include high costs and patent disputes. One change shaping the region is in vivo CAR-T development, supported by large acquisitions such as Eli Lilly’s deal for Orna Therapeutics.
Europe Builds the Nanoparticle Formulation Market Through Specialist Suppliers
Europe holds about 37.0% of the nanoparticle formulation market. Germany hosts BioNTech, CureVac, and Evonik Industries, a leading lipid supplier, and Switzerland hosts Lonza. Finland is home to Nanoform, and France hosts DIANT Pharma and other formulation specialists. The United Kingdom, the Netherlands, and Belgium have strong research programs. The European Medicines Agency has approved several nanoparticle medicines, including mRNA vaccines and siRNA drugs. Universities in Denmark and Sweden study new lipid designs. Key barriers include tighter biotech funding and slower approvals in some countries. One opportunity is domestic vaccine production capacity backed by governments after COVID-19.
Which Region Is Growing Fastest in the Nanoparticle Formulation Market?
Asia Pacific is growing fastest in the nanoparticle formulation market at a 12.1% CAGR through 2033. China has many mRNA and nanomedicine developers, and its companies are licensing programs to global pharma. India has a large generic and vaccine manufacturing base, with growing interest in lipid nanoparticle production. South Korea and Japan are investing in mRNA platforms and contract manufacturing. Singapore and Australia fund nanomedicine research. Lower manufacturing costs attract outsourcing from global drug makers, and India produces large volumes of generic liposomal drugs that improve bioavailability. Key barriers include regulatory differences. One change shaping the region is local mRNA vaccine production.
Latin America Develops the Nanoparticle Formulation Market Through Vaccine Production
Latin America is a developing nanoparticle formulation market. Brazil and Argentina are part of a global health program to build mRNA vaccine production capacity, supported by the World Health Organization. Mexico has a growing pharmaceutical sector and contract manufacturing that serves the United States. Chile and Colombia fund research into nanomedicine and drug delivery. Universities in the region are studying lower-cost formulations, and public institutes such as Bio-Manguinhos in Brazil have vaccine experience. Key barriers include limited funding and specialized equipment. One opportunity is regional vaccine production that uses lipid nanoparticles to reduce reliance on imports.
Middle East & Africa Adopts the Nanoparticle Formulation Market Through Technology Transfer
Middle East & Africa is an early-stage nanoparticle formulation market. South Africa hosts an mRNA technology transfer hub supported by the World Health Organization, and Egypt, Nigeria, Kenya, and Senegal are part of efforts to build vaccine capacity. Saudi Arabia and the United Arab Emirates are investing in biotech and local drug production. Israel has strong nanotechnology research and startups working on targeted drug delivery. Morocco is also building vaccine plants, and Rwanda has started mRNA production work. Key barriers include limited skilled staff and infrastructure. One opportunity is local vaccine production for regional health needs.
Competitive Landscape
The nanoparticle formulation market is fragmented. Large contract manufacturers and suppliers such as Evonik Industries, Lonza, and Cytiva compete with technology developers including Acuitas Therapeutics, Genevant Sciences, Arbutus Biopharma, Nanoform, Ascendia Pharmaceuticals, NanoVation Therapeutics, Ascension Sciences, and DIANT Pharma. Many small startups offer specialized platforms for targeting or specific drug types.
Companies compete on delivery efficiency, targeting ability, safety, intellectual property, scale-up capacity, and regulatory experience. Patents on lipid designs are valuable, and licensing fees form a large share of revenue for technology owners. Contract manufacturers win long-term supply contracts by proving they can make consistent batches at scale. Drug developers often choose partners that can support them from early trials to commercial launch. Large firms are buying smaller technology owners to secure delivery platforms, and many startups seek partnerships to fund trials. mRNA delivery know-how is especially valued.
Strategic moves show how competition is changing. In February 2026, Eli Lilly agreed to acquire Orna Therapeutics for up to US$ 2.4 billion. In March 2026, Hopewell Therapeutics licensed its tissue-targeting lipid formulations to Foxcroft Therapeutics. In June 2026, CEPI funded POP Biotechnologies, and Advanced NanoTherapies raised over US$ 31 million. These moves show competition shifting toward targeted and in vivo delivery.
Three themes shape vendor strategy. First, companies are developing tissue-targeting lipids. Second, they are expanding contract manufacturing capacity. Third, they are licensing platforms to large drug makers.
Nanoparticle Formulation Market Industry Leaders
- Evonik Industries
- Lonza
- Cytiva
- Ascendia Pharmaceuticals
- Nanoform
Recent Industry Developments
- June 2026: CEPI awarded up to US$ 9.7 million to POP Biotechnologies to advance its SNAP nanoparticle vaccine platform for H5N1 into Phase 1 - supports fast-response nanoparticle vaccines.
- June 2026: Advanced NanoTherapies raised over US$ 31 million in a Series B round for its nanoparticle-enabled dual-drug balloon platform - extends nanoparticle use into cardiovascular devices.
- March 2026: Hopewell Therapeutics licensed its tissue-targeting lipid nanoparticles to Foxcroft Therapeutics for a cancer vaccine - advances targeted mRNA delivery in oncology.
- February 2026: Eli Lilly agreed to acquire Orna Therapeutics for up to US$ 2.4 billion - brings circular RNA and lipid nanoparticle in vivo CAR-T into big pharma.
Companies Covered in the Report
- Evonik Industries
- Lonza
- Cytiva
- Ascendia Pharmaceuticals
- Nanoform
- Acuitas Therapeutics
- Genevant Sciences
- Arbutus Biopharma
- NanoVation Therapeutics
- Ascension Sciences
- DIANT Pharma
- POP Biotechnologies
Nanoparticle Formulation Market Report Scope
This report covers nanoparticle formulation services and technologies, including lipid, polymeric, and inorganic nanoparticles, used in clinical and commercial production for oncology, infectious diseases, genetic disorders, and other areas. It includes formulation development, licensing, and manufacturing revenue. The base year is 2025, and the forecast period runs from 2026 to 2033. All values are expressed in US$ Billion.
Nanoparticle Type
- Lipid Nanoparticles
- Polymeric Nanoparticles
- Inorganic Nanoparticles
- Others
Scale of Operation
- Clinical
- Commercial
Therapeutic Area
- Oncology
- Infectious Diseases
- Genetic Disorders
- Others
Regions
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Key Questions Answered in the Report
How big is the nanoparticle formulation market in 2026?
The nanoparticle formulation market is valued at US$ 6.80 billion in 2026, led by lipid nanoparticles and commercial-scale production.
What is the nanoparticle formulation market forecast to 2033?
The market is projected to reach US$ 12.67 billion by 2033, growing at a 9.3% CAGR and adding US$ 5.87 billion.
Which nanoparticle type is growing fastest in the market?
Polymeric nanoparticles are growing fastest at an 11.6% CAGR through 2033, driven by controlled-release and targeted cancer drug programs.
Which region is growing fastest in the nanoparticle formulation market?
Asia Pacific is growing fastest at a 12.1% CAGR through 2033, driven by biotech growth in China, India, and South Korea.
Which region holds the largest nanoparticle formulation market share?
North America holds the largest share at 46.0% in 2026, supported by leading RNA developers and strong venture funding.
1. Executive Summary
1.1. Global Nanoparticle Formulation Market Snapshot
1.2. Future Projections
1.3. Key Report Takeaways
1.4. Regional Snapshot
2. Market Overview
2.1. Market Definition and Report Scope
2.2. Historical Trends 2020–2025
2.3. Market Dynamics
2.3.1. Drivers
2.3.1.1. RNA Therapies Are Driving the Nanoparticle Formulation Market
2.3.1.2. Targeted Delivery Is Expanding the Nanoparticle Formulation Market
2.3.2. Restraints
2.3.2.1. Manufacturing Complexity Slows the Nanoparticle Formulation Market
2.3.2.2. Regulatory Hurdles Restrict the Nanoparticle Formulation Market
2.3.3. Market Opportunities
2.3.3.1. In Vivo Cell Therapies Open a High-Value Revenue Pool
2.3.3.2. Pandemic Preparedness Vaccines Create a Public-Funded Revenue Pool
3. Global Nanoparticle Formulation Market Outlook, 2020-2033
3.1. Global Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
3.1.1. Lipid Nanoparticles
3.1.2. Polymeric Nanoparticles
3.1.3. Inorganic Nanoparticles
3.1.4. Others
3.2. Global Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
3.2.1. Clinical
3.2.2. Commercial
3.3. Global Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
3.3.1. Oncology
3.3.2. Infectious Diseases
3.3.3. Genetic Disorders
3.3.4. Others
3.4. Global Nanoparticle Formulation Market Outlook, by Region, Value (US$ Billion), 2020-2033
3.4.1. North America
3.4.2. Europe
3.4.3. Asia Pacific
3.4.4. Latin America
3.4.5. Middle East & Africa
4. North America Nanoparticle Formulation Market Outlook, 2020-2033
4.1. North America Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
4.1.1. Lipid Nanoparticles
4.1.2. Polymeric Nanoparticles
4.1.3. Inorganic Nanoparticles
4.1.4. Others
4.2. North America Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
4.2.1. Clinical
4.2.2. Commercial
4.3. North America Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
4.3.1. Oncology
4.3.2. Infectious Diseases
4.3.3. Genetic Disorders
4.3.4. Others
4.4. North America Nanoparticle Formulation Market Outlook, by Country, Value (US$ Billion), 2020-2033
4.4.1. United States Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
4.4.2. United States Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
4.4.3. United States Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
4.4.4. Canada Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
4.4.5. Canada Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
4.4.6. Canada Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5. Europe Nanoparticle Formulation Market Outlook, 2020-2033
5.1. Europe Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
5.1.1. Lipid Nanoparticles
5.1.2. Polymeric Nanoparticles
5.1.3. Inorganic Nanoparticles
5.1.4. Others
5.2. Europe Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
5.2.1. Clinical
5.2.2. Commercial
5.3. Europe Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
5.3.1. Oncology
5.3.2. Infectious Diseases
5.3.3. Genetic Disorders
5.3.4. Others
5.4. Europe Nanoparticle Formulation Market Outlook, by Country, Value (US$ Billion), 2020-2033
5.4.1. Germany Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.2. Germany Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.3. Germany Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.4. Switzerland Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.5. Switzerland Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.6. Switzerland Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.7. Finland Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.8. Finland Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.9. Finland Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.10. France Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.11. France Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.12. France Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.13. United Kingdom Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.14. United Kingdom Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.15. United Kingdom Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.16. Netherlands Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.17. Netherlands Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.18. Netherlands Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.19. Denmark Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.20. Denmark Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.21. Denmark Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
5.4.22. Sweden Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
5.4.23. Sweden Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
5.4.24. Sweden Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6. Asia Pacific Nanoparticle Formulation Market Outlook, 2020-2033
6.1. Asia Pacific Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
6.1.1. Lipid Nanoparticles
6.1.2. Polymeric Nanoparticles
6.1.3. Inorganic Nanoparticles
6.1.4. Others
6.2. Asia Pacific Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
6.2.1. Clinical
6.2.2. Commercial
6.3. Asia Pacific Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
6.3.1. Oncology
6.3.2. Infectious Diseases
6.3.3. Genetic Disorders
6.3.4. Others
6.4. Asia Pacific Nanoparticle Formulation Market Outlook, by Country, Value (US$ Billion), 2020-2033
6.4.1. China Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.2. China Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.3. China Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6.4.4. India Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.5. India Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.6. India Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6.4.7. South Korea Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.8. South Korea Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.9. South Korea Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6.4.10. Japan Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.11. Japan Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.12. Japan Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6.4.13. Singapore Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.14. Singapore Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.15. Singapore Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
6.4.16. Australia Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
6.4.17. Australia Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
6.4.18. Australia Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
7. Latin America Nanoparticle Formulation Market Outlook, 2020-2033
7.1. Latin America Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
7.1.1. Lipid Nanoparticles
7.1.2. Polymeric Nanoparticles
7.1.3. Inorganic Nanoparticles
7.1.4. Others
7.2. Latin America Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
7.2.1. Clinical
7.2.2. Commercial
7.3. Latin America Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
7.3.1. Oncology
7.3.2. Infectious Diseases
7.3.3. Genetic Disorders
7.3.4. Others
7.4. Latin America Nanoparticle Formulation Market Outlook, by Country, Value (US$ Billion), 2020-2033
7.4.1. Brazil Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
7.4.2. Brazil Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
7.4.3. Brazil Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
7.4.4. Argentina Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
7.4.5. Argentina Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
7.4.6. Argentina Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
7.4.7. Mexico Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
7.4.8. Mexico Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
7.4.9. Mexico Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
7.4.10. Chile Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
7.4.11. Chile Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
7.4.12. Chile Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
7.4.13. Colombia Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
7.4.14. Colombia Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
7.4.15. Colombia Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8. Middle East & Africa Nanoparticle Formulation Market Outlook, 2020-2033
8.1. Middle East & Africa Nanoparticle Formulation Market Outlook, by Nanoparticle Type, Value (US$ Billion), 2020-2033
8.1.1. Lipid Nanoparticles
8.1.2. Polymeric Nanoparticles
8.1.3. Inorganic Nanoparticles
8.1.4. Others
8.2. Middle East & Africa Nanoparticle Formulation Market Outlook, by Scale of Operation, Value (US$ Billion), 2020-2033
8.2.1. Clinical
8.2.2. Commercial
8.3. Middle East & Africa Nanoparticle Formulation Market Outlook, by Therapeutic Area, Value (US$ Billion), 2020-2033
8.3.1. Oncology
8.3.2. Infectious Diseases
8.3.3. Genetic Disorders
8.3.4. Others
8.4. Middle East & Africa Nanoparticle Formulation Market Outlook, by Country, Value (US$ Billion), 2020-2033
8.4.1. South Africa Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.2. South Africa Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.3. South Africa Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.4. Egypt Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.5. Egypt Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.6. Egypt Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.7. Nigeria Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.8. Nigeria Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.9. Nigeria Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.10. Kenya Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.11. Kenya Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.12. Kenya Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.13. Senegal Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.14. Senegal Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.15. Senegal Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.16. Saudi Arabia Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.17. Saudi Arabia Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.18. Saudi Arabia Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.19. United Arab Emirates Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.20. United Arab Emirates Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.21. United Arab Emirates Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.22. Israel Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.23. Israel Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.24. Israel Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.25. Morocco Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.26. Morocco Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.27. Morocco Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
8.4.28. Rwanda Nanoparticle Formulation Market Outlook, by Nanoparticle Type, 2020-2033
8.4.29. Rwanda Nanoparticle Formulation Market Outlook, by Scale of Operation, 2020-2033
8.4.30. Rwanda Nanoparticle Formulation Market Outlook, by Therapeutic Area, 2020-2033
9. Competitive Landscape
9.1. Market Concentration and Industry Leaders
9.2. Competitive Differentiation
9.3. Strategic Moves and Market Direction
9.4. Recent Industry Developments
9.5. Company Profiles
9.5.1. Evonik Industries
9.5.2. Lonza
9.5.3. Cytiva
9.5.4. Ascendia Pharmaceuticals
9.5.5. Nanoform
9.5.6. Acuitas Therapeutics
9.5.7. Genevant Sciences
9.5.8. Arbutus Biopharma
9.5.9. NanoVation Therapeutics
9.5.10. Ascension Sciences
9.5.11. DIANT Pharma
9.5.12. POP Biotechnologies
10. Appendix
10.1. Research Methodology
10.2. Report Assumptions
10.3. Acronyms and Abbreviations
| Nanoparticle Type | Lipid Nanoparticles, Polymeric Nanoparticles, Inorganic Nanoparticles, Others |
| Scale of Operation | Clinical, Commercial |
| Therapeutic Area | Oncology, Infectious Diseases, Genetic Disorders, Others |
| Regions | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
Our Research Methodology
Considering the volatility of business today, traditional approaches to strategizing a game plan can be unfruitful if not detrimental. True ambiguity is no way to determine a forecast. A myriad of predetermined factors must be accounted for such as the degree of risk involved, the magnitude of circumstances, as well as conditions or consequences that are not known or unpredictable. To circumvent binary views that cast uncertainty, the application of market research intelligence to strategically posture, move, and enable actionable outcomes is necessary.
View Methodology
Quality Assured
Rigorous Validation Process

Confidentiality Assured
End-to-end Data Security

Custom Research Services
Tailored To Your Objectives
FAQs
The nanoparticle formulation market is valued at US$ 6.80 billion in 2026, led by lipid nanoparticles and commercial-scale production.
The market is projected to reach US$ 12.67 billion by 2033, growing at a 9.3% CAGR and adding US$ 5.87 billion.
Polymeric nanoparticles are growing fastest at an 11.6% CAGR through 2033, driven by controlled-release and targeted cancer drug programs.
Asia Pacific is growing fastest at a 12.1% CAGR through 2033, driven by biotech growth in China, India, and South Korea.
North America holds the largest share at 46.0% in 2026, supported by leading RNA developers and strong venture funding.
Related Reports
Pharmaceutical Temperature Controlled Packaging Solutions Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Pharmaceutical temperature controlled packaging solutions market to grow from US$ 6.86 billion in 2026 to US$ 13.98 billion by 2033 at a 10.7% CAGR.
Dermatology CRO Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
Explore the dermatology CRO market, projected to reach US$ 9.7 billion by 2033 at a 6.6% CAGR, with service, indication and regional insights.
Acetaminophen Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global acetaminophen market is valued at US$11.70 billion in 2026, reaching US$15.93 billion by 2033, growing at a 4.5% CAGR
Allergy Diagnostics and Therapeutics Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global allergy diagnostics and therapeutics market is valued at US$41.50 billion in 2026, reaching US$88.30 billion by 2033, growing at an 11.4% CAGR
Homeopathic Products Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The global homeopathic products market is valued at US$59.45 billion in 2026, reaching US$169.21 billion by 2033, growing at a 16.1% CAGR
Renal Biomarkers Market Size, Share, Insights, Competitive Landscape, and Forecast 2026 to 2033
The renal biomarkers market is projected to grow from US$1.73 billion in 2026 to US$2.87 billion by 2033, at a 7.5% CAGR, driven by early kidney testing.